
 Aluminum Flat Products Market | 2026-2036
Aluminum Flat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Flat Products Market Analysis
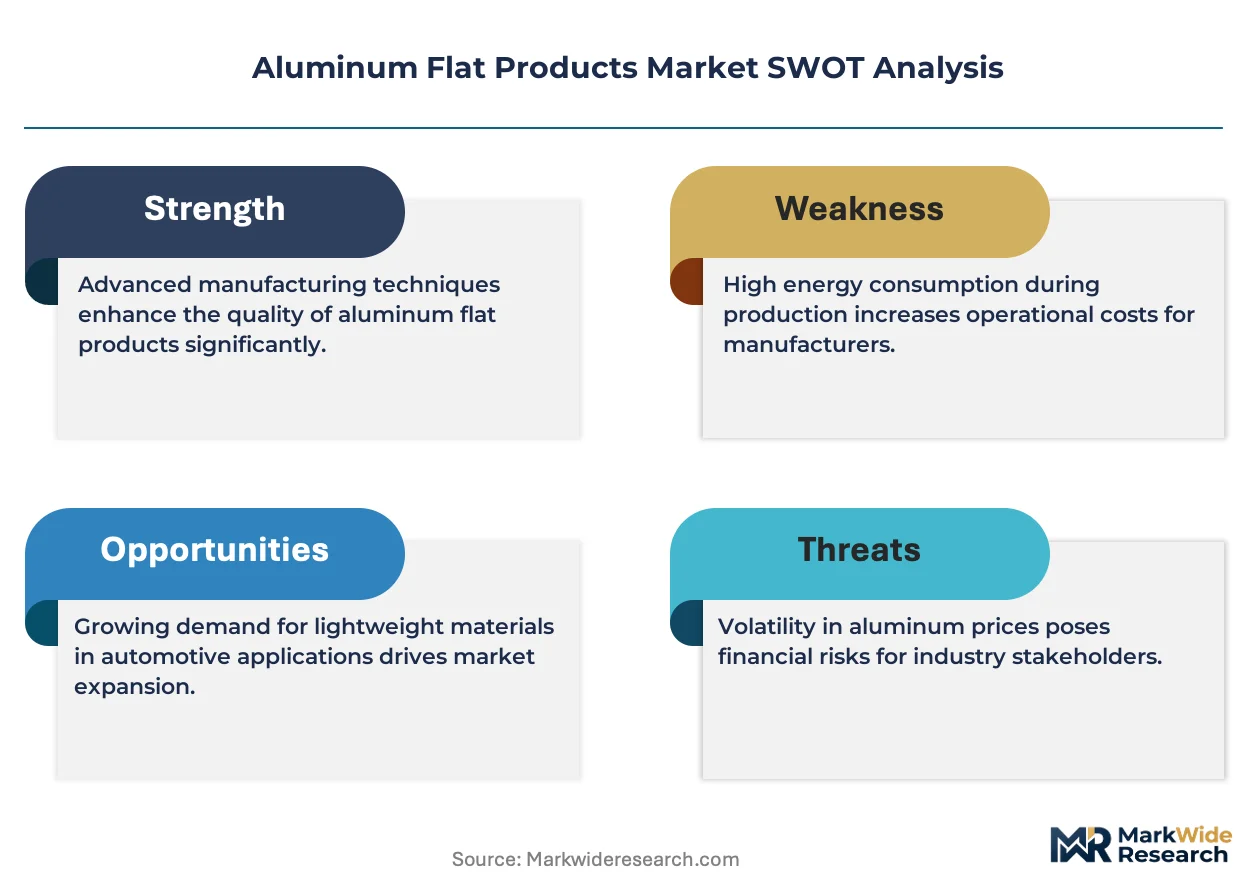
The capital-intensity divergence between integrated primary producers and downstream rolling specialists is redrawing competitive boundaries across the aluminum flat products value chain. Novelis leverages its closed-loop recycling network to sustain margin stability amid volatile LME pricing. Hindalco Industries Limited anchors its position through captive bauxite-to-rolled-products integration across Indian and overseas operations. Norsk Hydro competes on low-carbon primary metal output, differentiating its offering for European automotive OEMs with Scope 3 reduction targets.
Aluminum flat products comprise rolled, cast, and wrought aluminum alloys delivered in sheet, plate, coil, and foil geometries, typically spanning 0.2 mm to 150 mm in thickness depending on end-use structural requirements. These products serve as critical inputs where strength-to-weight ratio, corrosion resistance, and formability determine system performance, particularly in transportation and building envelopes. Sheets and coils occupy the largest volume share, with automotive body sheet representing the fastest-growing specification tier as OEMs substitute steel in closures and structural members. Plates retain premium positioning in aerospace wing and fuselage applications, where certification barriers limit supplier churn and sustain margin pools above commodity-grade coils. Foils face maturity in traditional packaging but find renewed specification intensity in lithium-ion battery current collectors.
The EPA tailpipe emission standards and NHTSA corporate average fuel economy rules in the United States mandate fleet-wide lightweighting, directly translating into aluminum content targets for passenger vehicles. ECHA REACH compliance and the EU Green Deal carbon border adjustments impose upstream emissions disclosure requirements on non-European suppliers, reshaping import competitiveness for Chinese and Indian mill products. Stakeholders must monitor evolving alloy certification protocols and smelter power-source documentation requirements, as these will determine qualified supplier status faster than capacity expansion timelines.
Market Dynamics
The EU Carbon Border Adjustment Mechanism and China's dual carbon goals are forcing smelters and rolling mills to reconfigure power sourcing and emissions documentation, redrawing competitive boundaries between low-carbon primary producers and conventional integrated mills.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA corporate average fuel economy rules in the United States mandate fleet-wide aluminum substitution in closures and structural members. OEM specification upgrades to 6xxx-series alloys are accelerating.
- Battery enclosure demand:Electric vehicle battery tray applications are pulling high-strength sheet volumes as cell-to-pack architectures proliferate across German and Chinese assembly lines.
- REACH compliance premiums:ECHA upstream emissions disclosure requirements are creating qualified supplier status for European mills with documented low-carbon power sourcing.
Market Restraints
- LME price volatility:Input cost swings for primary metal compress rolling margins, particularly for non-integrated specialists without captive smelter supply.
- Chinese supply concentration:Smelter capacity gravity in Shandong and Xinjiang creates regional dependency risk for global coil and plate availability.
- Steel substitution resilience:Advanced high-strength steel grades retain cost advantage in non-structural automotive applications, limiting aluminum penetration in economy vehicle segments.
Strategic Opportunities
- Indian downstream expansion:PLI scheme incentives for specialty alloys are attracting rolling capacity investments to serve domestic automotive and aerospace demand.
- Battery current collector foils:Lithium-ion cell manufacturing expansion is creating specification intensity for ultra-thin foil grades in South Korean and Japanese electrode supply chains.
- Closed-loop recycling networks:Automotive OEM take-back mandates in the EU are enabling toll-processing arrangements that secure scrap supply for secondary alloy production.
Industry Challenges
- Aerospace certification timelines:AS9100 and OEM-specific alloy qualifications require 18-36 month validation cycles, freezing supplier switches even when cost differentials emerge.
- Smelter power reconfiguration capex:Grid decarbonization and captive renewable builds demand capital allocation that competes with downstream rolling mill modernization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Flat Products Market |
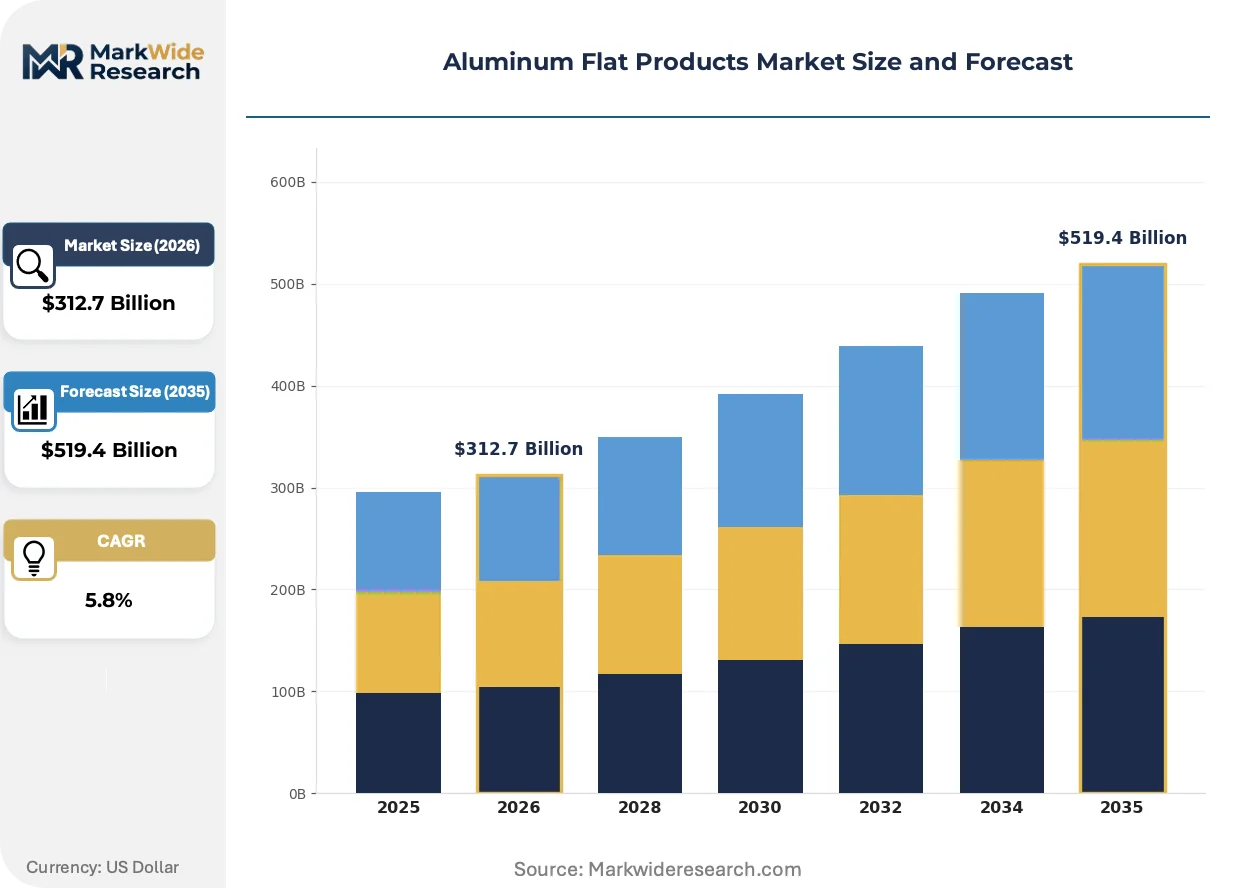
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $519.4 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Plates, Coils, Foils End User: Aerospace, Automotive, Construction, Packaging Thickness: Thin, Medium, Thick, Extra Thick Form: Flat, Rolled, Stretched, Forged |
| Companies Covered | Alcoa Corporation, Novelis, Constellium, Hindalco Industries Limited, Norsk Hydro, Arconic, UACJ Corporation, Aleris Corporation, National Aluminum Company Limited (NALCO), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Flat Products Market Emerging Trajectories
Active technology and policy vectors are compressing traditional process boundaries while elevating emissions traceability to a competitive differentiator across specification tiers.
Continuous strip casting is decomposing conventional hot rolling sequences by enabling direct gauge reduction from liquid metal to near-final thickness. Automotive body sheet producers in Germany are piloting twin-roll cast lines for 5xxx-series closure panels. This bypass is collapsing capital intensity thresholds for new market entry and eroding the scale advantages of traditional integrated mills.
REACH carbon border adjustments are mandating Scope 3 emissions documentation for imported mill products entering European automotive supply chains. Non-European suppliers face competitive exclusion without certified low-carbon primary metal sourcing. Chinese and Indian exporters are responding with dedicated low-carbon product lines and third-party verification investments.
Buyer consolidation among tier-one automotive stampers is compressing supplier qualification cycles and unbundling toll-processing from metal supply contracts. Large German and US OEMs are direct-sourcing slab and delegating rolling to contracted processors. This disintermediation is visible most acutely in battery enclosure supply chains where cell manufacturers specify alloy and gauge directly.
Aluminum Flat Products Market Segmentation
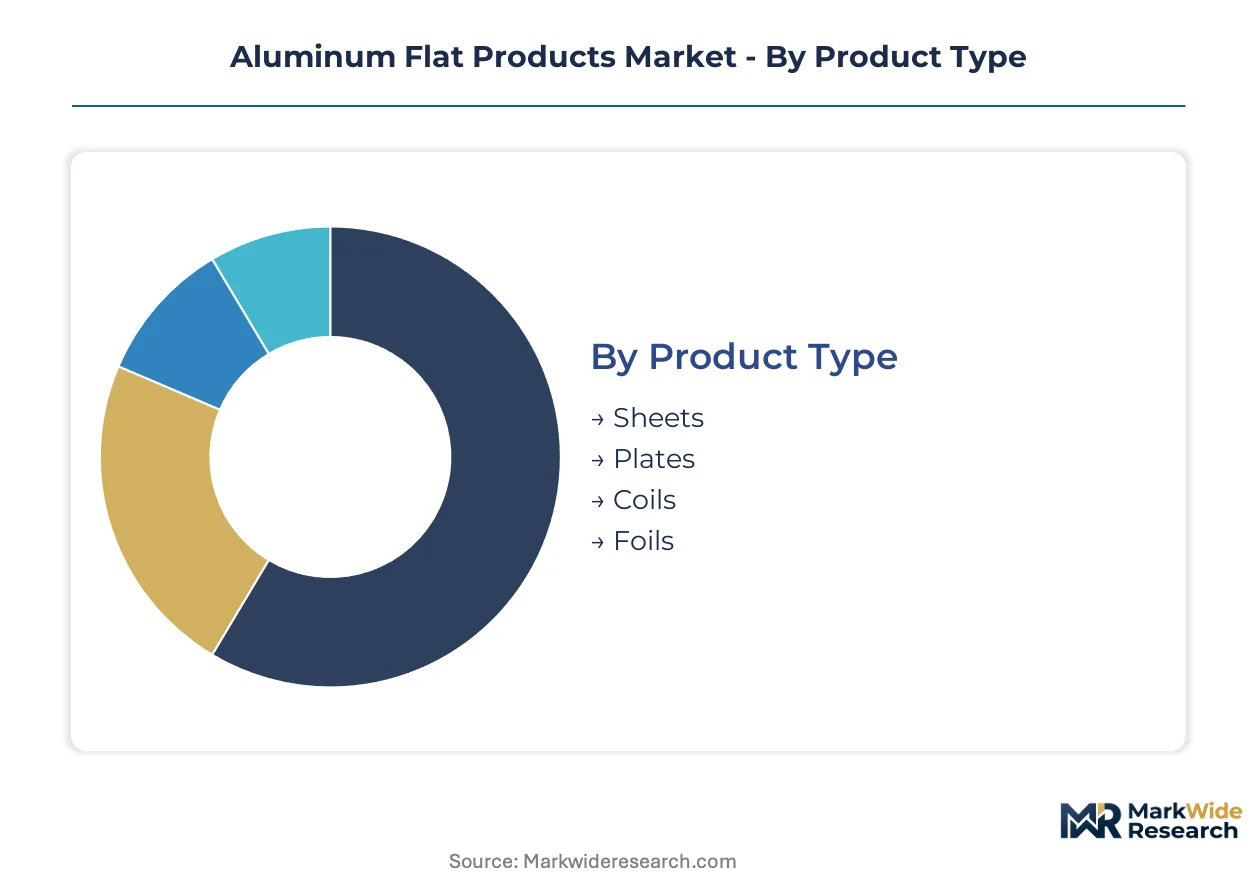
Segmentation in aluminum flat products reveals how margin pools concentrate in specification-intensive grades where certification barriers and alloy complexity limit supplier participation. Understanding these divides enables precise targeting of capacity investments and qualification resources.
Product Type:
Margin pools concentrate in plate and aerospace-grade sheet where AS9100 certification and OEM-specific qualifications sustain premium positioning above commodity coil products.
- Sheets:Rolled aluminum alloys delivered in flat geometries, typically 0.2-6.0 mm thick, serving automotive body panels and general fabrication. Demand concentrates in 6xxx-series automotive body sheet across German and US assembly plants, pulled by NHTSA fuel economy mandates requiring closure panel lightweighting.
- Plates:Thicker flat products exceeding 6.0 mm, produced to tight metallurgical specifications for structural load-bearing applications. Aerospace wing and fuselage programs in the United States and France sustain margin premiums through 18-36 month qualification cycles that freeze supplier switches.
- Coils:Continuously wound sheet metal supplied to high-volume stamping operations. Packaging and construction applications dominate volume, with commodity pricing pressure from Chinese mill exports.
- Foils:Ultra-thin products below 0.2 mm, including household, container, and technical grades. Lithium-ion battery current collector specifications are pulling ultra-thin foil demand in South Korean and Japanese electrode supply chains.
The dominant share belongs to coils, while sheets are closing the gap fastest.
End User:
Application-driven segmentation maps directly to specification intensity, with aerospace and automotive commanding alloy development resources while construction and packaging compete on throughput scale.
- Aerospace:Wing skins, fuselage panels, and structural members requiring damage-tolerant alloys with traceable melt history. Boeing and Airbus qualification protocols in the United States and France limit qualified supplier pools to mills with integrated primary smelting and dedicated aerospace rolling lines.
- Automotive:Body-in-white panels, closures, and battery enclosures where strength-to-weight optimization determines platform economics. Cell-to-pack architectures across German and Chinese EV assembly lines are accelerating specification upgrades to higher-strength 6xxx and 7xxx grades.
- Construction:Building envelope cladding, roofing, and structural applications where corrosion resistance and formability outweigh strength requirements. Volume concentration in Chinese and Indian infrastructure programs sustains commodity-grade coil demand.
- Packaging:Beverage cans, food containers, and flexible packaging laminates. Mature demand in North American and European can stock competes with emerging Asian market expansion.
Aerospace captures the highest margin per ton, though automotive is expanding most quickly.
Thickness:
Thickness classification determines rolling mill configuration requirements and correlates with end-use structural loading, creating distinct equipment specialization barriers between thin and thick product specialists.
- Thin:Products below 0.5 mm, primarily foils and light-gauge packaging sheet. Battery current collector specifications in South Korea and Japan demand thickness tolerances approaching metallurgical limits.
- Medium:0.5-6.0 mm range covering automotive body sheet and general industrial applications. German OEMs are piloting twin-roll casting for 5xxx-series closure panels in this band to collapse hot rolling sequences.
- Thick:6.0-25.0 mm plates for structural and marine applications. Shipbuilding programs in South Korea and Japan sustain demand for corrosion-resistant 5xxx-series plate.
- Extra Thick:Above 25.0 mm, specialized for heavy industrial and defense applications. Limited mill capacity and long lead times sustain premium positioning.
Medium thickness commands the largest volume position, with thin grades climbing the fastest on battery foil demand.
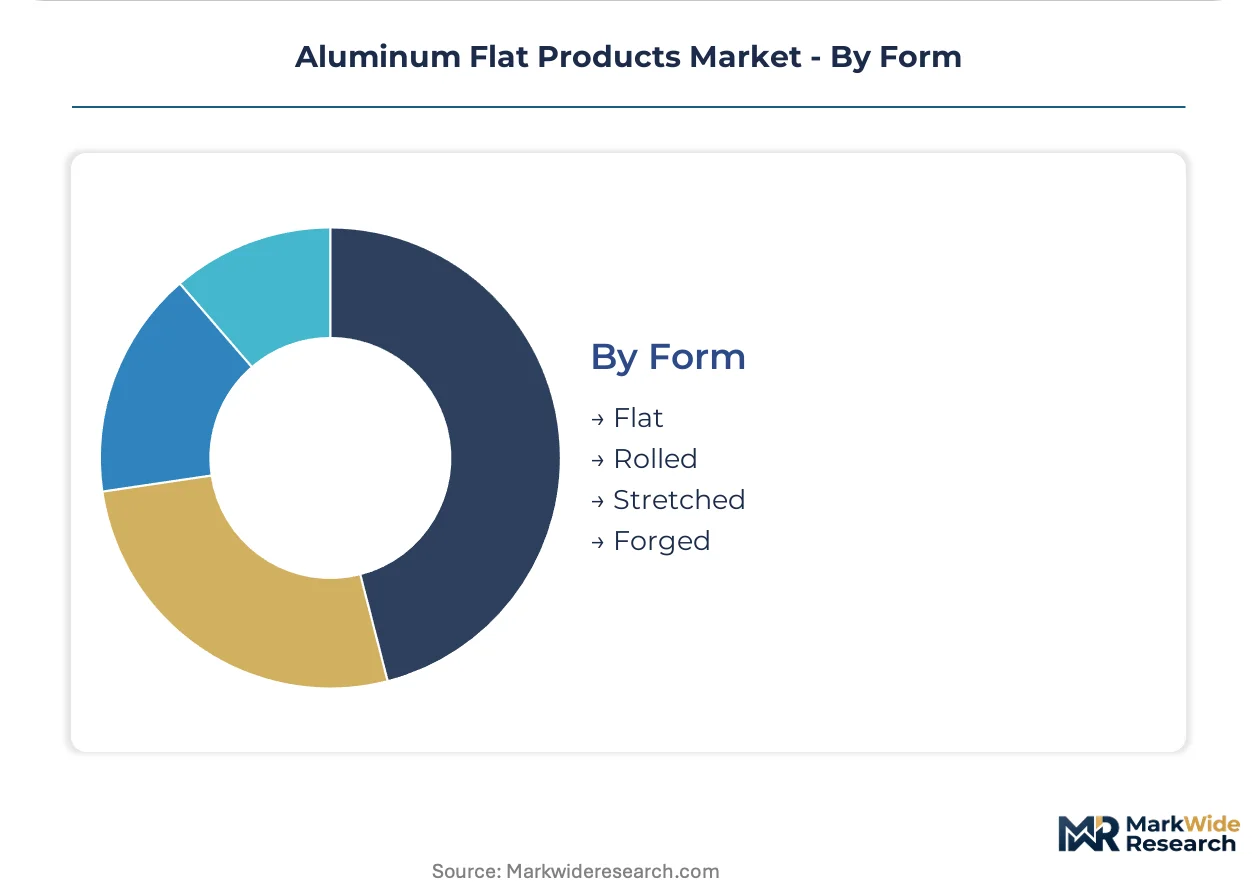
Form:
Form segmentation reflects processing method and resulting metallurgical properties, with rolled products dominating volume and forged forms retaining niche premium positioning in aerospace structural components.
- Flat:Direct-rolled or cast products with minimal subsequent working. Standard construction and packaging applications drive volume, with limited differentiation beyond surface finish.
- Rolled:Products subjected to sequential hot and cold rolling for precise gauge control and mechanical property development. Automotive and aerospace specification tiers require dedicated rolling mill investments with integrated heat treatment.
- Stretched:Plates subjected to post-rolling tension leveling to relieve residual stresses and improve dimensional stability. Wing and fuselage applications in the United States and France mandate this form for damage tolerance compliance.
- Forged:Hammer or press-forged products with refined grain structure for maximum strength-to-weight ratios. Landing gear and bulkhead applications in defense and commercial aerospace sustain limited but high-margin demand.
Rolled forms hold the dominant share, while stretched products are gaining share fastest on aerospace build rate recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb specification premiums for automotive-grade sheet with minimal price elasticity, while Chinese construction and Indian infrastructure purchasers drive volume through cost-sensitive commodity coil procurement.
United States
NHTSA corporate average fuel economy rules mandate aluminum closure panels across Detroit Three assembly programs. The EPA tailpipe emission standards reinforce lightweighting compliance timelines. Michigan and Ohio rolling corridors supply body-in-white sheet to Kentucky and Tennessee EV battery plants.
Germany
OEM specification upgrades to 6xxx-series alloys accelerate across BMW, Mercedes-Benz, and Volkswagen platforms. The EU Carbon Border Adjustment Mechanism imposes upstream emissions documentation requirements on imported coil. Bavarian and North Rhine-Westphalia mills pilot twin-roll casting for closure panel production.
China
Dual carbon goals force Shandong and Xinjiang smelters to reconfigure power sourcing toward grid decarbonization. The Ministry of Ecology and Environment tightens emissions intensity benchmarks for rolling mill permits. Yangtze River Delta battery manufacturers specify high-strength sheet for cell-to-pack enclosures.
India
PLI scheme incentives attract specialty alloy rolling investments for domestic automotive and aerospace demand. The Bureau of Indian Standards advances alloy certification protocols for defense and infrastructure applications. Gujarat and Maharashtra industrial corridors host downstream capacity expansions serving stampers in Tamil Nadu and Karnataka.
Japan
Ultra-thin foil specifications for lithium-ion battery current collectors pull metallurgical investment from South Korean electrode supply chains. METI industrial decarbonization roadmaps pressure smelter power sourcing disclosures. Kansai and Chubu rolling clusters supply precision strip to Osaka and Nagoya battery component manufacturers.
Aluminum Flat Products Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the aluminum flat products value chain. Integrated primary producers with captive smelting command margin stability through LME volatility, while downstream rolling specialists compete on alloy development speed and qualification relationships. Three archetypes dominate: integrated miners-to-metal giants, closed-loop recycling specialists, and regional toll-processors serving automotive OEM direct-sourcing programs. Capacity expansion and M&A consolidation represent the dominant competitive moves, particularly for battery enclosure sheet qualification.
Among North American integrated producers, Alcoa Corporation and Arconic occupy positions spanning primary smelting through aerospace-grade plate. Novelis exemplifies the closed-loop recycling archetype with toll-processing networks serving automotive OEM take-back mandates. Constellium and UACJ Corporation represent European and Japanese premium-tier specialists respectively, anchoring qualification-dependent segments where AS9100 and OEM-specific protocols limit supplier churn.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Novelis |
| Constellium |
| Hindalco Industries Limited |
| Norsk Hydro |
| Arconic |
| UACJ Corporation |
| Aleris Corporation |
| National Aluminum Company Limited (NALCO) |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German automotive OEMs and European rolling mills lock in both aluminum slab supply and price visibility across multi-year vehicle platform cycles. These arrangements transfer LME volatility risk to integrated primary producers while securing qualified mill capacity for 6xxx-series body sheet programs.
Pricing Analysis
After-sales service contracts for automotive toll-processing generate recurring revenue streams that offset margin compression in commodity coil sales. Three-tier pricing structure across aerospace-certified plate, automotive-grade sheet, and commodity construction coil separates specification premiums by certification intensity. Pricing pressure stems from Chinese export coil flooding Southeast Asian spot markets. Construction buyers in India exhibit highest price sensitivity, while aerospace procurement teams in France and the United States absorb premiums with minimal elasticity.
Supply Chain Analysis
Inventory buffers at German automotive stamping plants have compressed to three-week rolling schedules, forcing just-in-time coordination with Bavarian mill heat-treatment lines. Primary aluminum supply concentrates in China, Russia, and Canada, with rolling capacity clustering in Germany, the United States, and Japan. Bauxite feedstock draws from Australian and Guinean mines, while rolling mill operations hinge on natural gas and renewable power sourcing. Single-source vulnerability persists for aerospace-grade 7xxx-series slab qualified to Boeing and Airbus specifications. Distribution runs through mill-direct programs for automotive OEMs and merchant distributors for construction and packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM direct-sourcing platforms are disintermediating traditional toll-processors, creating ecosystem inflection where alloy specification control shifts from mills to cell manufacturers and platform engineers.
For Market Incumbents: Consolidate closed-loop recycling networks around European automotive take-back mandates to secure scrap supply for secondary 6xxx-series production. Deepen backward integration into captive bauxite mining to insulate rolling margins from LME volatility. Novelis and Hindalco demonstrate how scrap toll-processing arrangements defend position against Chinese export coil price pressure. For New Entrants and Emerging Players: Lead with twin-roll casting technology for 5xxx-series automotive closure panels, targeting German OEM pilot programs seeking to collapse hot rolling capital intensity. Battery current collector foils for South Korean electrode manufacturers offer the most penetrable specification tier, with qualification cycles shorter than aerospace plate. Position as dedicated low-carbon product lines with third-party verified Scope 3 documentation to meet EU Carbon Border Adjustment Mechanism requirements. For Investors and Strategic Acquirers: Capital is best deployed toward integrated miners-to-metal giants with captive smelting and established aerospace qualifications, given the five-to-ten-year viability window for primary aluminum assets. Rolling specialists with AS9100 certification and OEM-specific alloy approvals command scarcity premiums that sustain through commodity cycles. Watch for inflection in European automotive OEM direct-sourcing announcements, which signal contract structure shifts away from traditional toll-processing relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive ore supply insulates Hindalco and Alcoa from input cost volatility at LME-linked smelters. |
| Closed-Loop Recycling Network Expansion | Novelis automotive take-back arrangements secure scrap supply for secondary alloy production under EU mandates. |
| Low-Carbon Product Line Certification | Third-party verified Scope 3 documentation qualifies Chinese and Indian exporters for European automotive supply chains. |
| Twin-Roll Casting Technology Deployment | Bavarian mills pilot direct gauge reduction to bypass traditional hot rolling sequences for closure panels. |
| Battery Enclosure Sheet Qualification | Cell-to-pack architectures at German and Chinese EV plants pull high-strength 6xxx-series volume commitments. |
Methodological Framework
A spread of perspectives from rolling mill operations managers, automotive OEM platform engineers, aerospace procurement directors, and commodity trading analysts converged on the working assumptions driving this analysis. Primary fieldwork with these stakeholders combined with secondary validation from customs trade data, SEC filings of listed aluminum producers, LME warehouse stock reports, and ECHA REACH compliance databases. Bottom-up alloy-grade volume estimates triangulated against top-down national production statistics from Germany, China, and the United States.
Segmentation dimensions modeled include product type, end-use application, thickness classification, and regional production cluster across the analysis window. CAGRs derived from regression analysis of historical shipment data and projected substitution rates in automotive lightweighting programs. Forecast inputs incorporate NHTSA corporate average fuel economy compliance timelines and EU Carbon Border Adjustment Mechanism implementation phases.
Forecasts assume regulatory continuity in EPA tailpipe standards, EU Green Deal carbon border adjustments, and China's dual carbon goals; material policy shifts would require re-modeling supply and demand trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Prebaked Anodes for Aluminum Market
Metals
High-End Copper Foil Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Electrolytic Manganese Metal Market
Metals
United States Metal Casting Market
Metals
Neodymium Market
Metals
Amorphous Metal Cores Market
Metals
Steel Casting Market
Metals
Global Stretch Spring Wire Market
Metals
Copper and Copper Alloy Market
Metals
US Copper Scrap Market
Metals
Barium Market
Metals
India Metal Fabrication Market
Metals
Arc Ferrite Magnet Market
Metals
Beryllium Copper Billet Market