
 Stainless Steel Round Bar Market | 2026-2036
Stainless Steel Round Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Round Bar Market Outlook
European electric-arc furnace output is decoupling from traditional nickel-price indexing, creating margin volatility for downstream processors. ArcelorMittal leverages captive ferrochrome assets to buffer alloy surcharges across its Genk and Ghent facilities. Outokumpu sustains austenitic grade leadership through Tornio's integrated melt-to-bar circuit. Sandvik specializes in duplex and super-duplex bars for offshore energy, commanding premium positioning in North Sea supply chains.
Stainless steel round bar denotes solid cylindrical stock produced from iron-chromium alloys containing minimum ten-point-five percent chromium, with optional nickel, molybdenum, or nitrogen additions to achieve specific corrosion resistance or mechanical properties. Cold rolled bars deliver tight dimensional tolerances and enhanced surface finish for precision shafting and valve components, while hot rolled material serves structural and general engineering applications where subsequent machining removes surface scale. Forged bars dominate large-diameter requirements above two hundred millimeters for pressure vessel flanges and turbine bolting, where directional grain flow improves fatigue resistance. Aerospace end use concentrates demand for vacuum-arc remelted grades certified to AMS specifications, whereas construction procurement favors standard 304/316 grades in medium diameters for rebar alternatives and architectural supports.
ASTM A276 and ASTM A479 govern chemical composition and mechanical testing for general service and pressure-boundary applications respectively, with NACE MR0175/ISO 15156 limiting hardness for sour-gas environments. India's BIS IS 6603 and IS 6911 standards enforce domestic melt origin for government infrastructure contracts, restricting reroll access for imported blooms. The EU's Carbon Border Adjustment Mechanism will incrementally price embodied emissions in stainless bar imports from coal-intensive integrated mills. Stakeholders must model alloy surcharge exposure against scrap-based EAF cost curves and verify mill test certificate traceability ahead of evolving origin-certification requirements.
Market Dynamics
European electric-arc furnace output is decoupling from traditional nickel-price indexing, creating margin volatility for downstream processors who must now hedge alloy surcharges independently.
Growth Catalysts
- Aerospace precipitation-hardened grades:Landing gear assemblies require vacuum-arc remelted bars certified to AMS specifications, pulling high-performance material through qualified supply chains.
- India's BIS certification mandates:IS 6603 and IS 6911 standards enforce domestic melt origin for government infrastructure contracts, stimulating local capacity expansion.
- Ruhr industrial cluster demand:German tool-and-die makers source high-chromium grades for precision machining operations, concentrating procurement in a single specialized geography.
Market Restraints
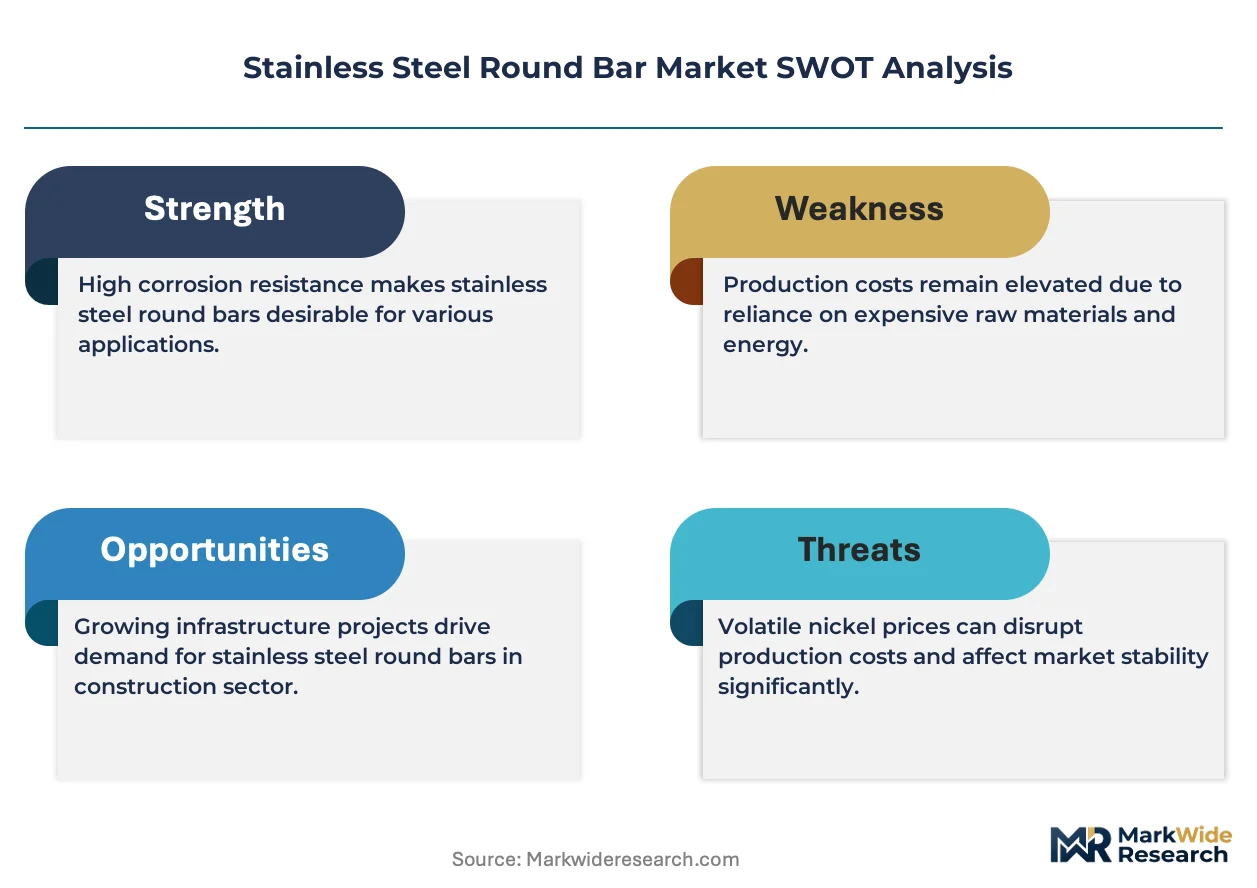
- Nickel price volatility:LME nickel futures swings transmit directly into alloy surcharge calculations, compressing processor margins when hedging proves ineffective.
- Scrap availability constraints:Premium-grade stainless scrap concentrates in European and Japanese collection networks, limiting EAF feedstock access for emerging market producers.
- Forging capacity bottlenecks:Large-diameter bar production above two hundred millimeters requires specialized press investments that few mills maintain.
Strategic Opportunities
- Offshore energy duplex grades:North Sea decommissioning and floating wind installations require super-duplex bars with PREN values above forty, commanding sustained premium positioning.
- EU Carbon Border Adjustment Mechanism:Incremental carbon pricing on imported bars creates competitive shelter for European EAF-based producers with verified low-emission credentials.
- Additive manufacturing feedstock:Gas-atomized powder derived from round bar stock opens aerospace and medical implant applications requiring lot-traceable virgin material.
Industry Challenges
- Vacuum-arc remelt certification timelines:AMS 5643 and AMS 5659 qualification cycles extend eighteen to twenty-four months, locking out new entrants from aerospace supply chains.
- NACE MR0175/ISO 15156 hardness compliance:Sour-gas environments require precise heat treatment documentation that many rerollers lack metallurgical expertise to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Round Bar Market |
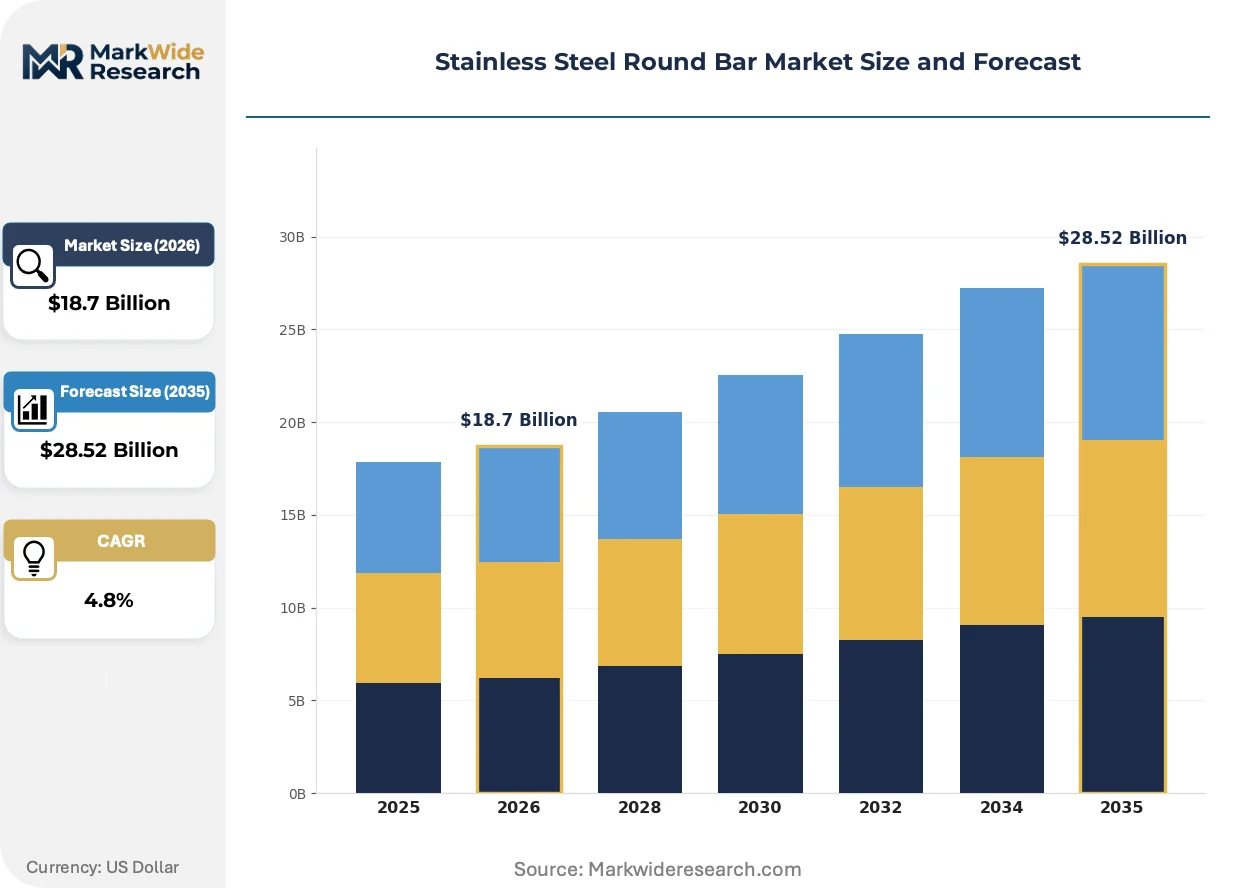
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Rolled, Hot Rolled, Forged, Extruded End Use Industry: Aerospace, Automotive, Construction, Manufacturing Size: Small Diameter, Medium Diameter, Large Diameter, Custom Size Delivery Mode: Direct Delivery, Stock Order, Just-in-Time, Others |
| Companies Covered | ArcelorMittal, Valbruna Stainless, Outokumpu, Tata Steel, Sandvik, Acerinox, Nippon Steel, Jindal Stainless, Thyssenkrupp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Round Bar Market Strategic Shifts
Digital alloy traceability and closed-loop scrap systems are restructuring how material provenance is verified and valued across stainless bar supply chains.
Blockchain-enabled mill test certificate verification is decentralizing quality assurance away from centralized third-party inspectors. Aerospace primes and nuclear fabricators now demand cryptographically signed documentation from melt to final bar. This distributed verification model compresses audit timelines while raising barriers for mills lacking integrated ERP-to-ledger connectivity.
REACH authorization requirements for hexavalent chromium in surface treatment are forcing conversion to trivalent passivation chemistries. European processors face reformulation costs for pickling and electropolishing lines. German automotive suppliers have accelerated this transition, rejecting incoming material with legacy coating specifications.
Spot-buying platforms for standard 304/316 grades are fragmenting traditional distributor relationships. Small machine shops in the US Midwest now source cut-length bar through digital exchanges that bypass regional service centers. This channel shift is most pronounced in job-shop metalworking, where price transparency outweighs technical support requirements.
Stainless Steel Round Bar Market Segmentation
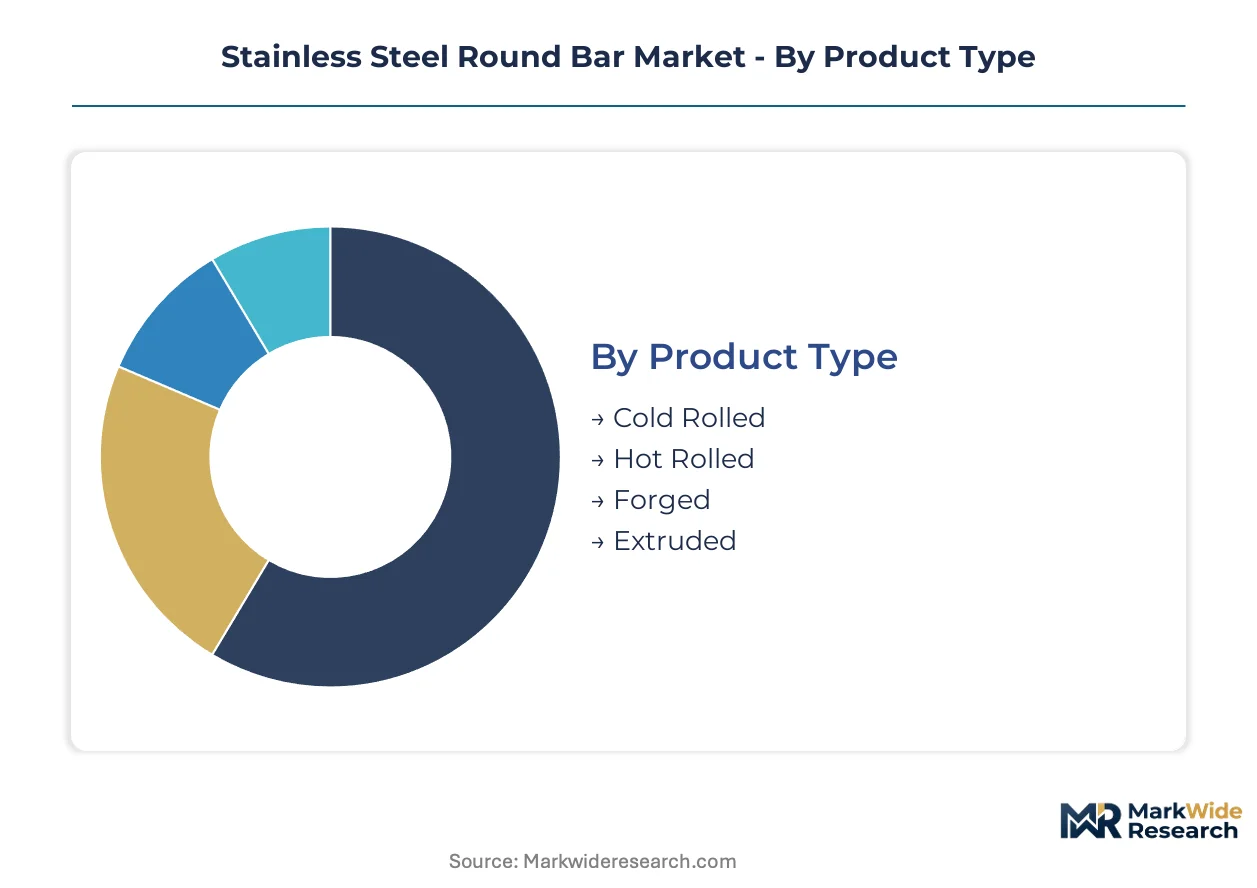
Stainless steel round bar procurement splits sharply between precision-driven specifications demanding tight tolerances and commodity-grade structural applications. Understanding these fault lines exposes where margin concentrates and where volume erodes price.
Product Type:
Cold rolled bars command premium positioning through dimensional precision, while hot rolled material anchors volume throughput in structural applications.
- Cold Rolled:Tight dimensional tolerances and enhanced surface finish suit precision shafting and valve components. German tool-and-die makers in the Ruhr cluster source these grades for machining operations where surface integrity determines tool life.
- Hot Rolled:Surface scale accepts subsequent machining removal for general engineering and structural applications. Construction procurement across India favors these grades for rebar alternatives and architectural supports under BIS IS 6603 mandates.
- Forged:Directional grain flow improves fatigue resistance for pressure vessel flanges and turbine bolting above two hundred millimeters diameter.
- Extruded:Near-net shapes reduce machining waste for specialized cross-sections in architectural and decorative applications.
Mature deployment sits with Hot Rolled. Newer deployment is concentrated in Cold Rolled.
End Use Industry:
Certification intensity separates aerospace and nuclear requirements from construction's specification flexibility.
- Aerospace:Vacuum-arc remelted grades certified to AMS specifications dominate landing gear assemblies. Precipitation-hardened alloys pull high-performance material through qualified supply chains with eighteen to twenty-four month qualification cycles.
- Automotive:German automotive suppliers enforce trivalent passivation chemistry compliance ahead of REACH authorization deadlines for hexavalent chromium.
- Construction:Standard 304/316 grades in medium diameters serve rebar alternatives and architectural supports. India's BIS IS 6911 standards enforce domestic melt origin for government infrastructure contracts.
- Manufacturing:General machine shops source cut-length bar through digital exchanges that bypass regional service centers, fragmenting traditional distributor relationships.
Certification barriers protect Aerospace margins. Price transparency is eroding Manufacturing procurement.
Size:
Processing capability constraints create discontinuities in supply availability across diameter ranges.
- Small Diameter:Cold finishing capacity concentrates in European and Japanese mills with precision rolling expertise.
- Medium Diameter:Construction and general engineering applications favor this range where standard inventory positions reduce lead times.
- Large Diameter:Forged bars dominate above two hundred millimeters where specialized press investments limit producer count. Directional grain flow requirements for pressure vessel flanges sustain premium positioning.
- Custom Size:Project-specific diameters for offshore energy and nuclear applications require mill-direct relationships with heat treatment documentation.
Capacity bottlenecks concentrate in Large Diameter. Standard inventory deployment dominates Medium Diameter.
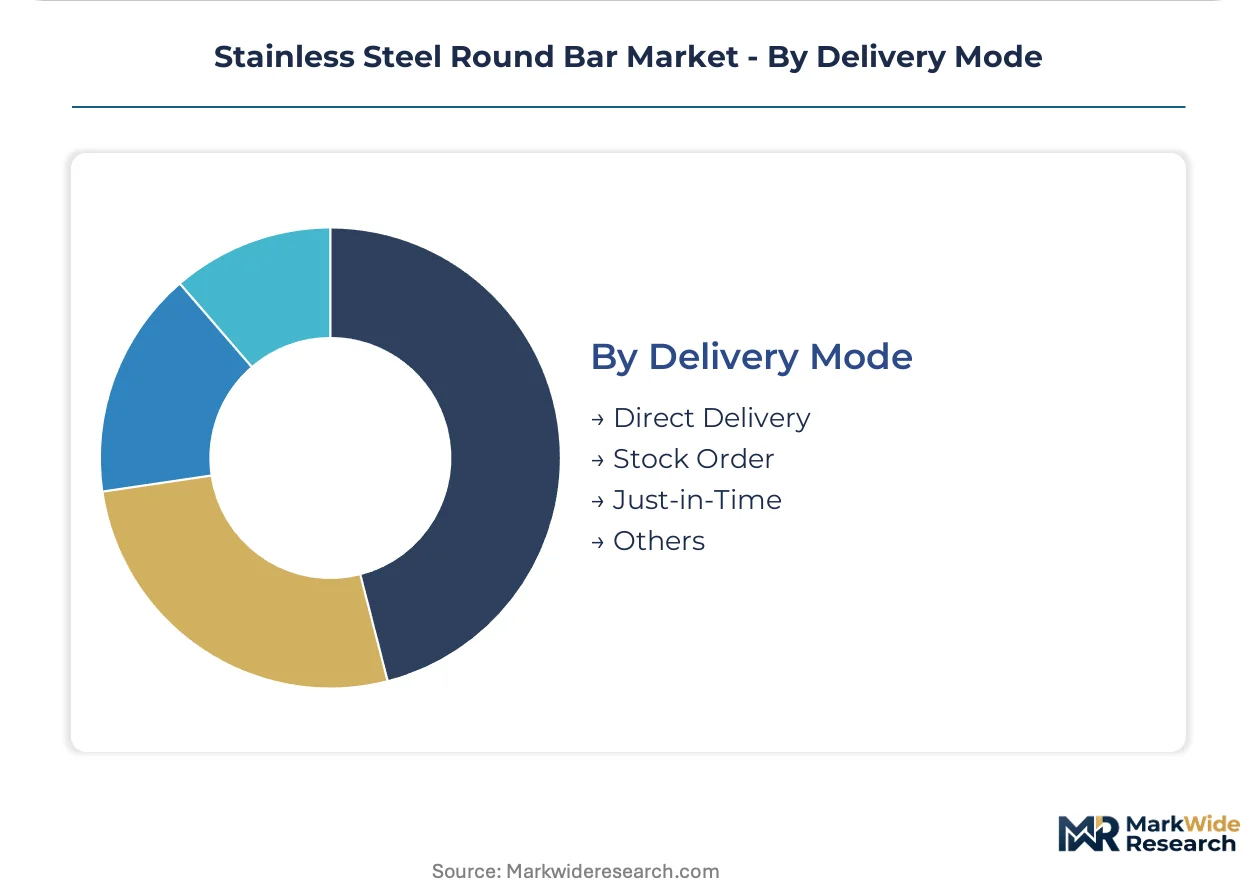
Delivery Mode:
Working capital requirements and demand predictability determine channel selection across customer segments.
- Direct Delivery:Mill-direct relationships serve aerospace primes and nuclear fabricators demanding cryptographically signed documentation from melt to final bar.
- Stock Order:Regional service centers hold standard 304/316 grades for job-shop metalworking where price transparency outweighs technical support.
- Just-in-Time:Automotive and precision manufacturing contracts synchronize delivery with production schedules, transferring inventory risk upstream.
- Others:Consignment arrangements and vendor-managed inventory serve long-term infrastructure contracts with predictable offtake.
Inventory risk sits with Stock Order. Demand predictability enables Just-in-Time expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromium ore deposits in South Africa and Kazakhstan anchor raw-material access for integrated stainless steel producers serving round bar markets across multiple continents.
Germany
Ruhr industrial cluster tool-and-die makers pull high-chromium grades for precision machining operations requiring tight dimensional tolerances. REACH authorization requirements for hexavalent chromium in surface treatment force conversion to trivalent passivation chemistries across processing facilities. Düsseldorf-based fabricators serve automotive suppliers rejecting legacy coating specifications ahead of regulatory deadlines.
India
Bureau of Indian Standards IS 6603 and IS 6911 mandates enforce domestic melt origin for government infrastructure contracts, stimulating local capacity expansion. BIS certification tightening for structural alloy bars restricts reroll access for imported blooms. Maharashtra and Gujarat industrial corridors concentrate new EAF investments serving construction rebar alternatives and architectural support applications.
United States
Midwest machine shops source cut-length bar through digital exchanges that bypass traditional regional service centers. Aerospace primes demand vacuum-arc remelted grades certified to AMS specifications for landing gear assemblies. Pennsylvania and Ohio processing facilities face margin compression from nickel-price volatility decoupled from traditional indexing mechanisms.
China
Dual carbon goals under MIIT guidance reshape integrated mill emissions profiles for stainless bar exports facing EU Carbon Border Adjustment Mechanism pricing. Yangtze River Delta fabricators concentrate cold-finishing capacity for precision shafting applications. NMPA-aligned quality documentation requirements strengthen for medical implant feedstock derived from round bar stock.
Japan
Premium-grade stainless scrap collection networks concentrate in industrial zones supporting EAF feedstock access for high-performance grades. METI-coordinated standards alignment reinforces JIS certification for aerospace and nuclear applications. Osaka-Kobe manufacturing belt maintains precision rolling expertise for small-diameter cold-rolled bars serving valve component producers.
Stainless Steel Round Bar Market Competitive Environment
Global majors compete with regional champions across integrated melt-to-bar circuits versus specialized reroll and finishing operations. The market structure tiered between captive ferrochrome-backed producers, scrap-based EAF specialists, and precision rerollers serving specification-intensive end uses. Three archetypes dominate: integrated mining-to-bar operators controlling alloy surcharge exposure; precision cold finishers commanding premium positioning in aerospace and medical channels; and regional rerollers competing on standard grade availability and logistics proximity. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure qualified supply chain positions.
Among integrated European producers, ArcelorMittal and Outokumpu exemplify the captive raw-material archetype, with the former leveraging ferrochrome assets and the latter sustaining austenitic grade leadership through integrated melt-to-bar circuits. Sandvik occupies a specialist position in duplex and super-duplex bars for offshore energy applications. These three companies represent contrasting strategic postures: scale-driven vertical integration, process-integrated grade specialization, and premium-tier material science focus respectively.
| Leading Market Players |
|---|
| ArcelorMittal |
| Valbruna Stainless |
| Outokumpu |
| Tata Steel |
| Sandvik |
| Acerinox |
| Nippon Steel |
| Jindal Stainless |
| Thyssenkrupp |
| Others |
Value Chain & Pricing Dynamics
Electric-arc furnace decoupling from nickel-price indexing simultaneously compresses processor margins and concentrates pricing power among captive ferrochrome producers. This metallurgical accounting shift rewards integrated mills with upstream alloy control while exposing rerollers to surcharge volatility.
Pricing Analysis
Warranty-backed certification packages separate aerospace-grade vacuum-arc remelted bars from commodity 304/316 stock sold on spot exchanges. Three-tier pricing structure across premium, standard, and economy levels tracks AMS qualification status, melt origin documentation, and heat treatment traceability. Cost compression in standard grades is intensifying because Midwest machine shops now source through digital platforms that bypass regional service center markups. Automotive and nuclear fabricators show least price sensitivity given eighteen-to-twenty-four-month qualification lock-in, while job-shop metalworking tolerates specification downgrade for logistics savings.
Supply Chain Analysis
AMS and NACE certification gating restricts qualified supplier pools to mills with integrated melt-to-bar circuits and metallurgical laboratory accreditation. Chromium ore concentrates in South Africa and Kazakhstan, while premium-grade stainless scrap networks center on Germany and Japan. Feedstock draws from ferrochrome smelters, nickel cathode producers, and specialized scrap collection systems. Single-source vulnerability sits with large-diameter forging presses above two hundred millimeters, where only a handful of European and Japanese facilities maintain capacity. Distribution runs through mill-direct relationships for specification-intensive end uses and regional service centers for construction-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forging capacity bottlenecks above two hundred millimeters prop pricing power for qualified producers, creating durable margin shelter against commodity-grade competition.
For Market Incumbents: To counter spot-buying platform disintermediation in standard grades, deepen captive ferrochrome integration through Genk and Ghent facility optimization, and accelerate blockchain-enabled mill test certificate deployment to raise technical switching costs for aerospace primes. For New Entrants and Emerging Players: Launch via additive manufacturing feedstock partnerships targeting gas-atomized powder qualification for medical implant applications, exploiting lot-traceable virgin material requirements that incumbent rerollers lack metallurgical expertise to satisfy. For Investors and Strategic Acquirers: Re-rating potential sits with duplex-grade specialists given North Sea decommissioning and floating wind installation pull-through; watch PREN forty-plus specification adoption rates as inflection indicator for super-duplex premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrochrome | ArcelorMittal buffers alloy surcharge exposure across Belgian facilities via captive chromite processing. |
| AMS Certification Investment | Eighteen-to-twenty-four-month qualification cycles lock aerospace supply chain positions against reroller competition. |
| Blockchain Traceability Deployment | Cryptographically signed documentation from melt to final bar compresses audit timelines for nuclear fabricators. |
| Super-Duplex Capacity Expansion | Sandvik commands sustained premium positioning in North Sea offshore energy through PREN forty-plus metallurgy. |
| Trivalent Passivation Conversion | German automotive suppliers reject legacy hexavalent chromium coatings ahead of REACH authorization deadlines. |
Study Parameters
Document review covered customs trade data, SEC filings from listed steel producers, BIS certification registries, and AMS specification databases, complemented by interviews with melt shop managers, aerospace procurement leads, tool-and-die makers in the Ruhr cluster, and nuclear fabricator quality directors. Secondary validation drew from EAF production statistics, ferrochrome pricing benchmarks, and EU Carbon Border Adjustment Mechanism draft implementation texts. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Cross-referencing historical alloy surcharge patterns against expert panel input on nickel-price decoupling effects shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type (cold rolled, hot rolled, forged), end-use industry (aerospace, automotive, construction, manufacturing), and diameter class. CAGRs derived from capacity expansion announcements, qualified supplier count trends, and specification intensity shifts in offshore energy procurement.
LME nickel volatility, BIS certification enforcement timing, and EU carbon border pricing implementation are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about scrap availability, qualification cycle durations, and regulatory adoption trajectories. A model refresh is warranted upon material change in alloy surcharge indexing conventions or domestic melt origin mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper and Copper Alloy Market
Metals
Aluminium Collars Market
Metals
Monel Alloy Market
Metals
Global Aluminum Market
Metals
Beryllium Copper Plate Market
Metals
Galvanizing Market
Metals
Global Aluminium Wire Rod Market
Metals
Titanium Mill Products Market
Metals
Silver Cyanide Market
Metals
United States Aluminum Extrusion Market
Metals
Rhodium Market
Metals
Silver Nitrate Market
Metals
Copper Azoles Market
Metals
Niobium Market
Metals
Hafnium Foil Market
Metals
Global Titanium Metal Market