
 High Purity Iron Powder Market | 2026-2036
High Purity Iron Powder Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Iron Powder Market Analytics
The gap between premium and commodity tiers is shifting from purity thresholds alone toward trace-element control and lot-to-lot consistency. Höganäs AB leverages its atomization expertise to anchor supply relationships with European automotive powder metallurgy customers. JFE Steel Corporation sustains a dominant position in Asian reduced powder through integrated steelmaking feedstock control. Rio Tinto Metal Powders differentiates via spherical powder capabilities for additive manufacturing feedstock.
High purity iron powder refers to refined metallic iron with total impurity content typically below one percent, produced through atomization, reduction, or electrolysis to achieve controlled particle morphology and compressibility for sintering or magnetic applications. Its primary industrial purpose centers on structural parts manufacturing, soft magnetic cores, and advanced coatings where consistent particle size distribution determines final performance. Atomized powder commands the largest volume share due to its suitability for automotive press-and-sinter operations, while spherical powder represents the fastest-expanding category as 3D printing qualification cycles shorten and powder recyclability improves. Reduced powder maintains cost advantages in mature magnetic materials applications where sphericity requirements remain less stringent.
EPA particulate matter standards and OSHA metalworking exposure limits govern U.S. production facility emissions and workplace powder handling protocols, while REACH registration requirements in Europe restrict certain residual element profiles in imported powders. China's GB standards and MIIT industrial policies promote domestic high-purity metal powder self-sufficiency through technical specifications that increasingly mirror automotive customer audit criteria. Stakeholders must monitor evolving lot-certification requirements across these jurisdictions to anticipate which purity grades will qualify for next-generation electric motor and hydrogen system applications.
Market Dynamics
Automotive OEMs are consolidating powder metallurgy supplier bases to secure lot-to-lot consistency for electric drivetrain components, compressing qualification timelines and reshaping competitive positioning around trace-element control rather than purity thresholds alone.
Growth Catalysts
- EPA Particulate Standards:Tightening OSHA metalworking exposure limits and EPA emissions protocols are forcing U.S. production facility upgrades that favor qualified high-purity suppliers with certified handling infrastructure.
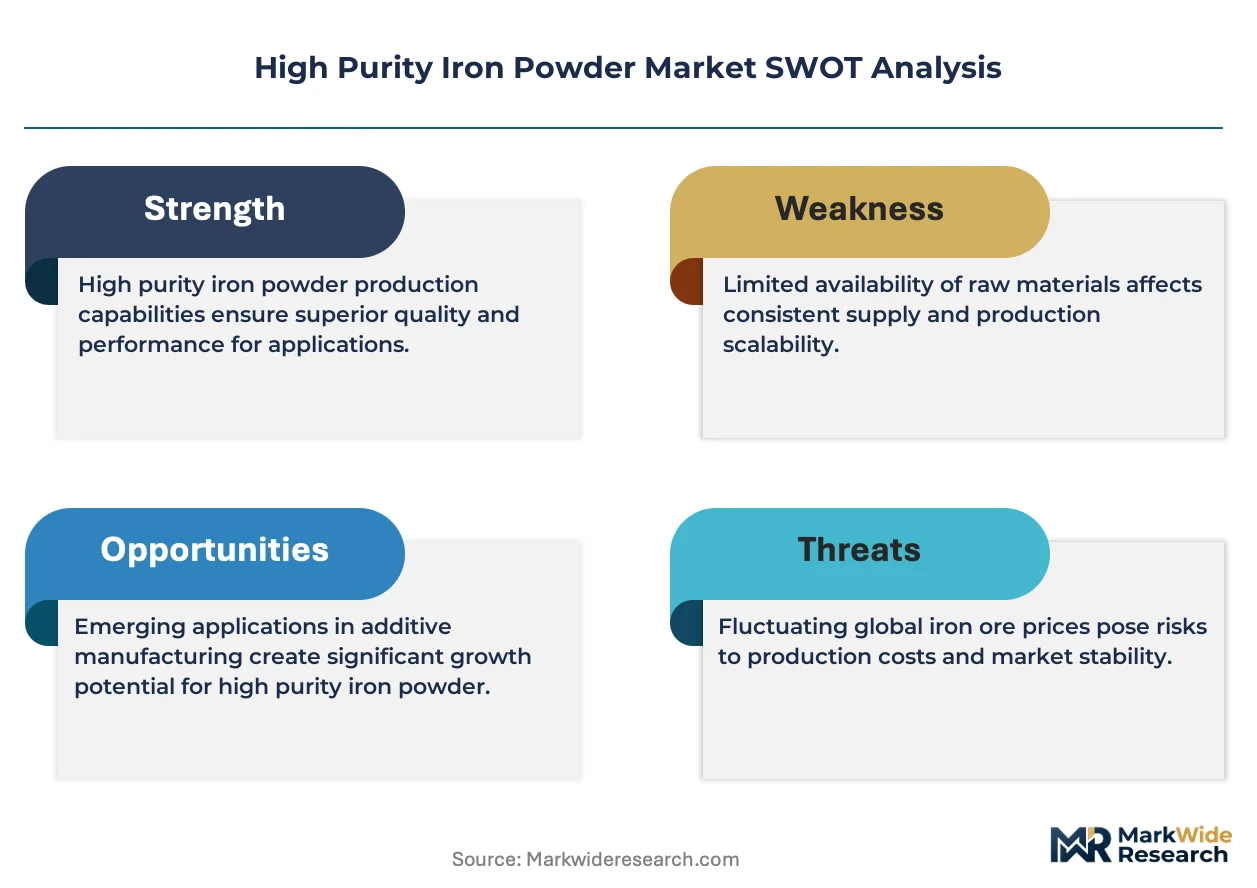
- Additive Manufacturing Feedstock:Spherical powder qualification cycles for 3D printing are shortening as powder recyclability protocols mature, expanding addressable demand beyond traditional press-and-sinter applications.
- China's Domestic Capacity Scaling:MIIT industrial policies promoting high-purity metal powder self-sufficiency are accelerating atomized powder output for soft magnetic cores and hydrogen system components.
Market Restraints
- Scrap Iron Price Volatility:Reduced powder production remains exposed to ferrous scrap input cost swings that compress margin buffers for magnetic materials suppliers.
- European Supply Concentration:REACH registration requirements and residual element restrictions concentrate qualified supply among atomization specialists with captive analytical capabilities.
- Spherical Powder Technical Limitations:Plasma atomization throughput constraints limit batch sizes for additive manufacturing qualification, elongating customer approval timelines.
Strategic Opportunities
- India's Electric Motor Manufacturing:PLI scheme incentives for domestic EV component production are creating first-mover openings for soft magnetic core powder suppliers establishing local atomization partnerships.
- Hydrogen System Components:Bipolar plate and membrane electrode assembly applications are emerging as high-purity iron powder demand centers with distinct surface area and corrosion resistance specifications.
- Direct-to-Printer Distribution:Powder OEMs are bypassing traditional distributor networks to establish certified powder management contracts with additive manufacturing service bureaus.
Industry Challenges
- Metallurgical Talent Scarcity:Atomization process engineering expertise concentrates at a handful of facilities, constraining capacity expansion timelines for new market entrants.
- Multi-Jurisdiction Certification Burden:Simultaneous REACH, EPA, and GB standard compliance requires redundant analytical testing protocols that extend lot-release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Iron Powder Market |
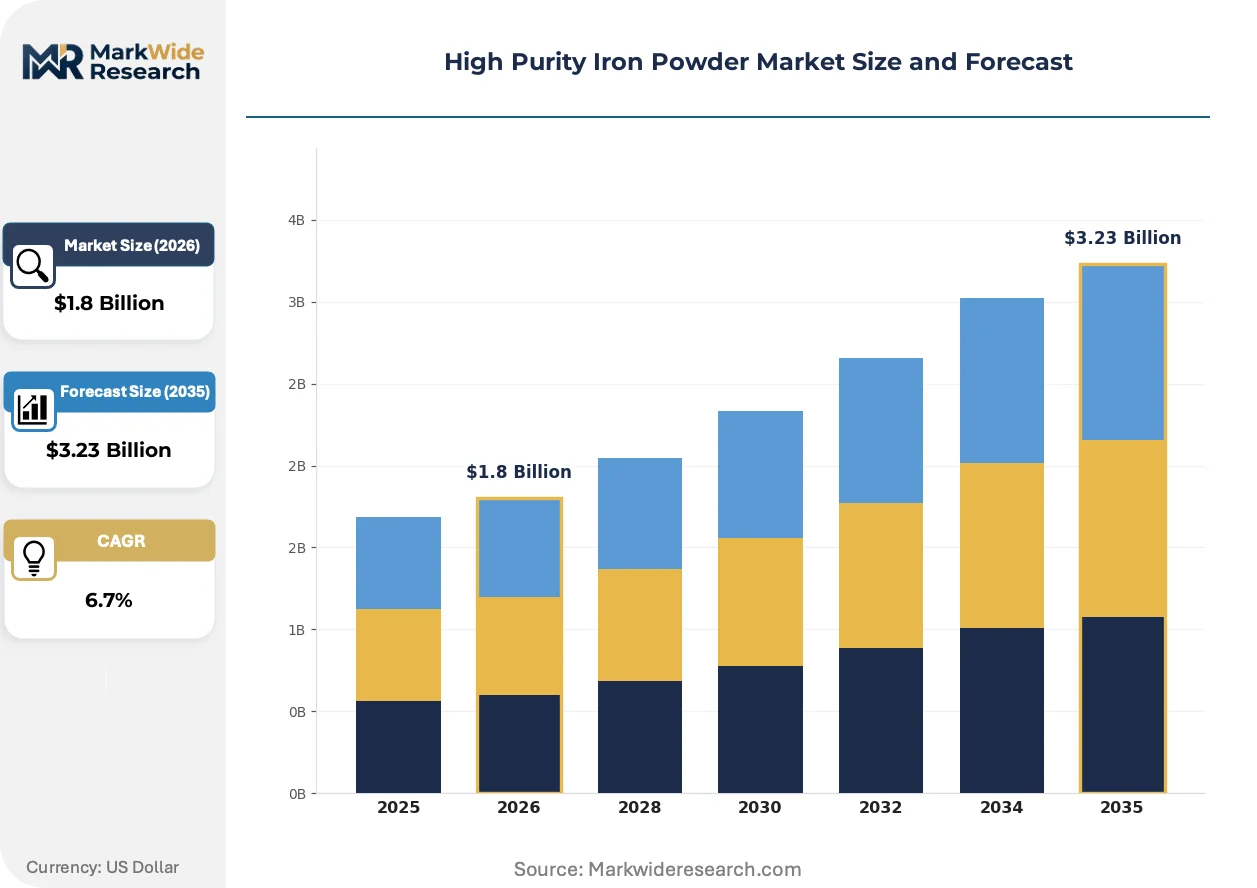
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Powder, Reduced Powder, Electrolytic Powder, Spherical Powder Application: 3D Printing, Magnetic Materials, Coatings, Electronics End User: Aerospace, Automotive Parts, Electronics Manufacturing, Chemical Industry Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Höganäs AB, Industrial Metal Powders (India) Pvt. Ltd., JFE Steel Corporation, Rio Tinto Metal Powders, BASF SE, American Elements, Reade International Corporation, Kobe Steel, Ltd., CNPC Powder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Iron Powder Market Evolving Landscape
Process control digitization and closed-loop powder recycling are compressing the gap between raw atomization output and application-specific performance specifications, reshaping how purity grades are defined and certified.
Plasma atomization is unifying spherical morphology control with oxygen content reduction in a single processing step. Aerospace and medical additive manufacturing buyers are adopting plasma-atomized feedstock for titanium and nickel superalloy components, establishing performance benchmarks that iron powder suppliers must match. This technology is unifying previously separate powder preparation stages, reducing handling contamination risk and compressing total production cycle time.
REACH registration requirements for residual element profiles are tightening supplier qualification protocols across European automotive powder metallurgy supply chains. The regulation mandates documented lot-to-lot traceability for arsenic, lead, and sulfur content that exceeds thresholds for sintered structural part applications. German and French automotive tier suppliers are responding by consolidating approved vendor lists and requiring annual third-party audit certifications.
Long-term offtake agreements are displacing spot market purchasing for high-volume automotive press-and-sinter operations. Tier suppliers are locking in three-to-five-year powder supply contracts with fixed pricing escalators and guaranteed volume allocations. This pattern is most visible in China's Yangtze River Delta automotive cluster, where domestic OEMs are securing captive atomized powder capacity through equity partnerships with steel mill affiliates.
High Purity Iron Powder Market Segmentation
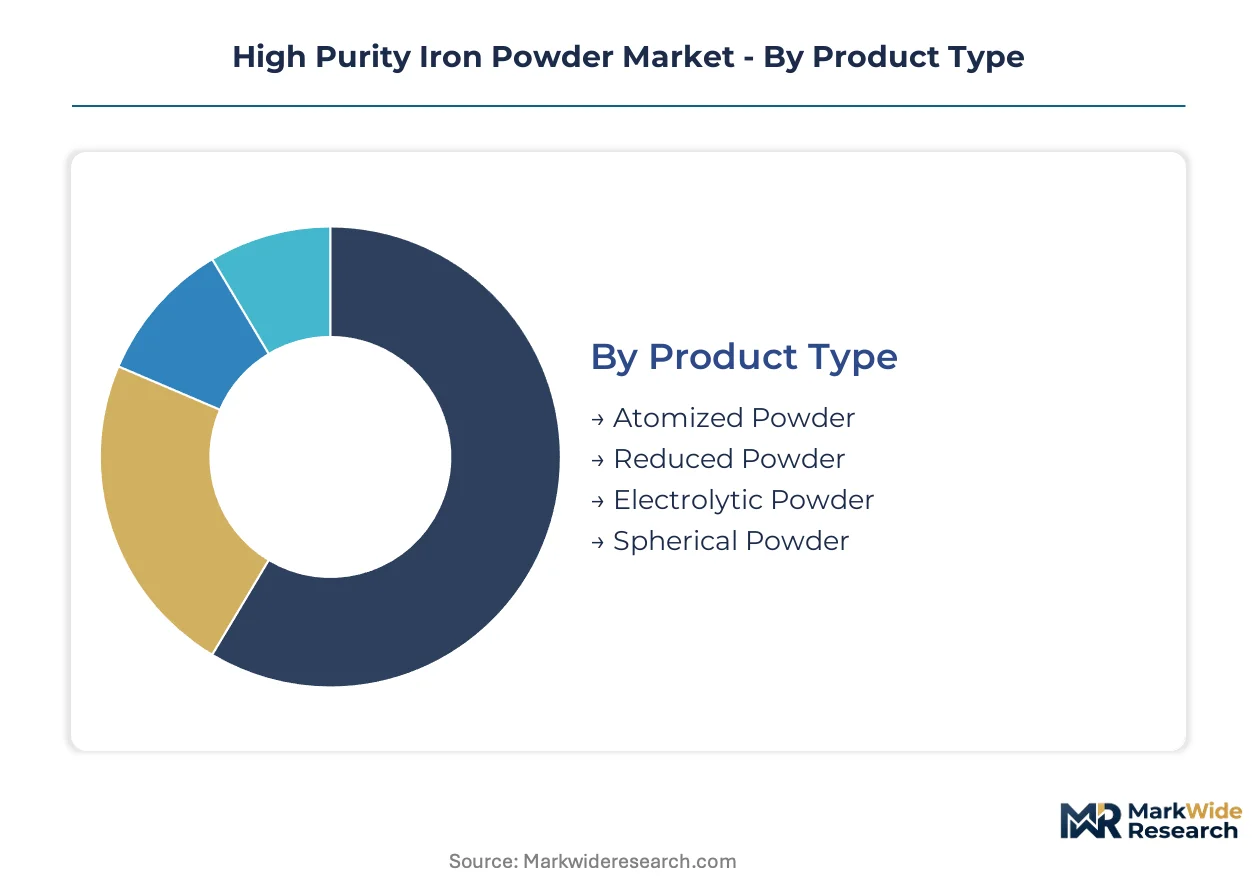
Segmentation in high purity iron powder reveals how manufacturing method, application specificity, and channel control determine margin capture. Each dimension exposes different competitive vulnerabilities around certification depth and customer lock-in duration.
Product Type:
Atomized powder dominates as a standalone feedstock requiring minimal downstream processing, while spherical powder embeds deeper into customer qualification systems with tighter specification binding.
- Atomized Powder:Produced through molten metal disintegration with water or gas, yielding irregular particles optimized for press-and-sinter density. Automotive drivetrain manufacturers in Germany and China concentrate procurement here, driven by lot-to-lot consistency requirements under REACH and MIIT audit protocols.
- Spherical Powder:Manufactured via plasma atomization or gas atomization with inert cooling, achieving near-perfect sphericity for flowability in additive manufacturing. Aerospace service bureaus in the United States and medical implant producers in Switzerland are shortening qualification cycles as powder recyclability protocols mature.
- Reduced Powder:Derived from iron oxide reduction in hydrogen or carbon monoxide atmospheres, maintaining cost advantages in soft magnetic core applications where sphericity demands remain relaxed.
- Electrolytic Powder:Produced through electrodeposition with the highest purity levels, serving niche electronics and specialty coating segments requiring sub-ppm trace element control.
Atomized powder leads volumes today; spherical powder is climbing the fastest as 3D printing adoption accelerates.
Application:
Application segmentation tracks how powder performance requirements fragment across value-added processing stages versus raw material substitution.
- 3D Printing:Demands spherical morphology with tight particle size distribution for laser powder bed fusion and binder jetting systems. Powder OEMs are establishing direct certified management contracts with service bureaus, bypassing traditional distributor networks.
- Magnetic Materials:Reduced powder anchors this segment for transformer cores and electric motor laminations, with India's PLI scheme incentives creating localized atomization partnerships for EV motor production.
- Coatings:Thermal spray and cold spray applications utilize atomized and electrolytic grades for corrosion protection, with hydrogen system bipolar plate specifications emerging as a distinct sub-segment.
- Electronics:Requires electrolytic powder for conductive pastes and electromagnetic shielding, where residual element thresholds under REACH restrict qualified supplier pools.
Magnetic materials consume the largest tonnage; 3D printing feedstock shows the steepest expansion trajectory.
End User:
End user segmentation distinguishes between specification-heavy embedded supply chains and spot-market accessible purchasing.
- Automotive Parts:Powder metallurgy tier suppliers consolidate approved vendor lists around atomized powder with guaranteed volume allocations. Long-term offtake agreements with three-to-five-year horizons now dominate procurement in China's Yangtze River Delta cluster.
- Aerospace:Qualification cycles for spherical powder in structural and engine components remain extended, though plasma atomization throughput improvements are compressing approval timelines.
- Electronics Manufacturing:Demands electrolytic grades with documented lot traceability for arsenic and lead content, concentrating supply among atomization specialists with captive analytical capabilities.
- Chemical Industry:Utilizes reduced powder for catalyst substrates and chemical reduction processes, with scrap iron price volatility compressing margin buffers for magnetic materials suppliers serving this segment.
Automotive parts anchor current demand; aerospace applications are expanding most quickly as additive manufacturing penetrates structural component production.
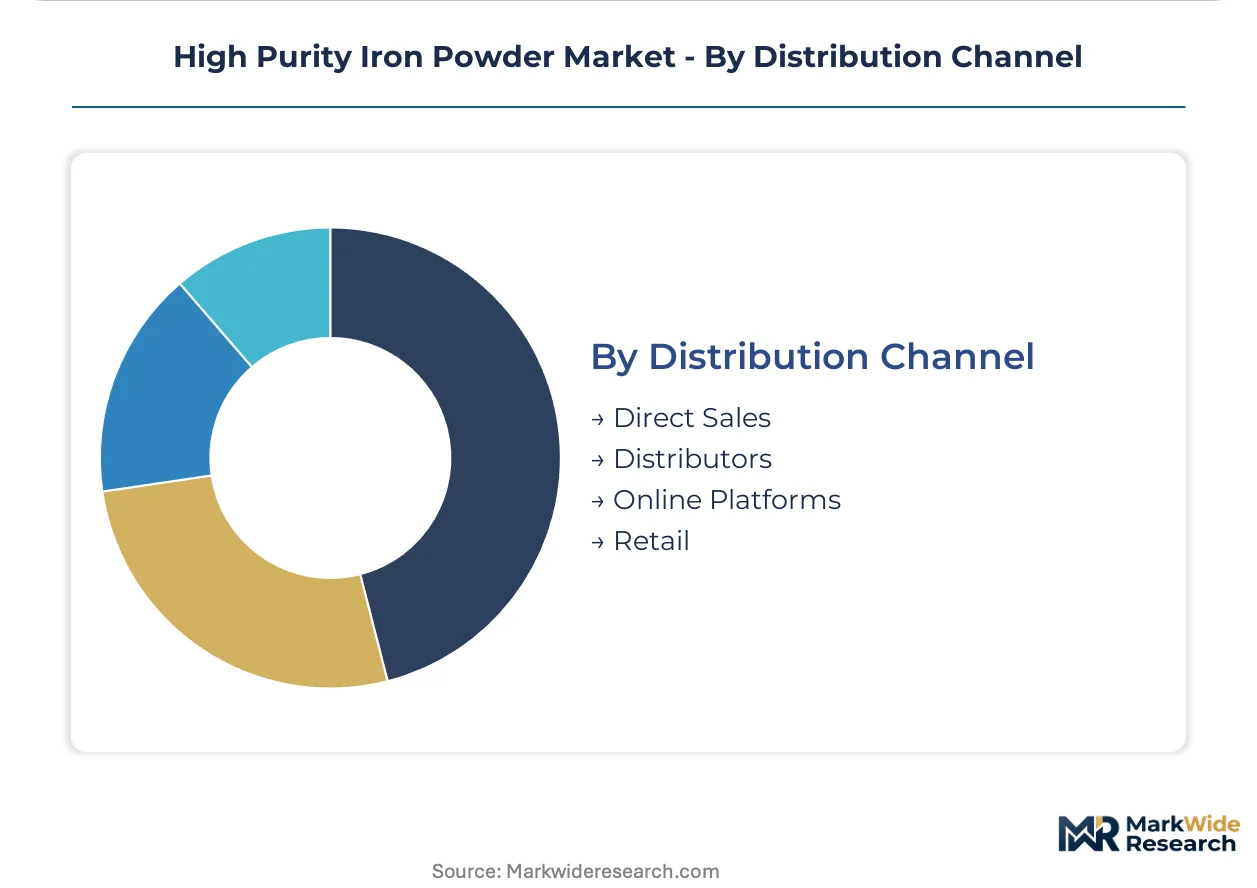
Distribution Channel:
Channel segmentation reflects the tension between technical support intensity and procurement cost minimization across customer scale tiers.
- Direct Sales:Powder OEMs deploy technical service teams for high-volume automotive and aerospace accounts, embedding specification control into customer process development.
- Distributors:Maintain inventory positions for mid-tier magnetic materials and coating customers, though REACH registration requirements are concentrating qualified supply among specialists with redundant analytical testing protocols.
- Online Platforms:Emerging for standardized atomized powder grades in research and prototyping quantities, with limited penetration in certified production supply chains.
- Retail:Minimal relevance for high purity grades, confined to hobbyist metalworking and educational supply with purity thresholds below industrial specifications.
Direct sales capture the premium tier; distributor relationships are gaining ground fastest among mid-scale additive manufacturing adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallurgical talent pools concentrate in legacy steelmaking regions where atomization expertise has accumulated across decades, anchoring production capacity near established automotive and aerospace manufacturing clusters.
China
MIIT industrial policies accelerate domestic atomized powder capacity scaling for soft magnetic cores and hydrogen system components. GB standards increasingly mirror automotive customer audit criteria for lot-to-lot traceability. The Yangtze River Delta automotive cluster secures captive atomization capacity through equity partnerships between domestic OEMs and steel mill affiliates.
Germany
REACH registration requirements tighten residual element restrictions for arsenic, lead, and sulfur content in sintered structural parts. German automotive tier suppliers consolidate approved vendor lists around atomization specialists with captive analytical capabilities. The Ruhr industrial region maintains concentrated powder metallurgy engineering expertise serving European drivetrain manufacturers.
United States
OSHA metalworking exposure limits and EPA particulate emissions protocols force production facility upgrades favoring qualified suppliers with certified handling infrastructure. Aerospace service bureaus shorten spherical powder qualification cycles as plasma atomization throughput improves. The Great Lakes manufacturing corridor anchors press-and-sinter operations for automotive drivetrain components.
India
PLI scheme incentives for domestic EV component production create first-mover openings for soft magnetic core powder suppliers. BIS standards and DGFT import policies promote localized atomization partnerships for electric motor manufacturing. The Pune-Nashik industrial belt attracts capacity investments from reduced powder producers serving transformer core applications.
Japan
METI industrial policies support advanced powder metallurgy R&D for next-generation electric motor laminations. JIS standards govern particle size distribution specifications for automotive press-and-sinter operations. The Chubu region around Nagoya maintains integrated steelmaking-to-powder production chains serving precision automotive component manufacturers.
High Purity Iron Powder Market Competitive Landscape
Top-tier vendors anchor atomization technology leadership, while mid-scale reduced powder specialists compete on magnetic materials cost positioning. The vendor base stratifies across captive steelmaking feedstock control, independent atomization specialists, and diversified chemical conglomerates with powder divisions. Three archetypes dominate: integrated steelmakers leveraging ore-to-powder traceability, standalone atomization houses with plasma spherical capabilities, and regional reduced powder producers serving cost-sensitive magnetic applications. Competitive moves concentrate on long-term offtake contracting and plasma atomization capacity expansion for additive manufacturing qualification.
Within the integrated steelmaker archetype, JFE Steel Corporation and Kobe Steel, Ltd. exemplify feedstock-controlled positioning. Höganäs AB occupies a position among standalone atomization specialists with established European automotive relationships. Rio Tinto Metal Powders represents the mining-affiliated model with spherical powder capabilities for emerging aerospace and medical additive manufacturing feedstock demand.
| Leading Market Players |
|---|
| Höganäs AB |
| Industrial Metal Powders (India) Pvt. Ltd. |
| JFE Steel Corporation |
| Rio Tinto Metal Powders |
| BASF SE |
| American Elements |
| Reade International Corporation |
| Kobe Steel, Ltd. |
| CNPC Powder |
| Others |
Value Network & Pricing Analysis
Captive atomization capacity integrated into Yangtze River Delta steel mill affiliates anchors both supply security and pricing power for Chinese automotive OEMs, compressing spot market liquidity and elevating long-term contract premiums for qualified European suppliers under REACH protocols.
Pricing Analysis
Contract-based long-term offtage agreements dominate high-volume automotive procurement, unbundling raw powder from technical service and lot-certification support. Price differentiation hinges on REACH residual element documentation and plasma atomization sphericity grades, with premium tiers capturing automotive electric drivetrain contracts. Cost compression in reduced powder magnetic materials intensifies as scrap iron input volatility erodes margin buffers. Tier suppliers in transformer core applications exhibit highest price sensitivity, while aerospace additive manufacturing buyers prioritize qualification speed over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with plasma atomization specialists concentrated in Germany, Japan, and the United States, where metallurgical talent scarcity constrains capacity replication. Feedstock draws from integrated steelmaking ore-to-powder chains, merchant scrap reduction operations, and electrolytic deposition facilities. Regulatory restriction risk concentrates in REACH registration timelines and EPA particulate handling certifications. Distribution runs through direct technical service relationships for automotive and aerospace accounts, with distributor networks retaining mid-tier magnetic materials and coating customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with automotive OEM consolidation around electric drivetrain powder metallurgy specifications shifting procurement toward trace-element-controlled premium grades and away from commodity purity thresholds.
For Market Incumbents: Acquire plasma atomization engineering teams to compress additive manufacturing qualification cycles and defend against standalone spherical powder specialists. Consolidate approved vendor relationships through three-to-five-year offtake agreements with fixed pricing escalators, locking in Yangtze River Delta automotive cluster demand before domestic Chinese capacity fully matures. For New Entrants and Emerging Players: Direct-to-printer digital distribution routes bypass established distributor networks and capture additive manufacturing service bureau demand as powder recyclability protocols standardize. Target India's Pune-Nashik industrial belt for soft magnetic core partnerships under PLI scheme incentives, offering localized atomization capacity that incumbent reduced powder producers lack. Position around hydrogen system bipolar plate specifications as an emerging application with distinct surface area requirements. For Investors and Strategic Acquirers: Roll-up economics work for standalone atomization specialists because automotive supplier consolidation is compressing the number of qualified vendors while elongating contract durations. Mid-cap European and North American plasma atomization houses with captive analytical capabilities represent the priority acquisition archetype. Watch for MIIT policy acceleration in China as the signal indicating whether domestic capacity scaling will displace import demand or merely absorb incremental growth.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Capacity Expansion | Compresses aerospace spherical powder qualification timelines for titanium and nickel superalloy benchmarks. |
| Backward Integration into Steelmaking Feedstock | Ore-to-powder traceability secures REACH-compliant residual element control for European automotive tier suppliers. |
| Direct-to-Printer Distribution Contracts | Bypasses traditional distributor networks to embed powder OEMs into additive manufacturing service bureau operations. |
| Long-term Offtake Agreement Structuring | Locks in Yangtze River Delta automotive demand through equity partnerships with domestic steel mill affiliates. |
| Hydrogen System Component Qualification | Opens bipolar plate and membrane electrode assembly specifications with distinct corrosion resistance requirements. |
Research Methodology
Bottom-up automotive and aerospace demand modeling reconciled against top-down atomization capacity tracking forms the analytical core. Primary interviews with powder metallurgy procurement directors, plasma atomization process engineers, REACH compliance officers, and additive manufacturing service bureau operators combined with secondary validation from SEC filings, customs trade data, MIIT industrial policy disclosures, and automotive production databases. Triangulation between end-use consumption estimates and supply-side facility utilization rates resolves data gaps.
Historical trendline analysis across atomized, spherical, reduced, and electrolytic powder categories identified inflection patterns in qualification cycle duration and contract structuring. Segmentation dimensions modeled include manufacturing method, application specificity, end-user industry, and distribution channel complexity, with CAGRs derived from regression against automotive electric vehicle penetration rates and additive manufacturing equipment installation growth. Scrap iron price volatility indices and REACH registration timeline distributions served as industry-specific forecast inputs.
Raw material cost swings, regulatory approval delays, and technology substitution in electric motor laminations are the dominant revision risks. Forecasts embed assumptions around MIIT capacity scaling trajectories and EPA particulate standard enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Asia-Pacific Aluminum Casting Market
Metals
Tinplate Market
Metals
Stainless Steel Sheet Market
Metals
Japan Aluminium Powder Market
Metals
India Steel Market
Metals
Steel Long Products Market
Metals
Lanthanum Market
Metals
Steel Casting Market
Metals
Lithium Foil Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Zinc Ingots Market
Metals
Carbotanium Market
Metals
Armour Steel Plate Market
Metals
Industrial Silver Market
Metals
Medium Carbon Steel Market
Metals
Cobalt Market