
 Cold Phosphating Chemicals Market | 2026-2036
Cold Phosphating Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Phosphating Chemicals Market Analytics
Zinc phosphate is shifting toward manganese and iron phosphate alternatives as OEMs target lower heavy-metal content and reduced sludge generation in pretreatment lines. Henkel AG & Co. KGaA leverages its global surface treatment portfolio to anchor automotive coating contracts across European assembly plants. BASF SE sustains R&D intensity in phosphate conversion coatings through dedicated application labs in Ludwigshafen. Chemetall GmbH dominates aerospace-qualified cold phosphating specifications through OEM process approvals.
Cold phosphating chemicals deposit crystalline phosphate layers on ferrous and non-ferrous metal surfaces at ambient temperatures, typically operating between 25°C and 50°C with pH ranges of 3.0 to 6.0 to provide corrosion resistance and paint adhesion without energy-intensive heating. Zinc phosphate formulations occupy the largest share of product-type revenue due to entrenched automotive specification requirements, while iron phosphate is recording the fastest growth as appliance manufacturers adopt simpler single-stage processes. Spray coating technology leads volume consumption in high-throughput automotive lines, though immersion coating retains margin pools in precision aerospace and defense applications where uniform coverage in complex geometries commands premium pricing.
EPA effluent guidelines and REACH Annex XVII restrictions on chromium(VI) compounds are compelling reformulation investments across North American and European supplier bases. China's MEE enforces stricter phosphate discharge standards in the Yangtze River Economic Belt, redirecting capacity toward closed-loop recycling systems. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product variants deliver superior compliance economics.
Market Dynamics
Automotive OEMs are mandating chrome-free pretreatment specifications across their supplier networks, forcing chemical formulators to retire legacy zinc-phosphate lines and recertify conversion coatings for multi-substrate compatibility.
Growth Catalysts
- REACH Annex XVII chromium(VI) restrictions:European coating lines must eliminate hexavalent chrome passivation, redirecting specification authority toward compliant cold phosphating chemistries.
- Aluminum-intensive vehicle architectures:OEMs in Germany and the United States require iron-phosphate systems that bond to mixed-metal substrates without galvanic corrosion activation.
- Closed-loop water recycling:China's MEE discharge limits in the Yangtze River Economic Belt are compelling pretreatment shops to adopt low-sludge phosphate formulations compatible with ultrafiltration recovery.
Market Restraints
- Zinc raw material volatility:Fluctuations in zinc concentrate pricing compress margin buffers for traditional phosphate suppliers locked into long-term automotive supply agreements.
- Technical performance gaps:Iron-phosphate coatings deliver inferior salt-spray resistance versus zinc systems, limiting penetration in corrosion-critical underbody applications.
- Substitution by zirconium-based thin-film pretreatments:Nanoceramic conversion coatings from Chemetall and Henkel are displacing phosphate layers in premium automotive segments.
Strategic Opportunities
- India's expanding automotive stamping capacity:Tata Motors and Mahindra are localizing body-in-white production, creating specification windows for phosphate pretreatment suppliers establishing technical service labs.
- Electronics cooling hardware:Heat sink manufacturers in South Korea and Taiwan are adopting cold phosphating for aluminum thermal management components prior to conformal coating.
- EU Green Deal industrial decarbonization incentives:Ambient-temperature phosphate processes qualify for energy-efficiency credits against heated alkaline cleaning alternatives.
Industry Challenges
- Process engineering talent scarcity:Pretreatment line operators lack cross-training in both chemical bath analytics and closed-loop water chemistry, slowing technology transitions.
- OEM qualification timelines:Automotive specification approvals require 18-24 month corrosion and adhesion validation cycles, freezing supplier switches until model-year changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Phosphating Chemicals Market |
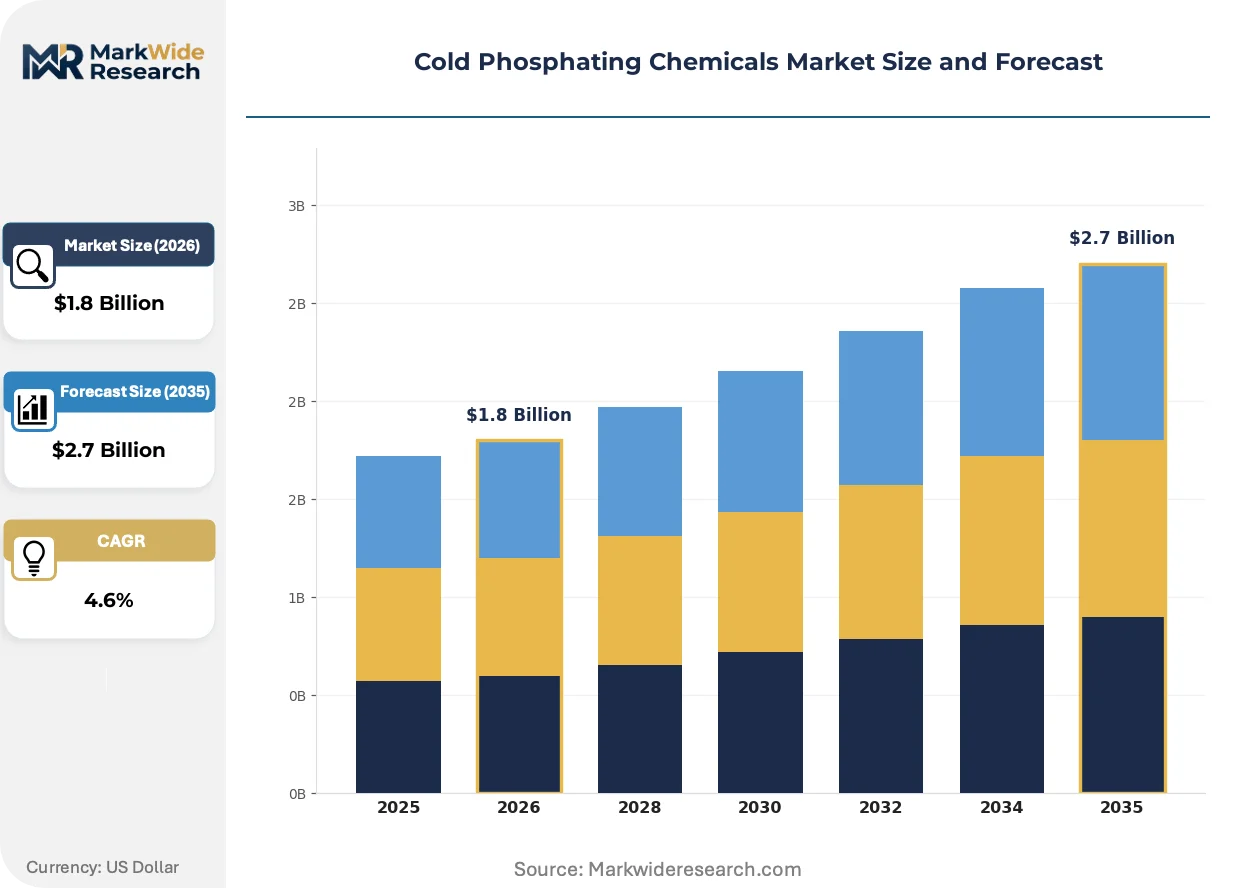
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Phosphate, Zinc Phosphate, Manganese Phosphate, Nickel Phosphate Application: Automotive Components, Electrical Appliances, Construction Materials, Aerospace Parts End User: Manufacturers, Distributors, OEMs, Aftermarket Providers Technology: Spray Coating, Immersion Coating, Electrochemical Deposition, Dip Coating |
| Companies Covered | BASF SE, Henkel AG & Co. KGaA, Chemetall GmbH, Parker Hannifin Corporation, AkzoNobel, Quaker Chemical, PPG Industries, Sika, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Phosphating Chemicals Market Evolving Landscape
Digital process control systems and real-time bath monitoring are compressing the technical distance between chemical suppliers and pretreatment line operators, reshaping how coating quality is guaranteed.
Sensor-integrated dosing equipment is automating phosphate bath chemistry maintenance in high-volume automotive plants. Tier-1 stamping suppliers in Stuttgart and Detroit are deploying conductivity and turbidity probes linked to programmable logic controllers that trigger additive replenishment without manual titration. This infrastructure is automating the technician-intensive monitoring tasks that previously caused coating defects during shift changes.
EPA effluent guidelines under the Clean Water Act are tightening total phosphorus discharge limits for metal finishing facilities. Pretreatment shops in Ohio and Michigan face permit renewals requiring zero-liquid-discharge or advanced biological phosphorus removal investments. The regulatory pressure is accelerating adoption of low-zinc and zero-zinc phosphate alternatives that generate less sludge and reduce downstream wastewater treatment burden.
Automotive OEMs are consolidating pretreatment chemical procurement through single-source framework agreements rather than regional spot purchasing. Volkswagen Group and Stellantis have shifted to global chemical supply contracts with centralized technical auditing, displacing the fragmented distributor networks that historically served individual assembly plants. This concentration is visible across European and North American coating operations where supplier reduction programs now mandate pan-regional service coverage and unified quality data platforms.
Cold Phosphating Chemicals Market Segmentation
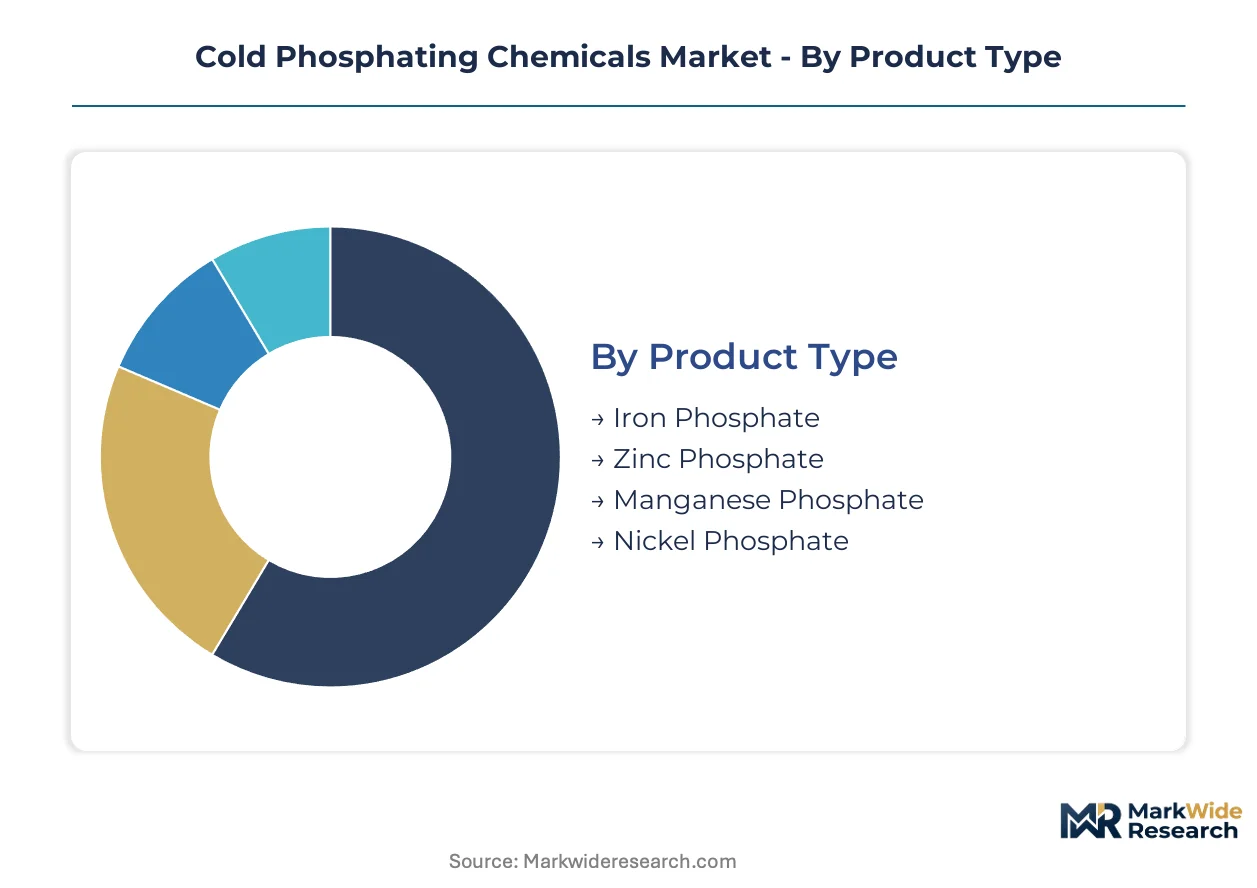
Cold phosphating chemicals segment across formulation chemistry, application method, and customer procurement patterns. Each dimension carries distinct margin profiles and qualification barriers that reshape supplier competitive positioning.
Product Type:
Standardization dominates zinc phosphate formulations while iron and manganese variants demand customer-specific tuning for substrate compatibility.
- Zinc Phosphate:Crystalline zinc phosphate conversion coatings deliver superior salt-spray resistance through dense, interlocking crystal structures. Automotive OEMs in Germany and the United States specify zinc systems for underbody and chassis components where corrosion protection spans vehicle lifetime. REACH Annex XVII chromium restrictions are redirecting specification authority toward compliant zinc-phosphate chemistries as OEMs eliminate hexavalent chrome passivation.
- Iron Phosphate:Amorphous iron phosphate deposits form at ambient temperatures with minimal sludge generation and simplified bath maintenance. Appliance manufacturers in China and Mexico are adopting single-stage iron phosphate processes for washing machine and refrigerator stampings where cost efficiency outweighs extreme corrosion requirements. EPA effluent guidelines are accelerating adoption of iron phosphate alternatives that reduce downstream wastewater treatment burden.
- Manganese Phosphate:Heavy-duty manganese phosphate coatings provide break-in lubricity for gear and bearing surfaces through oil-retentive crystalline structures.
- Nickel Phosphate:Specialty nickel phosphate formulations serve electronics cooling hardware and precision instrument applications requiring thermal conductivity with corrosion resistance.
Most installed capacity flows through zinc phosphate. Expansion is steepest in iron phosphate.
Application:
Volume concentration separates high-throughput automotive lines from precision aerospace programs with divergent qualification timelines.
- Automotive Components:Body-in-white stampings, chassis assemblies, and powertrain housings consume phosphate pretreatment chemicals across continuous conveyor systems. Aluminum-intensive vehicle architectures from Volkswagen Group and Stellantis require iron-phosphate systems compatible with mixed-metal substrates without galvanic corrosion activation.
- Aerospace Parts:Landing gear, engine mounts, and airframe structural components demand immersion-applied manganese phosphate with OEM process approvals from Chemetall and Henkel. FAA airworthiness directives and EASA certification requirements enforce 18-24 month validation cycles that freeze supplier switches until model-year changeovers.
- Electrical Appliances:Washing machine drums, refrigerator cabinets, and HVAC heat exchangers utilize spray-applied iron phosphate for cost-efficient corrosion protection prior to powder coating.
- Construction Materials:Structural steel fasteners, roofing components, and window framing systems employ zinc phosphate for outdoor durability in building envelope applications.
Automotive component demand anchors volume consumption. Aerospace parts command the highest formulation premiums.
End User:
Procurement centralization distinguishes global OEM framework agreements from fragmented distributor networks serving regional metal finishers.
- OEMs:Volkswagen Group and Stellantis have shifted to global chemical supply contracts with centralized technical auditing, displacing fragmented distributor networks that historically served individual assembly plants.
- Manufacturers:Tier-1 stamping suppliers in Stuttgart and Detroit deploy sensor-integrated dosing equipment linked to programmable logic controllers that automate bath chemistry maintenance without manual titration.
- Distributors:Regional chemical distributors serve independent metal finishing shops with blended phosphate concentrates and on-site technical service support.
- Aftermarket Providers:Automotive collision repair networks and industrial maintenance operations purchase packaged phosphate kits for spot repair and component refurbishment.
OEM direct procurement captures the largest contract value. Distributor channels retain the broadest geographic reach.
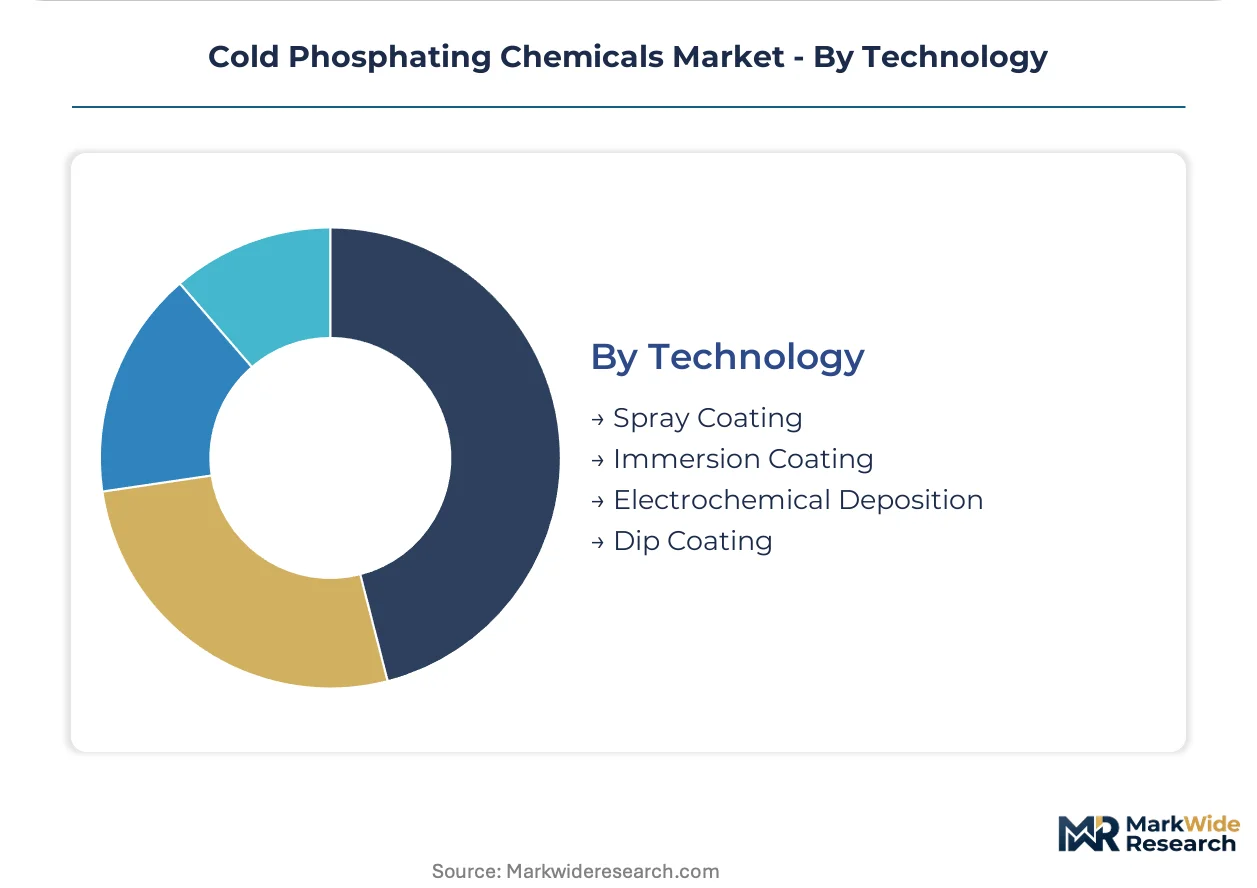
Technology:
Automation intensity separates high-volume spray operations from precision immersion cells with diverging capital requirements.
- Spray Coating:Automated spray tunnels process automotive body panels and appliance cabinets at line speeds exceeding 60 parts per minute. Conductivity and turbidity probes trigger additive replenishment without manual titration, compressing the technical distance between chemical suppliers and line operators.
- Immersion Coating:Dip tanks serve aerospace and defense applications where uniform coverage in complex geometries commands premium pricing. Chemetall dominates aerospace-qualified cold phosphating specifications through OEM process approvals for landing gear and engine mount components.
- Dip Coating:Batch immersion systems serve job shops processing mixed part geometries with flexible staging and manual transfer operations.
- Electrochemical Deposition:Anodic and cathodic phosphate systems provide enhanced coating adhesion for specialty substrates requiring controlled current density.
Spray coating infrastructure commands the largest installed base. Immersion coating retains the highest margin per liter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the highest concentration of automotive pretreatment specification authority, with German OEMs driving chrome-free chemistry mandates across their global supplier networks. Demand clusters in industrial corridors where surface treatment capacity serves automotive, aerospace, and appliance manufacturing.
United States
Detroit-area stamping plants and Ohio metal finishing corridors consume phosphate pretreatment chemicals for automotive body-in-white production. EPA effluent guidelines under the Clean Water Act tighten total phosphorus discharge limits for facilities in Michigan and Ohio, compelling zero-liquid-discharge investments. Tier-1 suppliers in Detroit deploy sensor-integrated dosing equipment linked to programmable logic controllers.
Germany
Volkswagen Group and Stellantis mandate chrome-free pretreatment specifications across European assembly plants, redirecting supplier qualification toward compliant cold phosphating chemistries. REACH Annex XVII chromium(VI) restrictions eliminate hexavalent chrome passivation from coating lines. BASF SE maintains dedicated application labs in Ludwigshafen supporting phosphate conversion coating development.
China
Yangtze River Economic Belt pretreatment shops face stricter phosphate discharge standards from MEE, redirecting capacity toward closed-loop recycling systems. Appliance manufacturers in Jiangsu and Zhejiang adopt single-stage iron phosphate processes for washing machine and refrigerator stampings. Shanghai and Suzhou industrial zones concentrate surface treatment capacity serving domestic automotive OEMs.
India
Tata Motors and Mahindra localize body-in-white production, creating specification windows for phosphate pretreatment suppliers establishing technical service labs. Central Pollution Control Board enforcement of wastewater discharge norms intensifies across automotive clusters in Maharashtra and Tamil Nadu. Pune and Chennai industrial corridors attract chemical formulators building regional application support infrastructure.
South Korea
Heat sink manufacturers in Gyeonggi-do and Incheon adopt cold phosphating for aluminum thermal management components prior to conformal coating. Ministry of Environment enforcement of industrial wastewater standards accelerates adoption of low-sludge phosphate formulations. Seoul Capital Area electronics manufacturing clusters drive demand for precision phosphate layers on cooling hardware.
Cold Phosphating Chemicals Market Competitive Landscape
Strategic partnerships dominate the current landscape as chemical suppliers align with automotive OEMs on multi-year framework agreements. The market structures around three tiers: diversified multinationals with global surface treatment portfolios, regional specialists with deep application expertise, and commodity distributors serving fragmented job shops. Three archetypes define competitive positioning: specification holders with OEM process approvals, formulation innovators with dedicated R&D infrastructure, and service-intensive providers with localized technical support. M&A activity and geographic expansion represent the dominant competitive moves as suppliers seek pan-regional coverage.
Within the diversified multinational tier, BASF SE and Henkel AG & Co. KGaA exemplify specification authority through global automotive coating contracts and dedicated application laboratories. Chemetall GmbH occupies a position as a process approval holder in aerospace-qualified cold phosphating specifications. These three German-anchored entities represent the premium-tier competitive vector where OEM qualification timelines and corrosion validation cycles create substantial entry barriers.
| Leading Market Players |
|---|
| BASF SE |
| Henkel AG & Co. KGaA |
| Chemetall GmbH |
| Parker Hannifin Corporation |
| AkzoNobel |
| Quaker Chemical |
| PPG Industries |
| Sika |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Specification-grade zinc phosphate chemistries command 40-60% premiums over commodity iron phosphate formulations, a divergence that reflects both corrosion-performance certification tiers and the concentrated supply base serving automotive OEM framework agreements. This tiered structure concentrates pricing power among German and US suppliers holding active process approvals from Volkswagen Group and Stellantis, while commodity-grade alternatives face margin compression from Chinese capacity expansion in the Yangtze River Economic Belt.
Pricing Analysis
Raw material pass-through from zinc concentrate markets drives quarterly contract adjustments for traditional phosphate suppliers locked into long-term automotive supply agreements. Pricing stratifies across aerospace-qualified, automotive-specified, and industrial-commodity tiers, with salt-spray certification levels and REACH compliance status as primary differentiation drivers. Cost compression in iron phosphate segments is intensifying because appliance manufacturers in Mexico and China prioritize unit economics over extreme corrosion performance. Tier-1 automotive stamping suppliers show the lowest price sensitivity due to specification lock-in, while independent metal finishing shops in distributor channels negotiate aggressively on blended concentrate volumes.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs require qualified backup suppliers for all phosphate pretreatment chemistries, creating redundant qualification investments across BASF, Henkel, and Chemetall production networks. Manufacturing concentrates in Germany, the United States, and China, with Ludwigshafen, Detroit-area corridors, and Shanghai-Suzhou industrial zones anchoring regional supply. Formulation draws from phosphoric acid, zinc oxide, and manganese carbonate feedstocks, with sulfuric acid derivatives as secondary inputs. Single-source vulnerability exists in aerospace-qualified manganese phosphate, where Chemetall holds dominant OEM process approvals for landing gear applications. Distribution runs through direct framework agreements with global OEMs, bypassing traditional distributor networks for high-volume automotive lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold phosphating chemicals function as a stable compounder anchored by automotive OEM specification inertia, where 18-24 month qualification cycles create durable incumbent positions even as substrate shifts toward aluminum-intensive architectures.
For Market Incumbents: Cement specification authority by securing process approvals for emerging aluminum-substrate formulations before model-year changeovers at Volkswagen Group and Stellantis. Backward integration into phosphoric acid production buffers margin pressure from sulfur and phosphate rock volatility. Prioritize certification investment in closed-loop bath chemistry systems compatible with China's MEE discharge standards, as regulatory divergence between jurisdictions favors suppliers with regional formulation platforms rather than centralized production. For New Entrants and Emerging Players: Launch via technical service partnerships with Tata Motors and Mahindra in Pune and Chennai industrial corridors, where localization of body-in-white production creates specification windows before incumbent labs achieve full regional coverage. India's automotive stamping capacity expansion represents the most penetrable geography, with Central Pollution Control Board enforcement intensifying demand for compliant pretreatment systems. Target electronics cooling hardware manufacturers in South Korea's Gyeonggi-do cluster as a secondary beachhead, leveraging simpler qualification timelines versus automotive OEM cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where regional specialists possess deep aerospace process approvals but lack pan-regional service coverage to compete for automotive framework agreements. The 5-10 year viability profile favors suppliers with dual capability in phosphate and zirconium-based thin-film pretreatments, as nanoceramic displacement threatens traditional zinc phosphate in premium segments. Acquisition targets should display active OEM process approvals in at least two geographic regulatory clusters. The signal to watch is Stellantis or Volkswagen Group awarding single-source global contracts with technical auditing requirements that exceed mid-tier supplier capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New Ludwigshafen application labs strengthen BASF's phosphate conversion coating development for REACH-compliant formulations. |
| Backward Integration | In-house phosphoric acid production insulates margin buffers from sulfur feedstock volatility in zinc phosphate lines. |
| Long-term Supply Agreement | Volkswagen Group framework contracts displace fragmented distributor networks with centralized technical auditing requirements. |
| Joint Venture | Technical service partnerships in Pune and Chennai accelerate qualification timelines for Tata Motors localization programs. |
| Green Manufacturing Transition | Ambient-temperature iron phosphate processes qualify for EU Green Deal energy-efficiency credits against heated alkaline alternatives. |
Research Methodology
Direct dialogue with pretreatment line operators, automotive OEM coating specification engineers, phosphate chemical procurement leads, and aerospace process approval managers grounded the qualitative foundation of this study. Secondary validation drew from EPA effluent guideline filings, REACH Annex XVII restriction updates, SEC 10-K disclosures from diversified chemical suppliers, and MEE discharge standard enforcement records in the Yangtze River Economic Belt. Bottom-up and top-down triangulation cross-referenced installed base estimates from automotive stamping capacity with chemical consumption rates per body-in-white unit.
Bottom-up modeling segmented volume and value across zinc, iron, manganese, and nickel phosphate formulation chemistries; spray, immersion, and dip application methods; and OEM direct, manufacturer, distributor, and aftermarket procurement channels. Top-down constraints anchored projections to automotive production forecasts and appliance manufacturing capacity in China, Germany, and the United States. CAGRs were derived from regression analysis of historical specification adoption rates and regulatory phase-in timelines, with aluminum-intensive vehicle architecture penetration and closed-loop water recycling adoption as primary industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential breakthrough displacement of phosphate layers by zirconium-based nanoceramic pretreatments, abrupt relaxation of MEE discharge enforcement in China, and automotive OEM consolidation that accelerates or delays specification standardization programs. Deviation in REACH Annex XVII expansion to cover additional heavy-metal compounds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Allyl Alcohol Market
Chemicals
Phenylethyl Market
Chemicals
Formalin Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Nonanoic Acid Market
Chemicals
Betaine Market
Chemicals
Paint Stripper Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Maleic Acid Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Immunochemicals Market