
 Lanthanum Market | 2026-2036
Lanthanum Market Size, Share, and Industry Trends Forecast 2026-2036
Lanthanum Market Outlook
Automotive battery cathode demand is pivoting sharply upward as nickel-lanthanum formulations gain traction in next-generation energy storage systems. Lynas Rare Earths leverages its Malaysian processing facility to sustain non-Chinese supply security for Western automakers. China Northern Rare Earth Group anchors domestic output through integrated mining-to-oxide operations in Baotou. MP Materials competes via its Mountain Pass extraction complex, though downstream separation capacity remains under development.
Lanthanum is a soft, ductile rare earth element with atomic number 57, typically refined to 99.9% purity through solvent extraction or ion exchange methods; its oxide form serves as a critical feedstock for optical glass, petroleum cracking catalysts, and nickel-metal hydride battery electrodes. Lanthanum oxide dominates product type volumes due to its versatility across glass and catalyst applications, while lanthanum carbonate concentrates margin pools in pharmaceutical-grade rare earth compounds. Battery applications expand fastest among end-use segments, though catalyst demand retains structural stability through fluid catalytic cracking unit retrofits in petroleum refining.
China's MIIT governs rare earth production quotas and export licensing, directly constraining global oxide availability for non-Chinese processors. REACH registration requirements in Europe and EPA hazardous material handling rules in the United States impose compliance costs that favor integrated producers with established certification pathways. Stakeholders must monitor processing capacity buildouts outside China and assess offtake security against evolving national stockpile policies.
Market Dynamics
Battery cathode chemistry is redirecting lanthanum demand streams as automakers phase nickel-metal hydride systems into hybrid powertrains while solid-state research advances.
Growth Catalysts
- MIIT production quotas:China's rare earth output controls are forcing non-Chinese processors to accelerate separation capacity buildouts, tightening oxide availability and elevating spot market premiums.
- Fluid catalytic cracking retrofits:Petroleum refiners in the US Gulf Coast and Rotterdam-Antwerp corridor are replacing zeolite catalysts with lanthanum-doped formulations to process heavier crude slates.
- Baotou-Jiangxi processing corridor:Concentrated rare earth refining infrastructure in China's Inner Mongolia and Jiangxi provinces anchors global oxide supply, creating geographic pull for downstream offtake agreements.
Market Restraints
- Neodymium-praseodymium price volatility:Co-mined rare earth price swings distort lanthanum cost accounting for integrated producers, compressing margin visibility in tolling arrangements.
- Single-source ion-adsorption clay:Heavy rare earth co-extraction dependence on southern Chinese clay deposits creates supply concentration risk for separated oxide outputs.
- Lithium-ion cathode substitution:NMC and LFP battery chemistries are displacing nickel-lanthanum formulations in full-electric vehicle segments, narrowing addressable demand pools.
Strategic Opportunities
- Malaysian separation capacity:Non-Chinese oxide processing infrastructure offers Western automakers supply chain diversification pathways outside MIIT quota constraints.
- Optical glass refractive index tuning:Smartphone camera lens manufacturers are adopting lanthanum-doped substrates for chromatic aberration correction in periscope zoom modules.
- US Inflation Reduction Act:Critical mineral domestic content thresholds for electric vehicle tax credits are incentivizing North American rare earth magnet and battery supply chain investments.
Industry Challenges
- Solvent extraction engineering talent:Rare earth separation chemistry expertise concentrates in Chinese state-owned enterprises, constraining Western facility commissioning timelines.
- REACH registration dossiers:European lanthanum compound importers face multi-year toxicology data compilation requirements under ECHA substance evaluation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lanthanum Market |
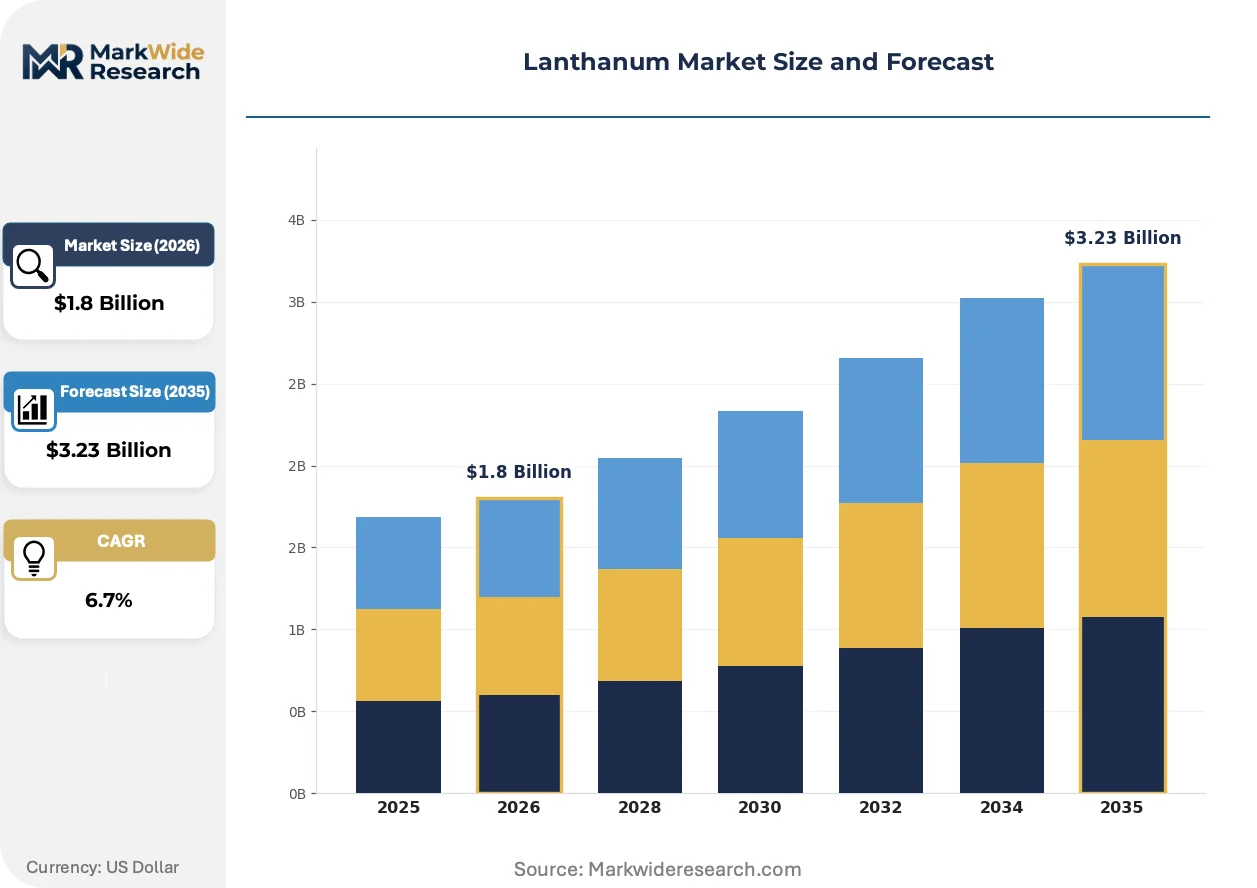
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lanthanum Oxide, Lanthanum Carbonate, Lanthanum Chloride, Lanthanum Hydroxide Application: Glass Manufacturing, Catalysts, Phosphors, Batteries End User: Electronics, Automotive, Aerospace, Energy Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Shenghe Resources Holding, Lynas Rare Earths, China Northern Rare Earth Group, Iluka Resources Limited, MP Materials, China Rare Earth Resources and Technology, China Rare Earth Holdings Limited, Arafura Rare Earths, Qiandong Rare Earth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lanthanum Market Strategic Shifts
Processing technology maturation outside China is redrawing competitive boundaries, while regulatory frameworks accelerate supply chain traceability requirements.
High-purity lanthanum metal production via molten salt electrolysis is converging with vacuum induction furnace capabilities at specialty alloy producers. Aerospace turbine blade manufacturers in the US and France are qualifying these inputs for single-crystal superalloy grain boundary strengthening. This metallurgical advance is compressing traditional oxide-to-metal conversion timelines and enabling just-in-time raw material positioning.
REACH authorization requirements for nickel compounds are compelling European battery recyclers to develop lanthanum recovery streams from spent nickel-metal hydride packs. ECHA substance restriction proposals are forcing cathode manufacturers to document supply chain provenance through mass balance certification. German and Polish processing facilities are investing in spectroscopic sorting equipment to meet these traceability mandates.
Automotive OEMs are consolidating rare earth procurement under direct offtake agreements with integrated miners, bypassing traditional trader intermediaries. Tier-1 battery suppliers in Japan and South Korea are responding by negotiating multi-year oxide supply contracts with fixed-volume escalators. This channel restructuring is most visible in Hyundai-Kia and Toyota supply chain disclosures, which now specify named rare earth separation facilities rather than commodity-grade specifications.
Lanthanum Market Segmentation

Lanthanum demand fragments across oxide purity grades, application chemistry requirements, and end-user certification standards. Each segmentation axis reveals distinct margin structures and supply chain access patterns for processors and consumers.
Product Type:
Purity thresholds and chemical stability define competitive positioning across refined lanthanum outputs.
- Lanthanum Oxide:A white crystalline powder refined to 99.9% purity through solvent extraction circuits, serving as the foundational feedstock for optical glass and petroleum cracking catalysts. Demand concentrates in China's Baotou-Jiangxi processing corridor, with Japanese optical glass manufacturers locking in multi-year offtake contracts to secure non-spot supply.
- Lanthanum Carbonate:A pharmaceutical-grade intermediate produced via precipitation from chloride solutions, commanding premium pricing in rare earth drug formulations and specialized ceramic applications. European REACH registration requirements constrain importer pools, favoring established processors with completed ECHA dossiers.
- Lanthanum Chloride:An aqueous solution feedstock for molten salt electrolysis and metal reduction processes, primarily consumed by aerospace alloy producers in France and the United States.
- Lanthanum Hydroxide:A hydrated precipitate used in wastewater treatment and specialty catalyst precursors, with demand anchored in South Korean environmental remediation projects.
Mature deployment sits with Lanthanum Oxide. Newer deployment is concentrated in Lanthanum Carbonate.
Application:
End-use chemistry specifications determine processing complexity and customer switching costs.
- Glass Manufacturing:Lanthanum-doped substrates enable high-refractive-index optical elements for smartphone periscope cameras and telescope lenses. Japanese and German precision optics manufacturers are expanding lanthanum oxide offtake to meet chromatic aberration correction specifications in next-generation mobile imaging systems.
- Catalysts:Fluid catalytic cracking units in US Gulf Coast and Rotterdam-Antwerp refineries deploy lanthanum-exchanged zeolites to process heavier crude slates with improved gasoline yields.
- Phosphors:Europium-activated lanthanum compounds generate red emission in LED and display backlighting systems, with Taiwanese and South Korean panel manufacturers driving specification evolution.
- Batteries:Nickel-lanthanum hydride cathodes power hybrid vehicle traction systems, though lithium-ion substitution pressures addressable demand in full-electric segments.
Established volume concentrates in Glass Manufacturing. Steepest expansion trajectory is visible in Batteries.
End User:
Customer certification requirements and volume scale differentiate procurement patterns across consuming industries.
- Electronics:Smartphone camera lens and display manufacturers in Japan, South Korea, and Taiwan specify 99.99% purity oxide with documented supply chain provenance.
- Automotive:Toyota and Hyundai-Kia battery supply chains now name specific rare earth separation facilities rather than commodity-grade specifications, consolidating procurement under direct offtake agreements.
- Aerospace:Single-crystal superalloy producers in the United States and France qualify lanthanum metal inputs for turbine blade grain boundary strengthening.
- Energy:Petroleum refiners in Texas, Louisiana, and the Netherlands retrofit FCC units with lanthanum-doped catalyst formulations.
Procurement consolidation is most advanced in Automotive. Specification stringency peaks in Aerospace.
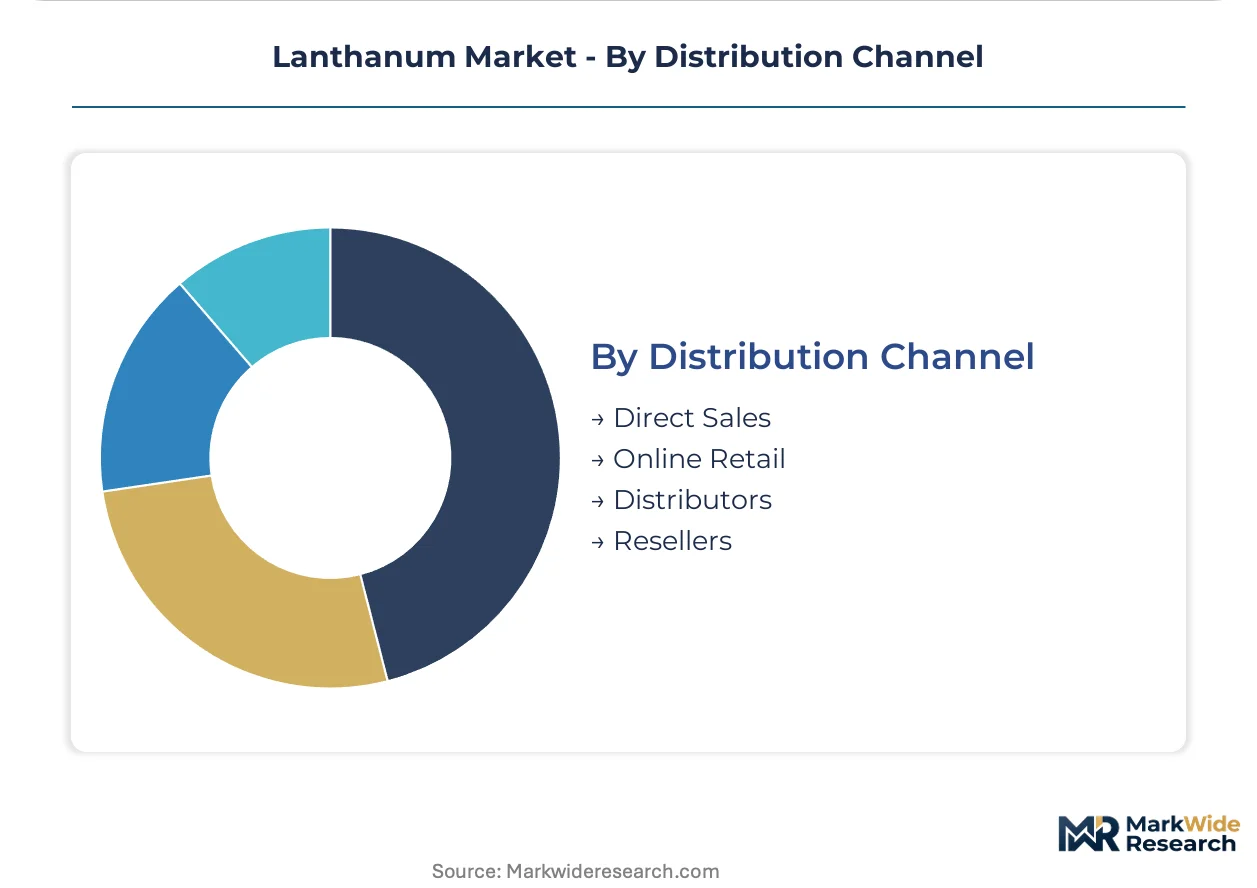
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and inventory risk allocation.
- Direct Sales:Integrated miners and major processors contract directly with automotive OEMs and aerospace tier-1 suppliers, bypassing trader intermediaries to secure volume commitments and technical collaboration.
- Distributors:Regional chemical distributors stock standardized oxide grades for mid-volume glass and catalyst consumers in Europe and North America.
- Online Retail:Laboratory and research-scale quantities move through specialized chemical supply platforms serving academic and R&D institutions.
- Resellers:Secondary market traders facilitate spot transactions for non-contracted volumes, particularly in Asian trading hubs.
Contract security concentrates in Direct Sales. Spot price exposure concentrates in Resellers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China mines and refines the majority of lanthanum oxide, yet consumption concentrates in Japan, South Korea, and the United States where battery cathode and optical glass manufacturers operate. This geographic disconnect forces non-Chinese processors to secure separation capacity outside MIIT quota constraints.
China
MIIT production quotas constrain rare earth oxide availability for export markets, tightening supply for Western automakers. The dual carbon goals accelerate consolidation of ion-adsorption clay mining in Jiangxi province. Baotou's integrated mining-to-oxide corridor anchors domestic refining infrastructure, with downstream consumers in Japan and South Korea negotiating multi-year offtake agreements to bypass spot market volatility.
United States
Petroleum refiners in Texas and Louisiana retrofit fluid catalytic cracking units with lanthanum-doped zeolite catalysts to process heavier domestic crude slates. EPA hazardous material handling rules impose compliance costs that favor integrated producers with established certification pathways. The Mountain Pass extraction complex in California supplies concentrate to emerging domestic separation projects, though downstream oxide capacity remains under development.
Japan
Precision optics manufacturers in Osaka and Tokyo expand lanthanum oxide offtake for smartphone periscope camera lenses requiring chromatic aberration correction. METI critical mineral stockpile policies incentivize direct procurement contracts with non-Chinese processors. Japanese automotive OEMs now name specific rare earth separation facilities in supply chain disclosures, consolidating procurement under direct agreements rather than commodity-grade specifications.
South Korea
Battery cathode producers in the Seoul Capital Area and Busan-Ulsan corridor consume nickel-lanthanum hydride formulations for hybrid vehicle traction systems. MFDS pharmaceutical-grade compound regulations constrain importer pools for lanthanum carbonate used in specialized drug formulations. Hyundai-Kia supply chain disclosures specify named separation facilities, reflecting channel restructuring away from trader intermediaries.
Germany
REACH registration requirements under ECHA substance evaluation protocols impose multi-year toxicology data compilation burdens on lanthanum compound importers. German optical glass manufacturers in Bavaria and the Ruhr region qualify 99.99% purity oxide with documented supply chain provenance for smartphone camera applications. Spectroscopic sorting investments at Polish and German processing facilities address emerging mass balance certification mandates for cathode supply chains.
Lanthanum Market Competitive Environment
Top-tier vendors anchor integrated mining-to-oxide operations, while mid-tier processors compete on geographic diversification and regulatory compliance capabilities. State-affiliated Chinese producers dominate upstream concentrate supply, constraining margin visibility for Western tolling arrangements. Three archetypes define competitive positioning: vertically integrated state enterprises, non-Chinese separation specialists, and emerging North American developers. Capacity expansion and strategic offtake partnerships constitute the dominant competitive moves, with automakers bypassing traditional trader channels to secure direct supply agreements.
Among integrated state-affiliated producers, China Northern Rare Earth Group and Shenghe Resources Holding exemplify the upstream-controlled archetype with captive access to Baotou-Jiangxi processing corridors. Lynas Rare Earths occupies a distinctive position as a non-Chinese oxide processor leveraging Malaysian separation capacity to supply Western automakers outside MIIT quota constraints. MP Materials represents the emerging North American developer archetype, with Mountain Pass extraction infrastructure feeding domestic downstream buildout projects.
| Leading Market Players |
|---|
| Shenghe Resources Holding |
| Lynas Rare Earths |
| China Northern Rare Earth Group |
| Iluka Resources Limited |
| MP Materials |
| China Rare Earth Resources and Technology |
| China Rare Earth Holdings Limited |
| Arafura Rare Earths |
| Qiandong Rare Earth Group |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement consolidation under direct offtake agreements anchors pricing power with integrated miners possessing MIIT quota access or Malaysian separation capacity, compressing trader margins and elevating contract premiums for qualified oxide supply.
Pricing Analysis
Margin tightening in pharmaceutical-grade lanthanum carbonate reflects REACH registration dossier completion costs and toxicology data compilation burdens that constrain importer pools. Three-tier pricing structure across battery-grade oxide, optical-grade oxide, and technical-grade carbonate separates specification stringency levels. Cost-down pressure on standard-grade oxide accelerates because fluid catalytic cracking catalyst buyers in US Gulf Coast refineries negotiate volume escalators with fixed-price collars. Battery cathode manufacturers exhibit least price sensitivity due to qualification timelines and supply security priorities, while wastewater treatment contractors demonstrate highest sensitivity to lanthanum hydroxide spot movements.
Supply Chain Analysis
REACH authorization and ECHA substance evaluation protocols gate European market access, favoring processors with completed registration dossiers and documented mass balance certification. Geographic supply concentrates in China's Inner Mongolia and Jiangxi provinces, with secondary processing nodes emerging in Malaysia and Australia. Raw material flows draw from Mountain Pass bastnaesite concentrate, Australian heavy mineral sands, and ion-adsorption clay deposits in southern China. Single-source vulnerability in solvent extraction engineering talent constrains Western facility commissioning timelines. Distribution runs through direct sales contracts with automotive OEMs and aerospace tier-1 suppliers, bypassing traditional chemical distributor channels for qualified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT production quotas and REACH registration requirements construct a cost-of-compliance moat that rewards integrated processors with established certification pathways and captive concentrate supply, while excluding speculative entrants lacking multi-year toxicology investment capacity.
For Market Incumbents: Deepen backward integration into Malaysian or Australian concentrate supply to secure oxide processing volumes outside MIIT quota constraints. Lock in multi-year offtake agreements with Japanese optical glass manufacturers and South Korean battery cathode producers before competitor capacity buildouts. Defend against lithium-ion cathode substitution by qualifying nickel-lanthanum hydride formulations for next-generation hybrid powertrain architectures.
For New Entrants and Emerging Players: Molten salt electrolysis capabilities for high-purity lanthanum metal production offer entry into aerospace superalloy qualification programs with lower incumbent density. Target US and French turbine blade manufacturers seeking grain boundary strengthening inputs with just-in-time delivery requirements. Pursue tolling arrangements with established separation facilities rather than greenfield solvent extraction investments.
For Investors and Strategic Acquirers: The window for entry favors non-Chinese oxide processors with Malaysian separation infrastructure and completed automotive OEM qualification programs. Long-term viability hinges on supply chain diversification mandates under US Inflation Reduction Act critical mineral thresholds and analogous European frameworks. Monitor MIIT quota allocation announcements as inflection indicators for spot market premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Malaysian Separation Capacity Expansion | Lynas Rare Earths sustains Western automaker supply security outside MIIT quota constraints. |
| Direct Offtake Agreement Consolidation | Toyota and Hyundai-Kia bypass trader intermediaries to name specific rare earth separation facilities. |
| REACH Registration Dossier Completion | European lanthanum carbonate importers secure market access under ECHA substance evaluation protocols. |
| Molten Salt Electrolysis Capability Buildout | US and French aerospace alloy producers qualify lanthanum metal for turbine blade grain boundary strengthening. |
| Spectroscopic Sorting Investment | German and Polish processing facilities meet emerging mass balance certification mandates for cathode supply chains. |
Study Parameters
Trade flow databases, SEC 10-K filings, and MIIT production quota disclosures formed the secondary backbone, cross-referenced against primary interviews with rare earth separation plant managers, automotive OEM procurement leads, and petroleum refinery catalyst specialists. Bottom-up and top-down triangulation validated oxide demand estimates across battery cathode, optical glass, and fluid catalytic cracking applications.
Bottom-up modeling aggregated end-use consumption patterns by purity grade and certification tier, while top-down analysis calibrated aggregate market trajectories against macroeconomic drivers. Segmentation dimensions spanned product type, application chemistry, end-user industry, and geographic processing corridor. CAGRs derived from historical volume trends and projected capacity buildouts, incorporating nickel-lanthanum hydride demand elasticity and lithium-ion substitution coefficients.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT quota policy shifts or breakthrough solid-state battery commercialization. Model outputs reflect assumptions regarding Malaysian separation capacity ramp schedules and REACH authorization timelines. A model refresh is warranted upon material change in US Inflation Reduction Act domestic content thresholds or ECHA substance restriction proposals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
US Ferrochrome Market
Metals
Bismuth Oxide Market
Metals
Copper Chromium Black Market
Metals
Palladium Market
Metals
High Purity Boron Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Aluminum Tubes Market
Metals
Cobalt Market
Metals
Titanium Market
Metals
Metal Casting Market
Metals
Rolled Steel Motor Market
Metals
Aluminum Flat Products Market
Metals
Silver-Platinum Paste Market
Metals
Galvanized Steel Market
Metals
Galvanizing Market
Metals
US and Mexico Stainless Steel Market