
 Metal Fiber Felt Market | 2026-2036
Metal Fiber Felt Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Fiber Felt Market Foresight
Stainless steel fiber is broadening its addressable base as sintered porous media displace ceramic and woven mesh alternatives in extreme-temperature filtration. Bekaert leverages integrated metal fiber drawing and sintering operations across Belgian and Chinese plants to anchor supply security for automotive catalyst substrates. Mott Corporation specializes in precision-engineered porous structures for semiconductor and chemical process industries, while Pall Corporation dominates aftermarket filtration service networks through extensive distributor control in North American refining corridors.
Metal fiber felt consists of randomly oriented metallic fibers, typically 2 to 40 microns in diameter, that are compressed and sinter-bonded to create tortuous-path porous structures with porosity ranging from 30% to 90%; this architecture delivers uniform permeability, thermal stability above 600°C, and mechanical resilience for high-differential-pressure service. Stainless steel variants command the largest value share given their corrosion resistance and weldability in petrochemical reactor vessels, while nickel-based grades in aerospace insulation represent the fastest-expanding margin pool due to superalloy pricing and FAA fireworthiness certification requirements. Custom shapes for turbine seal applications generate premium pricing over standard sheet and roll formats due to CNC contouring and non-destructive testing overhead.
EPA National Emission Standards for Hazardous Air Pollutants and REACH substance restrictions are forcing fabricators to certify fiber composition and leachate profiles for stack filtration installations. China's GB standards for industrial emissions and the EU F-Gas Regulation are tightening product performance benchmarks for thermal and acoustic insulation in power generation equipment. Stakeholders must monitor evolving alloy sourcing rules under conflict-mineral disclosure frameworks and decide whether captive fiber drawing or outsourced sintering better protects margin structures as qualification timelines extend.
Market Dynamics
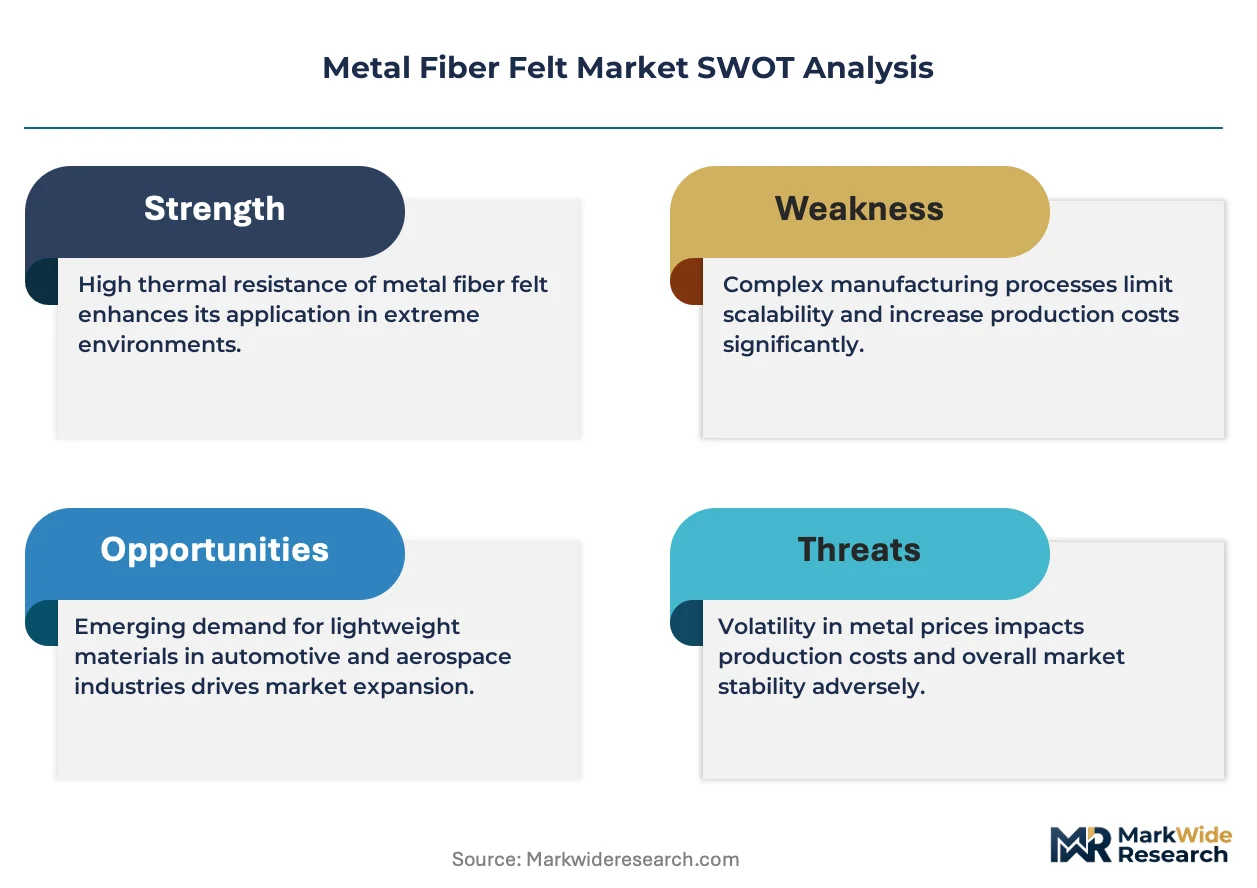
Sinter-bonded metal fiber architectures are displacing ceramic and woven mesh alternatives as EPA and REACH emissions standards harden qualification requirements for high-temperature filtration media across petrochemical and power generation installations.
Growth Catalysts
- EPA National Emission Standards for Hazardous Air Pollutants:Fabricators must certify fiber composition and leachate profiles for stack filtration, accelerating material substitution cycles in US refining corridors.
- Aerospace turbine insulation:FAA fireworthiness certification requirements for nickel-based superalloy grades are expanding addressable demand in engine system thermal management.
- China's chemical processing corridors:GB standards for industrial emissions are tightening product performance benchmarks, concentrating procurement in coastal petrochemical clusters.
Market Restraints
- Superalloy input cost volatility:Nickel and cobalt price swings compress margin pools for nickel-based fiber grades used in aerospace applications.
- Belgian-Chinese supply concentration:Integrated fiber drawing and sintering operations cluster in limited geographies, exposing buyers to single-source qualification risk.
- Ceramic fiber substitution in sub-600°C applications:Lower-cost alumina-silicate media retain share in temperature regimes where metal fiber performance advantages diminish.
Strategic Opportunities
- Semiconductor process gas filtration:Precision-engineered porous structures for wafer fabrication equipment represent underpenetrated demand with premium pricing tolerance.
- EU F-Gas Regulation thermal insulation mandates:Power generation equipment refurbishment cycles are creating specification windows for metal fiber acoustic and thermal barriers.
- Additive manufacturing convergence:Near-net-shape sintering techniques are enabling custom turbine seal geometries without CNC contouring overhead.
Industry Challenges
- Extended qualification timelines:Conflict-mineral disclosure frameworks and alloy sourcing rules are stretching certification cycles to 18-24 months for aerospace approvals.
- Captive versus outsourced sintering decisions:Capital intensity for in-house fiber drawing equipment forces mid-scale fabricators into margin-eroding tolling arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Fiber Felt Market |
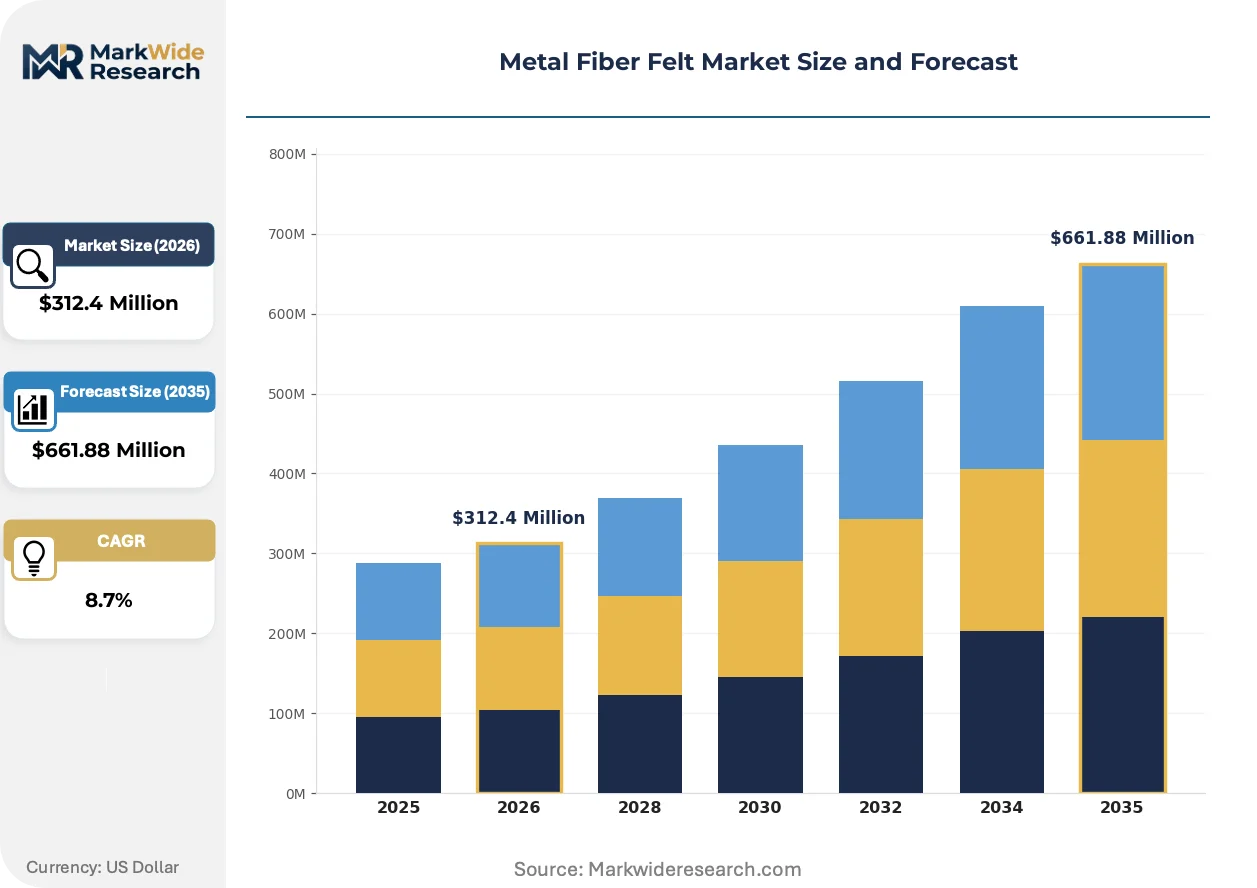
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Copper, Aluminum, Nickel Application: Filtration, Insulation, Acoustic, Reinforcement End User: Automotive, Aerospace, Oil & Gas, Power Generation Form: Sheets, Rolls, Pads, Custom Shapes |
| Companies Covered | Bekaert, Hengstler GmbH, Micronics Japan Co., Ltd., Mott Corporation, GKN Sinter Metals, Kurtz GmbH, Nippon Seisen Co., Ltd., Fiberguide Industries, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Fiber Felt Market Shifts & Advancements
Multi-layer sintered architectures and hybrid metal-ceramic composites are reshaping competitive positioning as end-users demand filtration media that survive both thermal shock and corrosive process streams.
Gradient-density sintered structures is converging with semiconductor process gas filtration requirements. Chip fabricators in Japan and Germany are specifying sub-micron retention ratings for chemical vapor deposition exhaust systems. This convergence is compressing the addressable market for conventional woven mesh in critical process applications.
REACH substance restrictions are forcing reformulation of binding agents and lubricants used in fiber drawing operations. ECHA scrutiny of nickel compound classifications is elevating documentation burdens for European fabricators. Aerospace suppliers are responding by accelerating qualification of cobalt-free superalloy alternatives in turbine seal applications.
Buyer consolidation among North American refining operators is compressing supplier negotiation cycles and unbundling aftermarket service contracts from initial equipment procurement. Integrated petrochemical majors are establishing direct technical relationships with sintering specialists, bypassing traditional distributor networks in the US Gulf Coast cluster.
Metal Fiber Felt Market Segmentation
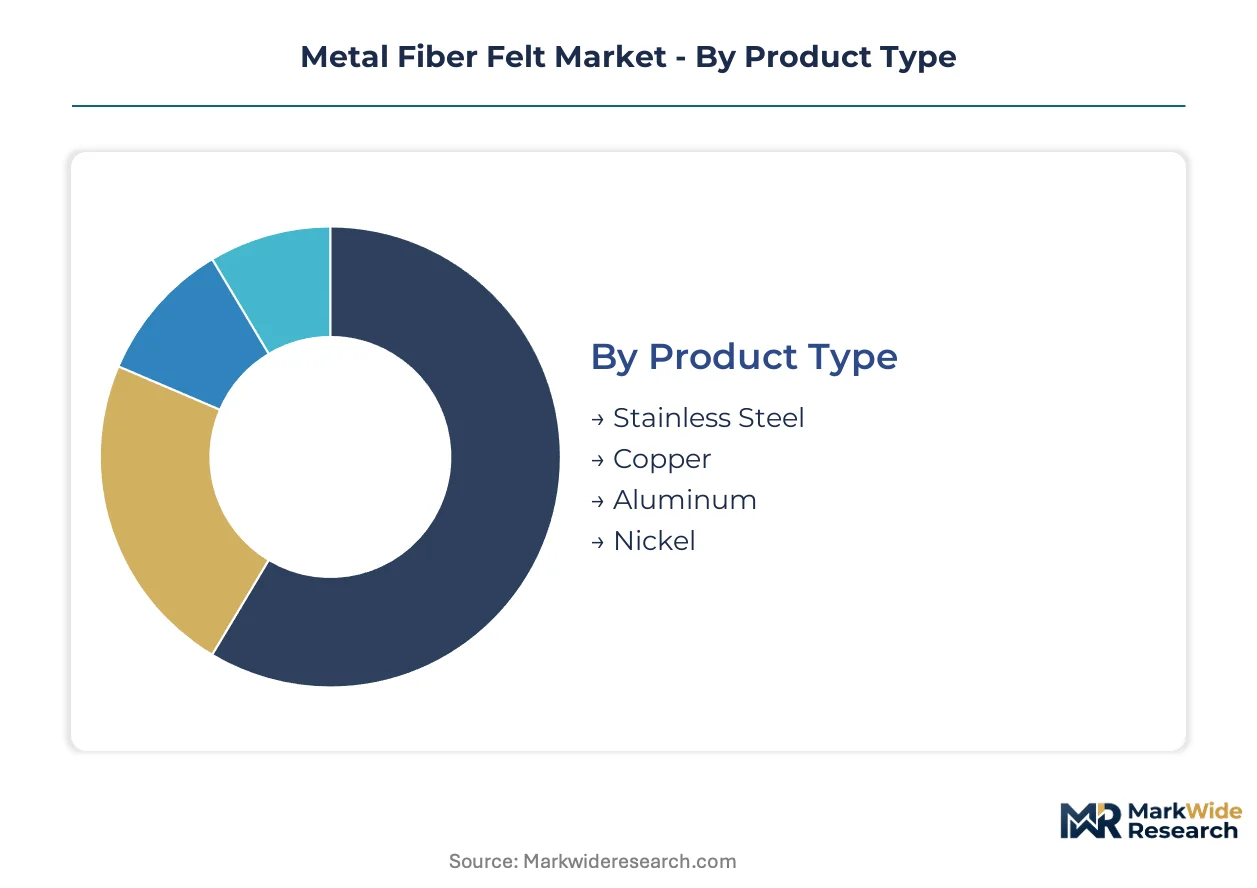
Metal fiber felt procurement hinges on material-specific certifications that gate entry into aerospace turbine seals, semiconductor process gas systems, and EPA-regulated stack filtration. Segment boundaries sharpen as REACH substance restrictions and FAA fireworthiness standards force buyers to match alloy grades precisely to end-use thermal and corrosion requirements.
Product Type:
Certification burdens vary sharply by alloy family, with nickel-based grades demanding FAA fireworthiness documentation and stainless steel requiring EPA leachate profiling for stack filtration installations.
- Stainless Steel:Austenitic and ferritic grades dominate petrochemical reactor vessel applications where weldability and corrosion resistance above 600°C justify premium over ceramic alternatives. Demand concentrates in the US Gulf Coast refining cluster as EPA National Emission Standards for Hazardous Air Pollutants harden particulate control requirements.
- Nickel:Superalloy fiber grades command the steepest pricing tiers due to cobalt content and aerospace qualification overhead. Procurement is accelerating among German and Japanese engine manufacturers seeking FAA-certified thermal insulation for turbine seal applications.
- Copper:High thermal conductivity variants serve specialized heat exchanger and electromagnetic shielding niches where electrical properties outweigh oxidation limitations.
- Aluminum:Lightweight fiber grades occupy cost-sensitive acoustic and thermal barrier applications below 400°C where density reduction drives specification.
Stainless steel sits at the top of the volume ranking, with nickel climbing the fastest as superalloy pricing and aerospace certification requirements expand addressable margin pools.
Application:
Cost tiers separate commodity filtration media from precision-engineered insulation and acoustic systems, with semiconductor process gas applications commanding the widest premiums.
- Filtration:Sinter-bonded porous structures with 30-90% porosity deliver tortuous-path particle retention for chemical vapor deposition exhaust and petrochemical stack emissions. Japanese chip fabricators are specifying sub-micron retention ratings that displace conventional woven mesh.
- Insulation:Multi-layer gradient-density architectures survive thermal shock in power generation equipment subject to EU F-Gas Regulation refurbishment mandates. Nickel-based grades are expanding share fastest in aerospace turbine thermal management.
- Acoustic:Random fiber orientation absorbs broadband noise in industrial enclosures and transportation systems where weight and temperature resistance constrain material selection.
- Reinforcement:Metal fiber felts strengthen polymer and ceramic matrix composites for friction and wear applications in automotive brake and clutch systems.
Filtration generates the largest revenue base, while insulation gains share fastest as power generation refurbishment cycles and aerospace procurement accelerate.
End User:
Customer type determines qualification timeline intensity, with aerospace approvals stretching 18-24 months under conflict-mineral disclosure frameworks while automotive catalyst substrates move faster.
- Aerospace:Engine system thermal management and turbine seal applications require FAA fireworthiness certification for nickel-based superalloy grades. German and Japanese manufacturers are expanding procurement of high-temperature filtration media as engine efficiency standards tighten.
- Automotive:Catalytic converter substrates and exhaust system filtration drive volume demand for stainless steel fiber felt with integrated drawing and sintering supply security.
- Oil & Gas:Petrochemical reactor vessels and stack filtration installations in the US Gulf Coast and China's coastal corridors specify corrosion-resistant grades under tightening emissions standards.
- Power Generation:Thermal and acoustic insulation for turbine and boiler systems faces EU F-Gas Regulation performance benchmarks driving refurbishment specification windows.
Automotive anchors volume demand through catalyst substrate scale, with aerospace expanding most quickly on superalloy pricing and certification premiums.
Form:
Supply concentration in Belgian and Chinese integrated fiber drawing and sintering operations shapes availability of standard formats versus custom geometries requiring CNC contouring overhead.
- Sheets:Flat sintered panels serve filtration and insulation applications with standardized dimensions for reactor vessel and stack installation. Chinese chemical processing corridors concentrate procurement for GB standard-compliant emissions control systems.
- Rolls:Continuous format enables high-volume automotive catalyst substrate production and acoustic barrier fabrication with minimal cutting waste.
- Pads:Pre-cut dimensions accelerate field installation in power generation and industrial maintenance applications where labor cost dominates material cost.
- Custom Shapes:CNC-contoured and non-destructive-tested geometries for turbine seals and semiconductor process gas components generate premium pricing multiples over standard formats.
Rolls lead volume throughput for automotive scale, with custom shapes gaining margin contribution fastest on aerospace and semiconductor precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical cluster drives the largest procurement volumes for high-temperature filtration media as EPA emissions standards harden stack installation requirements. German aerospace manufacturers and Japanese semiconductor fabricators anchor premium-grade demand for superalloy fiber grades.
United States
Petrochemical reactor vessels along the Texas and Louisiana coast specify corrosion-resistant stainless steel grades under EPA National Emission Standards for Hazardous Air Pollutants. Refining operators are unbundling aftermarket service contracts from initial equipment procurement. Direct technical relationships between integrated majors and sintering specialists are bypassing traditional distributor networks in Houston and Port Arthur.
Germany
Engine manufacturers in Bavaria and Baden-Württemberg are expanding procurement of nickel-based superalloy fiber for turbine seal thermal management. EU F-Gas Regulation refurbishment mandates for power generation equipment are tightening thermal insulation performance benchmarks. Stuttgart and Munich aerospace clusters face ECHA scrutiny of nickel compound classifications that elevate documentation burdens for fabricators.
China
GB standards for industrial emissions are concentrating procurement in coastal chemical processing corridors from Shanghai to Guangdong. Belgian-Chinese integrated fiber drawing operations anchor supply security for automotive catalyst substrates. Ningbo and Qingdao petrochemical clusters are qualifying sinter-bonded porous structures for stack filtration under tightening MEE enforcement.
Japan
Chip fabricators in Tokyo and Osaka are specifying sub-micron retention ratings for chemical vapor deposition exhaust systems. METI efficiency standards are accelerating material substitution cycles in semiconductor process gas filtration. Kyushu-based engine manufacturers are qualifying FAA-certified nickel fiber grades for turbine insulation applications.
Belgium
Integrated metal fiber drawing and sintering operations in Flanders supply automotive and aerospace tiers across European corridors. REACH substance restrictions are forcing reformulation of binding agents used in fiber drawing operations. Antwerp-based fabricators face qualification risk concentration as buyers seek dual-source arrangements for critical alloy grades.
Metal Fiber Felt Market Competitive Landscape
Global majors compete with regional champions across integrated versus outsourced sintering capabilities. The vendor base separates into three tiers: Belgian and Japanese integrated specialists with captive fiber drawing, North American precision-engineering houses serving semiconductor and aerospace niches, and Chinese scale players feeding automotive catalyst volume. Market structure rewards backward integration into metal fiber production and punishes toll-dependent mid-scale fabricators. Dominant competitive moves include capacity expansion in Chinese chemical processing corridors and technology licensing for near-net-shape sintering techniques.
Among European integrated specialists, Bekaert exemplifies the captive supply archetype through Belgian-Chinese fiber drawing operations. Mott Corporation and Pall Corporation anchor the North American precision-engineering tier, with the former representing specialty porous structure fabrication and the latter dominating aftermarket filtration service networks. These three names illustrate how geographic concentration and vertical scope separate margin pools in this market.
| Leading Market Players |
|---|
| Bekaert |
| Hengstler GmbH |
| Micronics Japan Co., Ltd. |
| Mott Corporation |
| GKN Sinter Metals |
| Kurtz GmbH |
| Nippon Seisen Co., Ltd. |
| Fiberguide Industries |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
Captive fiber drawing and sintering operations in Belgian and Chinese plants anchor both supply security and pricing power for integrated specialists serving automotive catalyst and aerospace insulation tiers. This backward integration shields margin structures from nickel and cobalt volatility while exposing toll-dependent mid-scale fabricators to cost pass-through vulnerability.
Pricing Analysis
Input-cost pass-through from nickel and cobalt commodity swings compresses margin pools for non-integrated fabricators dependent on outsourced superalloy fiber. Three-tier pricing structure across FAA-certified aerospace grades, EPA-compliant industrial filtration, and automotive catalyst substrates reflects certification overhead and volume scale differentiation. Pricing pressure stems from ceramic fiber substitution in sub-600°C applications where metal fiber performance advantages diminish. Automotive catalyst buyers exhibit highest price sensitivity due to standardized specifications and high-volume procurement, while semiconductor process gas filtration tolerates premium positioning for sub-micron retention ratings.
Supply Chain Analysis
Workforce availability for precision metalworking in Flanders and Zhejiang Province anchors integrated fiber drawing and sintering capacity. Supply concentrates in Belgium, China, and Japan for captive superalloy fiber production, with raw material dependencies on nickel cathodes, cobalt metal, and specialty steel scrap. Single-source qualification risk runs through Belgian-Chinese integrated operations as buyers seek dual-source arrangements for critical aerospace grades. Distribution runs through direct technical relationships between petrochemical majors and sintering specialists, bypassing traditional distributor networks in US Gulf Coast refining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Metal Fiber Felt Market functions as a regulatory compounder where EPA National Emission Standards for Hazardous Air Pollutants and FAA fireworthiness certification requirements continuously reset performance baselines and extend qualification timelines.
For Market Incumbents: Anticipate ceramic fiber substitution pressure in sub-600°C temperature regimes by accelerating qualification of gradient-density sintered architectures for semiconductor process gas applications. Defend margin position through captive fiber drawing investments in Chinese chemical processing corridors rather than margin-eroding tolling arrangements. Prioritize ECHA-compliant reformulation of binding agents ahead of REACH substance restriction enforcement. For New Entrants and Emerging Players: Enter via semiconductor process gas filtration white space where Japanese chip fabricators specify sub-micron retention ratings with limited incumbent penetration. Target EU F-Gas Regulation-driven power generation refurbishment cycles for thermal and acoustic insulation specifications. Pursue technology licensing partnerships for near-net-shape sintering techniques to bypass CNC contouring overhead in custom turbine seal geometries. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale toll-dependent fabricators because extended qualification timelines under conflict-mineral disclosure frameworks prevent rapid organic scaling. Long-term viability hinges on backward integration into metal fiber production or proprietary sintering IP. Watch for inflection in aerospace procurement velocity from German and Japanese engine manufacturers as signal for superalloy fiber grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Drawing | Captive metal fiber production shields margins from nickel-cobalt volatility for Belgian-Chinese integrated operators. |
| Capacity Expansion in Coastal China | Ningbo and Qingdao petrochemical clusters qualify sinter-bonded structures under tightening MEE emissions enforcement. |
| Technology Licensing for Near-Net-Shape Sintering | Additive manufacturing convergence enables custom turbine seals without CNC contouring overhead for aerospace tiers. |
| Long-term Supply Agreement with Refining Majors | Direct technical relationships bypass distributor networks in US Gulf Coast petrochemical corridors. |
| Green Manufacturing Transition | REACH-compliant reformulation of binding agents reduces ECHA documentation burdens for European fabricators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at sintering operations, procurement leads at petrochemical majors, aerospace Tier 1 supplier engineers, and aftermarket filtration service heads with secondary validation from SEC 10-K filings, customs and trade data, EPA enforcement databases, and ECHA substance restriction notifications. Bottom-up alloy-grade demand modeling and top-down end-use industry consumption estimates were triangulated against capacity announcements from integrated fiber drawing operations.
Segment-weighting across stainless steel, nickel-based superalloy, copper, and aluminum fiber grades incorporated application-specific certification timelines, with filtration, insulation, acoustic, and reinforcement end-uses further disaggregated by aerospace, automotive, oil and gas, and power generation customer types. CAGRs were derived from regression analysis of historical procurement patterns and forward projection of regulatory milestone impacts across the analysis window, with semiconductor process gas filtration and EU F-Gas Regulation refurbishment cycles serving as industry-specific demand inflection inputs.
The model holds under stable nickel-cobalt price regimes and sustained EPA-REACH regulatory enforcement; deviation in superalloy input cost volatility or aerospace qualification timeline extension would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Fiberglass Cloth Market
Fibers
Carbon Fiber Filament Market
Fibers
Global Fiber Reinforced Composites Market
Fibers
Global Fiberglass Mold Market
Fibers
Global Nylon Monofilament Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Global Bicomponent Fiber Market
Fibers
Global Concrete Fiber Market
Fibers
Precision Fiber Molding Market
Fibers
Fiber Metal Laminate (FML) Market
Fibers
Bioglass Fiber Market
Fibers
Carbon Fiber Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
High Performance Fibers for Defense Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
Basalt Continuous Fiber (BCF) Market