
 Bioglass Fiber Market | 2026-2036
Bioglass Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Bioglass Fiber Market Analysis
Orthopedic implant demand is shifting toward synthetic bone graft substitutes, pulling bioglass fiber volumes upward in spinal fusion and trauma applications. SCHOTT AG leverages its melt-draw expertise to dominate high-purity bioactive glass fiber supply for European medical device OEMs. Mo-Sci Corporation specializes in custom compositional formulations, while Stryker Corporation anchors hospital procurement channels through its established orthopedic portfolio. NovaBone Products competes in the dental regeneration segment with proprietary fiber architectures.
Bioglass fiber comprises silica-based glass compositions with calcium and phosphate additions that elicit controlled surface reactivity when implanted in physiological environments, typically forming hydroxycarbonate apatite within hours of tissue contact. The material serves primarily as a resorbable scaffold that bonds chemically to living bone while stimulating osteogenic cell differentiation. Bioactive glass fiber leads product type demand due to its direct therapeutic functionality, whereas orthopedic implants command the largest application margin pool as hospitals prioritize proven graft outcomes. Wound healing represents the fastest-growing application as chronic diabetic ulcer protocols incorporate antimicrobial glass fiber dressings.
FDA 510(k) clearance requirements and the EU MDR's strengthened clinical evidence mandates are elevating barrier-to-entry costs for new bioglass fiber suppliers. ISO 10993 biocompatibility testing series and ASTM F1534 standards govern material characterization protocols that manufacturers must satisfy before commercial distribution. Stakeholders should monitor how FDA breakthrough device designations for composite bone grafts reshape competitive timelines and reimbursement pathways.
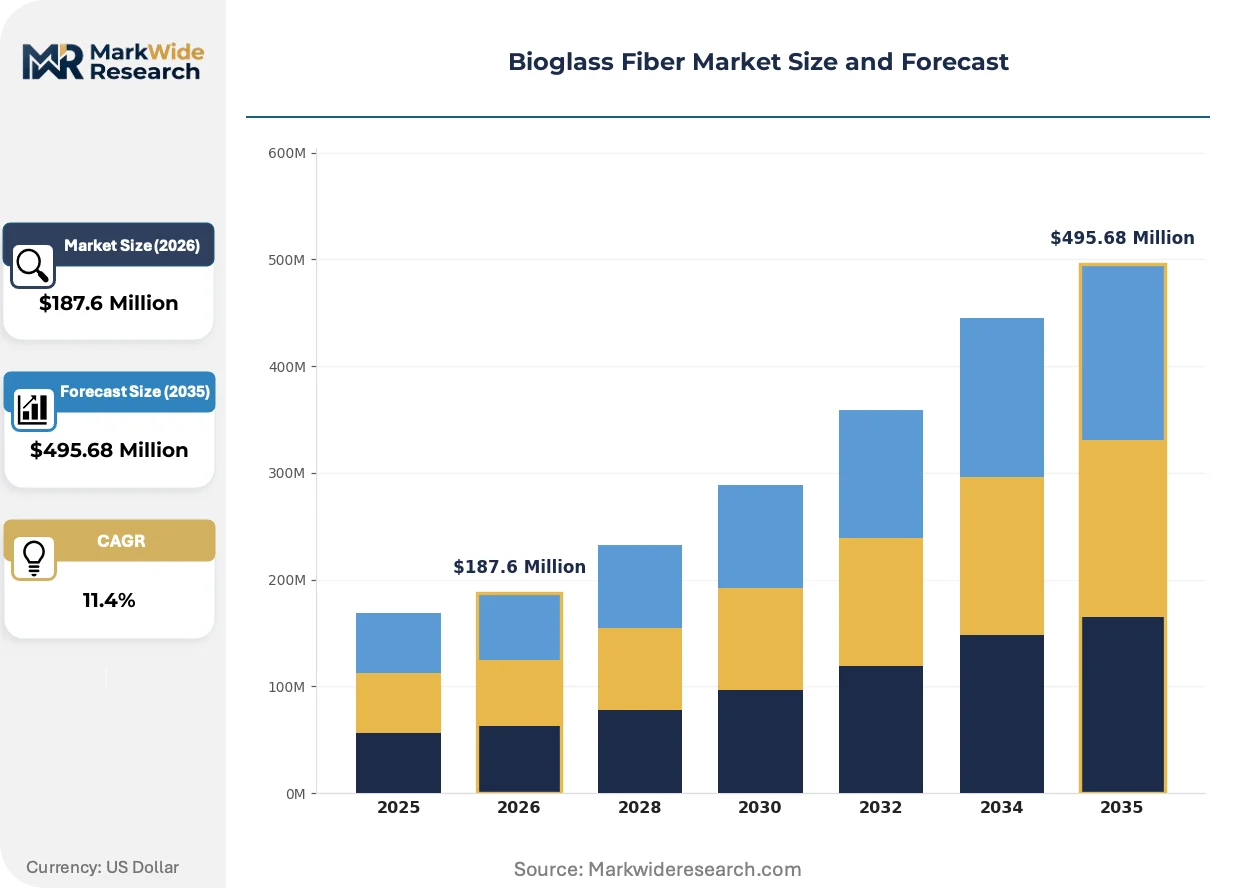
Market Dynamics
Orthopedic implant manufacturers are accelerating substitution of synthetic hydroxyapatite with bioactive glass compositions, compressing qualification timelines and reshaping supplier qualification hierarchies across spinal fusion and trauma fixation supply chains.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Bone void filler clearances for bioactive glass fiber are accelerating hospital procurement cycles, pulling volumes into spinal fusion protocols faster than ceramic alternatives.
- EU MDR Clinical Evidence Mandates:Strengthened biocompatibility testing requirements under the European Medical Device Regulation are favoring established glass fiber suppliers with ISO 10993 documentation libraries.
- South Korean MFDS Cluster Development:Seoul-based medical device OEMs are localizing bioactive glass fiber sourcing to reduce import dependency and shorten sterilization logistics loops.
Market Restraints
- High-Purity Silica Supply Concentration:Specialized silica feedstock for medical-grade bioglass fiber concentrates among German and US chemical suppliers, exposing converters to input cost volatility.
- ASTM F1534 Characterization Burden:Extended material testing protocols for surface reactivity and degradation kinetics stretch development budgets for new market entrants.
- Synthetic Hydroxyapatite Substitution Threat:Lower-cost ceramic bone graft substitutes retain preference in price-sensitive hospital systems, capping bioglass fiber penetration in emerging markets.
Strategic Opportunities
- Chronic Diabetic Wound Protocols:Antimicrobial glass fiber dressings are penetrating diabetic ulcer care pathways, opening volume channels outside traditional orthopedic implants.
- Japan PMDA Regenerative Medicine Framework:Accelerated approval pathways for combination products are enabling faster market entry for glass fiber-collagen composite scaffolds.
- 3D Printing Convergence:Integration of bioactive glass fiber into additive manufacturing workflows for patient-specific bone grafts is creating new service revenue models.
Industry Challenges
- ISO 10993-18 Chemical Characterization Expertise Gap:Shortage of toxicologists skilled in extractables and leachables analysis for glass fiber compositions is delaying regulatory submissions.
- Cold Chain Sterilization Infrastructure:Gamma and ethylene oxide sterilization capacity for porous fiber architectures requires specialized capex that mid-scale converters struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioglass Fiber Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $495.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminosilicate Fiber, Bioactive Glass Fiber, E-Glass Fiber, S-Glass Fiber End User: Medical Applications, Dentistry, Bone Regeneration, Tissue Engineering Application: Wound Healing, Drug Delivery, Orthopedic Implants, Biocompatible Coatings Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | ETS Wound Care LLC, SCHOTT AG, Mo-Sci Corporation, Zimmer Biomet Holdings, Inc., Stryker Corporation, Corbion Biotech, Inc., Vetra Biomaterials, NovaBone Products, LLC, Prosidyan, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioglass Fiber Market Emerging Trajectories
Bioactive glass fiber manufacturing is pivoting toward compositional precision and downstream integration, with melt-draw process control and antimicrobial ion doping emerging as the primary vectors of competitive differentiation.
Strontium-doped bioactive glass fiber is consolidating its position in osteoporotic bone repair applications. Spinal fusion surgeons are adopting strontium-substituted compositions for patients with compromised bone mineral density. This doping strategy is consolidating supplier margins by commanding premium pricing over standard 45S5 compositions while reducing revision surgery rates.
The EU MDR's strengthened clinical evidence requirements are compressing the supplier base for European medical device OEMs. Manufacturers must now submit post-market surveillance data and biological safety documentation that exceeds previous Medical Device Directive thresholds. German orthopedic implant producers are responding by consolidating supplier relationships toward vertically integrated glass fiber specialists with captive testing laboratories.
Hospital procurement departments are unbundling bone graft purchasing from implant system contracts. Previously captive sourcing through Stryker and DePuy Synthes is giving way to independent evaluation of synthetic graft substitutes based on published fusion rates and total procedure cost. This unbundling is most visible in US academic medical centers, where value analysis committees now separately review bioglass fiber bone void fillers.
Bioglass Fiber Market Segmentation
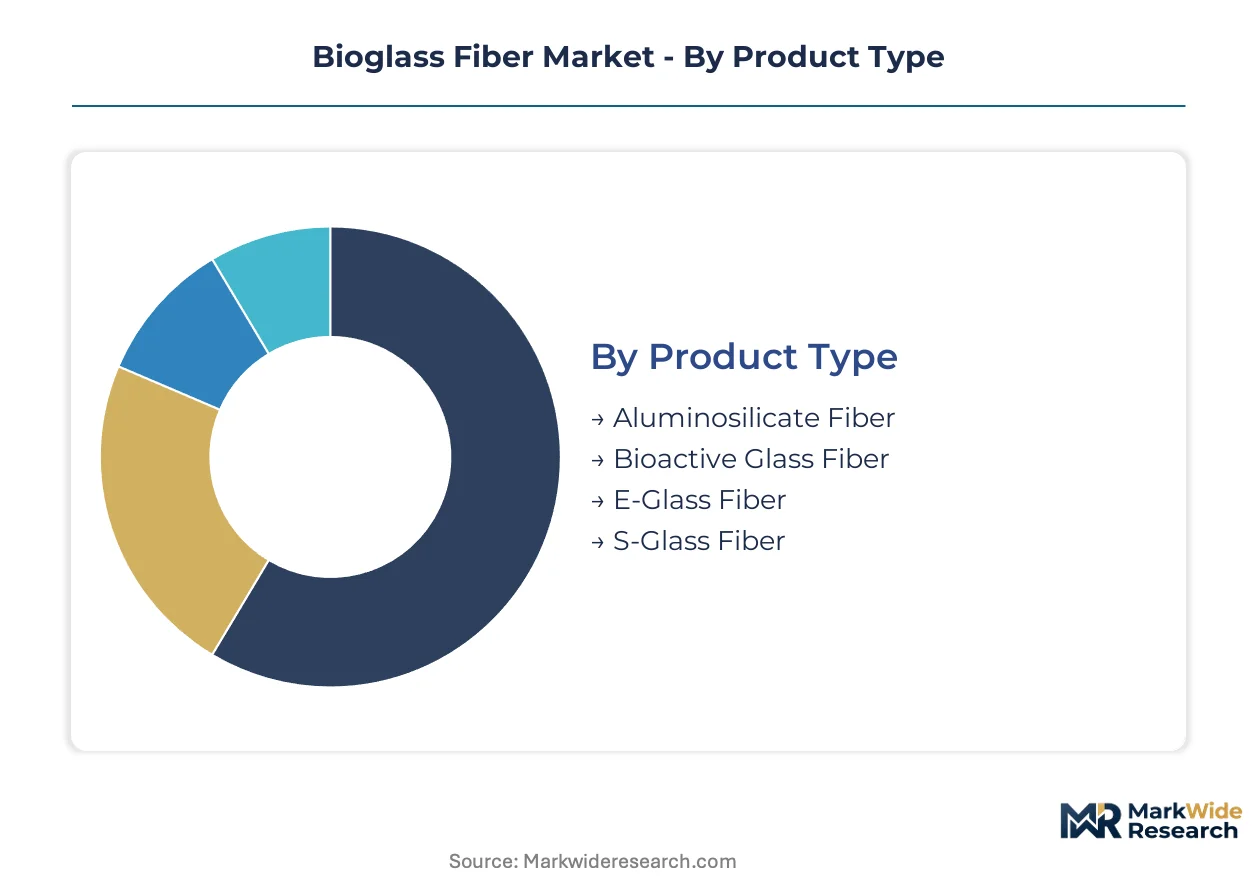
Bioglass fiber segmentation reveals how supply-side specialization fragments across compositional chemistries, clinical applications, and procurement channels. Each dimension carries distinct margin profiles and regulatory qualification burdens that reshape supplier competitive positioning.
Product Type:
High-purity silica feedstock concentrates among German and US chemical suppliers, exposing converters to input cost volatility and forcing compositional differentiation strategies.
- Bioactive Glass Fiber:Silica-based compositions with calcium and phosphate additions elicit controlled surface reactivity, forming hydroxycarbonate apatite within hours of tissue contact. Orthopedic implant manufacturers in Germany and the United States are pulling volumes into spinal fusion protocols faster than ceramic alternatives, compressing qualification timelines.
- S-Glass Fiber:High-strength magnesium aluminosilicate composition delivers superior tensile properties for load-bearing composite scaffolds. South Korean MFDS cluster development is localizing sourcing to reduce import dependency and shorten sterilization logistics loops.
- Aluminosilicate Fiber:Alumina-silica blends trade bioactivity for thermal stability and mechanical durability in non-resorbable reinforcement applications.
- E-Glass Fiber:Standard borosilicate formulation serves cost-sensitive industrial applications outside therapeutic segments.
Today's leader: Bioactive Glass Fiber. Tomorrow's challenger: S-Glass Fiber.
End User:
Customer procurement maturity varies sharply across clinical settings, with hospital value analysis committees demanding outcome documentation that dental practices rarely require.
- Orthopedic Implants:Spinal fusion and trauma fixation protocols dominate volume consumption as hospitals unbundle bone graft purchasing from implant system contracts.
- Wound Healing:Chronic diabetic ulcer care pathways are penetrating antimicrobial glass fiber dressings, opening volume channels outside traditional orthopedic applications and climbing the fastest among end user categories.
- Medical Applications:Broad hospital procurement spans general surgery and reconstructive procedures with heterogeneous specification requirements.
- Dentistry:Periodontal regeneration and socket preservation drive specialized fiber architecture demand with premium pricing tolerance.
- Bone Regeneration:Maxillofacial and cranial defect repair protocols require patient-specific scaffold geometries.
- Tissue Engineering:Research-stage applications in organ scaffold development remain pre-commercial with academic funding dependency.
Procurement gravity centers on orthopedic volume; margin expansion concentrates in wound care specialization.
Application:
Functional performance requirements stratify across therapeutic modalities, with surface reactivity specifications and degradation kinetics dictating supplier qualification hierarchies.
- Orthopedic Implants:Bone void fillers and spinal fusion scaffolds command the largest margin pool as FDA 510(k) clearances accelerate hospital procurement cycles.
- Wound Healing:Antimicrobial ion-doped dressings are consolidating supplier margins by commanding premium pricing over standard compositions.
- Drug Delivery:Controlled-release fiber matrices for localized therapeutic administration remain developmental with limited commercial scale.
- Biocompatible Coatings:Surface modification layers for metallic implant substrates require thin-film deposition expertise distinct from bulk fiber production.
Clinical evidence density favors orthopedic applications; regulatory pathway innovation favors wound care expansion.
Distribution Channel:
Channel economics reflect sterilization infrastructure requirements and lot traceability mandates that privilege direct relationships over arm's-length transactions.
- Direct Sales:Hospital system contracts and OEM supply agreements dominate high-volume orthopedic procurement with captive logistics integration.
- Distributors:Regional medical device specialists bridge geographic coverage gaps for mid-scale converters lacking field sales organizations.
- Specialty Stores:Dental and veterinary niche suppliers serve fragmented professional practices with higher per-unit service costs.
- Online Retail:Research-grade materials and small-lot consumables reach academic laboratories through digital procurement platforms.
Direct relationships anchor orthopedic volume; distributor networks capture geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic implant producers anchor regional demand concentration for medical-grade bioglass fiber, with specialized glass fiber clusters in Mainz and Jena supplying melt-draw expertise to European device OEMs.
Germany
Spinal fusion manufacturers in Baden-Württemberg and Bavaria are accelerating qualification of strontium-doped bioactive glass compositions for osteoporotic patient protocols. The EU MDR's strengthened clinical evidence mandates favor established suppliers with ISO 10993 documentation libraries. The Mainz-Rheinhessen chemical cluster hosts melt-draw specialists supplying high-purity fiber to DePuy Synthes and Zimmer Biomet production facilities.
United States
Hospital value analysis committees at academic medical centers in Boston and the Research Triangle are unbundling bone graft purchasing from implant system contracts. FDA 510(k) pathway streamlining for bone void fillers accelerates procurement cycles for spinal fusion protocols. The St. Louis bioscience corridor concentrates custom compositional formulation specialists serving mid-scale orthopedic OEMs.
South Korea
Seoul-based medical device OEMs in the Songdo biomedical cluster are localizing bioactive glass fiber sourcing to reduce import dependency from German suppliers. The MFDS cluster development program funds sterilization infrastructure for porous fiber architectures. Busan-Ulsan chemical complexes are adding medical-grade silica purification capacity to serve domestic implant manufacturers.
Japan
PMDA's regenerative medicine framework is accelerating approval pathways for glass fiber-collagen composite scaffolds in Osaka and Tokyo hospital networks. METI funding targets 3D printing convergence for patient-specific bone graft applications. The Kobe biomedical innovation cluster hosts research-stage tissue engineering programs exploring antimicrobial ion-doped dressings.
Switzerland
Swissmedic's streamlined certification procedures for combination products attract orthopedic device headquarters to the Basel-Zurich corridor. Precision glass engineering heritage in the Jura Arc supports specialty fiber production for dental regeneration applications. Geneva-based research hospitals are piloting chronic diabetic wound protocols using antimicrobial glass fiber dressings.
Bioglass Fiber Market Vendor Landscape
Strategic partnerships dominate the current landscape as specialized fiber producers align with orthopedic OEMs to compress regulatory qualification timelines. The vendor base stratifies across three tiers: multinational glass engineering conglomerates with captive medical divisions, mid-scale custom formulation specialists, and research-stage biomaterial startups. Two archetypes command pricing power: vertically integrated melt-draw specialists and ISO 10993-certified contract manufacturers. Competitive moves concentrate on portfolio diversification into wound care applications and geographic expansion through distributor networks in Asian medical device clusters.
Among German-based conglomerates, SCHOTT AG exemplifies the vertically integrated archetype with Mainz-centered melt-draw infrastructure. Mo-Sci Corporation and NovaBone Products occupy positions within the custom formulation tier, with the former representing Missouri-based specialty glass capabilities and the latter exemplifying Florida-centered dental regeneration focus. Stryker Corporation anchors the orthopedic OEM integration vector through its established hospital procurement channels.
| Leading Market Players |
|---|
| ETS Wound Care LLC |
| SCHOTT AG |
| Mo-Sci Corporation |
| Zimmer Biomet Holdings, Inc. |
| Stryker Corporation |
| Corbion Biotech, Inc. |
| Vetra Biomaterials |
| NovaBone Products, LLC |
| Prosidyan, Inc. |
| Others |
Supply Flow & Price Mechanics
Strontium-doped bioactive glass fiber manufacturing is compressing cost economics for orthopedic implant suppliers while simultaneously concentrating supply relationships around German and US melt-draw specialists with captive ISO 10993 testing infrastructure. This compositional precision shift rewards vertically integrated producers with pricing power over mid-scale converters lacking in-house material characterization laboratories.
Pricing Analysis
High-purity silica feedstock costs pass through directly to medical-grade bioglass fiber pricing, compressing margins for converters without long-term chemical supply agreements. Pricing stratifies across premium strontium-doped compositions, standard 45S5 formulations, and economy-grade E-glass alternatives, with FDA 510(k) certification tier commanding substantial premiums. Price erosion runs through economy segments as synthetic hydroxyapatite substitutes gain traction in cost-sensitive hospital systems. Orthopedic OEMs exhibit lowest price sensitivity due to unbundled procurement protocols, while dental practices demonstrate highest sensitivity to per-unit fiber costs.
Supply Chain Analysis
Freight costs for gamma-sterilized porous fiber architectures concentrate supply chain optimization efforts around regional sterilization hubs in Germany, the United States, and South Korea. Raw material dependencies center on specialized silica from German chemical suppliers, calcium phosphate precursors, and antimicrobial ion dopants. Single-source vulnerability in high-purity silica purification exposes converters to input disruption. Distribution runs through direct hospital system contracts for orthopedic volumes, with distributor networks capturing wound care geographic expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioglass fiber market functions as a regulatory compounder where EU MDR clinical evidence mandates and FDA 510(k) pathway streamlining simultaneously elevate barriers and accelerate volume capture for qualified suppliers.
For Market Incumbents: Lock in supplier consolidation gains by deepening backward integration into high-purity silica purification and expanding captive ISO 10993-18 toxicology laboratories. Synthetic hydroxyapatite substitution threats in emerging markets demand defensive pricing protocols and strontium-doped premium tier expansion to protect margin pools. For New Entrants and Emerging Players: Enter via antimicrobial glass fiber dressings for chronic diabetic wound protocols, the fastest-climbing application segment with lower regulatory qualification burdens than orthopedic implants. South Korean MFDS cluster development offers localized sourcing partnerships as a go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale custom formulation specialists with ISO 10993 documentation libraries but limited sterilization infrastructure. Long-term viability hinges on 3D printing convergence for patient-specific bone grafts. Watch FDA breakthrough device designations for composite bone grafts as inflection signal for reimbursement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-18 Toxicology Laboratory Investment | EU MDR compliance accelerates demand for extractables and leachables expertise. |
| Strontium Doping Process Scale-Up | Osteoporotic patient protocols command premium pricing over standard compositions. |
| South Korean Sterilization Infrastructure Partnership | MFDS cluster development reduces import dependency for Seoul-based OEMs. |
| 3D Printing Composite Scaffold Development | Patient-specific bone grafts create service revenue models outside commodity fiber sales. |
| Chronic Diabetic Wound Protocol Penetration | Antimicrobial ion-doped dressings open volume channels outside orthopedic implants. |
Methodological Framework
Coverage spans Germany, the United States, South Korea, Japan, and Switzerland, with primary inputs from each market cluster. The research combines interviews with orthopedic implant procurement managers, biomedical engineers at hospital value analysis committees, glass fiber plant managers, and regulatory affairs specialists with secondary validation through FDA 510(k) filings, EU MDR technical documentation, and hospital GPO contract databases. Bottom-up fiber volume estimates and top-down orthopedic implant market sizing were triangulated to reconcile production capacity with end-use consumption patterns.
Granularity-level modeling tracked bioactive glass fiber demand by compositional chemistry, end-user clinical setting, and distribution channel structure across the projection horizon. Segmentation dimensions included product type, application therapeutic modality, and regional regulatory cluster. CAGRs were derived from weighted average growth rates across these dimensions, incorporating strontium-doped formulation adoption curves and wound care protocol penetration rates as industry-specific demand drivers.
The model holds under stable FDA and EU MDR regulatory frameworks; deviation in sterilization infrastructure capacity or silica feedstock supply disruption would shift volume and pricing assumptions. Forecasts reflect documented assumptions about clinical adoption timelines and reimbursement pathway evolution. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Keratin Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
Europe Carbon Fiber Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Fiberglass Cloth Market
Fibers
Drug Integrated Polymer Fibers Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Ceramic Fiber Market
Fibers
Dry-Molded Fibre Market
Fibers
Global R-Glass Fiber Market
Fibers
Sisal Market
Fibers
Artificial Muscle Fibers Market
Fibers
Global Basalt Fiber Market
Fibers
Fiber Intermediates Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market