

Precision Fiber Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Fiber Molding Market Insights
Renewable energy is repositioning precision fiber molding toward larger-scale turbine blade production. Gurit Holding AG leverages its prepreg technology leadership to anchor European wind supply chains. Janicki Industries dominates aerospace tooling scale, while TPI Composites extends its molded blade manufacturing across North American wind installations.
Precision fiber molding engineers thermoset or thermoplastic resin matrices around aligned fiber reinforcements under controlled temperature and pressure cycles, achieving specific strength ratios exceeding most metallic alternatives. Carbon fiber sheets command premium positioning due to aerospace certification burdens, whereas glass fiber laminates occupy volume-driven renewable energy segments. Custom molded components compete on geometric complexity for defense and consumer electronics applications.
FAA airworthiness directives and EASA CS-25 standards govern aerospace fiber placement and bonding protocols, while REACH restricts certain epoxy hardeners in European production. OEM procurement teams must monitor evolving EPA emissions thresholds for open-mold processes and the EU Carbon Border Adjustment Mechanism's treatment of imported prepregs. Stakeholders should weigh certification backlog risks against qualification timelines for next-generation bio-based resin systems.
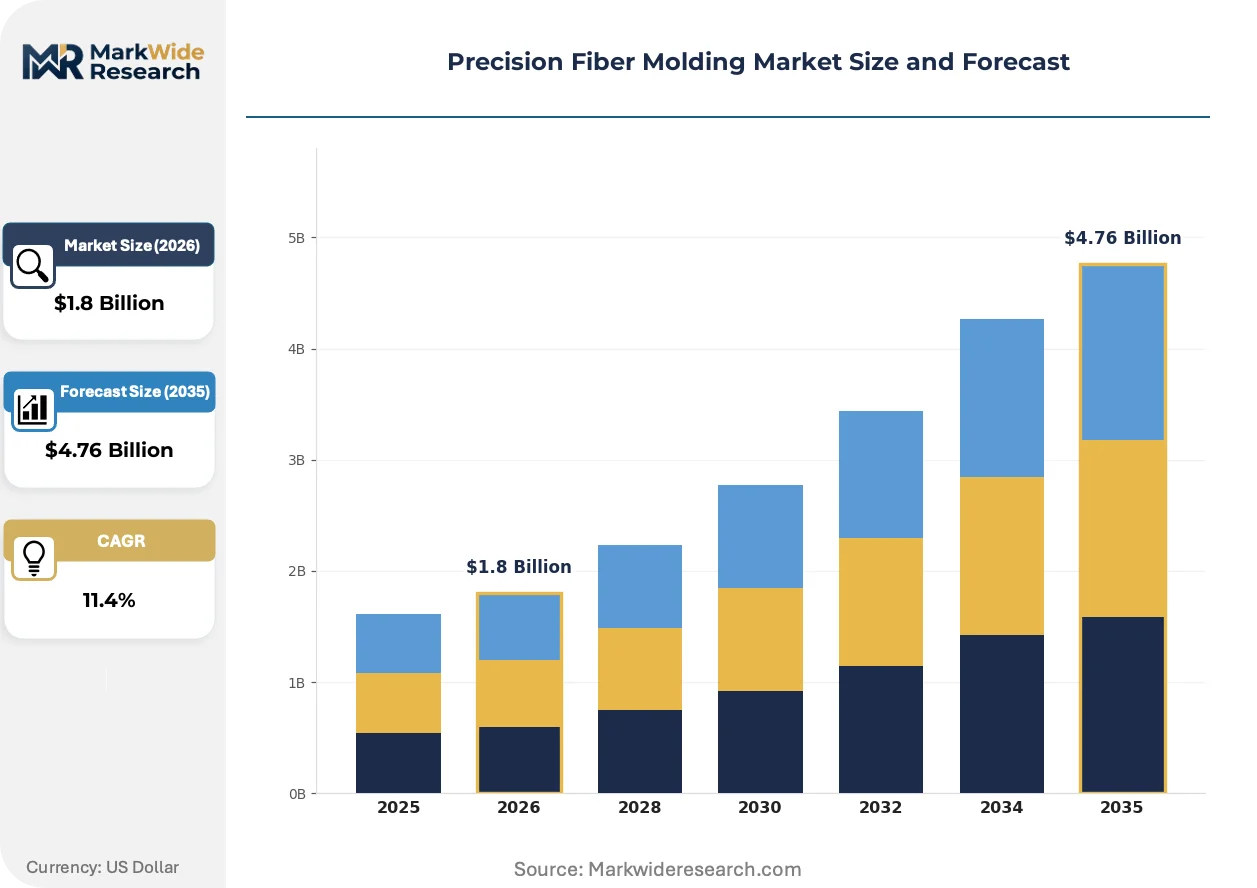
Market Dynamics
Aerospace OEMs are compressing component qualification timelines while simultaneously tightening embodied carbon specifications, forcing molders to reconcile accelerated certification with sustainable resin transitions.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Tightening material specifications are redirecting procurement toward low-carbon prepregs in German aerospace and automotive clusters.
- Wind turbine blade scaling:Renewable energy OEMs are demanding larger molded structures, pulling fiber placement capacity from traditional aerospace applications.
- Automotive lightweighting mandates:Structural battery enclosures and body-in-white components are absorbing thermoplastic composite capacity previously dedicated to industrial applications.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs swing with energy markets, compressing margin buffers for mid-tier molders without long-term supply agreements.
- Toray/Mitsubishi Chemical supply concentration:Japanese precursor manufacturers control upstream capacity, creating bottleneck risk for European and North American fabricators.
- Autoclave throughput limitations:Cured component size constraints cap economies of scale for aerospace structural parts exceeding six meters.
Strategic Opportunities
- India PLI scheme for advanced materials:Domestic manufacturing incentives are attracting precision molding investments for defense and space applications.
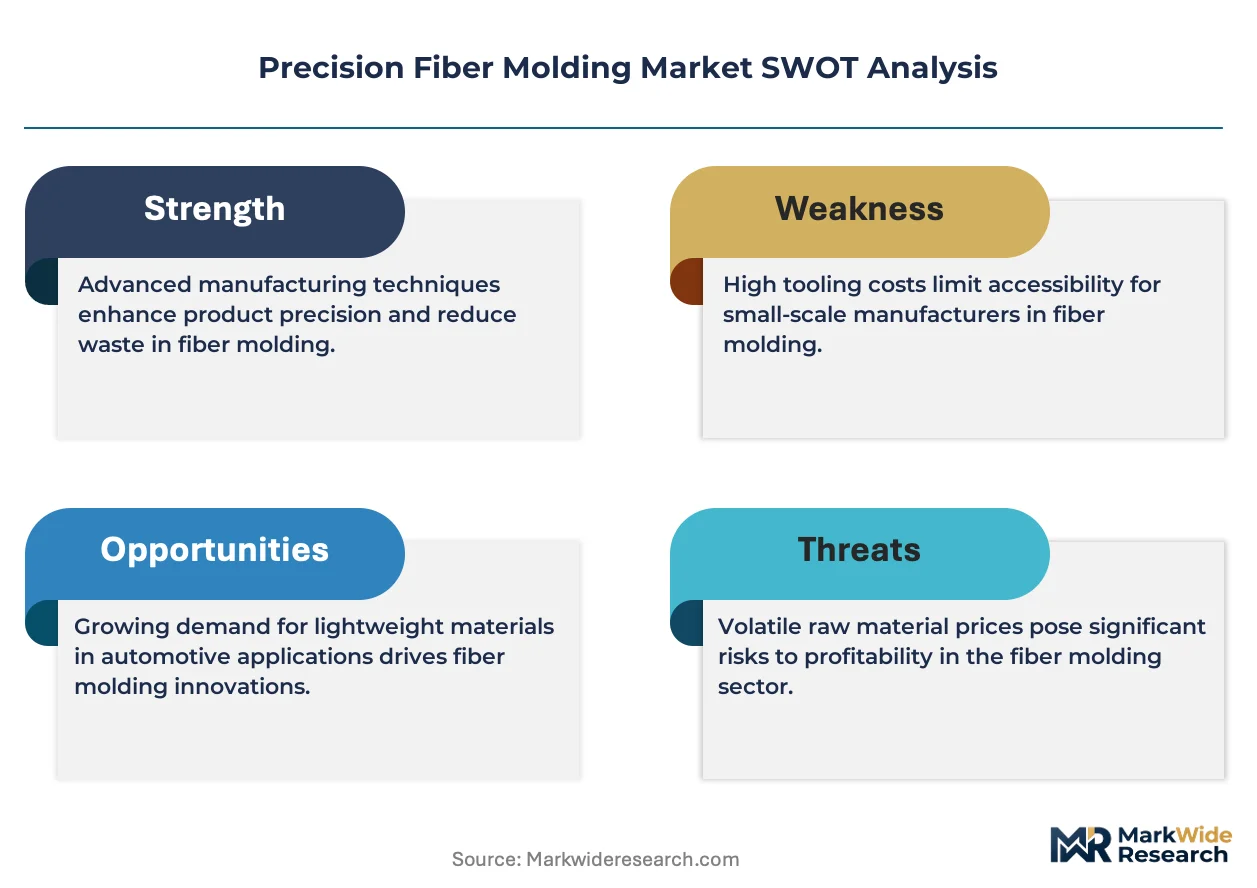
- Thermoplastic-thermoset hybrid processing:Overmolding combinations are unlocking geometric complexity previously unattainable with single-matrix systems.
- Direct digital manufacturing channels:Configurator-based ordering platforms are shortening quoting cycles for custom defense and medical components.
Industry Challenges
- Automated fiber placement programming expertise:Shortages of machine path optimization specialists are extending commissioning timelines for new production lines.
- EASA CS-25 and FAA concurrent certification:Dual qualification requirements for transatlantic aerospace programs are stretching engineering resources across parallel submission tracks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Fiber Molding Market Trends and Innovations
Process automation and material science advances are compressing development cycles while expanding the geometric and performance envelope of molded fiber structures across defense, energy, and mobility applications.
Out-of-autoclave thermoplastic composites are modularizing production workflows for mid-size structural components. Automotive Tier 1 suppliers are adopting these systems for battery tray manufacturing at volumes exceeding traditional aerospace programs. The technology is modularizing factory layouts, enabling cellular manufacturing configurations that slash capital intensity versus fixed autoclave installations.
REACH restrictions on certain epoxy hardeners are forcing formulation changes across European production facilities. ECHA substance evaluations are disqualifying legacy curing agents used in wind blade and marine applications. German molders are accelerating bio-based resin qualification programs to maintain market access under evolving chemical safety frameworks.
Consolidated procurement through integrated design-to-manufacture platforms is compressing supplier selection cycles. Aerospace OEMs are bundling tooling, molding, and finishing contracts with single-source partners capable of delivering finished aerostructures. This pattern concentrates most visibly in Bavaria and Baden-Württemberg, where tiered supplier networks align with major airframe assembly sites.
Precision Fiber Molding Market Segmentation
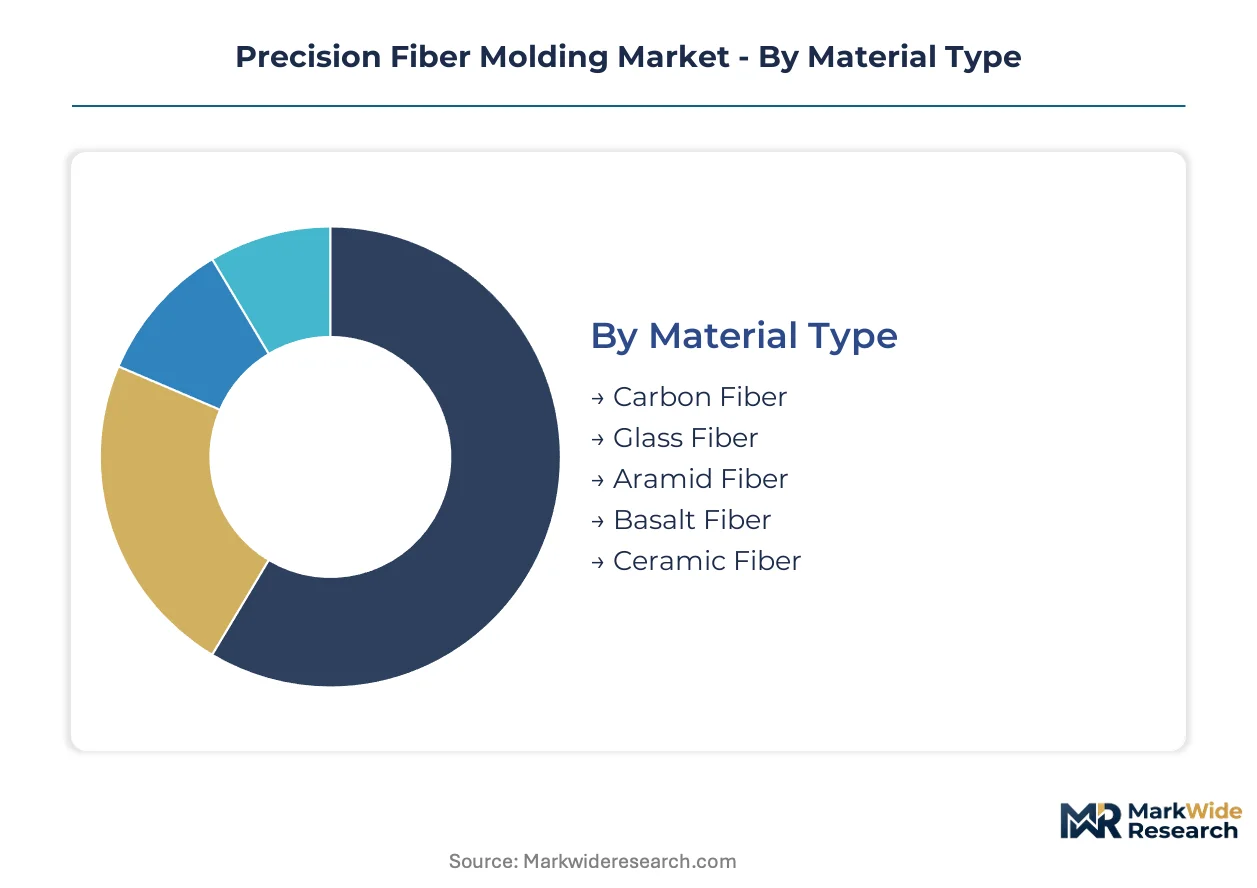
Upgrade cycles in aerospace tooling and wind turbine blade replacement schedules are fragmenting demand across material grades and geometric formats. Procurement teams segment suppliers by certification depth, resin compatibility, and autoclave scale rather than commodity pricing alone.
Material Type:
Replacement timelines for legacy metallic structures are accelerating fiber substitution decisions, with certification burdens and embodied carbon thresholds filtering material selection.
- Carbon Fiber:Toray T800 and T1100 grades dominate aerospace primary structures requiring specific strength ratios above 200 MPa/(g/cm³). FAA qualification timelines and EU Carbon Border Adjustment Mechanism compliance are concentrating procurement among German and Japanese precursor suppliers with established airworthiness dossiers.
- Glass Fiber:E-glass and S-2 formulations serve wind blade spar caps and automotive battery enclosures where cost thresholds override aerospace-grade certification. Demand clusters in Denmark's Vestas supply chain and TPI Composites' North American blade facilities.
- Aramid Fiber:Kevlar and Twaron reinforcements absorb ballistic impact in defense helmets and vehicle armor.
- Basalt Fiber:Russian and Ukrainian raw material sources supply corrosion-resistant rebar and marine applications.
- Ceramic Fiber:Oxide and non-oxide matrices withstand exhaust temperatures exceeding 1200°C in aerospace propulsion.
Volume placements concentrate in glass fiber; the faster expansion belongs to carbon fiber.
Product Type:
Customer tooling investments and part consolidation strategies are reshaping format preferences across defense, medical, and energy verticals.
- Custom Molded Components:Complex geometries for drone airframes and surgical robotics require multi-axis fiber placement and soluble mandrel extraction. Bavarian toolrooms and Janicki Industries' Washington facilities compete on programming sophistication and finish tolerances.
- Laminates:Prepreg stacks with controlled fiber orientation serve aircraft flooring and satellite panels. Gurit Holding AG's European supply chain and Toray's US prepreg operations anchor qualification-dependent procurement.
- Sheets:Flat stock feeds CNC machining centers for brackets and shims.
- Tubes:Filament-wound cylinders support bicycle frames and industrial rollers.
- Rods:Pultruded profiles reinforce concrete and utility poles.
Standard formats dominate current volume; custom geometries are climbing the fastest.
Application:
End-use performance requirements and regulatory exposure are segmenting molders by certification depth and resin system specialization.
- Aerospace:Primary structures and flight-critical components require EASA CS-25 and FAA concurrent qualification. Embodied carbon thresholds under EU Green Deal procurement rules are redirecting German OEMs toward bio-epoxy prepregs with full traceability.
- Renewable Energy:Wind turbine blades exceeding 80 meters demand automated fiber placement at scales autoclaves cannot accommodate. Out-of-autoclave thermoplastic processing is modularizing production for offshore installations.
- Defense:Ballistic protection and unmanned vehicle airframes absorb aramid and carbon fiber capacity.
- Consumer Electronics:Laptop chassis and wearable housings prioritize aesthetic surface finish.
- Sporting Goods:Bicycle frames and hockey sticks compete on weight claims and brand licensing.
Energy installations absorb the largest volume placements; aerospace maintains the steepest expansion trajectory.
End User Industry:
Supply chain integration depth and design authority location are determining procurement channel selection.
- OEMs:Airbus, Boeing, and Dassault Aviation retain direct molding contracts for proprietary wing and fuselage sections. Consolidated procurement through integrated design-to-manufacture platforms is compressing supplier selection cycles to single-source partnerships.
- Tier-1 Manufacturers:Spirit AeroSystems and GKN Aerospace manage subcontracted fiber placement for major airframe programs. REACH restrictions on epoxy hardeners are forcing formulation changes across their European production networks.
- System Integrators:Defense contractors bundle composite structures into platform-level deliveries.
- Aftermarket Suppliers:MRO facilities and replacement part fabricators serve aging aircraft fleets.
Tier-1 channels capture the greatest volume; OEM direct contracting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's Aerospace Technology Park outside Munich concentrates autoclave capacity serving Airbus and MTU Aero Engines. Germany's composites corridor between Munich and Stuttgart absorbs the highest European precision fiber molding investment intensity.
Germany
Airbus procurement teams at Hamburg and Toulouse source primary structures from Bavarian molders certified to EASA CS-25. EU Green Deal embodied carbon thresholds redirect contracts toward bio-epoxy prepregs with full supply chain traceability. The Munich-Stuttgart corridor hosts Toray's European prepreg distribution and Gurit Holding AG's wind blade resin operations.
United States
Boeing's Everett and Charleston facilities drive automated fiber placement demand for 787 and 777X wing structures. FAA airworthiness directives govern concurrent qualification timelines with EASA for transatlantic programs. Janicki Industries anchors aerospace tooling scale in Sedro-Woolley, Washington, while TPI Composites operates molded blade facilities across Iowa and New Mexico wind corridors.
China
COMAC's C919 production ramp pulls carbon fiber placement capacity toward Shanghai Pudong assembly lines. MIIT dual carbon goals accelerate domestic precursor manufacturing to reduce Toray and Mitsubishi Chemical import dependence. The Yangtze River Delta concentrates wind blade molding for Goldwind and Envision Energy offshore installations.
India
ISRO's launch vehicle programs and HAL's Tejas fighter contracts absorb aramid and carbon fiber capacity for defense applications. The PLI scheme for advanced materials offers 4-6% output-linked incentives to domestic precision molding investments. Gujarat's Special Investment Region near Vadodara attracts Indutch Composites Technology and European Tier-1 satellite structure suppliers.
Japan
Toray Industries and Mitsubishi Chemical control global carbon fiber precursor supply from Oita and Nagoya facilities. METI technology roadmaps prioritize thermoplastic composite processing for automotive lightweighting. The Chubu region around Nagoya anchors aerospace material qualification for Boeing and Airbus Japanese supply chain integration.
Precision Fiber Molding Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace qualification requirements favoring integrated design-to-manufacture partners while renewable energy tolerates modular component sourcing. The vendor base organizes into three tiers: Japanese precursor suppliers controlling upstream chemistry, European prepreg formulators managing qualification dossiers, and regional molders competing on autoclave scale and geometric complexity. Consolidation pressure concentrates among mid-tier fabricators lacking long-term supply agreements with Toray or Mitsubishi Chemical. Competitive moves center on backward integration into resin formulation and geographic expansion into Indian defense and space programs.
Among European prepreg specialists, Gurit Holding AG exemplifies the qualification-dependent archetype through its wind blade resin supply chain anchoring. Janicki Industries occupies a position within the large-scale tooling tier, representing aerospace fixture fabrication at scales exceeding conventional mold dimensions. TPI Composites sits within the renewable energy molding segment, exemplifying volume-driven blade manufacturing across North American wind installations.
| Leading Market Players |
|---|
| Gurit Holding AG |
| Janicki Industries |
| Dencam Composite A/S |
| SSP Technology |
| Molded Fiber Glass Companies |
| TPI Composites |
| Indutch Composites Technology Private Limited |
| Norco GRP |
| SCHÜTZ GmbH & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied carbon thresholds gate qualified supply access and premium-tier pricing power, forcing Tier-1 manufacturers to absorb bio-epoxy qualification costs while aerospace OEMs pass through carbon border adjustment premiums to downstream contracts. This sustainability mandate concentrates procurement leverage among German and Japanese precursor suppliers with established airworthiness dossiers, compressing margin buffers for mid-tier molders lacking long-term supply agreements.
Pricing Analysis
Lead-time-driven pricing stratification rewards short-cycle delivery with premium positioning, particularly for FAA-qualified carbon fiber prepregs facing concurrent EASA submission backlogs. Contract-based long-term offtake dominates aerospace procurement, while spot inventory discounts attract renewable energy buyers with flexible qualification timelines. Price differentiation hinges on certification grade and volume scale, with carbon fiber T800/T1100 grades commanding substantial premiums over glass fiber laminates. Pricing pressure stems from acrylonitrile precursor volatility, squeezing molders without Toray or Mitsubishi Chemical supply security. Wind blade manufacturers exhibit highest price sensitivity; defense contractors tolerate premium positioning for ballistic-grade aramid specifications.
Supply Chain Analysis
Certification and qualification gating concentrates aerospace-grade supply among Japan, Germany, and the United States, with Toray Industries and Mitsubishi Chemical controlling carbon fiber precursor chemistry from Oita and Nagoya facilities. Raw material dependencies center on acrylonitrile monomer, epoxy resin systems, and automated fiber placement equipment. Single-source vulnerability pervades the precursor tier, where Japanese manufacturers anchor upstream capacity without qualified alternatives. Distribution runs through integrated design-to-manufacture platforms consolidating tooling, molding, and finishing contracts with single-source partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EASA CS-25 and FAA concurrent certification requirements erect formidable barrier-to-entry moats protecting qualified incumbents from unqualified challengers.
For Market Incumbents: Hedge against bio-resin transition risks by accelerating backward integration into formulation chemistry before REACH restrictions disqualify legacy curing agents. Secure long-term precursor supply agreements with Toray or Mitsubishi Chemical to defend against acrylonitrile price volatility eroding margin buffers. Expand autoclave capacity in India's Gujarat Special Investment Region to capture PLI scheme incentives for defense and space applications. For New Entrants and Emerging Players: Thermoplastic-thermoset hybrid processing offers a technology-first wedge into automotive battery enclosure manufacturing, where out-of-autoclave methods bypass aerospace qualification bottlenecks. Target India's defense procurement channels for unmanned vehicle airframes and ballistic protection components, where domestic manufacturing incentives reduce established supplier advantages. Pursue direct digital manufacturing channels with configurator-based quoting platforms to compress sales cycles for custom medical and defense geometries. For Investors and Strategic Acquirers: Boeing or Airbus qualification of a bio-epoxy prepreg supplier is the leading indicator that sustainable resin transitions have achieved commercial viability across transatlantic aerospace programs. Over a multi-year horizon, vertically integrated molders with captive precursor relationships and full EASA/FAA dossiers represent the most defensible acquisition profile. Monitor ECHA substance evaluations for additional epoxy hardener disqualifications, which would trigger forced consolidation among European Tier-1 manufacturers lacking alternative formulation pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | German molders secure supply chain control against REACH restrictions on legacy curing agents. |
| Out-of-Autoclave Capacity Expansion | Automotive Tier-1 suppliers modularize production for battery tray volumes exceeding aerospace programs. |
| Concurrent EASA/FAA Qualification Investment | Airbus and Boeing procurement teams consolidate supplier selection around single-source aerostructure partners. |
| Geographic Expansion into India | ISRO and HAL contracts absorb aramid and carbon fiber capacity under PLI scheme incentives. |
| Direct Digital Manufacturing Platform Launch | Configurator-based ordering shortens quoting cycles for defense and medical custom geometries. |
Research Methodology
Independent corroboration across primary interviews with aerospace procurement directors, composite plant managers, wind blade manufacturing engineers, and defense contractor supply chain leads, combined with secondary validation through FAA airworthiness directives, EASA certification databases, customs and trade data, and SEC filings from listed precursor suppliers, underwrites the qualitative findings. Bottom-up segment sizing and top-down macroeconomic triangulation anchor volume and value estimates.
Comparable-period anchoring to historical aerospace production cycles and wind turbine installation schedules structures the projection framework across the analysis window. Segmentation dimensions include material type, product format, application vertical, and end-user channel, with CAGRs derived from regression analysis against carbon fiber precursor capacity expansion and renewable energy installation forecasts. Modeled inputs incorporate embodied carbon threshold compliance costs and automated fiber placement commissioning timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory restrictions on additional epoxy hardeners, geopolitical disruption to Japanese precursor exports, and breakthrough thermoplastic processing technologies displacing autoclave-dependent methods. Forecasts reflect documented assumptions about qualification timeline continuity and supply agreement renewal patterns. A model refresh is warranted upon material change in EU Carbon Border Adjustment Mechanism implementation scope or EASA/FAA harmonization protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.