
 Basalt Continuous Fiber (BCF) Market | 2026-2036
Basalt Continuous Fiber (BCF) Market Size, Share, and Industry Trends Forecast 2026-2036
Basalt Continuous Fiber (BCF) Market Insights
Aerospace parts procurement is pivoting toward thermally stable reinforcements as next-generation engine nacelles and interior panels seek alternatives to carbon fiber cost structures. Kamenny Vek leverages proprietary direct-melt furnace technology to sustain supply continuity for filament-wound pressure vessels. Zhejiang GBF Basalt Fiber Co. dominates roving output for Asian construction markets, while Technobasalt-Invest anchors European distribution through specialized logistics for braided rope applications.
Basalt Continuous Fiber consists of extruded filaments drawn from molten basalt rock at temperatures exceeding 1,400°C, yielding amorphous oxide fibers with tensile strength comparable to S-glass and superior chemical resistance to alkali environments. Construction composites command the largest application share, reflecting infrastructure developers' preference for corrosion-resistant rebar and mesh in marine-exposed concrete. Wind turbine blades represent the fastest-growing application segment, as blade lengths exceeding 80 meters demand fatigue-resistant spar cap materials that compete with glass-carbon hybrids on cost-performance metrics. Rovings lead product type volumes due to their compatibility with pultrusion and filament winding lines serving utility pole and pipe manufacturers.
EPA emissions standards for industrial mineral processing shape North American facility permitting, while REACH substance restrictions in Europe govern fiber surface chemistry and sizing agent composition. ECHA evaluation of persistent inorganic fibers influences classification debates that could redirect product development toward biosoluble formulations. Stakeholders must monitor regulatory divergence between EU hazard classifications and OSHA permissible exposure limits, as misalignment threatens cross-border supply qualification costs and manufacturing relocation decisions.
Market Dynamics
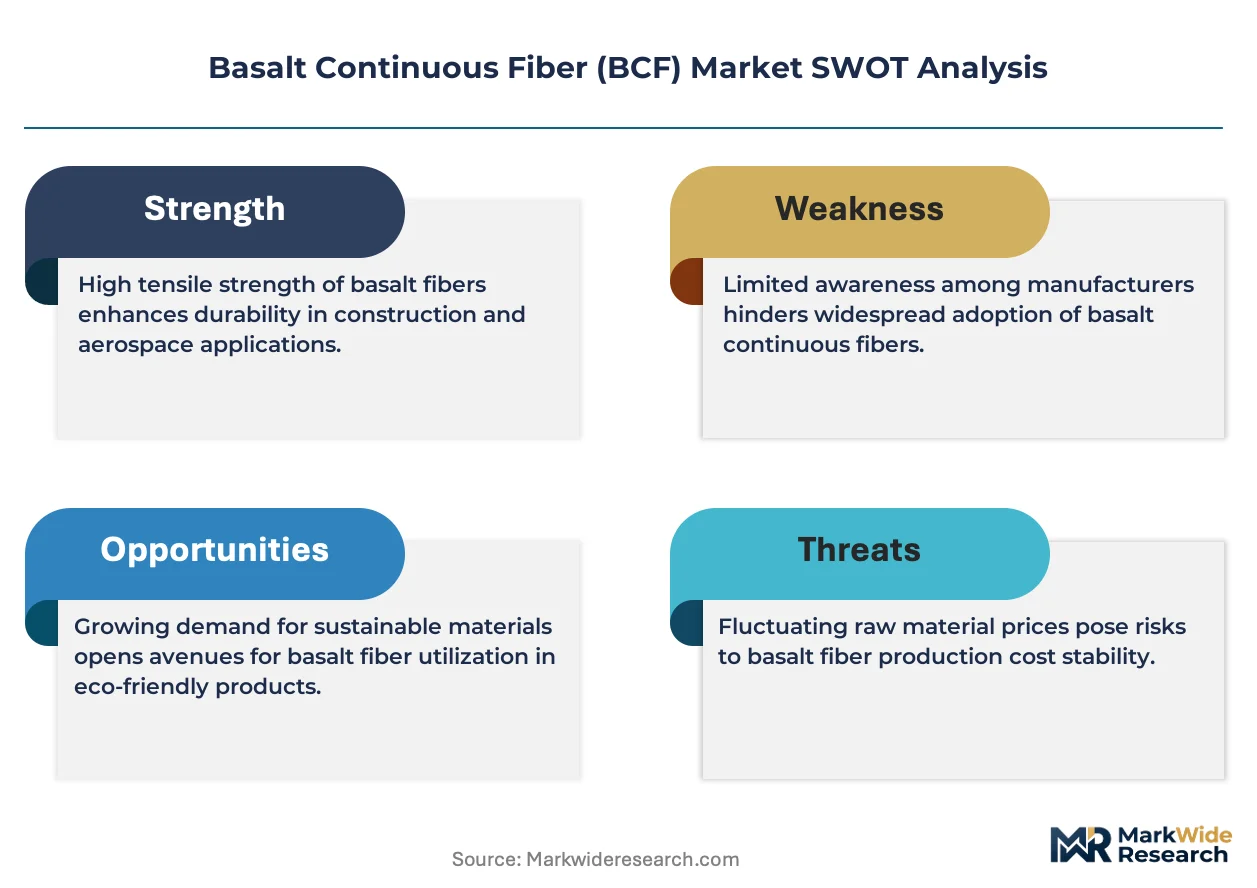
Direct-melt furnace technology is compressing production costs while REACH substance restrictions in Europe are redirecting specification decisions toward basalt-derived reinforcements, creating a bifurcation between cost-optimized supply and compliance-driven demand.
Growth Catalysts
- EU Green Deal procurement mandates:Infrastructure renewal projects across Germany and France now specify corrosion-resistant rebar and mesh in marine-exposed concrete, pulling roving volumes from domestic suppliers.
- Wind turbine blade scaling:Blade lengths exceeding 80 meters demand fatigue-resistant spar cap materials that compete with glass-carbon hybrids on cost-performance metrics.
- Automotive lightweighting programs:German OEMs are integrating BCF into underbody shields and battery enclosures to meet fleet emissions targets.
Market Restraints
- Energy input cost volatility:Melting basalt rock requires sustained temperatures exceeding 1,400°C, exposing producers to natural gas and electricity price swings.
- Russian supply concentration:Kamenny Vek and Technobasalt-Invest anchor a significant share of European filament supply, creating geopolitical exposure.
- Carbon fiber substitution threat:Aerospace interior panel specifications still default to carbon fiber where budget constraints permit, limiting BCF penetration in premium segments.
Strategic Opportunities
- India infrastructure build-out:The country's PLI scheme for advanced materials creates entry pathways for BCF rebar in coastal highway and port construction.
- Filament-wound pressure vessels:Hydrogen storage applications for fuel cell vehicles represent an emerging demand vertical with qualification timelines shortening.
- CE marking harmonization:Simplified conformity assessment for construction products is reducing time-to-market for new BCF fabric entrants.
Industry Challenges
- Furnace engineering talent scarcity:Direct-melt operation requires specialized refractory and thermal management expertise concentrated in legacy mineral wool industries.
- ECHA classification uncertainty:Persistent inorganic fiber evaluation timelines are delaying product development investments toward biosoluble formulations.
- Pultrusion line integration complexity:Legacy fiberglass equipment requires retrofitting for BCF roving tension and sizing compatibility, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basalt Continuous Fiber (BCF) Market |
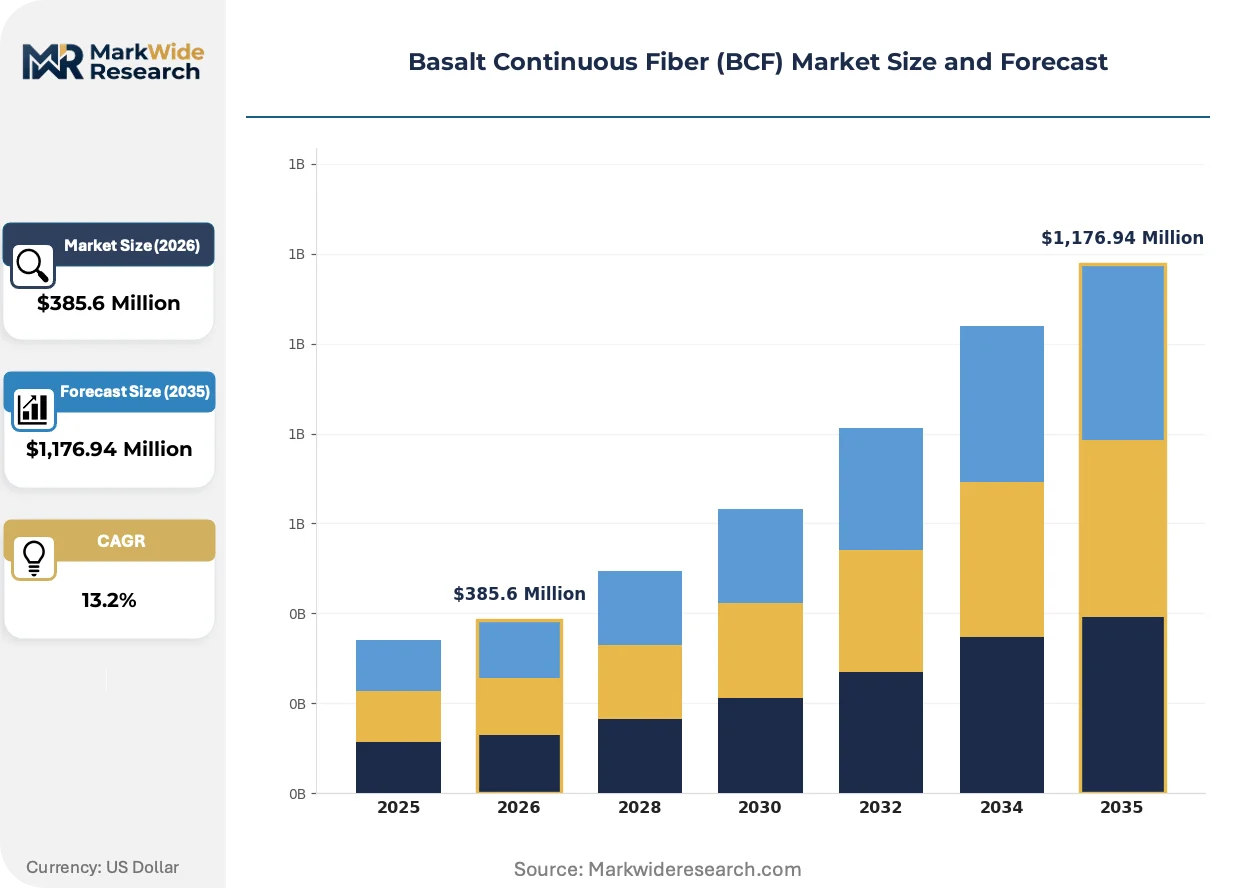
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,176.94 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Fibers, Rovings, Continuous Tow, Tow Fabrics, Braided Ropes Technology: Filament Winding, Pultrusion, Weaving, Knitting, Nonwoven Application: Construction Composites, Marine Components, Aerospace Parts, Wind Turbine Blades, Sporting Goods End User: Infrastructure Developers, Shipbuilders, Aircraft Manufacturers, Renewable Energy Firms, Athletics Equipment Makers |
| Companies Covered | Kamenny Vek, Zhejiang GBF Basalt Fiber Co., Technobasalt-Invest, Mafic SA, Deutsche Basalt Faser GmbH, Sudaglass Basalt Fiber Technology, Tespe srl, Basaltex NV, Sichuan Qianyi Composite Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basalt Continuous Fiber (BCF) Market Trends and Innovations
Process intensification in fiber drawing and surface chemistry engineering are reshaping cost curves and application boundaries simultaneously, with regulatory chemistry constraints now driving as much innovation as performance specifications.
Direct-melt furnace technology is overtaking traditional bushing-based drawing methods in new capacity installations. Chinese producers are adopting single-step melting and fiber formation to reduce energy intensity and capital requirements. This process convergence is overtaking the historical two-stage production model and compressing payback periods for greenfield investments.
REACH substance restrictions governing fiber surface chemistry and sizing agent composition are forcing reformulation of standard industrial grades. ECHA evaluation of persistent inorganic fibers is redirecting R&D expenditure toward biosoluble oxide compositions. European construction composite specifications are responding fastest, with German infrastructure tenders now requiring explicit fiber solubility documentation.
Specification-driven procurement is consolidating buyer power among tier-one wind turbine OEMs and automotive Tier 1 suppliers. Long-term offtake agreements with volume commitments are displacing spot market purchasing for roving and fabric grades. This pattern is most visible in Germany, where blade manufacturers and automotive lightweighting programs are locking in multi-year supply contracts to secure qualification continuity.
Basalt Continuous Fiber (BCF) Market Segmentation
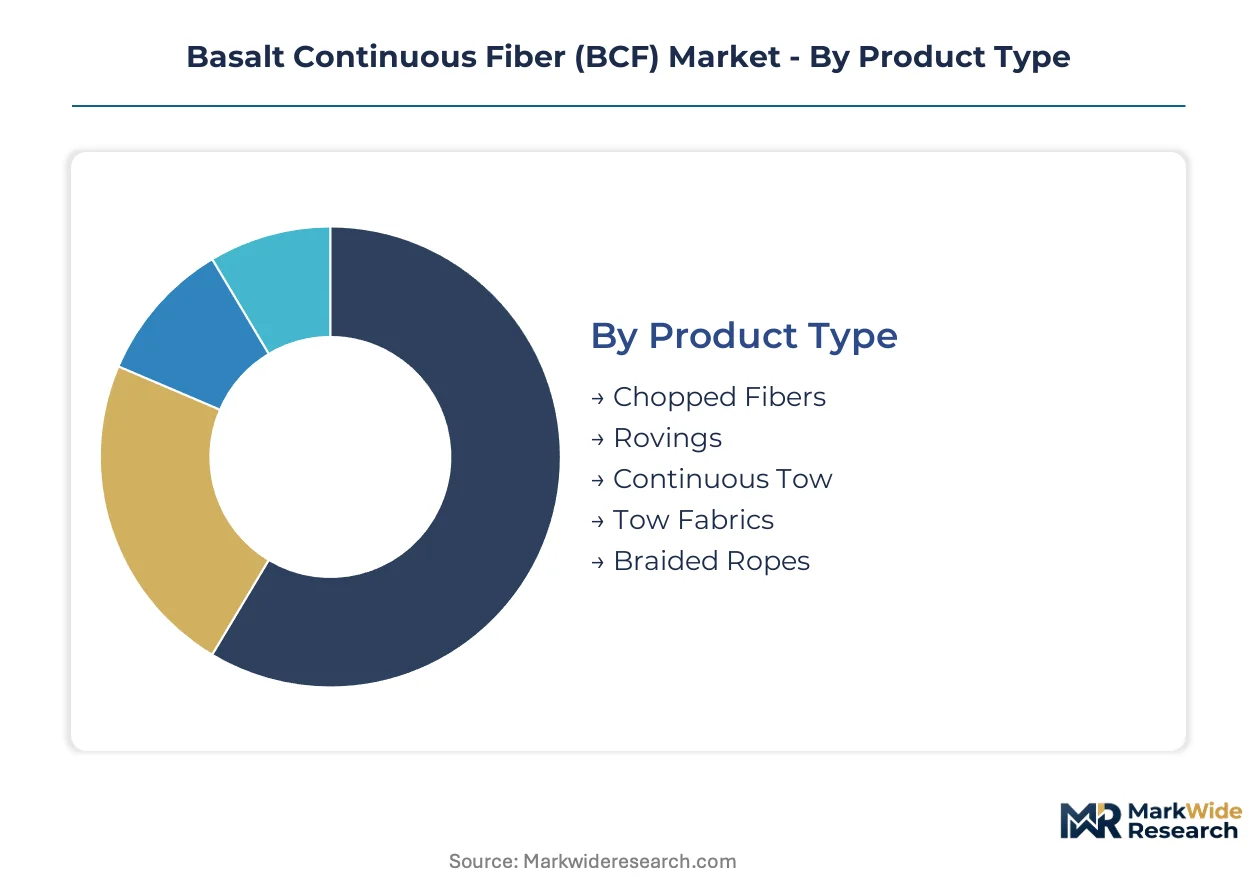
BCF procurement patterns diverge sharply across product forms and processing routes. Specification decisions hinge on thermal stability requirements, chemical exposure profiles, and compatibility with legacy composite manufacturing lines.
Product Type:
Filament diameter and bundle architecture determine processing economics and mechanical performance thresholds.
- Rovings:Untwisted bundles of continuous filaments serve as feedstock for pultrusion and filament winding operations. German utility pole manufacturers and pipe producers pull substantial volumes due to compatibility with existing glass fiber production infrastructure.
- Chopped Fibers:Short-cut filaments disperse through thermoplastic and thermoset matrices for injection molding and bulk molding compound applications. Automotive underbody shield programs specify these grades for impact resistance at reduced weight.
- Continuous Tow:Zero-twist assemblies feed automated tape laying and fiber placement systems. Aerospace interior panel trials evaluate these formats against carbon fiber cost structures.
- Tow Fabrics:Woven architectures from continuous tow provide multidirectional reinforcement for marine hull laminates and wind turbine blade skins.
- Braided Ropes:Tubular constructions from interlaced yarns serve mooring lines and seismic cable applications where fatigue resistance outweighs stiffness requirements.
Mature deployment sits with Rovings. Newer deployment is concentrated in Braided Ropes.
Technology:
Process selection locks in fiber orientation control, void content, and production throughput.
- Pultrusion:Continuous pulling through heated dies produces constant-profile sections with high fiber volume fractions. Infrastructure rebar and grating manufacturers dominate consumption, though line retrofitting for BCF tension compatibility extends qualification timelines.
- Filament Winding:Computer-controlled fiber placement onto rotating mandrels creates pressure vessels and pipe structures. Hydrogen storage tank developers are accelerating qualification protocols for this technology pairing.
- Weaving:Interlacing warp and weft tows yields fabric preforms for hand lay-up and resin transfer molding. Marine composite shops favor these formats for complex curvature accommodation.
- Knitting:Loop formation from continuous fibers produces stretchable reinforcements for conformable molds and complex geometries.
- Nonwoven:Random fiber mat structures provide isotropic in-plane properties for surfacing veils and core materials.
Volume leadership belongs to Pultrusion. Steepest expansion trajectory is Filament Winding.
Application:
Performance requirements and regulatory exposure create distinct specification tiers across end-use sectors.
- Construction Composites:Corrosion-resistant rebar, mesh, and structural profiles for marine-exposed concrete dominate procurement volumes. EU Green Deal procurement mandates in Germany and France explicitly specify these materials for infrastructure renewal.
- Wind Turbine Blades:Spar caps and shear webs exceeding 80 meters in length demand fatigue-resistant reinforcements. Blade OEMs are locking in multi-year offtake agreements as fiberglass substitution accelerates.
- Marine Components:Hull laminates and superstructures leverage alkali resistance superior to E-glass. Shipbuilders in coastal markets specify these for reduced maintenance cycles.
- Aerospace Parts:Engine nacelles and interior panels seek thermally stable alternatives to carbon fiber where cost constraints apply. Qualification cycles remain extended due to certification requirements.
- Sporting Goods:Bicycle frames and fishing rods exploit vibration damping characteristics. Niche positioning limits volume relative to industrial applications.
Revenue concentration rests with Construction Composites. Gaining share fastest are Wind Turbine Blades.
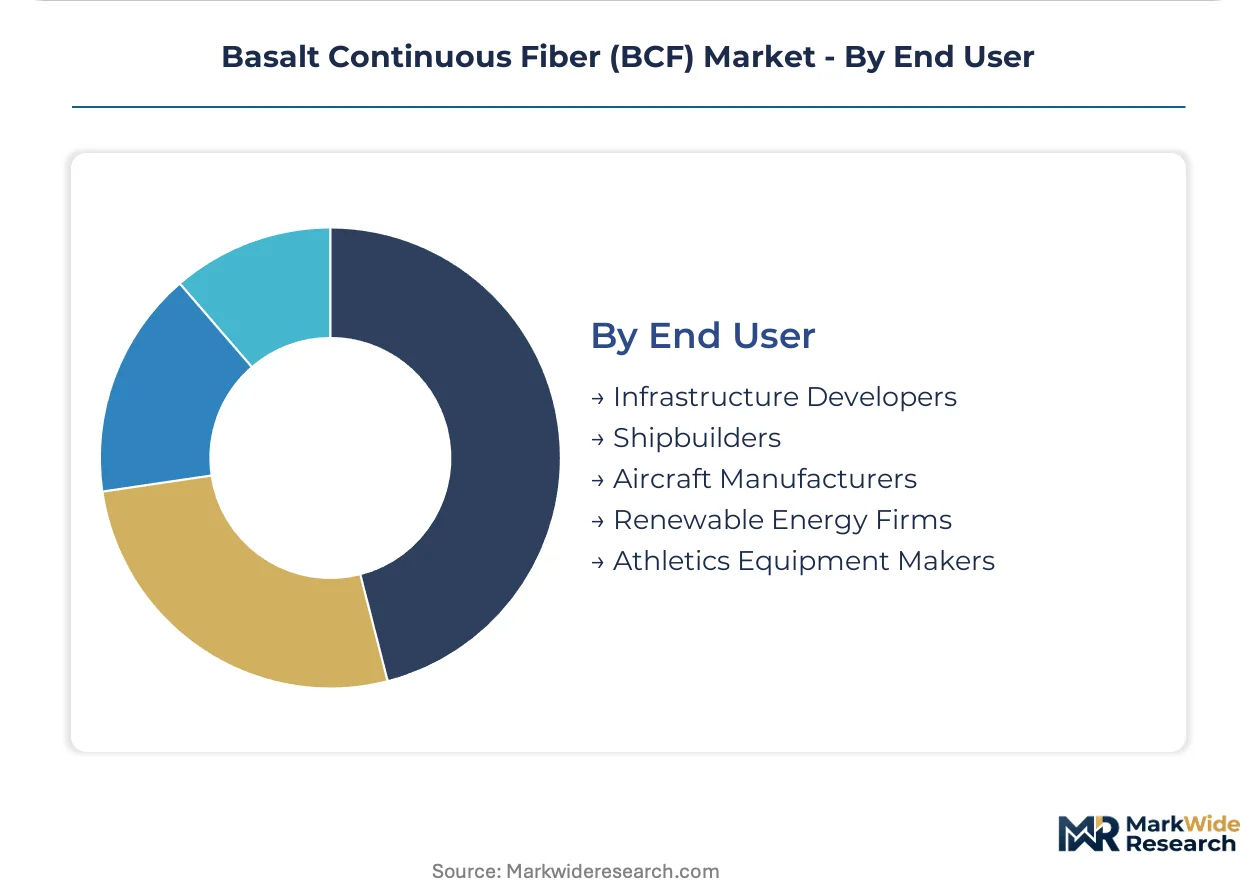
End User:
Buyer sophistication and procurement scale segment the demand base into specification-driven and cost-optimized tiers.
- Infrastructure Developers:Public and private entities executing port, highway, and building projects. REACH compliance documentation and CE marking conformity drive qualification requirements for European tenders.
- Renewable Energy Firms:Wind farm developers and turbine OEMs with consolidated purchasing power. Long-term supply agreements displace spot market transactions for roving and fabric grades.
- Shipbuilders:Commercial and naval vessel constructors specifying laminates for hull and superstructure applications.
- Aircraft Manufacturers:Tier 1 suppliers and OEMs evaluating BCF for non-structural interior components. FAA and EASA certification pathways constrain adoption velocity.
- Athletics Equipment Makers:Specialized manufacturers serving cycling, fishing, and winter sports markets. Smaller batch sizes limit pricing leverage.
Contract maturity is highest with Infrastructure Developers. Emerging specification intensity characterizes Renewable Energy Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Zhejiang and Jiangsu provinces concentrate Chinese basalt fiber capacity, while EU Green Deal procurement mandates redirect European specification decisions toward domestic and Russian suppliers. REACH compliance frameworks and EPA emissions standards create divergent qualification pathways across major demand centers. Industrial clusters in Germany, China, the United States, Russia, and India anchor regional supply-demand dynamics.
Germany
Automotive lightweighting programs and infrastructure renewal projects pull substantial roving volumes from domestic suppliers. EU Green Deal procurement mandates explicitly specify corrosion-resistant rebar and mesh for marine-exposed concrete in port and highway construction. The Rhine-Ruhr industrial corridor hosts filament winding operations serving hydrogen storage tank developers with shortened qualification timelines.
China
Zhejiang GBF Basalt Fiber Co. dominates roving output for Asian construction markets through direct-melt furnace installations. GB standards and MIIT industrial policy guide facility permitting and product certification for domestic infrastructure build-out. The Yangtze River Delta cluster concentrates pultrusion line capacity for utility pole and pipe manufacturers seeking fiberglass alternatives.
United States
EPA emissions standards for industrial mineral processing shape North American facility permitting and furnace technology selection. Wind turbine blade OEMs scale procurement as spar cap material specifications shift toward fatigue-resistant alternatives to glass-carbon hybrids. Texas and Iowa manufacturing corridors anchor composite fabrication for renewable energy supply chains.
Russia
Kamenny Vek leverages proprietary direct-melt furnace technology to sustain supply continuity for European filament-wound pressure vessel markets. Geopolitical exposure concentrates around Technobasalt-Invest's specialized logistics for braided rope applications serving EU infrastructure tenders. The Ural industrial region maintains refractory and thermal management expertise from legacy mineral wool industries.
India
The PLI scheme for advanced materials creates entry pathways for BCF rebar in coastal highway and port construction projects. BIS standards and CEA regulations govern composite material specifications for public infrastructure tenders. Gujarat and Maharashtra industrial zones concentrate preliminary demand assessment for corrosion-resistant reinforcement in marine-exposed concrete applications.
Basalt Continuous Fiber (BCF) Market Competitive Landscape
Top-tier vendors anchor premium-tier supply, while mid-scale specialists occupy technology-differentiated niches. The competitive structure stratifies across furnace technology proprietors, regional volume producers, and application-specific fabricators. Archetypes include direct-melt technology leaders, roving-focused scale operators, and specialized logistics providers for braided constructions. Dominant competitive moves encompass capacity expansion in Chinese special economic zones and strategic partnerships securing long-term offtake agreements with wind turbine OEMs.
Within the technology-leadership tier, Kamenny Vek exemplifies proprietary furnace operation, while Zhejiang GBF Basalt Fiber Co. occupies a position as a scale-driven roving supplier. Technobasalt-Invest represents the specialized-distribution archetype, anchoring European market access through logistics capabilities. These three entities collectively illustrate the geographic and functional segmentation defining competitive positioning in basalt fiber supply.
| Leading Market Players |
|---|
| Kamenny Vek |
| Zhejiang GBF Basalt Fiber Co. |
| Technobasalt-Invest |
| Mafic SA |
| Deutsche Basalt Faser GmbH |
| Sudaglass Basalt Fiber Technology |
| Tespe srl |
| Basaltex NV |
| Sichuan Qianyi Composite Material |
| Others |
Pricing and Supply Chain Analysis
Family-owned furnace operators in Russia and sovereign-backed producers in China anchor supply discipline through long-dated capacity commitments, insulating premium-tier pricing from spot-market volatility while compressing margins for undifferentiated roving grades.
Pricing Analysis
Premium-mid-economy pricing differentiation separates qualified suppliers for EU Green Deal tenders from commodity-grade exporters. Short-lead-time premiums apply to filament-wound pressure vessel feedstock for hydrogen storage developers facing compressed qualification timelines. Price compression runs through standard roving grades as Chinese direct-melt capacity additions outpace German infrastructure procurement growth. Renewable energy firms exhibit lowest price sensitivity due to multi-year offtake structures, while Asian construction distributors negotiate aggressively on volume.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and Zhejiang special economic zones buffer lead-time volatility for qualified buyers. Basalt rock feedstock draws from volcanic deposits in Russia, China, and India, with furnace refractories sourced from legacy mineral wool supply chains in Germany. Single-source vulnerability concentrates around Kamenny Vek's proprietary direct-melt technology for European pressure vessel markets. Distribution runs through specialized logistics providers for braided rope applications serving marine and seismic cable contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and ECHA persistent fiber evaluations erect compliance moats that favor incumbent producers with documented biosoluble formulation pathways, raising capital requirements for qualification beyond mid-scale entrant reach.
For Market Incumbents: Anticipate carbon fiber cost reductions in aerospace interior panels by accelerating CE-marked fabric development for construction composites. Lock in backward integration into basalt rock quarries to secure feedstock cost visibility. Prioritize furnace engineering talent retention as Russian supply concentration risks trigger customer qualification audits. For New Entrants and Emerging Players: Launch via filament-wound pressure vessel partnerships targeting Indian PLI-scheme infrastructure projects. White-space opportunity sits with hydrogen storage tank developers seeking shortened qualification timelines outside established EU supply chains. Avoid direct competition in German automotive lightweighting programs where incumbent offtake agreements block entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor direct-melt technology proprietors in China facing margin compression from overcapacity. Long-term viability hinges on regulatory chemistry compliance rather than scale economics alone. Monitor ECHA classification timelines as the inflection signal for biosoluble formulation investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Quarries | Captive feedstock supply insulates Kamenny Vek from Russian export duty volatility. |
| CE Marking Harmonization Investment | Accelerates German infrastructure tender qualification for roving and fabric grades. |
| Direct-Melt Furnace Technology Licensing | Chinese producers compress Indian entrant capital requirements through know-how transfer. |
| Long-Term Supply Agreement with Wind OEMs | Locks in volume commitments as blade lengths exceed 80-meter fatigue thresholds. |
| Biosoluble Formulation R&D Partnership | Positions European incumbents ahead of ECHA persistent fiber reclassification risk. |
Research Methodology
Document review covered customs trade filings, ECHA substance evaluation dossiers, and EU tender procurement databases, complemented by interviews with filament winding plant managers, wind turbine blade procurement leads, construction composite technical directors, and REACH compliance consultants. Secondary validation drew from MIIT industrial policy circulars, EPA emissions permitting records, and BIS standard development committee minutes. Bottom-up capacity assessments and top-down demand aggregation were cross-referenced for triangulation.
Historical capacity utilization patterns were cross-referenced against expert panel input on furnace technology adoption curves across the projection horizon. Segmentation modeling incorporated product type, processing technology, application performance tier, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity commissioning schedules. Industry-specific inputs included wind turbine blade length evolution trajectories and hydrogen storage tank qualification protocol timelines.
Geopolitical supply disruption, ECHA classification timeline acceleration, and energy input cost volatility are the dominant revision risks for forecast outputs. Forecasts reflect documented assumptions regarding REACH compliance cost pass-through and direct-melt technology diffusion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
E-Glass Fiber Market
Fibers
Thermoformed Fiber Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Artificial Muscle Fibers Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Viscose Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Dry-Molded Fibre Market
Fibers
Fiberglass Cloth Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
North America Glass Fiber Reinforced Gypsum Market