
 Metal Cutting Machine Market | 2026-2036
Metal Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Cutting Machine Market Intelligence
Aerospace procurement is consolidating as a primary demand pillar for precision metal cutting equipment. TRUMPF leverages its German engineering base to dominate high-power fiber laser installations for titanium airframe work. AMADA Co. Ltd. anchors Asian supply chains through extensive service networks and localized CNC production. DMG Mori Co., Ltd. competes on multi-axis machining centers that bridge milling and laser hybrid operations for complex aerostructures.
Metal cutting machines are powered equipment systems that sever metallic workpieces through thermal, mechanical, or electrical energy application, typically achieving tolerances from ±0.001 inches in laser systems to ±0.005 inches in plasma arc configurations, serving fundamental fabrication needs across discrete manufacturing. CNC Machines retain the largest installed base but Laser Cutters capture expanding margin pools as fiber source technology reduces operating costs for thin-to-medium gauge processing. Water Jet Cutters occupy specialized niches where heat-affected zones must be eliminated, particularly in aerospace superalloy and composite-metal stack cutting.
OSHA machine guarding standards and EPA National Emission Standards for Hazardous Air Pollutants shape equipment design requirements and facility compliance investments across American metalworking plants. CE marking under the EU Machinery Directive and REACH substance restrictions influence export specifications and material choices for cutting consumables. Stakeholders must monitor evolving carbon border adjustments and energy efficiency labeling schemes that will increasingly filter procurement decisions for capital-intensive cutting platforms.
Market Dynamics
Energy efficiency mandates from the EU Machinery Directive and EPA emissions standards are accelerating replacement cycles across metalworking facilities, compressing capital equipment lifecycles from fifteen years toward eight-year refresh horizons.
Growth Catalysts
- CE marking compliance deadlines:European manufacturers face mandatory machinery safety upgrades under evolving EU directives, forcing systematic replacement of legacy mechanical cutting platforms with guarded laser and water jet systems.
- Titanium airframe demand:Aerospace OEMs in Germany and Japan require tighter tolerances for next-generation aircraft programs, driving procurement of multi-axis CNC and hybrid laser-milling centers.
- China's eastern manufacturing corridor:Domestic shipbuilders and automotive stamping plants in Jiangsu and Zhejiang provinces are executing bulk fleet expansions of high-power fiber laser cutters.
Market Restraints
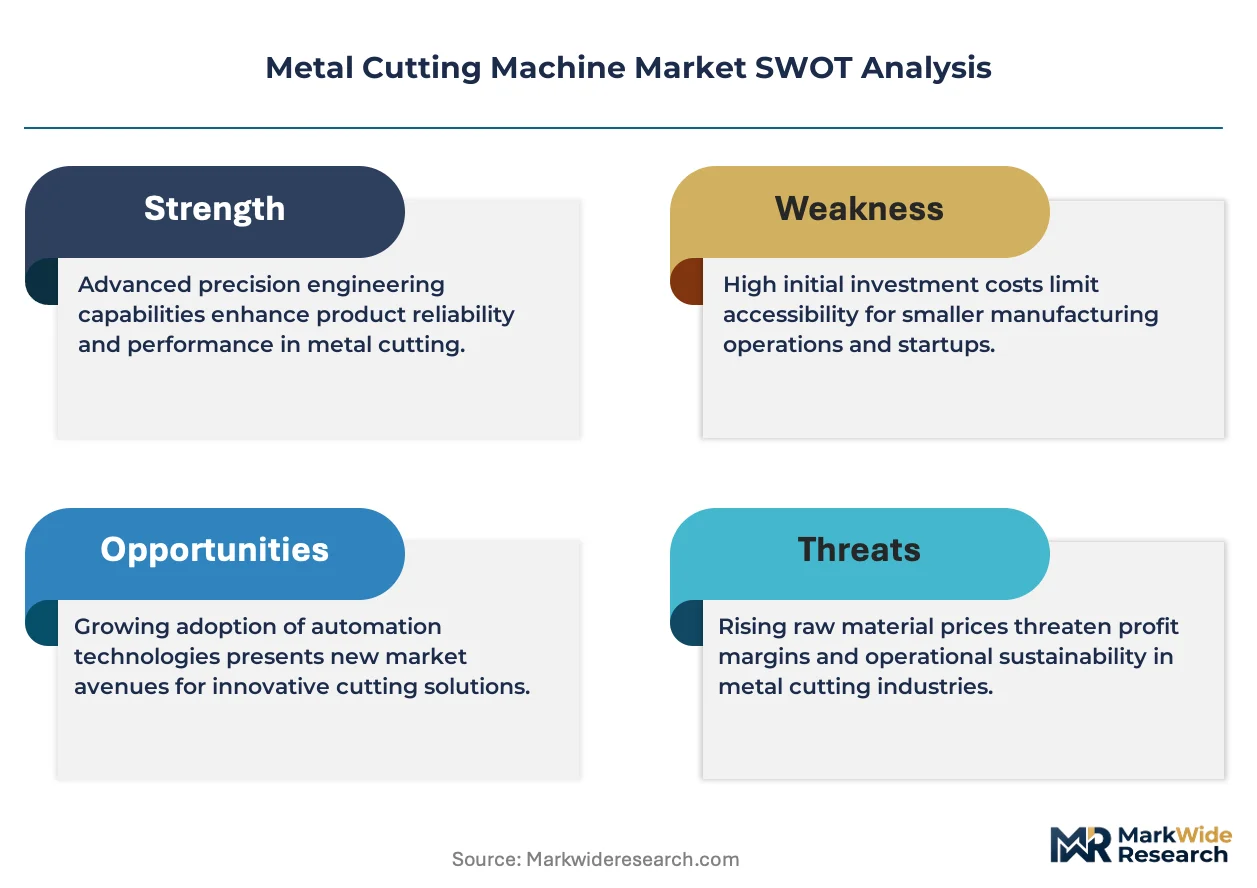
- Fiber laser source supply concentration:German and Japanese component suppliers control high-power resonator manufacturing, creating vulnerability for North American and Chinese system integrators.
- Skilled technician scarcity:Multi-axis programming and laser optics calibration require specialized labor pools that remain shallow in emerging manufacturing clusters.
- Plasma arc substitution ceiling:Thick-plate cutting above 25mm retains cost advantages for oxy-fuel and plasma systems, limiting fiber laser penetration in heavy fabrication.
Strategic Opportunities
- Indian PLI scheme for capital goods:Production-linked incentives for precision manufacturing equipment create localized assembly opportunities for mid-power laser and CNC platforms.
- Laser-waterjet hybrid convergence:Systems combining thermal cutting speed with abrasive waterjet finish quality address composite-metal stack applications in aerospace aftermarket repair.
- Equipment-as-a-service channels:Pay-per-cut and leased capacity models are penetrating job shop segments previously excluded by upfront capital barriers.
Industry Challenges
- CNC-laser integration complexity:Hybrid machining centers require synchronized control architectures that strain legacy shop floor IT infrastructure and maintenance protocols.
- REACH substance compliance:Cutting fluid formulations and abrasive garnet sourcing face evolving chemical registration requirements that disrupt consumables supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Cutting Machine Market |
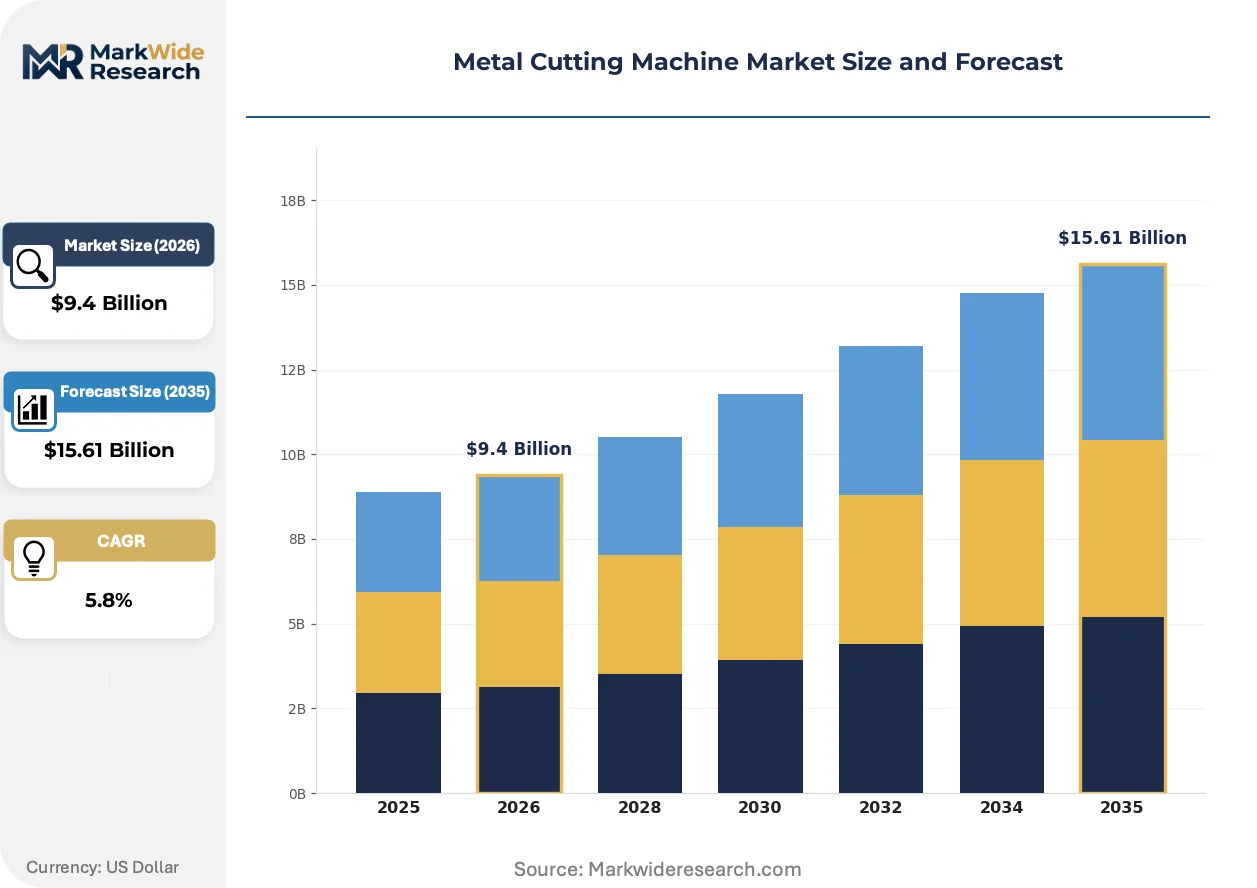
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $15.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Machines, Laser Cutters, Plasma Cutters, Water Jet Cutters Technology: Thermal Cutting, Mechanical Cutting, Electrical Discharge Machining, Ultrasonic Cutting End User: Aerospace, Automotive, Construction, Shipbuilding Application: Sheet Metal Fabrication, Parts Manufacturing, Prototyping, Repair Services |
| Companies Covered | TRUMPF, AMADA Co. Ltd., ESAB Corporation, DMG Mori Co., Ltd., Bystronic Laser AG, Lincoln Electric Company, Coherent Corp., Han's Laser Technology Industry Group Co., Ltd., Flow International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Cutting Machine Market Strategic Shifts & Innovations
Digital thread integration and AI-driven predictive maintenance are restructuring how cutting equipment generates value beyond the initial severing operation, shifting competitive differentiation toward uptime guarantees and process optimization.
Ultrafast picosecond fiber lasers are electrifying precision micro-machining applications in medical device and electronics packaging. Swiss and German medical OEMs are adopting these sources for stent and implant fabrication at accelerated qualification timelines. This technology is electrifying the margin structure of cutting equipment by commanding three to four times the service revenue of conventional systems through sealed optical path maintenance contracts.
EPA National Emission Standards for Hazardous Air Pollutants now mandate capture and filtration systems for metalworking particulate below five microns. American job shops must retrofit or replace open-bed plasma and oxy-fuel tables with enclosed cutting cells. High-volume structural steel processors in Texas and Ohio are absorbing the steepest compliance costs, accelerating consolidation toward larger integrated fabricators.
Outcome-based service contracts are displacing traditional break-fix maintenance arrangements across European automotive stamping networks. Tier-one suppliers now contract for guaranteed availability and per-part cutting costs rather than owning equipment outright. German and Czech automotive supply clusters exhibit the densest adoption of these performance-guarantee structures.
Metal Cutting Machine Market Segmentation
Metal cutting machine procurement patterns diverge sharply across product architectures, energy modalities, and end-use tolerances. Capital deployment decisions hinge on whether operations prioritize throughput velocity, geometric precision, or heat-affected zone elimination.
Product Type:
Laser cutters demand the steepest upfront capital outlays, with high-power fiber resonators and precision motion platforms driving acquisition costs well above mechanical alternatives.
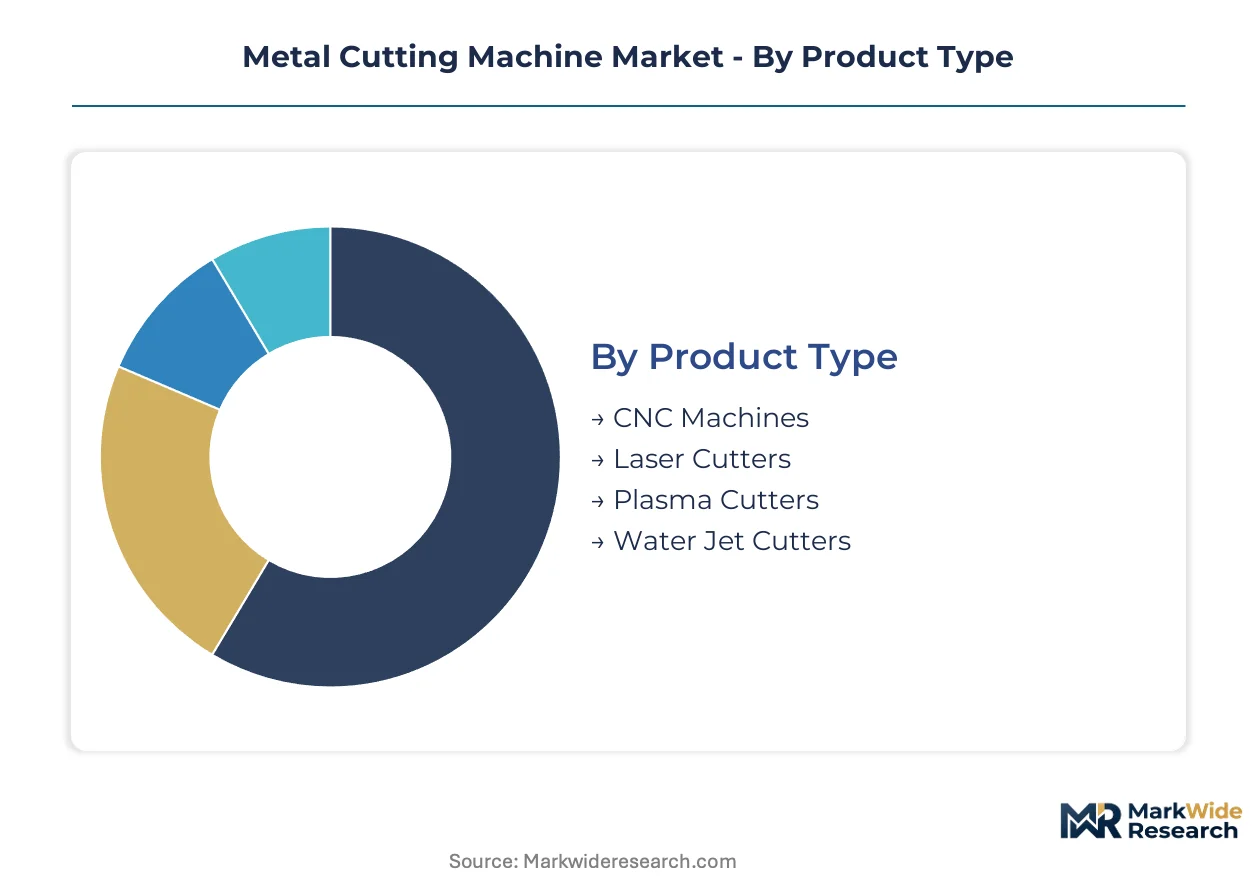
- CNC Machines:Computer-numerical control platforms deploy mechanical force through rotating cutting tools, achieving tolerances suitable for most subtractive operations. Aerospace OEMs in Germany and Japan anchor replacement demand as legacy three-axis fleets age out of compliance with tightened CE machinery safety directives.
- Laser Cutters:Fiber and CO2 sources concentrate photon energy for non-contact severing, with fiber technology slashing operating costs for thin-to-medium gauge processing. China's eastern manufacturing corridor—particularly Jiangsu and Zhejiang provinces—drives bulk fleet expansion among domestic shipbuilders and automotive stamping plants seeking speed advantages over plasma alternatives.
- Plasma Cutters:Electric arc ionization cuts electrically conductive metals at lower capital thresholds than laser systems. Heavy fabrication yards retain these platforms for thick-plate work above 25mm where thermal efficiency outweighs edge quality requirements.
- Water Jet Cutters:Abrasive garnet streams eliminate heat-affected zones entirely, serving aerospace superalloy and composite-metal stack applications where material integrity is paramount.
CNC machines absorb the bulk of installed capacity; laser cutters are expanding most quickly as fiber source economics improve.
Technology:
Thermal modalities dominate volume throughput, while non-thermal approaches command premium positioning in specialized tolerance bands.
- Thermal Cutting:Laser, plasma, and oxy-fuel processes apply concentrated heat to melt or vaporize metal. American structural steel processors in Texas and Ohio face steep retrofit costs under EPA National Emission Standards for Hazardous Air Pollutants, forcing enclosure upgrades or platform replacement.
- Mechanical Cutting:Shearing, sawing, and milling operations remove material through physical force application. Job shops serving construction and general fabrication rely on these systems for cost efficiency in low-tolerance batch work.
- Electrical Discharge Machining:Controlled spark erosion machines hardened conductive materials without mechanical stress. Tool-and-die manufacturers and medical device fabricators deploy wire and sinker EDM for intricate geometries in titanium and tungsten carbide.
- Ultrasonic Cutting:High-frequency mechanical vibration severs brittle or layered materials with minimal chipping. Emerging applications in carbon fiber composite trimming and ceramic substrate dicing are gaining traction among electronics packaging specialists.
Thermal cutting retains the deepest installed base; electrical discharge machining is climbing the fastest on precision medical and aerospace demand.
End User:
Aerospace and automotive segments drive specification intensity, while construction and shipbuilding prioritize throughput economics over geometric complexity.
- Aerospace:Tier-one suppliers and OEMs demand multi-axis hybrid systems combining laser speed with milling precision for titanium airframe components. German and Japanese manufacturers are consolidating procurement around TRUMPF and DMG Mori platforms capable of ±0.001 inch tolerances.
- Automotive:Stamping plants and body-in-white operations require high-volume sheet metal processing with rapid die changeover. European automotive networks—particularly German and Czech supply clusters—are shifting toward outcome-based service contracts guaranteeing availability and per-part cutting costs.
- Construction:Structural steel fabricators and metal building component suppliers utilize plasma and oxy-fuel systems for beam and plate processing. Compliance burdens from EPA particulate capture mandates are accelerating consolidation toward larger integrated operators.
- Shipbuilding:Korean and Chinese yards deploy gantry-mounted fiber laser systems for hull panel and bulkhead fabrication. The sector's thick-plate requirements sustain demand for high-power resonators above 10kW output.
Automotive absorbs the bulk of installed capacity; aerospace is gaining share fastest on next-generation aircraft program ramps.
Application:
Volume manufacturing and prototype development sit at opposite ends of the equipment specification spectrum, with repair services occupying a fragmented middle ground.
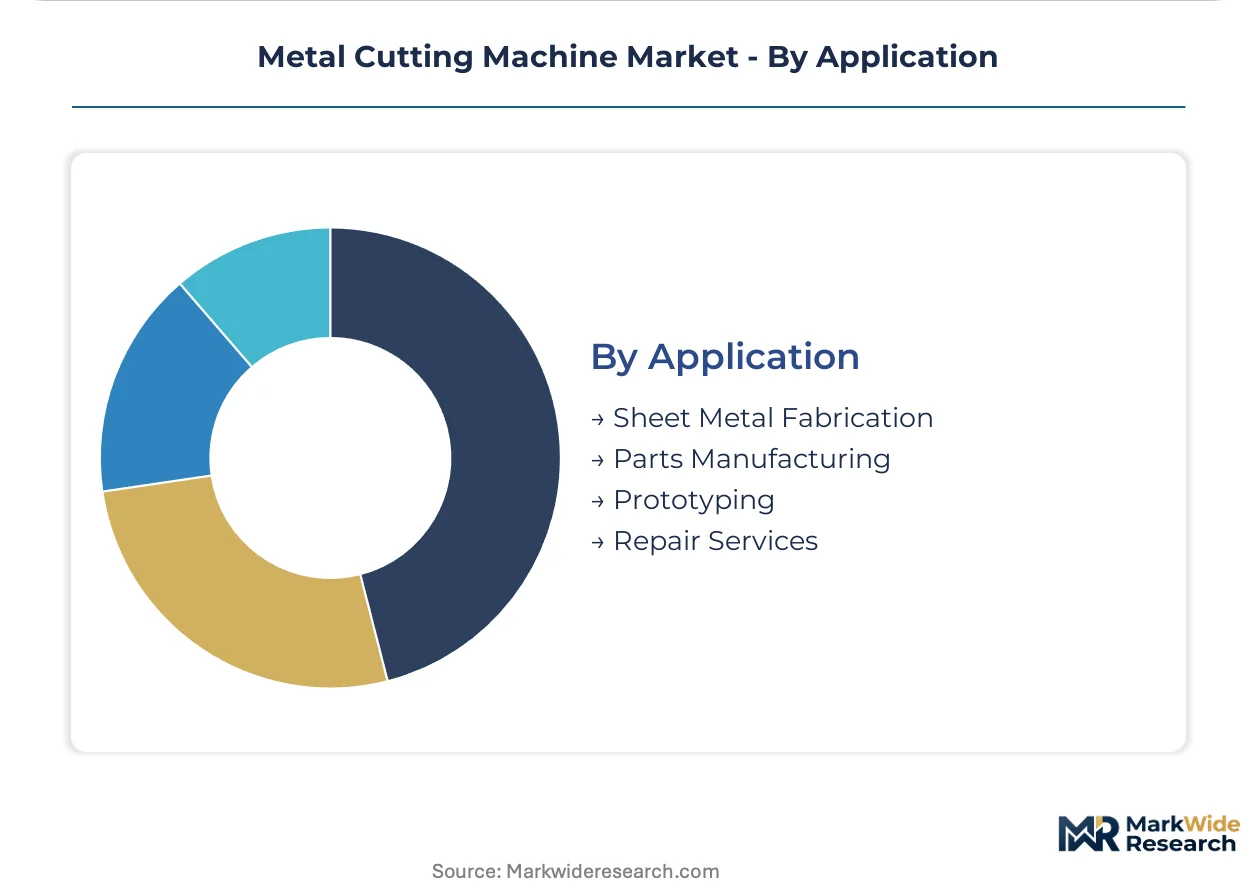
- Sheet Metal Fabrication:Flat stock processing for enclosures, chassis, and structural components constitutes the largest addressable volume. Job shops compete on nesting efficiency and rapid turnaround, favoring fiber laser platforms with automated material handling.
- Parts Manufacturing:Discrete component production for OEM supply chains demands repeatable precision and statistical process control. Swiss and German medical OEMs are qualifying ultrafast picosecond fiber lasers for stent and implant fabrication at accelerated timelines.
- Prototyping:Low-volume, high-mix operations require flexible programming and minimal setup overhead. Water jet systems serve this segment where material experimentation and heat-sensitive alloys predominate.
- Repair Services:Aftermarket maintenance of worn components and field-service cutting operations utilize portable plasma and abrasive water jet equipment. Laser-waterjet hybrid convergence is penetrating this niche for composite-metal stack restoration in aerospace MRO facilities.
Sheet metal fabrication commands the deepest equipment base; parts manufacturing is expanding most quickly on medical and aerospace qualification demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor functions as the dominant concentration zone, where Jiangsu and Zhejiang provinces anchor high-power fiber laser procurement for shipbuilding and automotive stamping operations.
China
Domestic shipbuilders and automotive stamping plants in Jiangsu and Zhejiang provinces drive bulk fleet expansions of high-power fiber laser cutters. The country's dual carbon goals under MEE accelerate replacement of energy-intensive mechanical platforms. Shanghai and Ningbo industrial zones concentrate gantry-mounted systems above 10kW output for hull panel fabrication.
Germany
Aerospace OEMs demand multi-axis hybrid systems for titanium airframe components with tightened tolerances. CE marking compliance under the EU Machinery Directive forces systematic replacement of legacy mechanical cutting platforms. Bavarian and Baden-Württemberg engineering clusters dominate high-power resonator integration for precision aerostructure work.
United States
Structural steel processors in Texas and Ohio absorb steep retrofit costs under EPA National Emission Standards for Hazardous Air Pollutants. OSHA machine guarding standards mandate capture and filtration systems for particulate below five microns. American job shops consolidate toward enclosed cutting cells and larger integrated fabricators to manage compliance burdens.
Japan
Aerospace manufacturers expand CNC machine fleets to meet tighter tolerances for next-generation aircraft programs. METI industrial policy supports precision manufacturing equipment upgrades through targeted incentive structures. Nagoya and Osaka industrial corridors concentrate hybrid laser-milling center deployments for complex aerostructure production.
India
The PLI scheme for capital goods creates localized assembly opportunities for mid-power laser and CNC platforms. BIS standards alignment pressures import-dependent system integrators toward domestic production partnerships. Gujarat and Maharashtra industrial zones attract precision manufacturing equipment investments for automotive and general fabrication segments.
Metal Cutting Machine Market Key Industry Players
Top-tier vendors anchor the premium precision tier, while mid-scale system integrators populate the volume fabrication segment. German and Japanese engineering houses dominate high-power fiber laser and multi-axis CNC architectures through captive optical and motion-control technologies. Strategic archetypes include full-stack platform builders, component-specialist integrators, and regional assembly partners. Competitive moves center on hybrid technology convergence and outcome-based service contract penetration.
Within the full-stack precision tier, TRUMPF and DMG Mori Co., Ltd. exemplify German-engineered platform dominance for aerospace-grade applications. AMADA Co., Ltd. occupies a position bridging Asian supply chain density with extensive localized service networks. These three entities represent distinct competitive vectors: optical source integration, multi-axis machining center hybridization, and regional service infrastructure scale.
| Leading Market Players |
|---|
| TRUMPF |
| AMADA Co. Ltd. |
| ESAB Corporation |
| DMG Mori Co., Ltd. |
| Bystronic Laser AG |
| Lincoln Electric Company |
| Coherent Corp. |
| Han's Laser Technology Industry Group Co., Ltd. |
| Flow International Corporation |
| Others |
Cost & Logistics Intelligence
Fiber source technology maturation simultaneously compresses operating costs for thin-gauge processing and concentrates optical component supply among German and Japanese resonator manufacturers. This dual effect reshapes procurement economics across the value chain, with buyers facing lower lifetime costs but higher vulnerability to upstream bottlenecks.
Pricing Analysis
Short lead-time premiums command substantial markups for high-power fiber resonators, while spot inventory of mid-power systems trades at discounted clearing rates. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade hybrid platforms from automotive stamping configurations and general fabrication job shop equipment. Pricing pressure stems from Chinese domestic laser source manufacturers capturing mid-power segments below 6kW output. Tier-one automotive suppliers exhibit lowest price sensitivity due to outcome-based contracting structures, whereas independent job shops face acute capital constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Chinese shipbuilders and German aerospace OEMs, while distributor networks serve fragmented job shop segments. Manufacturing concentration centers on Germany, Japan, and China for precision motion platforms and optical resonators. High-purity rare earth dopants for fiber lasers and precision ball screw assemblies draw from concentrated upstream sources. Single-source vulnerability in high-power resonator manufacturing creates structural risk for North American and European system integrators. Distribution runs through authorized service partners for installation and aftermarket support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-power fiber resonator manufacturing capacity constraints prop pricing power for incumbent optical source suppliers, sustaining margin structures despite downstream cost compression.
For Market Incumbents: Anchor defensive positioning through captive resonator manufacturing and CE marking compliance certification investments. German and Japanese engineering houses should deepen backward integration into precision motion control components to offset emerging Chinese laser source competition. Hybrid laser-milling center development represents the critical R&D lever for aerospace tier-one retention. For New Entrants and Emerging Players: Begin with mid-power fiber laser assembly partnerships under India's PLI scheme for capital goods, where BIS standards alignment creates localized procurement advantages. Equipment-as-a-service channels for job shop segments offer the most penetrable white-space, with pay-per-cut models bypassing upfront capital barriers. Target automotive aftermarket repair facilities with laser-waterjet hybrid systems for composite-metal stack applications. For Investors and Strategic Acquirers: Re-rating potential sits with precision motion control specialists given aerospace tolerance tightening and multi-axis hybrid platform demand. Long-term viability favors component-specialist integrators with captive optical or motion technologies rather than pure assembly operations. Monitor Chinese domestic resonator qualification timelines as the critical inflection signal for pricing power erosion in mid-power segments.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Convergence | Laser-milling center integration addresses titanium airframe tolerance requirements from German and Japanese OEMs. |
| Outcome-Based Service Contracts | Guaranteed availability structures penetrate European automotive stamping networks in German and Czech supply clusters. |
| Localized Assembly Partnerships | India PLI scheme alignment enables mid-power laser production for Gujarat and Maharashtra industrial zones. |
| Resonator Manufacturing Scale-Up | Captive high-power fiber source production defends against Chinese import substitution in 10kW+ output segments. |
| CE Marking Compliance Investment | Machinery safety directive adherence secures European aerospace and automotive OEM procurement eligibility. |
Research Approach
Document review covered trade customs data, SEC filings from publicly traded equipment manufacturers, and EU Machinery Directive compliance databases, complemented by interviews with plant engineers at German aerospace OEMs, procurement leads at Chinese shipbuilders, aftermarket service heads at Japanese distributors, and maintenance directors at American structural steel processors. Secondary validation drew from EPA National Emission Standards enforcement records, METI industrial policy disclosures, and BIS standards documentation. Bottom-up installation base modeling and top-down capital expenditure triangulation anchored volume and value estimates.
Installed base projections and replacement cycle analysis across the modeling period incorporated energy modality segmentation, end-use tolerance requirements, and regional regulatory compliance clusters. CAGRs derived from fitted adoption curves for fiber laser technology penetration and mechanical platform retirement rates. Industry-specific inputs included CE marking compliance deadline impacts, EPA retrofit cost absorption capacity, and Chinese dual carbon policy enforcement intensity.
Underlying measurement precision varies by segment; aerospace and automotive end-use data carry tighter precision than fragmented job shop estimates due to consolidated buyer concentration. Forecasts reflect assumptions regarding regulatory enforcement continuity, resonator supply expansion timelines, and skilled technician availability in emerging manufacturing clusters. Periodic stress-testing of base assumptions is recommended against observed Chinese domestic laser source market share progression and EU carbon border adjustment implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Painting Tools Market
Tools
Sand Control Tools Market
Tools
Grabber Pole Market
Tools
Foam Cutting Machine Market
Tools
Bi-Metal Band Saw Blade Market
Tools
GCC Machine Tools Market
Tools
Thread Milling Machine Market
Tools
Edge Banding Machine Market
Tools
Bottle Jack Market
Tools
Structural Wood Screws Market
Tools
Key Cutting Machine Market
Tools
Fastening Power Tools Market
Tools
Woodworking CNC Tools Market
Tools
Deburring Tool Market
Tools
Water Pump Pliers Market
Tools
Woodcarving Tool Market