
 Water Pump Pliers Market | 2026-2036
Water Pump Pliers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Pump Pliers Market Analytics
Consolidation among multi-trade facility maintenance contractors is repositioning procurement patterns toward bulk-purchase agreements with specialized distributors. Knipex leverages its forged chrome-vanadium steel expertise to command premium positioning in industrial plumbing channels. Channellock sustains domestic manufacturing scale from its Pennsylvania operations, anchoring supply reliability for North American utility fleets. Bahco competes through ergonomic handle innovations that reduce repetitive-strain claims among professional users.
Water pump pliers are adjustable gripping tools with serrated jaws and a sliding pivot mechanism, typically forged from chrome-vanadium or carbon steel alloys to deliver torque multiplication on hexagonal and rounded fasteners in confined mechanical spaces. Their primary purpose spans pipe fitting, plumbing assembly, and automotive cooling system service where conventional open-end wrenches cannot engage. Adjustable pliers generate the dominant revenue share due to versatility across trade applications, while stainless steel variants command margin premiums in marine and food-processing environments where corrosion resistance is mandatory. Rubber grip handles now outsell bare steel configurations in professional channels as OSHA-aligned ergonomics requirements tighten.
ISO 5743 governs jaw geometry and load ratings for adjustable wrenches and pliers in international commerce, while Germany's KBA-referenced tool safety standards and the EU's REACH chemical restrictions on plating substances constrain material choices for European manufacturers. The US OSHA hand-tool safety guidelines influence corporate purchasing specifications for insulated handle variants in electrical applications. Stakeholders must monitor evolving alloy sourcing costs and ergonomic certification requirements as trade labor shortages intensify specification bargaining power.
Market Dynamics
Copper-to-PEX piping transitions across North American residential construction are compressing tool replacement cycles and elevating demand for adjustable gripping tools with expanded jaw capacity ranges.
Growth Catalysts
- REACH-compliant chrome-vanadium standards:Germany's material specifications are elevating quality benchmarks across European supply chains, forcing upgrades that benefit premium forged tool manufacturers.
- Utility fleet standardization:North American electrical and water utilities are consolidating vendor lists around OSHA-aligned insulated handle variants for field technician safety compliance.
- Infrastructure maintenance expansion:China's eastern manufacturing belt is directing municipal budgets toward mechanical system upkeep, creating sustained replacement demand for corrosion-resistant gripping tools.
Market Restraints
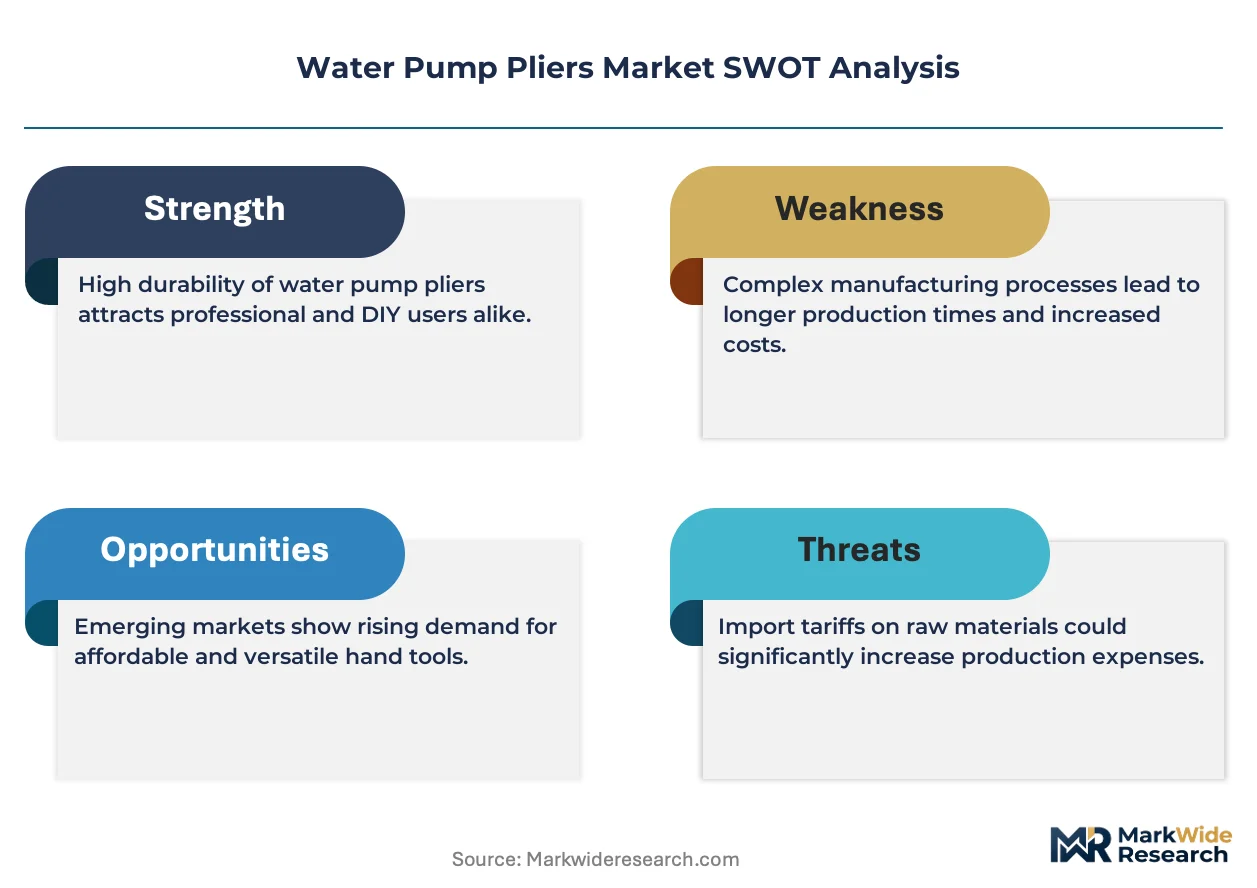
- Alloy cost volatility:Chrome-vanadium and carbon steel input prices fluctuate with energy-intensive smelting operations, compressing margin stability for forged tool producers.
- Supply concentration in Pennsylvania:Domestic North American scale manufacturing clusters in a single state create weather and logistics vulnerability for utility fleet procurement.
- Power tool substitution:Cordless impact drivers with socket adapters are displacing manual torque applications in automotive cooling system service bays.
Strategic Opportunities
- Marine and food-processing stainless variants:Corrosion-resistant configurations command premium positioning in coastal maintenance and hygienic processing environments where plating degradation is unacceptable.
- Ergonomic certification tailwinds:OSHA hand-tool safety guidelines are tightening corporate purchasing specifications for rubber grip handles that reduce repetitive-strain claims.
- Multi-trade facility maintenance consolidation:Bulk-purchase agreements with specialized distributors are repositioning procurement patterns away from fragmented retail channels.
Industry Challenges
- Forging technician skill scarcity:Heat-treatment and die-craft expertise required for chrome-vanadium precision is concentrating among aging workforce cohorts in German and Japanese manufacturing clusters.
- ISO 5743 compliance timelines:Jaw geometry and load rating certification delays are extending product launch cycles for adjustable mechanism redesigns targeting international commerce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Pump Pliers Market |
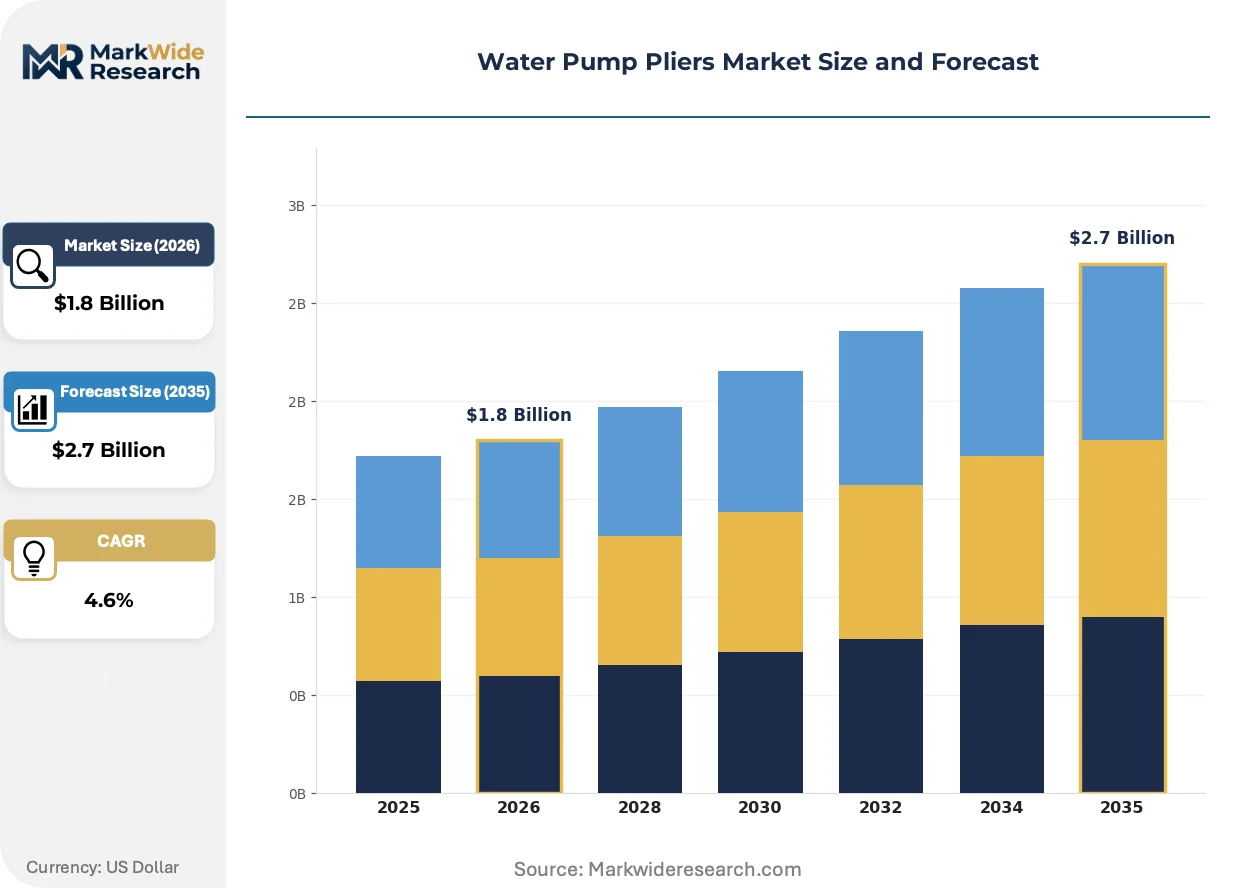
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pliers, Adjustable Pliers, Mini Pliers, Locking Pliers Material: Steel, Carbon Steel, Stainless Steel, Aluminum Handle Type: Rubber Grip, Plastic Handle, Steel Handle, Insulated Handle Application: Plumbing, Automotive, Construction, Electrical |
| Companies Covered | Knipex, Bahco, Channellock, Rothenberger, Stanley, Bosch, Klein Tools, Irwin Tools, Facom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Pump Pliers Market Evolving Landscape
Tool specification is converging around ergonomic performance metrics and material traceability as professional channels harden purchasing requirements.
Composite handle materials with integrated vibration damping are unifying grip comfort with torque feedback precision. Plumbing contractors in Germany and Japan are specifying these configurations for daily-use tools. This convergence is compressing the addressable market for bare steel handles while expanding certified ergonomic product lines.
EU REACH chemical restrictions on plating substances are constraining surface treatment choices for European manufacturers. Chrome alternatives including ceramic-based coatings are gaining qualification for food-contact and marine applications. German tool producers are responding with in-house electroplating process controls that document substance compliance.
Corporate purchasing departments are consolidating vendor relationships around documented ergonomic outcomes. Facility maintenance contractors are displacing open retail procurement with multi-year supply agreements that bundle tool replacement with injury-rate guarantees. This behavior is most visible in North American utility and municipal fleet operations.
Water Pump Pliers Market Segmentation
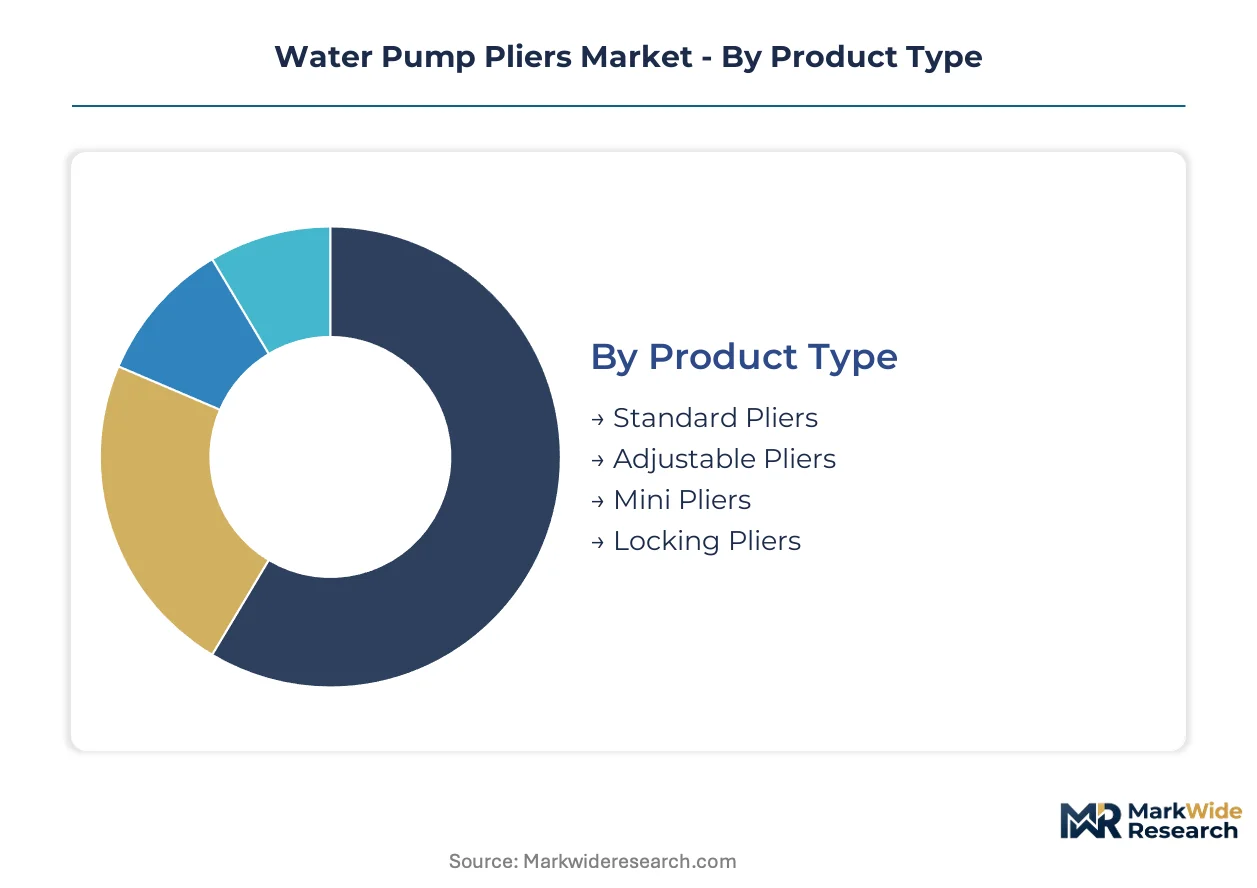
Water pump pliers segmentation reveals how tool specification tracks distinct procurement channels. Professional plumbing contractors prioritize adjustable mechanisms and ergonomic certification, while industrial maintenance fleets demand material traceability and insulated safety variants.
Product Type:
Standalone hand tools dominate professional tool belts, while embedded gripping systems integrate into specialized maintenance rigs.
- Adjustable Pliers:Sliding pivot mechanisms expand jaw capacity across fastener sizes, accommodating copper-to-PEX piping transitions in North American residential construction. Plumbing contractors specify these for daily-use versatility that reduces carried inventory.
- Standard Pliers:Fixed-jaw configurations deliver torque precision for repetitive assembly tasks where fastener sizing is uniform. German automotive cooling system bays specify these for consistent hexagonal engagement.
- Mini Pliers:Compact 150-200mm lengths access confined mechanical spaces in appliance repair and electronics assembly.
- Locking Pliers:Self-locking jaw mechanisms maintain clamping pressure without continuous hand force, specified for welding prep and pipe holding.
Adjustable pliers lead volumes today; locking pliers are gaining share fastest in industrial maintenance consolidation.
Material:
Cost tiers separate commodity carbon steel from premium corrosion-resistant alloys.
- Chrome-Vanadium Steel:Heat-treated forged alloys meet Germany's REACH-compliant specifications for load rating and durability. European supply chains are elevating procurement requirements around these material benchmarks.
- Stainless Steel:Corrosion-resistant configurations command premium positioning in marine environments and food-processing facilities where plating degradation violates hygiene protocols. China's eastern manufacturing belt is expanding municipal infrastructure maintenance budgets toward these variants.
- Carbon Steel:Lower-alloy compositions serve price-sensitive retail channels and occasional-use consumer segments.
- Aluminum:Lightweight forged bodies reduce technician fatigue in overhead electrical work and extended-reach applications.
Chrome-vanadium steel leads volumes today; stainless steel is climbing the fastest on regulatory tightening in processing industries.
Handle Type:
Application environments dictate ergonomic certification requirements and electrical safety specifications.
- Rubber Grip:Thermoplastic elastomer overmolds dampen vibration and reduce repetitive-strain claims. OSHA-aligned corporate purchasing specifications are displacing bare steel configurations in North American professional channels.
- Insulated Handle:Dielectric-rated materials protect against accidental electrical contact in utility fleet operations. US OSHA hand-tool safety guidelines drive standardization around 1000V-rated variants for field technician compliance.
- Plastic Handle:Glass-reinforced polymer housings balance cost and grip security in construction trades.
- Steel Handle:Bare forged bodies persist in price-competitive retail and developing-market procurement where ergonomic certification carries no premium.
Rubber grip handles lead volumes today; insulated variants are expanding most quickly on utility fleet safety mandates.
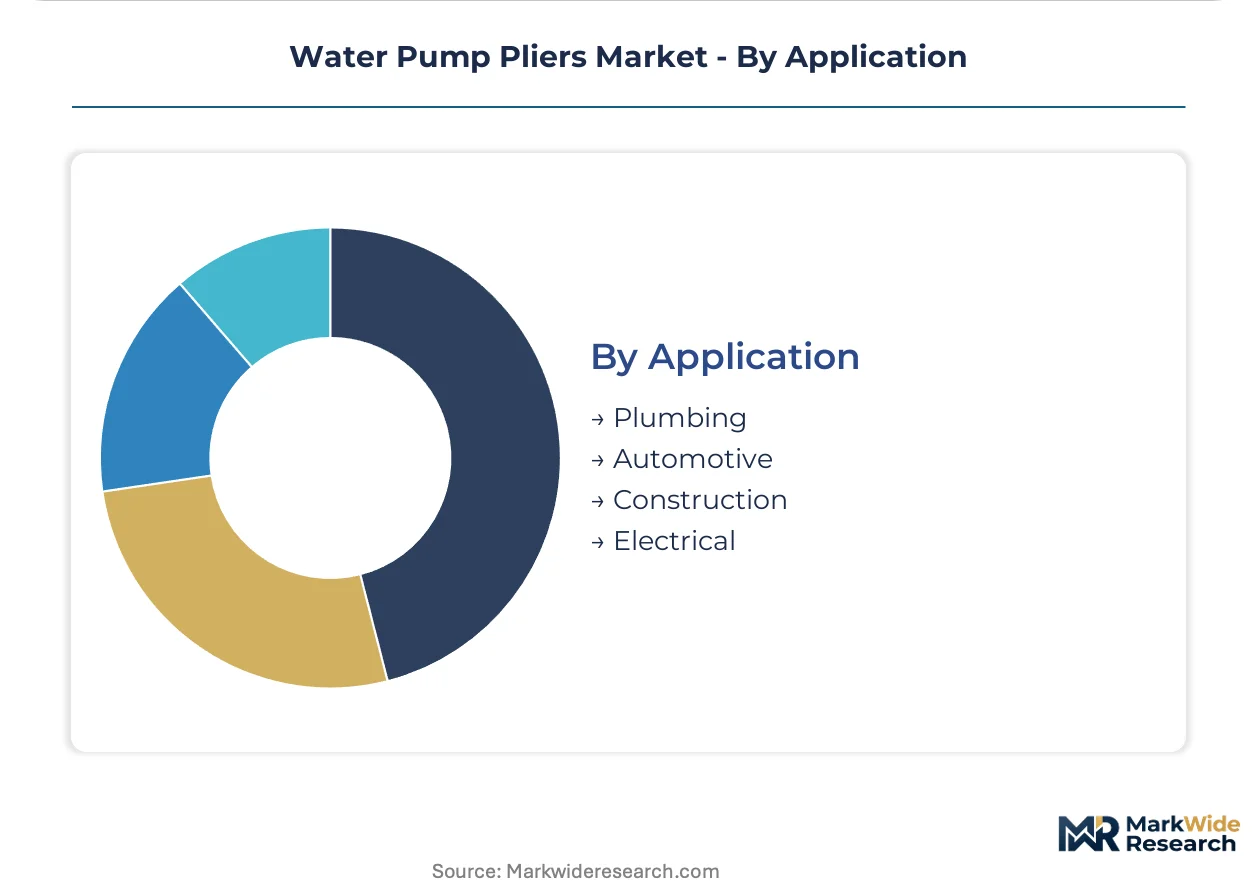
Application:
Customer type separates fragmented retail procurement from consolidated corporate vendor relationships.
- Plumbing:Pipe fitting and assembly tasks drive replacement demand as copper-to-PEX transitions accelerate tool refresh cycles. Multi-trade facility maintenance contractors are consolidating bulk-purchase agreements around specialized distributors.
- Automotive:Cooling system service and hose clamp work specify corrosion-resistant finishes against glycol exposure. Cordless impact drivers with socket adapters are displacing manual torque applications in high-volume service bays.
- Construction:General mechanical assembly and temporary fastening tasks prioritize durability under jobsite abuse.
- Electrical:Insulated tool requirements dominate utility and commercial contractor specifications where arc-flash protection is mandatory.
Plumbing leads volumes today; electrical applications are gaining share fastest on safety standardization across utility fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German forging technician expertise anchors premium tool production capacity, while Chinese municipal infrastructure budgets and US utility fleet standardization create distributed demand centers across three continents.
United States
OSHA hand-tool safety guidelines drive insulated handle procurement across electrical utility fleets and municipal water departments. Pennsylvania hosts concentrated domestic forging operations serving North American utility standardization programs. Copper-to-PEX piping transitions in residential construction compress replacement cycles for adjustable gripping tools.
Germany
REACH chemical restrictions and KBA-referenced tool safety standards elevate chrome-vanadium material specifications across European supply chains. Heat-treatment expertise concentrates in Solingen and Remscheid industrial clusters where precision forging traditions support premium positioning. Automotive cooling system bays specify fixed-jaw configurations for consistent hexagonal engagement.
China
Eastern manufacturing belt municipal budgets direct infrastructure maintenance spending toward corrosion-resistant tool variants. SAMR standards alignment and dual carbon goals shape smelting energy intensity for alloy production. Yangtze River Delta fabrication clusters scale output for domestic replacement demand and export qualification.
Japan
METI industrial standards and aging workforce demographics intensify ergonomic certification requirements for professional channels. JIS-compliant precision forging concentrates in Chubu and Kansai manufacturing regions. Electronics assembly and appliance repair sectors specify mini plier configurations for confined mechanical spaces.
India
BIS quality benchmarks and PLI scheme incentives for capital goods manufacturing reshape import substitution dynamics. Maharashtra and Gujarat industrial corridors host emerging forging capacity serving construction and plumbing trades. Price-competitive carbon steel variants dominate retail channels where ergonomic certification carries limited premium.
Water Pump Pliers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Premium forged tool manufacturers command industrial plumbing and utility channels through material certification and ergonomic compliance. Mid-scale regional fabricators serve price-sensitive construction trades with standard carbon steel configurations. Strategic moves concentrate on bulk-purchase agreement capture with multi-trade facility maintenance contractors and die-craft skill retention through apprentice programs.
Among German precision forging specialists, Knipex and Bahco occupy positions exemplifying premium-tier chrome-vanadium expertise and ergonomic innovation respectively. Channellock anchors North American scale manufacturing from its Pennsylvania base, representing domestic supply reliability for utility fleet procurement. These three entities illustrate how geographic forging traditions translate into distinct channel positioning across OSHA-aligned, REACH-compliant, and cost-optimized market segments.
| Leading Market Players |
|---|
| Knipex |
| Bahco |
| Channellock |
| Rothenberger |
| Stanley |
| Bosch |
| Klein Tools |
| Irwin Tools |
| Facom |
| Others |
Value Network & Pricing Analysis
Multi-trade facility maintenance contractors concentrate procurement volume through bulk-purchase agreements, anchoring pricing power around bundled multi-year supply contracts with injury-rate guarantees rather than transactional spot purchases.
Pricing Analysis
Bundled service contracts that wrap tool replacement with ergonomic certification documentation command premium positioning against unbundled transactional sales through retail channels. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant chrome-vanadium forged tools from carbon steel commodity variants and bare steel retail configurations. Pricing pressure stems from alloy cost volatility in energy-intensive smelting operations, compressing margin stability for forged producers. Carbon steel retail channels exhibit highest price sensitivity, while insulated handle variants for utility fleets show lowest sensitivity due to OSHA compliance mandates.
Supply Chain Analysis
Certification gating through ISO 5743 jaw geometry standards and REACH chemical restrictions constrains supplier qualification, elevating forging expertise concentration in Germany, Japan, and Pennsylvania as primary supply nodes. Raw material flows draw from chrome-vanadium and carbon steel alloy producers, rubber grip thermoplastic elastomer compounders, and dielectric-rated insulation material specialists. Single-source vulnerability concentrates in Pennsylvania's domestic forging cluster, exposing utility fleet procurement to weather and logistics disruption. Distribution runs through specialized industrial distributors serving multi-trade contractors, displacing fragmented retail channels in professional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where OSHA hand-tool safety guideline tightening and REACH chemical restrictions continuously elevate specification floors, converting compliance investments into durable competitive moats.
For Market Incumbents: Lock in die-craft skill retention through apprentice programs anchored in Solingen and Remscheid industrial clusters, defending against forging technician scarcity that threatens precision heat-treatment capacity. Deepen backward integration into chrome-vanadium alloy sourcing to buffer margin compression from smelting energy cost volatility. Capture multi-trade facility maintenance contractors through multi-year bulk agreements that bundle tool replacement with documented ergonomic outcomes.
For New Entrants and Emerging Players: Specialized distributors serving North American electrical utility fleets represent the most accessible channel entry point, given consolidated vendor list standardization around OSHA-aligned insulated handle variants. Target stainless steel marine and food-processing variants where corrosion-resistant specifications command premium positioning and incumbent qualification timelines create white space. Pursue qualification under EU REACH ceramic-based coating pathways as chrome plating alternatives gain regulatory traction.
For Investors and Strategic Acquirers: Diversified industrial tool conglomerates are the most active acquirers in this space, seeking precision forging capabilities to fill portfolio gaps in professional plumbing and utility channels. Mid-scale German and Japanese forging specialists with documented ergonomic certification pipelines represent prime acquisition targets over a five-to-ten year consolidation horizon. Monitor alloy smelting energy cost trajectories as the critical inflection signal for margin compression severity and forced exit dynamics among carbon steel-dependent regional fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Apprentice Program Expansion | Solingen forging clusters secure die-craft expertise against aging workforce attrition. |
| REACH-Compliant Coating Investment | Ceramic-based surface treatments qualify for food-contact and marine regulatory pathways. |
| Multi-Year Supply Agreement | Facility maintenance contractors bundle tool replacement with injury-rate guarantees. |
| Insulated Handle Certification | OSHA-aligned 1000V-rated variants capture utility fleet standardization mandates. |
| Stainless Steel Variant Launch | Corrosion-resistant configurations penetrate coastal maintenance and hygienic processing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plumbing contractors, utility fleet procurement officers, industrial distributor category managers, and forging plant operations directors with secondary validation against customs trade records, SEC tool manufacturer filings, OSHA regulatory guidance documents, and EU REACH substance restriction databases. Bottom-up channel volume estimates and top-down alloy consumption analysis triangulated market sizing across the analysis window.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns observed through copper-to-PEX piping transitions and ergonomic certification adoption curves. The analytical framework modeled segmentation across product type, material grade, handle configuration, and application vertical, with CAGRs derived from trade flow momentum and procurement budget trajectories. Chrome-vanadium alloy cost indices and utility fleet standardization program timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to smelting energy intensity regulations and forging workforce demographic shifts. Projections reflect documented assumptions regarding OSHA guideline enforcement timing and REACH chemical restriction expansion scope. A model refresh is warranted upon material change in alloy sourcing cost structures or ergonomic certification mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Standard Parts for Tool Making Market
Tools
Pneumatic Bolting Tools Market
Tools
Hydraulic Tools and Equipment Market
Tools
Drill Presses Market
Tools
Parting-Off Blades Market
Tools
Global Cutting Discs Market
Tools
Lathe Machines Market
Tools
Cordless Power Drill Market
Tools
Auger Drill Bits Market
Tools
Woodworking CNC Tools Market
Tools
Machine Tools Market
Tools
Orbital Recip Saw Market
Tools
Bandsaw Machines Market
Tools
Gear Cutting Machines Market
Tools
Fastening Power Tools Market
Tools
Asia Pacific Power Tools & Hand Tools Market