
 Fastening Power Tools Market | 2026-2036
Fastening Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Fastening Power Tools Market Foresight
Equipment leasing and pay-per-use rental models is fragmenting capital requirements across the fastening power tools competitive landscape. Bosch leverages its in-house battery platform to sustain cordless technology leadership across European job sites. Makita anchors its position through manufacturing scale in Japan and Southeast Asia. Hilti differentiates via direct sales channel control and fleet management services that lock in contractor loyalty.
Fastening power tools are motorized devices designed to apply controlled torque for inserting or removing threaded and non-threaded fasteners, typically operating within torque ranges from 2 Nm for precision electronics assembly to over 3,000 Nm for heavy structural bolting in steel construction. These tools incorporate clutch mechanisms, torque sensors, or impact mechanisms to prevent material damage while ensuring joint integrity in production and field environments. Cordless technology leads product type momentum as lithium-ion battery energy density improvements enable runtime parity with corded alternatives across drilling and driving applications. Pneumatic systems retain share in high-volume automotive assembly where compressed air infrastructure already exists, though cordless displacement is accelerating in metalworking segments. Construction end users generate the largest revenue pool, with woodworking representing a concentrated margin segment for premium brushless motor configurations.
OSHA workplace safety standards and the EPA energy efficiency directives shape product design requirements for noise reduction and battery recycling compliance in the United States. The EU Green Deal and REACH chemical regulations are forcing material substitutions in battery packs and housings across European markets. ISO 5393 and IEC 62841 standards govern torque accuracy and mechanical safety testing protocols that determine market access eligibility. Stakeholders must monitor battery chemistry transitions and regulatory harmonization gaps between North American and European certification regimes to anticipate compliance cost shifts.
Market Dynamics
Cordless lithium-ion platforms are compressing pneumatic system share as OSHA silica dust enforcement tightens and contractors prioritize jobsite mobility over fixed air infrastructure. This technology transition is redistributing value capture toward battery and motor suppliers while eroding traditional compressor-dependent service revenues.
Growth Catalysts
- OSHA Silica Dust Rules:Compressed air systems face escalating compliance costs for dust containment, pushing residential builders toward sealed cordless alternatives that eliminate exhaust particulates.
- Brushless Motor Efficiency:Electronics assembly lines in Germany and Japan are specifying precision torque tools with sensor-feedback clutches to reduce joint failure rates in electric vehicle battery enclosures.
- China Infrastructure Scale:Domestic procurement policies for high-speed rail and urban transit projects are concentrating demand for 1,000+ Nm torque wrenches within local manufacturing supply chains.
Market Restraints
- Lithium Supply Concentration:Battery cell production for tool packs depends on cathode material refining concentrated in China, exposing OEMs to export quota volatility and forced technology transfer requirements.
- Pneumatic Infrastructure Lock-In:Automotive assembly plants in the US Midwest retain sunk-cost compressed air networks that delay cordless conversion despite superior total cost of ownership.
- REACH Chemical Substitution:EU regulations on cobalt and nickel compounds in battery electrodes are forcing reformulation cycles that extend R&D timelines by 18-24 months for European tool manufacturers.
Strategic Opportunities
- India Construction Formalization:The country's PLI scheme for power tool manufacturing is attracting component suppliers to Gujarat and Tamil Nadu industrial corridors ahead of anticipated residential building code enforcement.
- Battery-as-a-Service Models:Fleet management platforms are emerging in Germany where contractors pay per fastening operation rather than capitalizing tool assets, shifting revenue to recurring service streams.
- 5G-Enabled Torque Monitoring:Integration of cellular connectivity with cloud-based joint documentation is creating new specification requirements for critical infrastructure projects in Japan and South Korea.
Industry Challenges
- Certification Timeline Compression:IEC 62841 safety testing protocols for cordless tools require 14-18 months for full approval, lagging behind product development cycles and delaying market entry.
- Technician Skill Polarization:Advanced brushless diagnostics and battery management systems demand electronics troubleshooting capabilities that traditional mechanical tool repair networks lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fastening Power Tools Market |
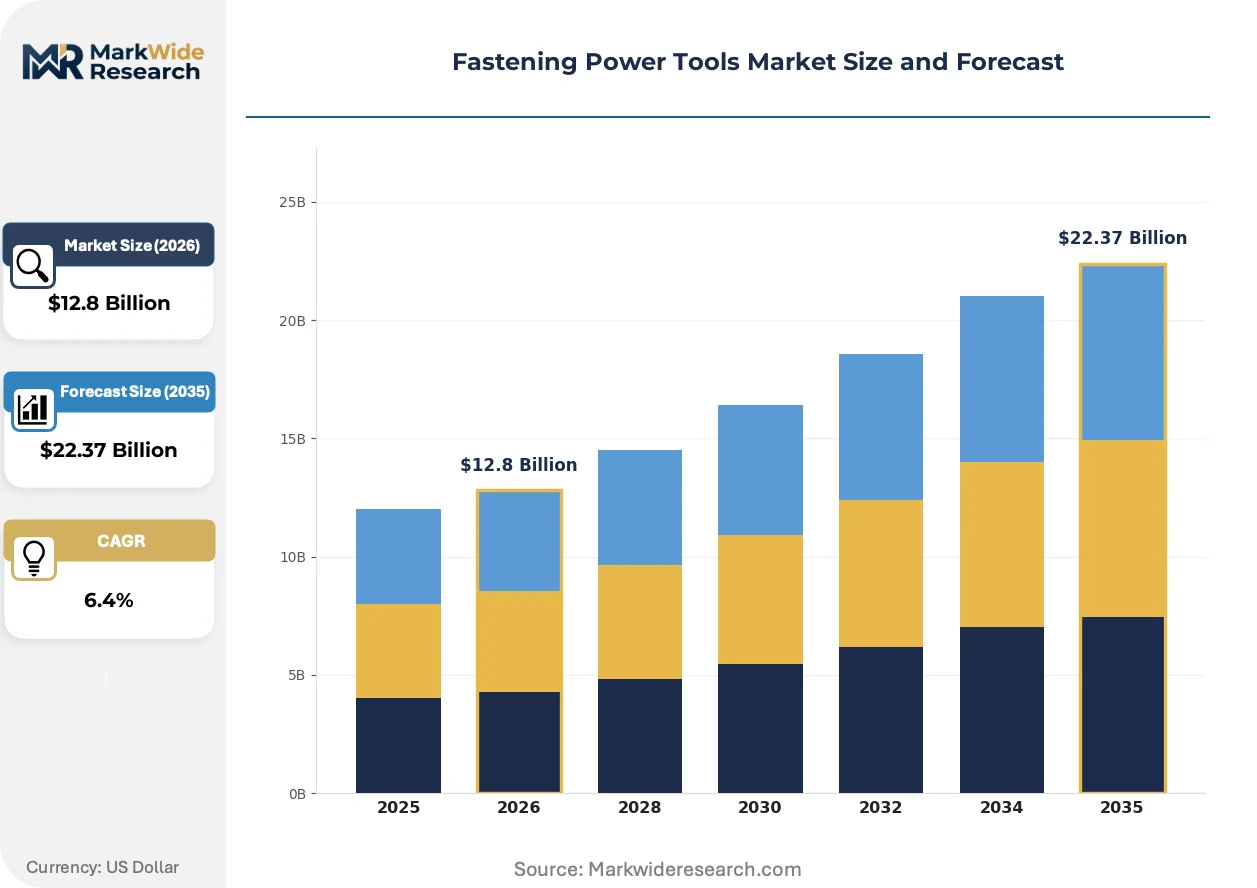
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Screwdrivers, Nail Guns, Wrenches Technology: Cordless, Corded, Pneumatic, Hydraulic End User: Construction, Automotive, Woodworking, Metalworking Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Stanley Black & Decker, Bosch, Makita, Hilti, Techtronic Industries, Hitachi Koki, DeWalt, FEIN, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fastening Power Tools Market Shifts & Advancements
Intelligent fastening systems are converging sensor hardware, connectivity protocols, and predictive analytics to transform tools from commodity equipment into data-generating assets. This shift is redefining competitive advantage around software integration and fleet intelligence rather than torque specifications alone.
Brushless DC motor technology is hybridizing with precision torque sensors and Bluetooth-enabled data logging to create tools that automatically document every fastening operation for quality traceability. Automotive OEMs in Germany and Japan are specifying these connected systems for electric vehicle battery pack assembly where joint failure carries catastrophic liability. The technology is compressing the market for standalone torque testers and manual documentation workflows.
REACH chemical regulations in the European Union are mandating cobalt reduction in lithium-ion battery cathodes, forcing cell suppliers to accelerate nickel-manganese-aluminum formulations. Tool manufacturers serving EU markets must redesign battery pack thermal management to accommodate higher-nickel chemistries that present elevated fire risk during fast-charging cycles. This regulatory pressure is most acute for premium professional brands targeting German automotive and aerospace contractors.
Equipment-as-a-service contracting is displacing outright purchase models among mid-sized US construction firms seeking to convert fixed capital to operating expenditure. Hilti's direct sales organization and Bosch's service partner networks are capturing this demand through bundled maintenance and guaranteed uptime agreements. The shift is most visible in California and Texas where volatile project pipelines make balance sheet flexibility a priority for general contractors bidding on infrastructure megaprojects.
Fastening Power Tools Market Segmentation
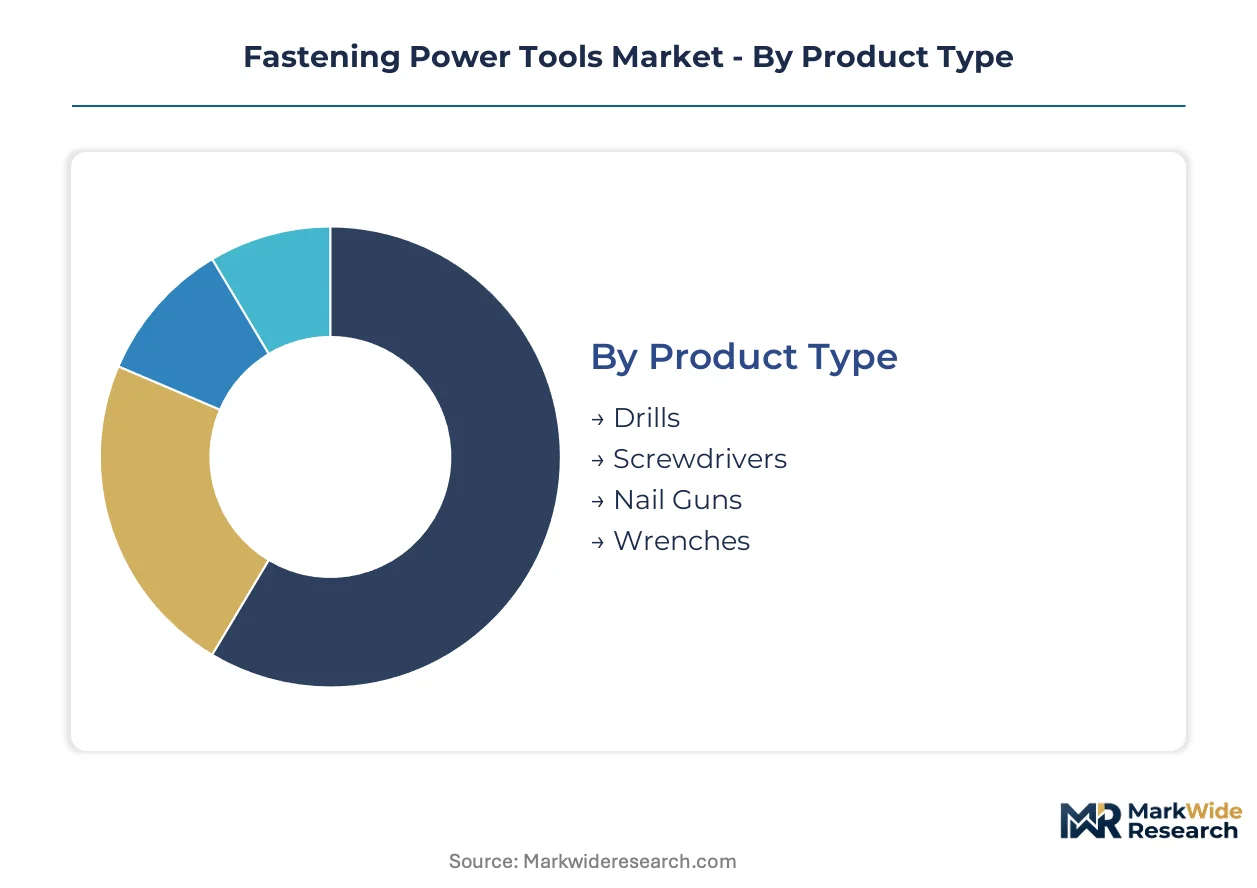
Fastening power tools fragment across four dimensions that determine replacement cycles, margin capture, and channel economics. Product type and technology choices drive capital intensity, while end-user concentration shapes geographic demand patterns and distribution strategies.
Product Type:
Replacement velocity varies sharply by product category, with high-frequency-use tools cycling fastest and precision instruments enduring longest in service fleets.
- Drills:Multi-function drilling and driving platforms dominate residential construction procurement with torque ranges spanning 20-80 Nm for general carpentry. German and Japanese contractors specify brushless motor variants for concrete and masonry applications where runtime reliability determines labor productivity.
- Screwdrivers:Precision torque tools with clutch mechanisms serve electronics assembly lines requiring 2-15 Nm repeatability for circuit board enclosures. South Korean battery manufacturers and German automotive suppliers specify these for electric vehicle module assembly where joint documentation carries liability weight.
- Nail Guns:Pneumatic and gas-actuated systems retain share in US residential framing where compressed air infrastructure remains sunk cost, though cordless displacement accelerates in renovation segments.
- Wrenches:Impact and torque-controlled variants span 100-3,000+ Nm for structural steel and heavy equipment maintenance, with Chinese high-speed rail procurement concentrating demand for calibrated precision models.
Drills anchor the volume base while screwdrivers gain share at the steepest rate.
Technology:
Capital deployment and operating cost structures diverge dramatically across power platforms, determining customer switching economics and OEM service revenue potential.
- Cordless:Lithium-ion battery platforms with brushless DC motors now achieve runtime parity with corded alternatives across 18V-54V architectures. OSHA silica dust enforcement in the United States and EU workplace noise directives accelerate displacement of exhaust-generating pneumatic systems in indoor construction.
- Corded:AC-powered tools retain cost advantage in stationary workshop environments and developing markets where electricity access outpaces battery supply chain maturity. Indian woodworking clusters and Brazilian metalworking shops specify these for continuous-duty grinding and cutting attachments.
- Pneumatic:Compressed air systems dominate high-volume automotive assembly in the US Midwest and Mexico where central plant infrastructure represents sunk capital, though cordless conversion gains traction in metalworking job shops.
- Hydraulic:High-torque systems exceeding 5,000 Nm serve offshore oil platforms, wind turbine installation vessels, and heavy civil infrastructure where explosive atmosphere certification precludes electrical alternatives.
Cordless technology commands the premium tier while pneumatic systems defend installed base revenue through compressor service contracts.
End User:
Application environments dictate specification requirements, with mobility needs and joint criticality determining technology selection and price tolerance.
- Construction:General contractors and specialty trades generate the largest revenue pool, with residential builders in California and Texas prioritizing cordless mobility for volatile project pipelines. Commercial concrete and steel erection in China concentrates demand for high-torque calibrated systems.
- Automotive:Assembly plants and tier suppliers specify connected torque tools with data logging for warranty traceability. German OEMs mandate Bluetooth-enabled documentation for battery pack assembly where joint failure carries catastrophic recall risk.
- Woodworking:Cabinet shops and millwork operations represent a concentrated margin segment for premium brushless configurations with dust-sealed housings. Italian furniture manufacturers and US custom builders specify these for precision joinery.
- Metalworking:Fabrication shops and machinery manufacturers drive demand for high-torque impact systems and precision torque multipliers. Japanese shipyards and German machine tool builders anchor this specification-intensive segment.
Construction absorbs the highest absolute volume while automotive generates the steepest technology premium.
Distribution Channel:
Channel selection determines customer relationship depth, with direct engagement capturing fleet management revenue and retail access serving fragmented replacement demand.
- Online Retail:E-commerce platforms serve price-sensitive residential users and small contractors in remote markets, with Amazon and specialized tool portals capturing replacement battery and accessory demand.
- Offline Retail:Big-box home improvement chains and independent dealers provide immediate availability for emergency replacements, with Lowe's and Home Depot dominating US residential procurement.
- Distributors:Industrial supply houses and construction-focused wholesalers bundle credit terms and technical support for mid-sized contractors, with Würth and Grainger anchoring this channel in North America and Europe.
- Direct Sales:Manufacturer-controlled field organizations capture fleet management contracts and guaranteed uptime agreements. Hilti's direct model in Germany and Bosch's service partner networks convert capital expenditure to recurring revenue streams.
Direct sales commands the highest customer lifetime value while online retail expands fastest among price-transparent replacement purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fastening power tools trade flows reveal a pronounced export concentration in East Asian manufacturing hubs against import dependency in infrastructure-heavy emerging markets. China, Japan, and Germany generate the dominant manufacturing surpluses while the United States, India, and Gulf states absorb the bulk of cross-border procurement.
United States
Residential construction volatility and OSHA silica dust enforcement drive cordless conversion across California and Texas job sites. The EPA energy efficiency directives shape battery recycling compliance requirements for tool pack imports. Midwest automotive assembly corridors around Detroit and Chicago retain pneumatic infrastructure that slows cordless displacement despite superior mobility economics.
Germany
Automotive OEMs mandate connected torque tools with Bluetooth documentation for electric vehicle battery pack assembly. REACH chemical regulations force cobalt reduction in battery cathodes, extending R&D timelines for local manufacturers. Bavarian industrial clusters around Munich and Nuremberg concentrate precision tool specification for aerospace and automotive tier suppliers.
China
Domestic procurement policies for high-speed rail and urban transit concentrate demand for 1,000+ Nm calibrated torque wrenches. MIIT battery standards and dual carbon goals accelerate local cell production for tool pack integration. Yangtze River Delta manufacturing bases around Shanghai and Suzhou anchor export-oriented production for Southeast Asian and Middle Eastern markets.
Japan
Precision electronics assembly lines specify sensor-feedback clutch tools for electric vehicle module production. METI industrial standards govern torque accuracy certification for automotive and shipbuilding applications. Nagoya and Osaka industrial corridors concentrate brushless motor development for premium professional tool exports.
India
Construction formalization and anticipated building code enforcement drive power tool procurement in Gujarat and Tamil Nadu industrial corridors. The PLI scheme for power tool manufacturing attracts component suppliers ahead of domestic demand acceleration. Mumbai and Delhi-NCR contractor fleets increasingly specify cordless platforms for jobsite mobility in dense urban construction.
Fastening Power Tools Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing value from battery cells, brushless motors, and precision sensors. The vendor base stratifies across three tiers: multinational tool platforms with captive battery ecosystems, regional manufacturers serving price-sensitive construction markets, and specialized torque instrument makers for automotive and aerospace certification. Consolidation pressure concentrates in the mid-tier as battery platform investments create scale barriers. Competitive moves center on fleet management service expansion and backward integration into cell production.
Among diversified industrial platforms, Stanley Black & Decker and Bosch exemplify the battery-ecosystem archetype through in-house cell sourcing and multi-brand portfolio architecture. Makita occupies a position representing manufacturing-scale competitiveness anchored in Japanese and Southeast Asian production bases. Hilti sits within the direct-sales archetype, converting capital expenditure to recurring revenue through field-based fleet management contracts. These three patterns—ecosystem control, manufacturing scale, and service integration—define the competitive vectors reshaping procurement relationships with construction and automotive end users.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Bosch |
| Makita |
| Hilti |
| Techtronic Industries |
| Hitachi Koki |
| DeWalt |
| FEIN |
| Ingersoll Rand |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese battery cell production is compressing pack costs for cordless tool OEMs while simultaneously eroding supplier pricing power across European and North American procurement offices. This utilization imbalance rewards buyers with volume leverage while forcing mid-tier manufacturers toward bare-metal assembly economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates brushless motor configurations with ISO 5393 torque certification from commodity brushed alternatives and unbranded imports. Pricing pressure stems from Chinese cell oversupply feeding downstream pack assembly. Residential contractors exhibit highest price sensitivity, while German automotive tier suppliers tolerate premium positioning for traceability features.
Supply Chain Analysis
Contract manufacturing for tool packs concentrates among Foxconn, BYD Electronics, and Desay Battery facilities across Dongguan and Shenzhen industrial zones. Cell production draws from cathode refining operations in China, South Korea, and Japan. Raw material dependencies span lithium carbonate, nickel sulfate, and rare-earth magnet powders. Single-source vulnerability around NCM cathode formulations from Chinese state-linked refiners exposes OEMs to export quota disruption. Distribution runs through direct sales organizations for fleet contracts and industrial distributors for spot replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fastening power tools market functions as a service-attach opportunity where fleet management and battery-as-a-service revenues expand faster than hardware unit sales. Recurring maintenance contracts and guaranteed uptime agreements now capture margin pools that hardware commoditization has compressed.
For Market Incumbents: Pre-empt cordless displacement in automotive assembly by securing long-term battery supply agreements before Chinese cell export quotas tighten further. Consolidate position through backward integration into brushless motor production in Vietnam or Mexico to sidestep tariff exposure on Chinese magnet assemblies. Lock in German automotive tier suppliers with embedded torque documentation software that raises switching costs. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial corridors offer underpenetrated contractor fleets where cordless adoption lags behind jobsite formalization. Target mid-sized residential builders in Texas and California seeking balance-sheet flexibility through rental models rather than capital purchase. Enter through equipment-as-a-service partnerships with existing distributor credit networks rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward torque sensor and connectivity module specialists serving German automotive and Japanese shipbuilding certification requirements. Long-term viability favors component suppliers with captive relationships to brushless motor platforms and cloud-based joint documentation software. Monitor MIIT battery standard revisions and OSHA silica enforcement intensity as inflection signals for cordless conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Platform Launch | Converts capital expenditure to recurring revenue for California and Texas contractors facing volatile project pipelines. |
| Backward Integration into Cell Production | Reduces exposure to Chinese cathode export quotas while capturing margin from lithium-ion pack assembly. |
| 5G-Enabled Torque Monitoring Integration | Meets Japanese automotive OEM specification requirements for cloud-based joint documentation and warranty traceability. |
| REACH-Compliant Battery Chemistry Reformulation | Accelerates nickel-manganese-aluminum cathode adoption to satisfy EU chemical substitution mandates for German market access. |
| Direct Sales Organization Expansion | Captures fleet management contracts from mid-sized construction firms seeking guaranteed uptime agreements over unit purchase. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade databases, and IEC certification registries. Interviews with procurement directors at construction OEMs, aftermarket service heads at industrial distributors, plant engineers at automotive tier suppliers, and regulatory affairs leads at battery cell manufacturers informed demand-side validation. Bottom-up unit shipment estimates triangulated against top-down value projections derived from channel revenue disclosures.
Forecast inputs span cordless technology penetration curves, OSHA enforcement intensity indices, and REACH compliance cost trajectories across the projection horizon. Segmentation modeling incorporates product type, power platform technology, end-user industry vertical, and distribution channel economics. CAGRs derive from regression analysis against construction spending forecasts and automotive production schedules. Battery chemistry transition timelines and certification protocol revision cycles feed scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-subsidized cell producers or rapid REACH cobalt ban acceleration would shift outcomes. Quarterly review of MIIT battery standard drafts, OSHA silica citation rates, and German automotive OEM torque specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Foldable Ladder Market
Tools
Global Electric Portable Drill Market
Tools
Allen Key Market
Tools
Manual Cutting Equipment Market
Tools
Leather Cutting Machine Market
Tools
Vise-Grip Pliers Market
Tools
Global Metal Forming Machine Tools Market
Tools
Cordless Blind Rivet Gun Market
Tools
Multi-Tasking Machine Tools Market
Tools
Wood Router Market
Tools
Construction Nails Market
Tools
Gear Hobbing Cutter Market
Tools
Spray Gun Market
Tools
Press Machine Market
Tools
Broaching Tools Market
Tools
Drilling Tools Market