
 Edge Banding Machine Market | 2026-2036
Edge Banding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Banding Machine Market Foresight
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales across the edge banding machine landscape. HOMAG Group leverages its global service network to capture recurring revenue streams. BIESSE Group anchors its competitiveness through intensive R&D investment in automated edge processing systems. SCM Group specializes in high-speed CNC configurations for premium furniture manufacturers.
An edge banding machine applies thermoplastic or veneer strips to exposed edges of wood-based panels using hot-melt adhesive, pressure rollers, and trimming units operating at feed speeds up to 30 meters per minute. Automatic systems dominate volume sales among furniture manufacturers seeking throughput above 500 panels per shift. CNC-controlled machines represent the fastest-expanding product category as panel processors adopt servo-driven corner rounding and pre-milling functions. PVC edge banding material commands the largest share of consumables demand due to durability and cost efficiency in mass cabinet production.
CE marking under the EU Machinery Directive governs safety compliance for equipment sold across Europe, while China's GB standards and SAMR oversight shape domestic product certification requirements. The US OSHA machinery guarding standards influence North American equipment specifications for operator protection. Stakeholders must monitor regulatory divergence between regional certification frameworks when configuring product portfolios for multi-territory deployment.
Market Dynamics
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales, as HOMAG Group, BIESSE Group, and SCM Group compete through recurring revenue streams rather than transactional machine deliveries alone.
Growth Catalysts
- CE marking compliance:The EU Machinery Directive mandates safety certifications that favor established European manufacturers with testing infrastructure, tightening competitive barriers for new entrants.
- Custom furniture manufacturing:Panel processors serving bespoke cabinetry demand CNC-controlled systems with servo-driven corner rounding, pulling automatic edge banding configurations into mid-tier workshops.
- PVC edge banding material dominance:Durability and cost efficiency in mass cabinet production sustain consumables demand, creating captive aftermarket revenue for original equipment suppliers.
Market Restraints
- Hot-melt adhesive input volatility:Petroleum-derived EVA and PUR adhesives expose machine operators to raw material cost swings that compress operating margins.
- German machinery cluster concentration:Critical component suppliers and technical expertise concentrate in Baden-Württemberg and Bavaria, creating geographic supply risk.
- Manual edge banding substitution:Small carpentry shops in Eastern Europe and Southeast Asia continue using hand-held trimmers for batch sizes below 50 panels.
Strategic Opportunities
- China's GB standards evolution:SAMR oversight of woodworking machinery safety creates compliance advisory services for European exporters seeking domestic certification.
- Pre-milling function integration:Convergence of CNC routing and edge processing into single-pass workflows opens premium positioning for system integrators.
- Direct spare parts platforms:Digital channels bypass traditional distributor networks, capturing margin previously allocated to regional service partners.
Industry Challenges
- Servo calibration expertise scarcity:CNC-controlled corner rounding demands mechatronics technicians that vocational programs in Poland and Romania have not scaled to match installation growth.
- OSHA guarding retrofit complexity:North American safety audits frequently require physical barrier modifications that interrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Banding Machine Market |
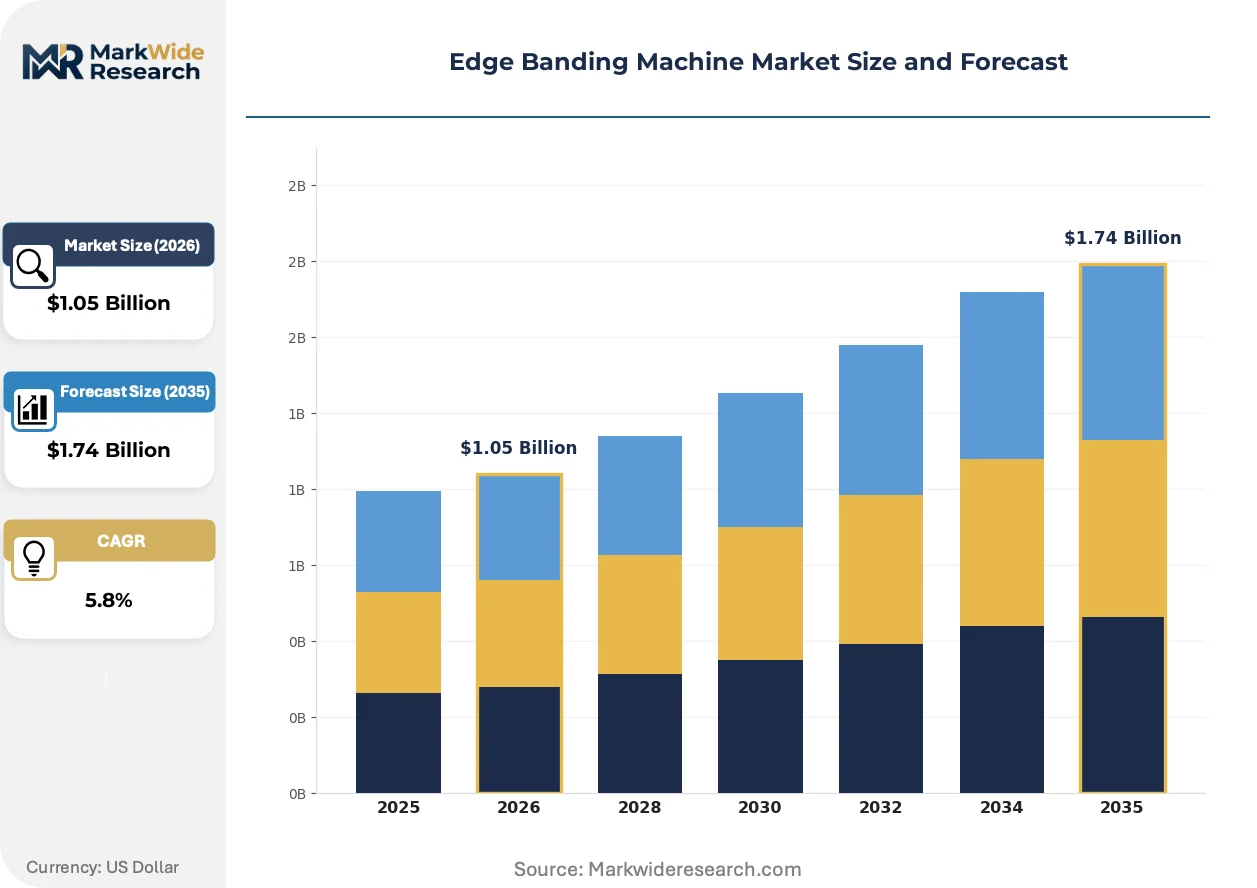
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.74 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, CNC Application: Furniture Manufacturing, Cabinet Production, Flooring, Panel Processing Material: Wood, PVC, Melamine, Veneer End User: Furniture Makers, Contractors, Retailers, DIY Enthusiasts |
| Companies Covered | IMA Schelling Group, KDT Machinery, BIESSE Group, Qingdao Unisunx Machinery, Nanxing Machinery, SCM Group, Felder Group, Shandong Dongteng Machinery, HOMAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Banding Machine Market Shifts & Advancements
Automation architectures are compressing the distinction between standalone edge banding units and integrated panel processing lines, forcing equipment suppliers to reposition around workflow software rather than mechanical specifications.
Laser edge banding technology is collapsing the traditional post-glue cleanup step by activating polymer functional layers without liquid adhesive. Premium furniture manufacturers in Northern Italy are adopting these systems at replacement cycle points. The technology is collapsing maintenance schedules and consumables inventory requirements that previously structured service revenue models.
REACH chemical restrictions on formaldehyde emissions from wood-based panels are tightening adhesive formulation standards across European manufacturing. Equipment suppliers must validate hot-melt compatibility with low-emission substrates. High-speed CNC configurations for premium furniture manufacturers face the most intensive recertification timelines.
Buyer concentration among contract furniture manufacturers is compressing procurement cycles toward total-cost-of-ownership evaluations. Distributor-led specification processes are losing ground to direct engineering engagement. Germany's woodworking machinery cluster exhibits the most pronounced shift toward lifecycle service contracting.
Edge Banding Machine Market Segmentation
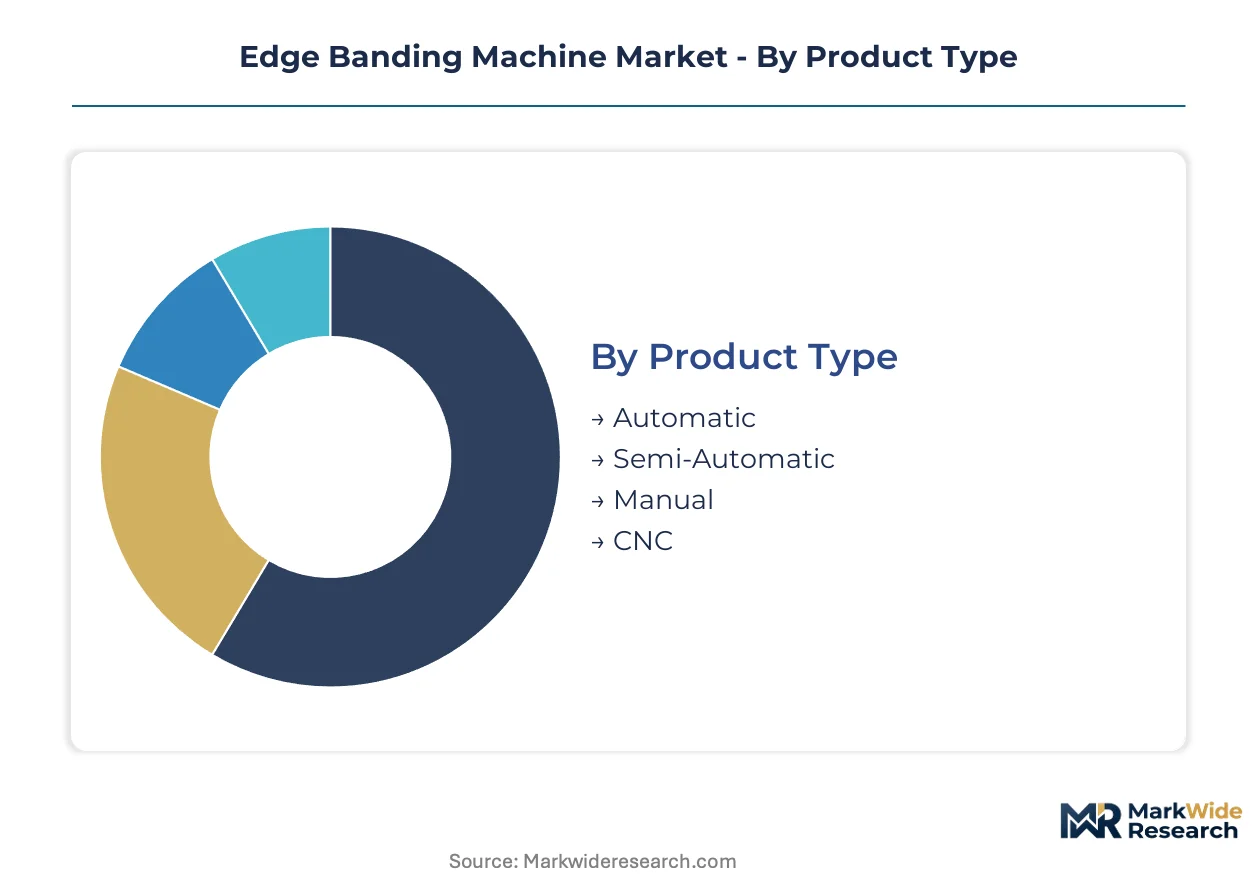
Edge banding machine segmentation reveals distinct technology tiers and material workflows that dictate procurement patterns across furniture manufacturing. Each dimension—product automation level, application intensity, substrate compatibility, and buyer sophistication—creates separate competitive arenas with divergent margin structures and service requirements.
Product Type:
Mature configurations dominate installed base volumes while emerging automation architectures reshape replacement cycles and aftermarket economics.
- Automatic:Continuous-feed systems with integrated pre-milling, gluing, and trimming operate at 20-30 meters per minute. German cabinet manufacturers in Baden-Württemberg specify these for throughput above 500 panels per shift, driving CE-compliant safety retrofits that favor established European suppliers.
- CNC:Servo-driven corner rounding and multi-axis edge profiling enable single-pass processing of complex geometries. Northern Italian premium furniture producers adopt these at replacement points, pulling servo calibration expertise into scarce supply.
- Semi-Automatic:Intermediate feed systems with manual loading suit mid-tier workshops transitioning from hand-held trimmers.
- Manual:Portable edge banding units persist in Eastern European carpentry shops processing batch sizes below 50 panels.
Automatic configurations retain volume leadership; CNC holds the steepest expansion curve.
Application:
Cost tier differentiation separates high-throughput mass production from bespoke fabrication workflows with divergent equipment specifications.
- Furniture Manufacturing:Mass cabinet and residential furniture production demands continuous-feed automatic systems with rapid changeover between PVC and veneer substrates. Contract furniture manufacturers in Germany evaluate total-cost-of-ownership metrics that compress distributor influence.
- Cabinet Production:Kitchen and bath cabinetry requires precise corner rounding and moisture-resistant edge seals. North American producers face OSHA guarding retrofit complexity during safety audits.
- Flooring:Laminate and engineered wood plank processing uses specialized wide-belt edge banding configurations.
- Panel Processing:Architectural millwork and commercial fixtures demand multi-material flexibility across melamine, veneer, and solid wood edges.
Furniture manufacturing commands the largest equipment installed base; cabinet production exhibits the most intensive CNC upgrade activity.
Material:
Customer type segmentation aligns substrate durability requirements with equipment adhesive systems and consumables revenue models.
- PVC:Thermoplastic edge banding dominates mass production through durability and cost efficiency. Hot-melt adhesive compatibility with PVC sustains captive aftermarket parts demand for original equipment suppliers serving high-volume cabinet manufacturers.
- Veneer:Natural wood edge banding requires precise thickness calibration and pre-heating systems for proper adhesion. Premium furniture producers in Northern Italy specify these for aesthetic continuity with solid wood substrates.
- Melamine:Paper-impregnated decorative edges serve mid-market furniture with balanced cost and scratch resistance.
- Wood:Solid wood edge banding persists in bespoke craftsmanship and restoration applications.
PVC retains consumables volume leadership; veneer gains share fastest among premium positioning strategies.
End User:
Volume concentration among professional fabricators creates procurement scale advantages that reshape distribution economics.
- Furniture Makers:Integrated manufacturers and independent workshops purchase automatic and CNC systems through direct engineering engagement rather than distributor-led specification. Lifecycle service contracting is concentrating among Germany's woodworking machinery cluster.
- Contractors:Commercial installation firms require portable or semi-automatic units for on-site finishing of architectural millwork.
- Retailers:Home improvement chains stock entry-level manual and semi-automatic equipment for pro-sumer segments.
- DIY Enthusiasts:Hobbyist woodworkers represent minimal equipment revenue but sustain accessory and consumables demand through direct spare parts platforms.
Furniture makers dominate capital equipment procurement; contractors show the fastest adoption of portable CNC configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Northern Italy demonstrate the lowest price elasticity, prioritizing CNC automation and lifecycle service contracts over upfront equipment costs. Eastern European workshops and Southeast Asian carpentry operations retain higher sensitivity, deferring automatic system adoption until batch sizes exceed 500 panels per shift.
Germany
Baden-Württemberg and Bavaria host the densest concentration of woodworking machinery manufacturers, with cabinet producers specifying CE-compliant automatic systems for throughputs above 500 panels per shift. The EU Machinery Directive mandates safety certifications that favor established domestic suppliers with in-house testing infrastructure. Stuttgart's machinery cluster anchors global premium positioning through intensive R&D in servo-driven corner rounding.
China
Panel processing growth in Guangdong and Zhejiang provinces pulls automatic edge banding adoption into mid-tier workshops serving export furniture markets. SAMR oversight of GB standards for woodworking machinery safety creates compliance complexity for European equipment exporters. The Yangtze River Delta exhibits fastest CNC upgrade activity as domestic manufacturers localize servo calibration expertise.
United States
Contract furniture manufacturers in North Carolina and California evaluate total-cost-of-ownership metrics that compress traditional distributor influence. OSHA machinery guarding standards require physical barrier retrofits that interrupt production schedules during safety audits. The Southeast furniture corridor shows concentrated demand for high-speed configurations serving mass cabinet production.
Italy
Premium furniture producers in Lombardy and Veneto adopt laser edge banding systems at replacement cycle points, eliminating post-glue cleanup steps. REACH chemical restrictions on formaldehyde emissions tighten adhesive formulation standards across regional manufacturing. The Brianza furniture district concentrates demand for veneer-compatible systems with precise thickness calibration.
Poland
Mid-tier workshops in the Łódź and Poznań regions transition from manual trimmers to semi-automatic systems as batch sizes grow. Vocational programs have not scaled mechatronics technician output to match CNC installation growth, creating servo calibration expertise scarcity. EU structural funds support machinery modernization in woodworking clusters near the German border.
Edge Banding Machine Market Competitive Landscape
Full-line system integrators and component specialists split the market into distinct competitive arenas with divergent margin structures and customer retention mechanics. German and Italian machinery clusters anchor premium positioning through CE certification infrastructure and proximity to demanding furniture manufacturers. Three archetypes dominate: integrated workflow providers bundling software with mechanical systems; high-speed CNC specialists serving premium furniture tiers; and cost-optimized fabricators targeting emerging market volume. Consolidation pressure concentrates among mid-scale European players seeking geographic coverage, while Asian manufacturers expand through direct spare parts platforms that bypass distributor networks.
Within the full-line integrator tier, HOMAG Group, BIESSE Group, and SCM Group exemplify positioning around lifecycle service contracting rather than transactional equipment sales. KDT Machinery and Nanxing Machinery sit within the scale-driven cohort of Chinese fabricators localizing automatic system production for domestic and Southeast Asian markets. Qingdao Unisunx Machinery and Shandong Dongteng Machinery represent the cost-optimized archetype targeting workshop upgrades from manual to semi-automatic configurations. IMA Schelling Group and Felder Group occupy positions bridging premium European engineering with mid-market accessibility.
| Leading Market Players |
|---|
| IMA Schelling Group |
| KDT Machinery |
| BIESSE Group |
| Qingdao Unisunx Machinery |
| Nanxing Machinery |
| SCM Group |
| Felder Group |
| Shandong Dongteng Machinery |
| HOMAG Group |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's machinery cluster concentrates servo motor and CNC controller manufacturing, translating upstream component scarcity into pricing leverage for integrated system suppliers serving premium furniture manufacturers. Equipment margins compress when Chinese fabricators localize automatic system production for mid-tier workshops, yet aftermarket service contracts retain value capture for European incumbents with calibration expertise.
Pricing Analysis
Aftermarket parts and field service contracts generate lifetime value multiples exceeding original equipment transactions. Three-tier pricing structure across premium CNC, standard automatic, and economy semi-automatic levels reflects certification grade differentiation and servo complexity. Cost compression in mid-tier configurations is intensifying because Chinese manufacturers bypass distributor markups through direct spare parts platforms. Contract furniture manufacturers in Germany exhibit lowest price sensitivity, while Eastern European carpentry shops defer automatic system adoption until batch thresholds justify capital deployment.
Supply Chain Analysis
Extended payment terms from German machinery OEMs to component suppliers stabilize working capital across the Baden-Württemberg cluster. Manufacturing concentration in Germany, Italy, and China shapes equipment availability, with critical servo drives and precision ball screws drawing from Japanese and German sources. Single-source vulnerability in mechatronics components creates disruption risk when vocational training pipelines fail to match installation growth. Distribution runs through authorized service partners for CE-compliant systems, while Chinese fabricators sell direct through digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser edge banding technology is collapsing traditional adhesive-based maintenance schedules, creating a regulatory-technology inflection that reconfigures service revenue models across the projection horizon.
For Market Incumbents: Harden lifecycle service contracting against laser technology displacement by bundling predictive maintenance software with mechanical system sales. Deepen backward integration into servo calibration training programs to offset mechatronics technician scarcity threatening installation quality. CE certification infrastructure remains a defendable moat against emerging market entrants lacking in-house testing capabilities. For New Entrants and Emerging Players: Mid-tier workshops in Poland and Romania transitioning from manual trimmers represent the most penetrable entry point for semi-automatic system penetration. Portable CNC configurations for on-site architectural millwork contractors show fastest adoption velocity with minimal incumbent saturation. Go-to-market execution should anchor on direct spare parts platforms that capture margin previously allocated to regional distributor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-line system integrators bundling software with mechanical systems. Long-term viability over the next decade favors acquisition targets with established calibration expertise and installed base density in Northern Italy and Germany. The signal to watch is laser edge banding adoption rates among premium furniture manufacturers, which would accelerate obsolescence of adhesive-dependent service models.| Strategic Initiative | Industry Significance |
|---|---|
| Servo Calibration Training Program | Addresses technician scarcity constraining CNC installation growth in Eastern Europe. |
| Direct Spare Parts Platform Launch | Bypasses distributor networks to capture margin in Chinese and Southeast Asian markets. |
| Laser Edge Banding System Development | Eliminates adhesive consumables revenue while collapsing competitor maintenance schedules. |
| CE Compliance Advisory Service | Captures SAMR certification complexity for European exporters entering Chinese markets. |
| Pre-Milling Function Integration | Converges CNC routing and edge processing into premium single-pass workflow offerings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and machinery production databases. Interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads informed operational reality checks. Secondary validation drew from CE marking documentation, SAMR GB standard publications, OSHA machinery guarding directives, and woodworking machinery cluster economic reports. Bottom-up equipment shipment analysis triangulates against top-down furniture production capacity estimates.
Forecast inputs incorporate automation level adoption curves, substrate material transition patterns, and regional regulatory enforcement intensity across the projection horizon. Segmentation dimensions span product automation tier, application intensity, edge banding material compatibility, and end-user procurement sophistication. CAGRs derive from installed base replacement cycles, technology substitution elasticities, and workshop expansion rates in emerging manufacturing clusters. Servo calibration expertise supply constraints and laser technology penetration thresholds shape scenario boundaries.
Macroeconomic conditions sit as an overlay; deviation in construction spending, furniture export demand, or petroleum-derived adhesive input costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Thickness Planers Market
Tools
Floor Saw Market
Tools
Caulking Gun Market
Tools
Nail Gun Market
Tools
Collated Screws Market
Tools
Fixed Cutter Bits Market
Tools
Automatic Lathe Machines Market
Tools
Screw Fastener Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Woodcarving Tool Market
Tools
Vertical Milling Machine Market
Tools
Fatigue Testing Machine Market
Tools
Woodworking Circular Saw Blades Market
Tools
Rebar Cutter Market
Tools
Foam Cutting Machine Market