
 Bottle Jack Market | 2026-2036
Bottle Jack Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Jack Market Analysis
China is rewriting capacity dynamics across the bottle jack supply base as domestic foundries and machining clusters scale output for export and local consumption. Zhejiang Yipeng Machinery Co., Ltd. leverages integrated casting and finishing operations to control cost positions in mid-capacity segments. Enerpac Tool Group anchors premium hydraulic portfolios through industrial channel partnerships in North America and Europe. Torin Inc. competes aggressively on price in automotive aftermarket channels through high-volume SKU strategies.
A bottle jack is a vertical hydraulic lifting device utilizing a piston-cylinder assembly and pump mechanism to raise heavy loads through confined stroke lengths, typically rated by tonnage capacity and operating pressure. The device serves essential functions in vehicle maintenance, structural lifting, and machinery positioning where space constraints prevent the use of floor jacks or overhead cranes. Hydraulic jacks dominate volume shipments across industrial and automotive end users due to proven reliability and lower unit economics. Pneumatic and electric variants capture faster expansion in fleet maintenance operations and automated workshop environments where cycle time reduction carries operational value. Distribution through specialty stores and wholesale channels still commands the majority of transaction flow, though online retail is gaining share among DIY enthusiasts and small repair shops seeking price transparency.
OSHA lifting equipment standards in the United States, CE marking requirements under the EU Machinery Directive, and China's GB/T quality standards collectively shape product compliance burdens and market access thresholds for manufacturers. These frameworks mandate load-testing protocols, safety factor margins, and traceable material certifications that elevate production costs for non-compliant suppliers. Stakeholders must monitor evolving regional enforcement patterns and decide whether to pursue modular platform designs that simplify certification across multiple jurisdictions or specialize for single-market dominance.
Market Dynamics
China's tightening GB/T certification requirements for hydraulic lifting equipment are forcing manufacturers to restructure quality assurance protocols and foundry partnerships, compressing margins for non-compliant suppliers while consolidating order flow toward certified producers.
Growth Catalysts
- Automotive aftermarket expansion:North American repair shops are expanding tool procurement budgets for fleet maintenance, lifting demand for mid-capacity hydraulic units rated 10-20 tons.
- OSHA workplace safety mandates:US enforcement of load-testing protocols and safety factor margins is accelerating replacement cycles for aging shop floor equipment.
- Electric variant adoption:Fleet maintenance operations are specifying pneumatic and electric bottle jacks to reduce cycle times in high-volume workshop environments.
Market Restraints
- Cast iron input volatility:Foundry-grade pig iron prices fluctuate with Chinese export quotas, compressing margin predictability for mid-tier manufacturers.
- Zhejiang supply concentration:Domestic Chinese machining clusters control 60-70% of global casting capacity, creating geographic vulnerability for buyers.
- Overhead crane substitution:Permanent lift installations in new manufacturing facilities displace portable hydraulic solutions for heavy machinery positioning.
Strategic Opportunities
- EU Green Deal compliance positioning:CE marking under tightened EU Machinery Directive creates premium tier for low-carbon foundry output and energy-efficient pump mechanisms.
- Online retail channel penetration:DIY enthusiasts and small repair shops are migrating to e-commerce platforms for price-transparent SKU comparison and bulk purchasing.
- India infrastructure buildout:Central government capital expenditure on road maintenance and commercial vehicle fleets is generating first-time demand for certified lifting equipment.
Industry Challenges
- GB/T certification timeline compression:China's accelerated safety standard revisions force simultaneous re-engineering of piston-cylinder assemblies and pump valve systems.
- Traceable material documentation:Load-testing protocols now require batch-level foundry certification, adding administrative burden to procurement and inventory management.
- Legacy equipment interoperability:Automated workshop environments demand electric jack integration with fleet management software, straining smaller manufacturers' R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Jack Market |
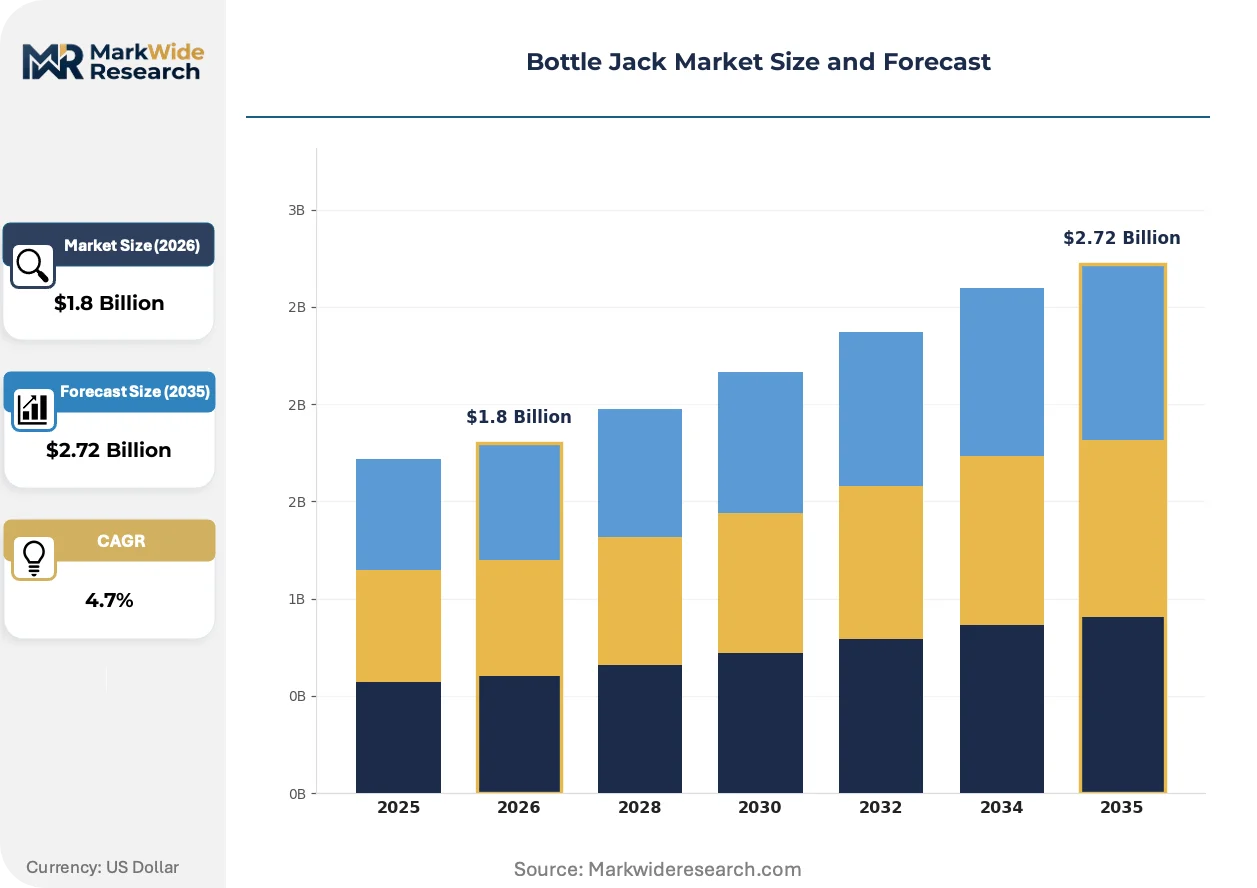
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Jack, Pneumatic Jack, Electric Jack, Manual Jack End User: Automobile Repair, Construction, Industrial Manufacturing, DIY Enthusiasts Capacity: 1 Ton, 2 Ton, 3 Ton, 5 Ton Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Ellis Manufacturing Company, Metro Hydraulic Jack Co., Zhejiang Yipeng Machinery Co., Ltd., Zinko Hydraulic Jacks, Shinn Fu Company of America, Torin Inc., Sunex Tools Inc., Enerpac Tool Group, Powerbuilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Jack Market Emerging Trajectories
Electrification of workshop equipment and compressed certification timelines are restructuring competitive advantage around software integration capabilities and foundry compliance depth rather than pure manufacturing scale.
Aluminum alloy piston construction is collapsing the weight differential between portable and fixed lifting solutions. Mobile service technicians in Germany and the United States are adopting sub-15-kilogram electric units for roadside assistance. This material shift is collapsing the traditional segmentation between shop-floor and field-service equipment categories.
REACH substance restrictions on hydraulic fluids are forcing reformulation of pump lubricants across EU-bound production lines. Industrial channel partners now require full material safety data sheet compliance before listing new SKUs. Premium hydraulic portfolios are absorbing certification costs through industrial partnerships in Germany and France while economy tiers face delisting pressure.
Buyer concentration among national fleet operators is compressing supplier negotiation cycles and unbundling after-sales service from equipment procurement. Large automotive groups in the Midwest United States now specify multi-year maintenance contracts separate from capital purchase orders. This unbundling is most visible in commercial vehicle leasing channels where total cost of ownership calculations dominate vendor selection.
Bottle Jack Market Segmentation
Bottle jack procurement patterns diverge sharply across user sophistication levels and operational intensity. Fleet operators prioritize certified hydraulic units with traceable load-testing documentation, while DIY purchasers trade durability for portability and price transparency.
Product Type:
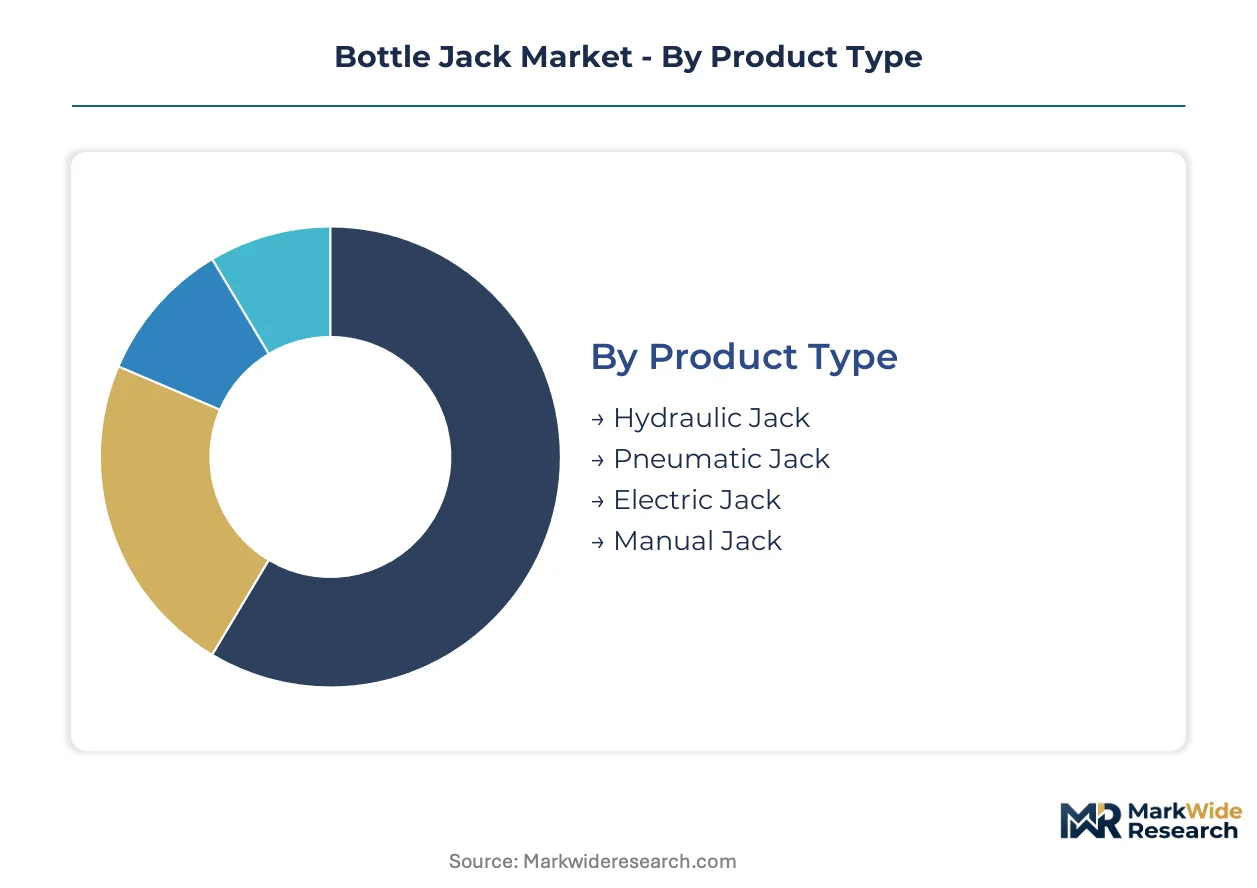
Mature hydraulic architectures dominate installed bases, yet emerging electric and pneumatic variants are capturing specification share in automated workshop environments.
- Hydraulic Jack:Piston-cylinder assemblies utilizing manual pump mechanisms deliver proven reliability under confined stroke constraints. Midwest automotive repair corridors specify 10-20 ton units with OSHA-compliant safety factor margins for fleet maintenance operations.
- Electric Jack:Motor-driven pump systems integrate with fleet management software for cycle time reduction in high-volume commercial vehicle servicing. German roadside assistance operators now specify sub-15-kilogram aluminum alloy units for mobile deployment.
- Pneumatic Jack:Compressed air actuation suits continuous-duty manufacturing floors where shop air infrastructure exists.
- Manual Jack:Screw or ratchet mechanisms serve occasional-use scenarios with minimal maintenance requirements.
Hydraulic Jack retains volume leadership; Electric Jack holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive fleet operators from price-sensitive independent technicians and hobbyist purchasers.
- Automobile Repair:Commercial service bays demand certified lifting equipment with batch-level material traceability. OSHA enforcement of load-testing protocols accelerates replacement cycles for aging floor equipment across United States repair networks.
- Industrial Manufacturing:Permanent machinery positioning applications favor heavy-capacity units with extended duty cycles. Overhead crane installations in new Chinese facilities increasingly displace portable hydraulic solutions for heavy-load scenarios.
- Construction:Field-service requirements prioritize weather-sealed pump mechanisms and ruggedized casting integrity.
- DIY Enthusiasts:E-commerce migration enables price-transparent SKU comparison and bulk purchasing for home garage applications.
Automobile Repair commands procurement volume concentration; Industrial Manufacturing faces the most severe substitution pressure from permanent lift infrastructure.
Capacity:
Volume distribution clusters in mid-range ratings where automotive aftermarket demand intersects with foundry production economics.
- 3 Ton:Passenger vehicle servicing represents the commercial sweet spot for general repair shops. United States specialty store channels move the highest transaction velocity in this rating for light truck and SUV maintenance.
- 5 Ton:Commercial vehicle and light industrial applications require reinforced cylinder wall thickness and enhanced base plate stability. India's road maintenance infrastructure buildout is generating first-time demand for certified 5-ton units in state fleet procurement.
- 1 Ton:Compact motorcycle and small equipment lifting suits mobile technician toolkits.
- 2 Ton:Compact passenger car servicing balances portability with adequate safety margins.
3 Ton maintains the broadest addressable user base; 5 Ton is climbing the fastest specification curve among fleet operators.
Distribution Channel:
Customer type fragmentation drives channel bifurcation between relationship-based wholesale and transaction-efficient digital platforms.
- Specialty Stores:Hands-on product evaluation and immediate availability support professional technician procurement. Midwest United States automotive tool distributors maintain extensive 10-20 ton hydraulic inventory for same-day contractor fulfillment.
- Online Retail:Price transparency and SKU breadth attract DIY enthusiasts and small independent shops. Zhejiang-based manufacturers leverage direct-to-buyer platforms to bypass traditional wholesale markups in North American aftermarket channels.
- Wholesale:Volume contracting and multi-year maintenance agreements dominate national fleet operator relationships.
- Direct Sales:OEM integration and custom specification engineering serve specialized industrial applications.
Specialty Stores retain transaction flow leadership; Online Retail is gaining share fastest among sub-commercial purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific throughput for hydraulic lifting equipment, channeling Zhejiang foundry output to North American automotive corridors and European industrial distributors.
United States
Midwest manufacturing corridors spanning Michigan, Ohio, and Illinois generate concentrated demand from commercial fleet operators and heavy machinery service depots. OSHA enforcement of load-testing protocols accelerates replacement cycles for aging shop floor equipment. Detroit-area automotive tool distributors maintain extensive 10-20 ton hydraulic inventory for same-day contractor fulfillment.
China
Zhejiang and Jiangsu machining clusters control 60-70% of global casting capacity for hydraulic lifting components, serving both export markets and domestic infrastructure buildout. GB/T certification requirements under SAMR oversight force simultaneous re-engineering of piston-cylinder assemblies and pump valve systems. Ningbo-Shaoxing foundry networks are scaling output for certified mid-capacity segments bound for European aftermarket channels.
Germany
Ruhr industrial heritage and contemporary automotive engineering sustain premium-tier demand for precision lifting equipment in commercial vehicle manufacturing. CE marking under the EU Machinery Directive and REACH substance restrictions on hydraulic fluids elevate compliance thresholds for imported equipment. Stuttgart-area industrial channel partners now require full material safety data sheet compliance before listing new SKUs.
India
Central government capital expenditure on road maintenance and commercial vehicle fleets generates first-time demand for certified lifting equipment across state procurement networks. BIS quality standards for industrial machinery create compliance pathways for domestic foundries and importers alike. Maharashtra and Gujarat automotive manufacturing clusters are absorbing initial volumes of 5-ton rated units for fleet maintenance operations.
Japan
Automotive OEM supply chain integration and precision manufacturing culture sustain demand for high-reliability hydraulic systems in assembly line applications. METI industrial standards and JIS certification frameworks govern material traceability and load-testing documentation requirements. Nagoya-area machinery distributors specialize in compact electric variants for space-constrained workshop environments.
Bottle Jack Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in foundry and machining operations. The vendor base organizes around three structural tiers: premium hydraulic portfolios anchored through industrial channel partnerships, mid-capacity specialists leveraging integrated casting and finishing operations, and high-volume aftermarket competitors pursuing aggressive SKU proliferation. Consolidation pressure concentrates among certified producers as GB/T and CE compliance costs escalate. Dominant competitive moves include backward integration into captive foundry capacity and geographic expansion through direct-to-buyer e-commerce platforms.
Among Zhejiang-based fabricators, Zhejiang Yipeng Machinery Co., Ltd. exemplifies the integrated casting-finishing archetype controlling cost positions in mid-capacity segments. Enerpac Tool Group occupies a position on the premium-tier vector through industrial channel partnerships in North America and Europe. Torin Inc. represents the high-volume aftermarket competitor pursuing price-transparent SKU strategies in automotive service channels.
| Leading Market Players |
|---|
| Ellis Manufacturing Company |
| Metro Hydraulic Jack Co. |
| Zhejiang Yipeng Machinery Co., Ltd. |
| Zinko Hydraulic Jacks |
| Shinn Fu Company of America |
| Torin Inc. |
| Sunex Tools Inc. |
| Enerpac Tool Group |
| Powerbuilt |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Zhejiang foundry networks for cast iron cylinder castings determines both the three-tier pricing spread across premium, standard, and economy segments and the geographic vulnerability baked into procurement strategies for North American distributors.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from spot-market transactions. Three-tier pricing stratifies across CE-certified premium units with full material traceability, OSHA-compliant standard SKUs for commercial repair networks, and unbranded economy imports for DIY channels. Cost compression in the economy tier intensifies because Zhejiang exporters absorb GB/T recertification expenses to maintain North American aftermarket access. Fleet operators show the least price sensitivity, prioritizing batch-level documentation and multi-year maintenance bundling over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for North American distributors. Foundry-grade pig iron, precision-machined piston assemblies, and hydraulic pump valves draw from concentrated Zhejiang and Jiangsu machining clusters. Single-source vulnerability in casting capacity creates chokepoint risk when SAMR accelerates GB/T compliance timelines. Distribution runs through specialty store networks for professional technicians and direct-to-buyer platforms for independent repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottle jack market sits in an early-cycle expansion phase as electric variant adoption penetrates fleet maintenance operations and roadside assistance networks.
For Market Incumbents: Build certification depth as the defensive moat. Deepen captive foundry relationships in Ningbo-Shaoxing corridors to secure GB/T-compliant casting supply before non-compliant competitors face delisting. Invest in software integration capabilities for electric jack fleet management connectivity, as automated workshop environments increasingly specify API-compatible lifting equipment. Channel control through exclusive industrial distributor partnerships in the Midwest United States protects margin positions against Zhejiang direct-to-buyer encroachment. For New Entrants and Emerging Players: Build out white-space positions in India's state fleet procurement networks, where BIS certification creates a compliance barrier that domestic foundries can satisfy faster than established exporters. Target 5-ton capacity ratings for commercial vehicle maintenance, the fastest-climbing specification tier among infrastructure buildout programs. Pursue a direct-to-buyer e-commerce angle with price-transparent SKU comparison tools, bypassing wholesale markups that inflate landed costs for small independent shops. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified mid-cap specialists with integrated casting-finishing operations and established CE marking pathways. Long-term viability hinges on regulatory compliance depth rather than pure manufacturing scale, positioning integrated Zhejiang fabricators and premium-tier industrial channel partners as durable acquisition targets. Watch GB/T enforcement intensity as the inflection signal—accelerated SAMR audit schedules would compress margins for non-compliant suppliers and accelerate order flow concentration toward certified producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | Secures GB/T-compliant casting supply for CE marking and OSHA certification pathways. |
| Electric Jack Fleet Management Integration | Aligns with commercial vehicle operator specifications for cycle time reduction and software interoperability. |
| Direct-to-Buyer E-Commerce Platform Launch | Bypasses wholesale markups for price-sensitive DIY and small repair shop segments. |
| Multi-Year Maintenance Contract Unbundling | Separates after-sales service revenue from capital equipment sales for fleet operator relationships. |
| Aluminum Alloy Piston Material Transition | Enables sub-15-kilogram mobile units for German and United States roadside assistance deployment. |
Methodological Framework
Desk research of customs trade databases, SAMR certification registries, and OSHA enforcement records preceded structured interviews with maintenance directors at commercial fleet operators, aftermarket tool distributors, foundry operations managers, and industrial procurement leads. Primary fieldwork across Midwest automotive corridors and Zhejiang machining clusters combined with secondary validation against SEC filings and BIS quality standard documentation. Bottom-up SKU-level demand modeling triangulated against top-down market sizing from production capacity estimates.
The analytical framework held regulatory enforcement timelines and foundry capacity utilization fixed across the projection horizon while varying electric variant adoption curves and fleet operator procurement centralization. Segmentation modeling spanned product type, capacity rating, end-user sophistication tier, and distribution channel structure. CAGRs derived from unit shipment trajectories weighted by average selling price evolution in each tier. Forecast inputs incorporated GB/T certification timeline compression and REACH hydraulic fluid reformulation requirements.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment by non-compliant Zhejiang exporters or accelerated SAMR audit schedules would shift outcomes toward faster market concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Hand and Power Tools Market
Tools
Global Vertical Grinding Machine Market
Tools
Global Flange Fasteners Market
Tools
Boring Tools Market
Tools
Concrete Saw Market
Tools
Global Protractor Market
Tools
Fiber Laser Cutting Machines Market
Tools
Gas Cutting Machine Market
Tools
Europe Paint Spray Guns Market
Tools
Tool Boxes Market
Tools
Drilling Tools Market
Tools
Step Ladder Market
Tools
Cold and Hot Tool Steel Market
Tools
Hand Saw Market
Tools
China Power Tools and Hand Tools Market