
 Stamping Machines Market | 2026-2036
Stamping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Stamping Machines Market Analytics
The direct-sales channel for large-tonnage presses is narrowing as Asian builders tighten control over aftermarket service networks. AIDA Engineering Ltd. leverages its Tokyo R&D base to sustain proprietary servo-drive architectures. Gestamp Automoción anchors European demand through captive stamping capacity tied to OEM just-in-sequence programs. AMADA competes in precision sheet-metal segments where software-integrated turret-to-press workflows differentiate output quality.
Stamping machines apply progressive or transfer die force to sheet metal, typically delivering 30 to 2,500 metric tons of press capacity with stroke rates from 10 to 1,500 per minute depending on drive architecture. These systems form structural automotive panels, connector housings, and appliance enclosures through controlled plastic deformation. Servo stamping leads technology migration because programmable slide motion reduces die wear and permits warm-forming of advanced high-strength steels. The automotive end-user segment occupies the dominant value share, though electronics manufacturing represents the fastest-expanding demand pool as miniaturization drives micro-stamping precision requirements.
OSHA lockout-tagout rules and EPA metalworking fluid emissions standards shape US equipment specifications, while CE marking under the EU Machinery Directive mandates integrated safety controllers for European installations. China's GB standards for mechanical press safety and Japan's JIS B 6402 precision benchmarks create divergent compliance burdens for multi-regional suppliers. Stakeholders must monitor how servo-motor supply constraints and rare-earth magnet pricing alter total cost of ownership calculations against legacy hydraulic alternatives.
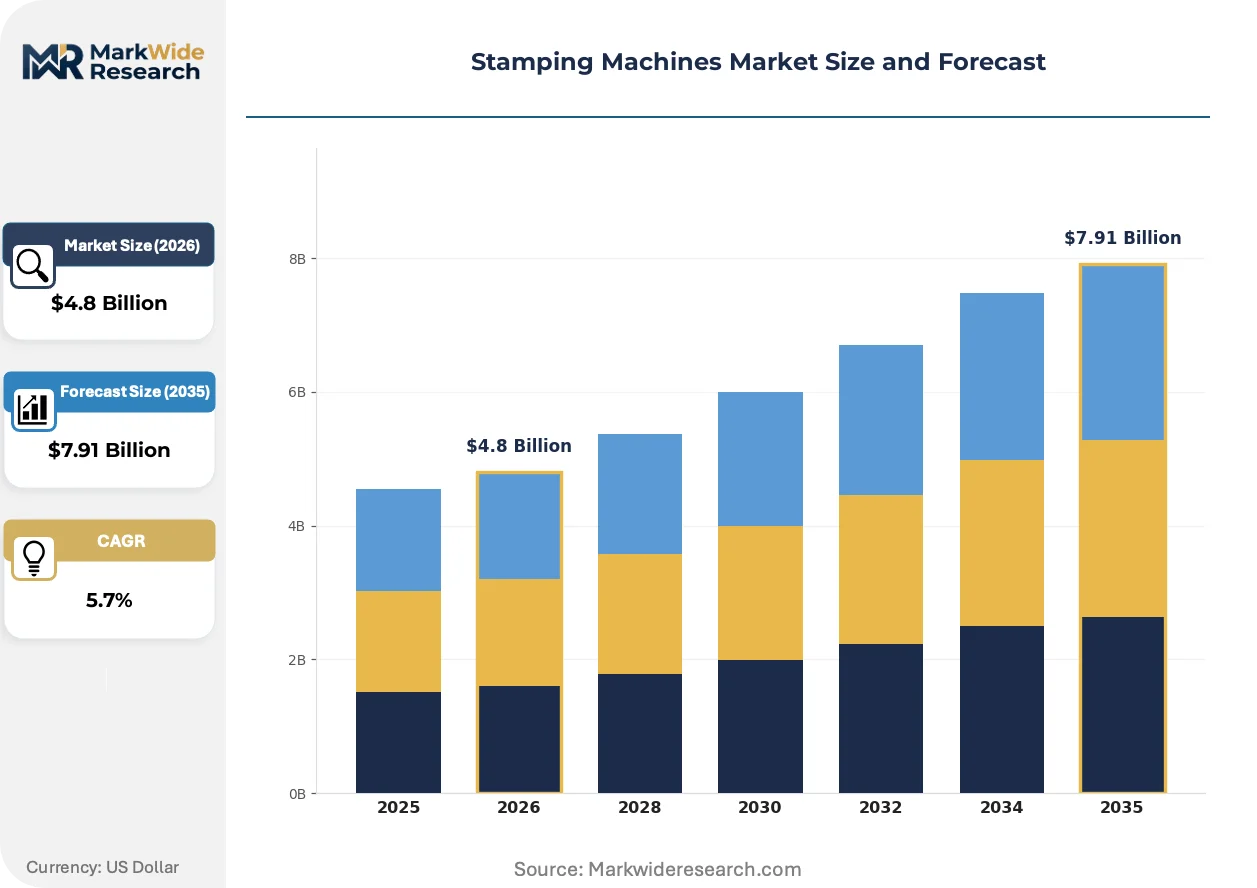
Market Dynamics
Servo-electric press architectures are displacing legacy mechanical and hydraulic systems across automotive stamping operations, driven by programmable slide motion that cuts die wear and enables warm-forming of advanced high-strength steels.
Growth Catalysts
- EU Green Deal carbon targets:German automotive OEMs face binding emission reduction mandates that favor energy-efficient servo-electric presses over hydraulic alternatives, accelerating fleet replacement cycles.
- Dual carbon goals in China:Yangtze River Delta manufacturing clusters must meet provincial energy-intensity benchmarks, driving domestic substitution of imported machine tools with locally produced servo stamping systems.
- Advanced high-strength steel forming:Warm-forming process requirements for third-generation automotive steels demand programmable thermal-mechanical profiles that only servo drives deliver at production scale.
Market Restraints
- Rare-earth magnet supply concentration:Servo motor production depends on neodymium-iron-boron magnets sourced predominantly from Chinese refining operations, creating input cost volatility and geopolitical exposure.
- CE marking compliance burden:The EU Machinery Directive mandates integrated safety controllers that add engineering cost and certification timeline for European-bound equipment.
- Hydraulic press residual value:Secondary markets for conventional hydraulic systems in Southeast Asia and Latin America sustain lower-cost competition, delaying full technology transition.
Strategic Opportunities
- Electronics micro-stamping:Connector housing and semiconductor lead-frame applications represent underpenetrated demand as miniaturization drives sub-millimeter precision requirements beyond current mechanical press capabilities.
- India PLI scheme for auto components:Production-linked incentive frameworks for advanced automotive manufacturing create tariff-advantaged entry for servo press suppliers establishing local assembly.
- Software-integrated turret-to-press workflows:Convergence of CAD/CAM nesting algorithms with real-time slide control enables lights-out operation models that differentiate precision sheet-metal service providers.
Industry Challenges
- Servo drive commissioning expertise:Programmable motion profiles require controls engineers with mechatronics training, a skill set concentrated at Japanese and German OEM headquarters and scarce in emerging manufacturing clusters.
- Legacy die set incompatibility:Existing progressive die investments at tier suppliers cannot fully exploit servo motion capabilities without redesign, creating integration friction and capital duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stamping Machines Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Stamping, Hydraulic Stamping, Pneumatic Stamping, Servo Stamping End User: Automotive Industry, Electronics Manufacturing, Aerospace Sector, Consumer Goods Technology: Numerical Control, Manual Operation, Automatic Operation, Hybrid Technology Size: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Arconic Corporation, Gestamp Automoción, Magna International Inc., Aisin Corporation, STAMTEC, AMADA, Chin Fong, AIDA Engineering Ltd., BRUDERER AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stamping Machines Market Evolving Landscape
Digital thread integration from design to forming is compressing development cycles and enabling mass customization in automotive panel production. Three interconnected developments are restructuring competitive positioning.
Direct-drive servo motors are collapsing the performance gap between mechanical flywheel presses and hydraulic systems in deep-draw applications. Tier-one automotive suppliers in Japan and Germany are retrofitting transfer press lines with torque-dense servo drives to eliminate clutch-brake maintenance and enable mid-stroke dwell for complex part geometries. This architecture shift is collapsing the traditional segmentation between high-speed blanking and heavy-forming equipment categories.
China's GB standards for mechanical press safety are tightening interlock and guarding requirements that diverge from ISO and ANSI specifications. Domestic certification bodies are enforcing localized testing protocols that extend equipment approval timelines for non-Chinese suppliers. Stamping lines destined for Yangtze River Delta automotive plants must undergo separate conformity assessment processes, fragmenting product development roadmaps for multi-regional builders.
Aftermarket service contracts are unbundling from original equipment sales as Asian builders tighten control over spare parts distribution and remote diagnostics access. Direct-sales channels for large-tonnage presses are narrowing as manufacturers capture recurring revenue through captive maintenance networks. This restructuring is most visible in China's industrial clusters, where local content rules favor domestic service providers with real-time inventory positioning.
Stamping Machines Market Segmentation
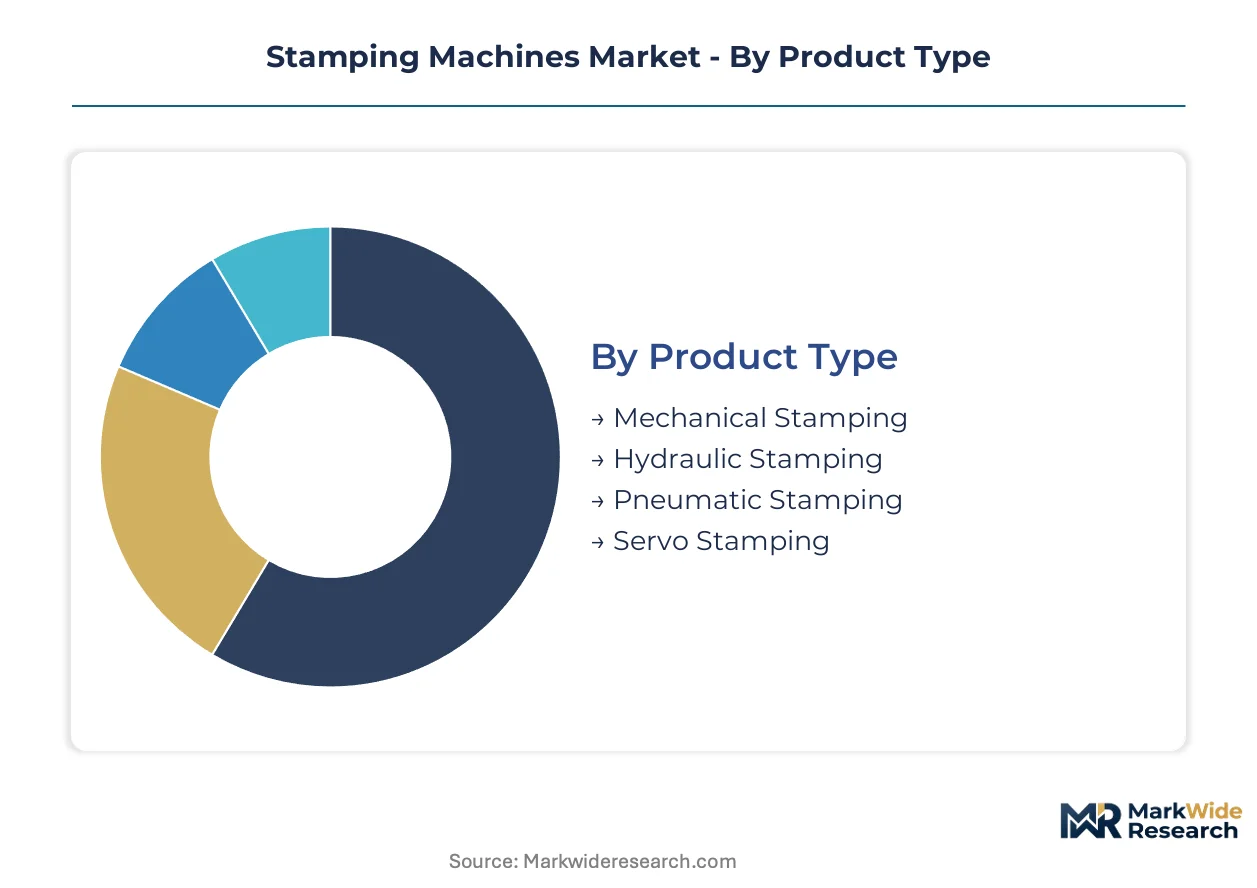
Stamping machine procurement patterns diverge sharply across product architectures and end-use applications. Segment boundaries are blurring as servo technology penetrates traditional mechanical strongholds and electronics manufacturing demands precision beyond legacy press capabilities.
Product Type:
Cost tier separates the four product architectures, with capital intensity and energy efficiency driving substitution patterns across automotive and appliance manufacturing.
- Servo Stamping:Programmable slide motion via direct-drive torque motors enables mid-stroke dwell and warm-forming of advanced high-strength steels. German and Japanese automotive OEMs anchor demand as EU Green Deal carbon targets and METI energy-efficiency mandates accelerate fleet replacement.
- Mechanical Stamping:Flywheel-driven crank mechanisms deliver high-speed blanking at 10-1,500 strokes per minute for high-volume automotive panels. China's Yangtze River Delta cluster sustains residual demand where local content rules favor domestically produced mechanical systems.
- Hydraulic Stamping:Fluid-powered force generation suits deep-draw applications requiring sustained pressure through the forming stroke. Southeast Asian and Latin American secondary markets sustain lower-cost competition.
- Pneumatic Stamping:Compressed-air actuation serves light-gauge precision work in electronics connector housing. Miniaturization trends in semiconductor lead-frame manufacturing are expanding addressable applications.
Servo Stamping holds installed capacity. Mechanical Stamping is rotating up the share rankings.
End User:
Application focus determines specification requirements, with automotive volume dominance contrasting against electronics precision demands.
- Automotive Industry:Structural panel forming and chassis component production consume 30-2,500 metric ton press capacity across progressive and transfer die lines. Gestamp Automoción and tier-one suppliers in Germany and Japan anchor demand through just-in-sequence captive stamping capacity.
- Electronics Manufacturing:Micro-stamping of connector housings and semiconductor lead-frames demands sub-millimeter precision beyond mechanical press capabilities. Connector miniaturization in 5G infrastructure and electric vehicle power electronics is climbing the fastest.
- Aerospace Sector:Titanium and aluminum alloy forming for airframe brackets and engine components requires specialized thermal-mechanical profiles. US and European defense procurement sustains niche demand.
- Consumer Goods:Appliance enclosure blanking and forming serves washing machine, refrigerator, and HVAC housing production. Chinese domestic appliance brands in the Yangtze River Delta drive regional concentration.
Automotive Industry commands capital deployment. Electronics Manufacturing is expanding most quickly.
Technology:
Maturity level distinguishes the four control architectures, with digital integration depth determining competitive differentiation.
- Numerical Control:Computer-programmed slide positioning and force profiling enables repeatable precision across batch sizes. AMADA and Japanese builders differentiate through software-integrated turret-to-press workflows.
- Automatic Operation:Sensor-fed adaptive control with automatic die protection and quality feedback loops supports lights-out manufacturing models. German automotive suppliers lead adoption for overnight production runs.
- Manual Operation:Operator-dependent setup and stroke initiation persists in job-shop environments with high-mix, low-volume profiles. Residual demand concentrates in Indian and Southeast Asian metalworking clusters.
- Hybrid Technology:Combined servo-mechanical architectures blend flywheel energy with programmable motion segments. AIDA Engineering leverages Tokyo R&D capabilities for proprietary hybrid drive patents.
Numerical Control dominates new equipment specifications. Hybrid Technology is gaining share fastest.
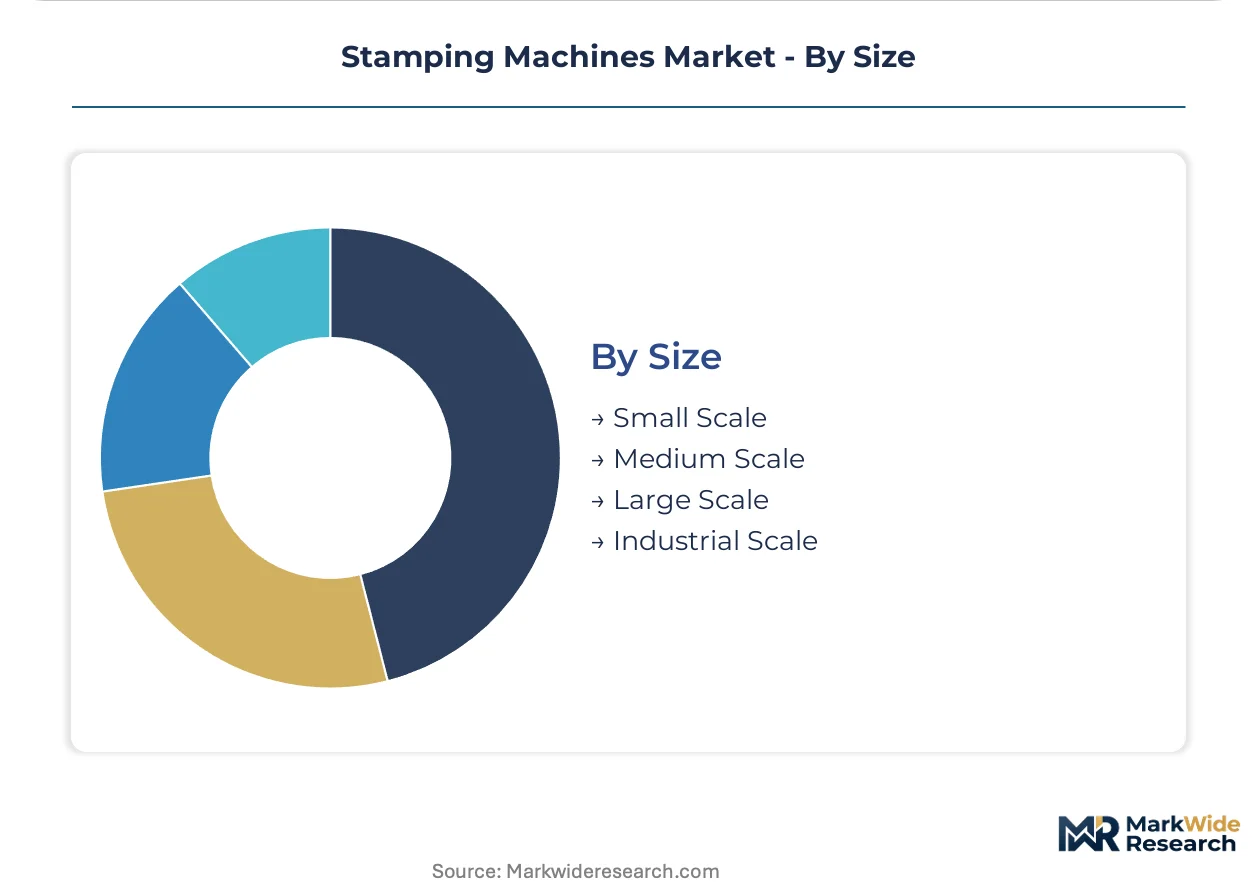
Size:
Volume scale determines facility infrastructure requirements, with press tonnage and footprint driving plant-level capital planning.
- Industrial Scale:Press lines exceeding 1,000 metric tons and 50-meter footprints serve automotive OEM stamping plants with dedicated press shops. German and Japanese OEM headquarters concentrate installed base.
- Large Scale:500-1,000 ton systems with automated transfer mechanisms serve tier-one automotive component suppliers. China's Yangtze River Delta automotive cluster drives regional demand concentration.
- Medium Scale:100-500 ton presses with manual or semi-automatic feed suit contract metalformers serving diversified industrial customers. Indian PLI scheme beneficiaries are expanding medium-scale servo capacity.
- Small Scale:Benchtop and floor-standing units under 100 tons serve prototype development and precision electronics work. Japanese precision component manufacturers anchor premium pricing.
Industrial Scale anchors capital allocation. Medium Scale is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs extract pricing premiums for CE-certified servo presses while Chinese domestic suppliers undercut on first cost in Southeast Asian secondary markets. This asymmetry fragments procurement patterns across developed and emerging manufacturing clusters.
Germany
EU Green Deal carbon targets force fleet-wide replacement of hydraulic systems with energy-efficient servo-electric architectures. KBA vehicle certification rules indirectly mandate cleaner production equipment across supplier tiers. The Baden-Württemberg automotive corridor concentrates captive stamping capacity tied to OEM just-in-sequence programs.
China
Provincial dual carbon goals in Jiangsu and Zhejiang accelerate domestic substitution of imported machine tools. GB standards for mechanical press safety create divergent compliance timelines versus ISO specifications. The Yangtze River Delta cluster absorbs volume demand as local content rules favor domestically produced servo systems.
Japan
METI energy-efficiency mandates drive tier-one suppliers toward programmable slide motion technologies. JIS B 6402 precision benchmarks differentiate premium equipment specifications for export markets. The Chubu region around Nagoya anchors proprietary servo-drive development through concentrated OEM headquarters.
United States
OSHA lockout-tagout rules shape equipment specifications for automotive stamping operations. EPA metalworking fluid emissions standards add compliance engineering cost to domestic installations. The Midwest manufacturing belt sustains residual demand for large-tonnage mechanical presses in established supplier parks.
India
PLI scheme incentives for advanced automotive components attract servo press suppliers establishing local assembly. BIS certification requirements extend equipment approval timelines for imported systems. The Maharashtra-Gujarat industrial corridor drives medium-scale capacity expansion among contract metalformers.
Stamping Machines Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying drive modules and control systems. The vendor base separates into consolidated Japanese-German equipment builders, diversified automotive Tier-1 captives, and emerging Chinese domestic suppliers. Two strategic archetypes dominate: vertically integrated press manufacturers with captive R&D, and automotive suppliers backward-integrating into stamping capacity. Competitive moves concentrate on M&A for servo-drive technology access and geographic expansion through local assembly partnerships.
Among Japanese precision equipment builders, AIDA Engineering Ltd. and AMADA occupy positions reflecting concentrated mechatronics expertise. AIDA Engineering exemplifies the R&D-anchored archetype through its Tokyo-based development operations. AMADA sits within the software-integrated workflow tier where turret-to-press convergence differentiates output quality. Gestamp Automoción represents the automotive-captive model, with stamping capacity tied directly to OEM supply chain integration.
| Leading Market Players |
|---|
| Arconic Corporation |
| Gestamp Automoción |
| Magna International Inc. |
| Aisin Corporation |
| STAMTEC |
| AMADA |
| Chin Fong |
| AIDA Engineering Ltd. |
| BRUDERER AG |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Yangtze River Delta cluster compresses margins for standard mechanical presses while tightening supply for servo-electric systems with proprietary drive architectures. This utilization split rewards builders with captive R&D and aftermarket service networks, while forcing price-responsive competitors toward undifferentiated volume tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order servo presses from standard mechanical systems by a substantial multiple, with programmable slide motion and integrated safety controllers commanding tiered pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling, with CE-marked European equipment carrying brand premiums over Chinese domestic alternatives. Cost compression in the standard mechanical tier is intensifying because secondary markets in Southeast Asia sustain residual hydraulic demand. Tier-one automotive OEMs in Germany and Japan show lowest price sensitivity, while Indian contract metalformers under PLI scheme pressure exhibit highest responsiveness to first-cost positioning.
Supply Chain Analysis
Tariff exposure between China and Western automotive markets dominates supply chain risk planning for multi-regional equipment builders. Rare-earth magnet refining concentrates in China, with servo motor production drawing from neodymium-iron-boron supply chains anchored in Chinese processing operations. Critical inputs include precision ball screws, torque-dense servo drives, and advanced high-strength steel die materials. Single-source vulnerability in rare-earth magnet supply creates input cost volatility that feeds through to total cost of ownership calculations. Distribution runs through manufacturer-captive service networks with localized spare parts inventory, particularly in China's industrial clusters where domestic providers hold regulatory preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stamping machine incumbents face substitution defense against additive manufacturing and advanced casting technologies that threaten geometric complexity applications. Servo-electric architecture leadership remains the critical moat.
For Market Incumbents: Pre-empt commoditization by deepening proprietary servo-drive patent portfolios and tightening aftermarket service network control in China's Yangtze River Delta cluster. Lock in tier-one automotive OEMs through long-term just-in-sequence capacity partnerships that embed switching costs. The threat of Chinese domestic suppliers with local content rule advantages demands rapid certification investment for GB standards compliance. For New Entrants and Emerging Players: India's Maharashtra-Gujarat industrial corridor offers the most penetrable white-space for medium-scale servo press assembly under PLI scheme tariff advantages. Target electronics micro-stamping applications where miniaturization demands exceed current mechanical press capabilities. A software-integrated turret-to-press workflow go-to-market angle differentiates against legacy equipment providers in precision sheet-metal service markets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because servo-drive technology access concentrates among Japanese and German R&D-anchored builders with scarce mechatronics engineering talent. Acquisition targets with hybrid technology patents and established GB standards certification in China warrant premium positioning. Watch rare-earth magnet pricing volatility as the inflection signal for hydraulic-to-servo substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Patent Acquisition | Secures programmable motion capabilities that METI mandates and EU Green Deal carbon targets favor. |
| GB Standards Certification Investment | Unlocks Yangtze River Delta procurement channels where local content rules disadvantage uncertified imports. |
| Aftermarket Service Network Captivity | Captures recurring revenue streams as Asian builders tighten control over spare parts distribution. |
| India Local Assembly Partnership | Captures PLI scheme tariff advantages for medium-scale capacity serving Maharashtra-Gujarat metalformers. |
| Electronics Micro-Stamping Capability Buildout | Addresses connector miniaturization demands in 5G infrastructure and electric vehicle power electronics. |
Research Methodology
A standing panel of plant engineers at tier-one automotive suppliers, aftermarket service heads at Japanese equipment builders, OEM procurement teams in Germany, and controls specialists at servo-drive component manufacturers provided ongoing calibration. Primary interviews combined with secondary validation from SEC filings of listed machine-tool manufacturers, Japanese Ministry of Economy Trade and Industry energy-efficiency disclosures, and EU Machinery Directive implementation guidance. Bottom-up equipment shipment tracking and top-down automotive production capacity modeling enabled triangulation across analysis sources.
Scenario-bracketing framed optimistic and conservative trajectories for servo-electric penetration rates across the projection horizon. Segmentation dimensions modeled include press architecture type, end-use industry concentration, control technology maturity, and facility scale tier. CAGRs derived from fitted growth curves applied to base-year installed capacity estimates, with inputs from rare-earth magnet price indices and automotive OEM capital expenditure plans informing trajectory selection.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic suppliers with state-backed local content advantages would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Bale Openers Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Static Crane Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Baler Market