
 Painting Tools Market | 2026-2036
Painting Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Painting Tools Market Analysis
Skilled painter shortages across developed economies is redrawing how tool suppliers allocate R&D and distribution resources. The Sherwin-Williams Company leverages its captive retail network to bundle applicators with coatings, sustaining repeat purchase velocity. Wooster Brush Company anchors its position through specialized filament technology for premium finishes. Asian Paints Limited competes on cost-engineered rollers and brushes tailored to tropical climate performance.
Painting tools encompass handheld and powered instruments—brushes with flagged-tip synthetic filaments, nap-specified rollers, HVLP spray guns, and containment trays—engineered to transfer coatings onto substrates with controlled film thickness and minimal overspray. Their primary purpose spans architectural finishing, industrial corrosion protection, and automotive refinishing where surface preparation quality dictates coating longevity. Brushes and rollers retain dominance in residential and commercial applications where precision edging and texture control command premium pricing, while spray guns capture industrial and automotive volume where speed and uniform coverage reduce labor hours. Nylon and polyester filaments displace natural bristles across waterborne coating formulations, shifting material procurement strategies among manufacturers.
EPA regulations on volatile organic compound emissions from architectural coatings directly constrain spray gun design specifications and trigger demand for low-overspray technologies in the United States. REACH chemical restrictions and CE marking requirements under the EU Machinery Directive shape product compliance costs and market access thresholds for European distribution. OSHA workplace exposure limits for isocyanates and crystalline silica influence personal protective equipment bundling and tool ventilation features. Stakeholders must weigh regulatory compliance investments against private-label erosion in big-box retail channels.
Market Dynamics
Professional painter shortages across developed economies are forcing tool suppliers to redesign products for lower-skill operators while automating finish quality. This labor compression is accelerating demand for ergonomic, self-leveling applicators that reduce technique dependency.
Growth Catalysts
- Waterborne coating mandates:EPA VOC regulations and REACH restrictions in Europe are phasing out solvent-based formulations. Tool manufacturers are engineering synthetic filament brushes and corrosion-resistant spray systems compatible with these compliant coatings.
- China construction scale:Domestic infrastructure and automotive refinish expansion is concentrating procurement volumes. Local manufacturers are capturing share through climate-adapted roller nap specifications and cost-optimized production.
- DIY renovation persistence:Post-pandemic homeowner tool ownership remains elevated. Retail channels are expanding private-label brush and roller assortments targeting occasional-use buyers.
Market Restraints
- Titanium dioxide volatility:Pigment cost fluctuations compress coating margins and indirectly constrain tool refresh budgets among professional contractors.
- Natural bristle supply concentration:China dominates hog bristle processing for oil-based applications. Trade friction and livestock disease outbreaks disrupt filament availability.
- Spray equipment capital intensity:HVLP and airless systems require compressor infrastructure. Small-scale painters remain locked into manual applicators.
Strategic Opportunities
- India residential construction:Urban housing shortfalls and government affordable housing initiatives are expanding addressable tool demand. Cost-engineered synthetic brushes suited to tropical humidity represent white space.
- Automotive refinish automation:Robotic spray cell integration is creating demand for precision-calibrated gun tips and programmable fluid delivery systems.
- EU Green Deal procurement:Public infrastructure projects are mandating low-carbon material sourcing. Tool suppliers certifying recycled-content handles and bio-based filaments gain specification advantage.
Industry Challenges
- Skilled applicator pipeline collapse:Vocational training programs for finish trades have contracted across Germany, the United Kingdom, and the United States. Manufacturers must simplify tool operation without sacrificing output quality.
- Multi-jurisdiction compliance stacking:CE marking under the EU Machinery Directive, OSHA silica exposure limits, and state-level California VOC rules create overlapping certification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Painting Tools Market |
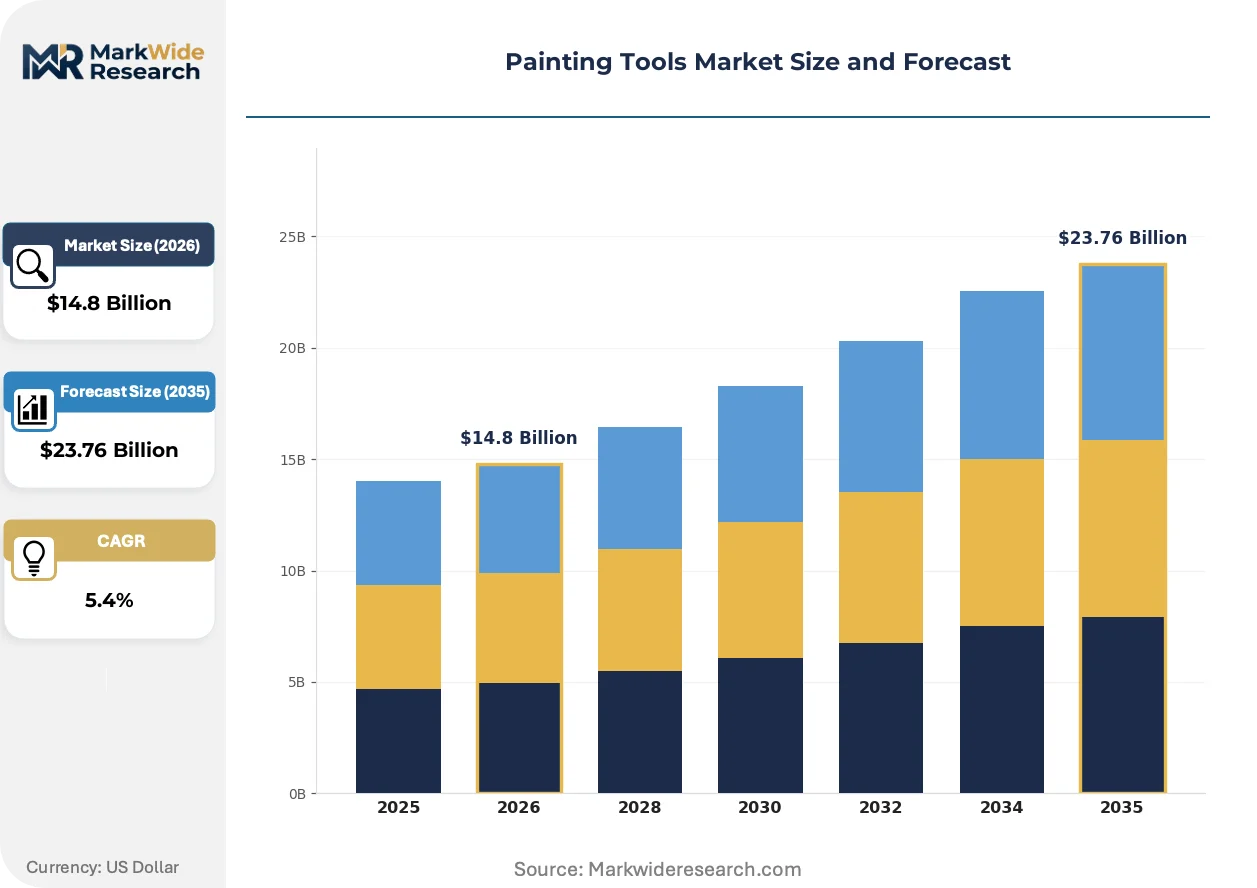
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paint Rollers, Brushes, Spray Guns, Paint Trays Material: Wood, Nylon, Polyester, Foam End User: Professionals, DIY Enthusiasts, Contractors, Industrial Users Application: Residential, Commercial, Automotive, Industrial |
| Companies Covered | Gordon Brush Mfg. Co Inc., The Sherwin-Williams Company, Asian Paints Limited, Wooster Brush Company, Linzer Products Corporation, Purdy Corporation, Mill Rose Company, Braun Brush Co., Allway Tools Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Painting Tools Market Emerging Trajectories
Synthetic filament formulations and digital coating application systems are redrawing competitive boundaries between premium and commodity tool tiers. Suppliers are racing to integrate smart feedback mechanisms that reduce operator error.
Microfiber and advanced polymer filament technologies are fragmenting the traditional brush market. Professional painters in North America and Western Europe are adopting flagged-tip synthetics for waterborne enamel work at accelerating rates. This material shift is fragmenting supplier bases as chemical companies bypass conventional brush manufacturers to sell direct-formulation filament.
REACH chemical restrictions and the EU Green Deal are tightening allowable substance lists for tool components. ECHA substance of very high concern designations are forcing handle resin reformulations and metal plating substitutions. German and French industrial coating contractors are absorbing compliance costs through specification premiums.
Contractor procurement consolidation is compressing distributor margins. Large painting services in the United States are bypassing traditional supply houses for direct manufacturer relationships with volume pricing. This channel disintermediation is most visible in the Sun Belt residential construction belt where national account structures dominate.
Painting Tools Market Segmentation
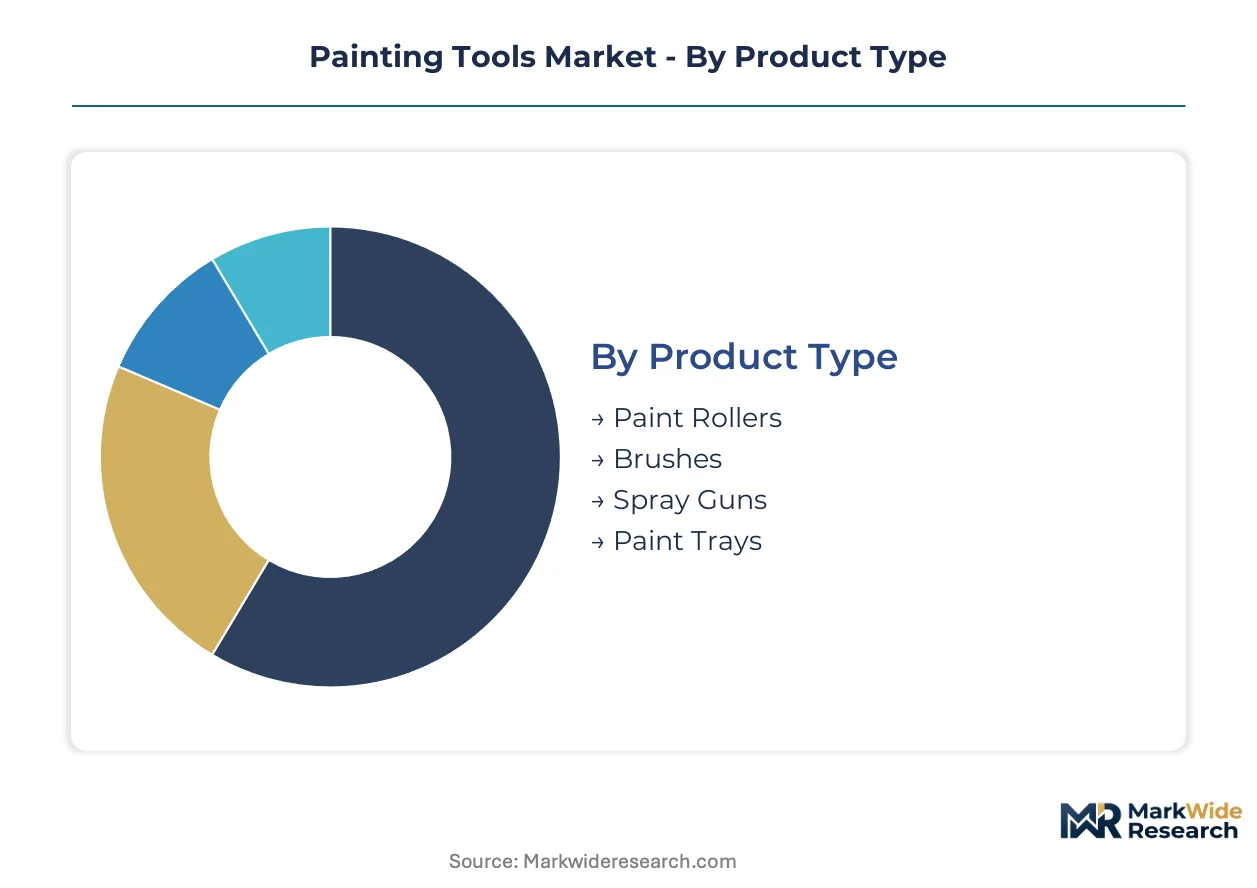
Segmentation in painting tools determines channel allocation, margin structure, and R&D priority. Professional contractors purchase through specialized distributors while DIY buyers concentrate in big-box retail and e-commerce. Material compatibility with waterborne coatings now shapes product development roadmaps across every segment.
Product Type:
Rollers and brushes flow through hardware retail and pro-distributor channels, while spray guns concentrate in industrial supply and automotive refinish specialists. Private-label penetration varies sharply by tool complexity.
- Paint Rollers:Nap-specified fabric cylinders mounted on wire frames, with pile density calibrated to surface texture and coating viscosity. Demand concentrates in North American residential renovation where speed on large wall surfaces reduces labor hours. Foam and microfiber nap materials are displacing traditional lambswool as waterborne latex coatings dominate architectural formulations.
- Brushes:Handheld applicators with flagged-tip synthetic filaments or natural bristles, engineered for edge precision and controlled film thickness. Professional painters in Western Europe specify premium synthetics for waterborne enamel work, driving filament technology differentiation among suppliers.
- Spray Guns:HVLP and airless systems for high-speed coating transfer with minimal overspray. Industrial corrosion protection and automotive refinish applications in Germany and the United States absorb capital-intensive equipment with compressor infrastructure requirements.
- Paint Trays:Containment reservoirs with integrated grids for roller loading and excess removal. Disposable plastic variants capture DIY volume through mass retail while metal trays retain professional preference for durability.
Brushes dominate installed base across all geographies. Spray guns are where expansion concentrates as automotive refinish automation accelerates.
Material:
Cost tier alignment separates premium filament formulations from commodity inputs, with performance certification driving price stratification.
- Nylon:Synthetic polymer filaments with excellent waterborne coating compatibility and shape retention. Professional specification in the United States favors flagged-tip nylon for latex enamel applications where smooth finish quality commands labor premiums.
- Polyester:Lower-cost synthetic alternative with superior solvent resistance for oil-based formulations. Asian manufacturing clusters in China and Vietnam exploit polyester cost engineering for tropical climate roller nap production.
- Wood:Traditional handle material from hardwood stock, now facing sustainability scrutiny under EU Green Deal procurement criteria. German contractors increasingly specify FSC-certified or reclaimed-content handles for public infrastructure projects.
- Foam:Open-cell and closed-cell polymer structures for specialty applicators and disposable trays. DIY channel volume in North American big-box retail absorbs foam products for single-project use with minimal cleanup.
Wood handles retain legacy installed base among traditional painters. Nylon and polyester synthetics are where expansion concentrates as waterborne mandates proliferate.
End User:
Customer type determines purchase frequency, price sensitivity, and support requirements, with professionals demanding durability and DIY buyers prioritizing convenience.
- Professionals:Skilled painters purchasing through distributor channels with volume pricing and technical support. Labor shortages across the United States and Germany are forcing tool simplification for lower-skill operators without quality sacrifice.
- DIY Enthusiasts:Occasional-use homeowners buying through retail and e-commerce with elevated post-pandemic tool ownership persistence. Private-label brush and roller assortments target this segment with economy-tier positioning.
- Contractors:Multi-crew operations consolidating procurement through direct manufacturer relationships, bypassing traditional supply houses. National account structures dominate Sun Belt residential construction in the United States.
- Industrial Users:Maintenance and production facilities specifying corrosion-resistant spray systems for asset protection. OSHA exposure limits for isocyanates and crystalline silica influence ventilation and PPE bundling.
Professionals dominate revenue concentration. Contractors are where expansion concentrates as procurement consolidation accelerates.
Application:
End-use environment dictates tool specification, with surface preparation requirements and coating chemistry driving selection criteria.
- Residential:Architectural finishing in single-family and multi-family housing where brush and roller precision controls aesthetic outcomes. Urban housing shortfalls in India are expanding addressable tool demand for cost-engineered synthetics.
- Commercial:Office, retail, and institutional projects with accelerated schedules favoring roller productivity on large surface areas. EPA VOC regulations constrain spray application in occupied buildings.
- Automotive:Refinish and OEM coating requiring HVLP precision and robotic spray cell integration. German and Japanese automotive manufacturing clusters demand programmable fluid delivery systems.
- Industrial:Corrosion protection for infrastructure, marine, and energy assets where coating longevity depends on surface preparation quality. REACH chemical restrictions shape tool material compliance for European industrial contractors.
Residential dominates unit volume. Automotive is where expansion concentrates as refinish automation and electric vehicle production scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations on volatile organic compound emissions anchor the United States as the dominant geography for spray gun specification and low-overspray technology development. Tool procurement patterns diverge sharply across major economies based on construction intensity, coating chemistry mandates, and labor availability constraints.
United States
Residential renovation activity in the Sun Belt drives brush and roller refresh cycles among professional contractors. EPA VOC regulations constrain spray application in occupied commercial buildings, favoring manual applicators. Dallas-Fort Worth and Phoenix construction clusters absorb volume-priced national account structures.
Germany
Automotive refinish automation in Stuttgart and Wolfsburg manufacturing corridors demands precision-calibrated HVLP systems. REACH chemical restrictions and CE marking under the EU Machinery Directive shape compliance costs for tool imports. Bavarian industrial coating contractors specify recycled-content handles for public infrastructure.
China
Domestic infrastructure scale and automotive refinish sector expansion concentrate procurement volumes. GB standards and MEE environmental enforcement push low-VOC coating compatibility in tool design. Yangtze River Delta manufacturing clusters produce cost-optimized synthetic filament for tropical climate performance.
India
Urban housing shortfalls and government affordable housing initiatives expand addressable tool demand. BIS certification requirements and DGFT import regulations shape market access for foreign suppliers. Maharashtra and Gujarat construction corridors absorb cost-engineered brushes suited to high-humidity application.
Japan
Automotive OEM coating precision requirements in Toyota City and Yokohama clusters drive robotic spray cell integration. METI industrial standards and JIS certification govern tool performance specifications. Kansai region refinish specialists specify programmable fluid delivery systems for electric vehicle production scale-up.
Painting Tools Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with coating-captive retailers and independent brush fabricators occupying distinct competitive positions. The structure rewards filament technology differentiation in premium waterborne applications while cost engineering dominates tropical climate markets. Two archetypes predominate: coating-captive distributors leveraging retail network bundling, and filament specialists commanding specification premiums through material science. Competitive moves concentrate on direct manufacturer relationships with consolidated contractor accounts and sustainability certification for EU Green Deal procurement eligibility.
Among coating-captive retailers, The Sherwin-Williams Company exemplifies the integrated distribution archetype through its captive retail network. Wooster Brush Company and Asian Paints Limited represent contrasting specialization strategies—premium filament technology versus cost-engineered tropical climate adaptation. These three anchors illustrate how geographic market requirements fragment competitive positioning between specification-driven and volume-driven procurement channels.
| Leading Market Players |
|---|
| Gordon Brush Mfg. Co Inc. |
| The Sherwin-Williams Company |
| Asian Paints Limited |
| Wooster Brush Company |
| Linzer Products Corporation |
| Purdy Corporation |
| Mill Rose Company |
| Braun Brush Co. |
| Allway Tools Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between synthetic filament producers and brush manufacturers lock in both hog bristle substitution supply and forward price visibility as REACH compliance costs harden material specifications. These contracts insulate premium tool suppliers from titanium dioxide volatility while exposing commodity tier producers to spot market filament squeezes.
Pricing Analysis
Price spreads between German automotive-grade HVLP systems and Southeast Asian manual applicators exceed threefold, reflecting CE marking compliance burdens and precision calibration requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by filament certification grade and handle sustainability credentials. Pricing pressure stems from private-label expansion in North American big-box retail compressing branded brush margins. DIY enthusiasts exhibit highest price sensitivity while German industrial contractors absorb specification premiums for REACH-compliant synthetic filaments.
Supply Chain Analysis
Inventory cycles for natural hog bristle extend to six months as livestock disease outbreaks in China disrupt processing volumes and trigger allocation protocols among European brush fabricators. Manufacturing gravity centers on China for cost-optimized polyester filament, Germany for precision-engineered spray systems, and Vietnam for tropical-climate roller nap production. Raw material dependencies encompass petroleum-derived synthetic polymers, FSC-certified hardwood stock, and corrosion-resistant metal alloys for industrial spray components. Single-source vulnerability concentrates in Chinese hog bristle processing for oil-based coating applications. Distribution runs through specialized pro-distributor channels for contractor-grade equipment and mass retail for DIY consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The painting tools market sits in early-cycle expansion as waterborne coating mandates across EPA and REACH jurisdictions force tool replacement waves incompatible with legacy natural bristle inventories.
For Market Incumbents: Secure direct manufacturer relationships with Sun Belt residential contractors consolidating procurement through national account structures, bypassing traditional distributor margins. Deepen backward integration into flagged-tip synthetic filament production to defend against chemical companies selling direct-formulation materials. Prioritize EU Green Deal certification for recycled-content handles to capture Bavarian public infrastructure specification premiums.
For New Entrants and Emerging Players: Lead with cost-engineered synthetic brushes tailored to Maharashtra and Gujarat construction corridors where tropical humidity degrades conventional filament performance. Target India's affordable housing initiative procurement channels before incumbent coating-captive retailers establish localized bundling. Emphasize climate-adapted roller nap specifications as the primary technical wedge against established synthetic suppliers.
For Investors and Strategic Acquirers: Filament technology specialists with proprietary polymer formulations represent the most defensible acquisition archetype as waterborne coating compatibility becomes non-negotiable across professional specification. Long-term viability hinges on regulatory compliance capability rather than manufacturing scale alone. Monitor ECHA substance of very high concern designations as the critical inflection signal for forced handle resin reformulations and stranded asset risk in legacy tool inventories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Filament | Chemical companies bypassing brush manufacturers threaten core input access for premium waterborne applications. |
| EU Green Deal Certification Program | German and French public infrastructure projects now mandate recycled-content handles and bio-based filaments. |
| Direct Manufacturer Relationship Structure | Sun Belt national accounts bypass distributor margins and lock in volume pricing with consolidated contractors. |
| Climate-Adapted Product Line Expansion | Maharashtra and Gujarat construction corridors require humidity-resistant synthetics absent from standard portfolios. |
| Robotic Spray Cell Integration Partnership | Stuttgart and Wolfsburg automotive clusters demand programmable fluid delivery systems for refinish automation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from coating-captive retailers, and EU ECHA substance restriction notifications. Interviews with professional painting contractors, distributor procurement managers, synthetic filament R&D directors, and automotive refinish equipment specialists informed demand-side assumptions. Top-down market sizing from construction activity indices and coating consumption figures triangulated against bottom-up unit economics from brush and roller manufacturer cost structures.
Segmentation dimensions modeled encompass product type, filament material grade, end-user archetype, and application environment across the projection horizon. CAGRs derive from regression analysis of historical tool refresh cycles against coating formulation shift timelines. Forecast inputs include EPA VOC enforcement intensity, REACH substance restriction phase-ins, and automotive refinish automation adoption curves in German and Japanese manufacturing clusters.
The analysis sits within stated boundaries; outcomes outside sustained waterborne coating mandate enforcement or accelerated skilled painter shortage trajectories would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and contractor procurement consolidation velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Machining Centers Market
Tools
Pruning Saw Market
Tools
Power Nibbler Market
Tools
Workholding Tools Market
Tools
Grinding Machines Market
Tools
Aluminum Folding Ladders Market
Tools
Metal Forming Tools Market
Tools
Theodolite Market
Tools
Wire Cutters Market
Tools
Horizontal Milling Machine Market
Tools
Mechanical Puller Market
Tools
Woodworking CNC Tools Market
Tools
Leather Cutting Machine Market
Tools
Woodworking Power Tools Market
Tools
Impact Wrenches Market
Tools
Digital Cutting Machine Market