
 Deburring Tool Market | 2026-2036
Deburring Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Deburring Tool Market Analytics
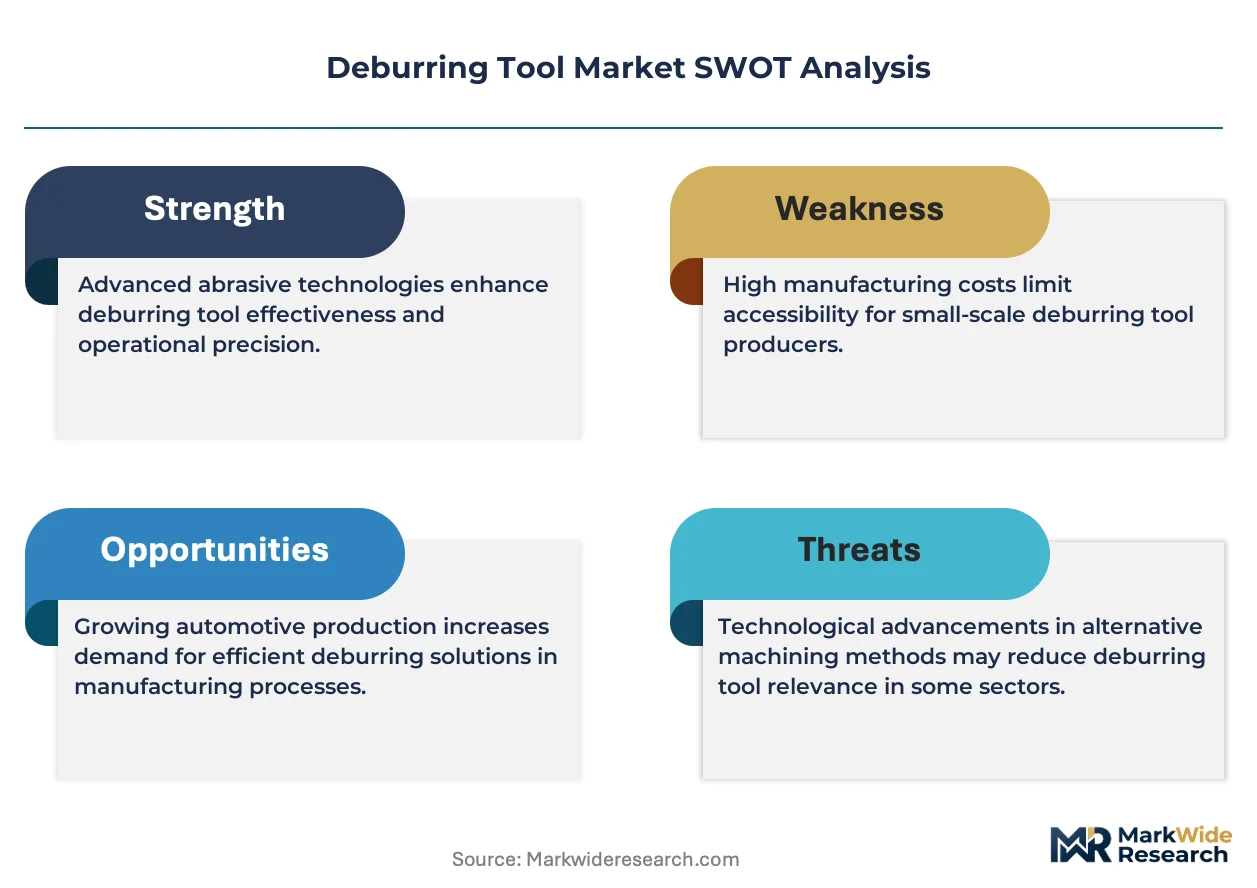
REACH is rebalancing the cost-of-entry calculus for European deburring tool suppliers, favoring non-abrasive chemistries and closed-loop coolant systems over traditional abrasive methods. ATI Industrial Automation leverages its robotic end-effector expertise to dominate automated deburring cells in automotive stamping plants. Heule anchors its position through patented back-spotfacing and deburring tools that eliminate secondary operations in aerospace through-hole finishing. BORIDE Engineered Abrasives specializes in bonded abrasive points and stones, sustaining margins via deep vertical integration into ceramic grain supply.
A deburring tool removes burrs, sharp edges, and residual material from machined, cast, or stamped workpieces using mechanical cutting edges, abrasive media, pneumatic rotation, ultrasonic cavitation, or electrochemical dissolution. These tools operate at rotational speeds from 3,000 to 50,000 RPM for power units, with carbide, high-speed steel, or diamond-impregnated cutting surfaces chosen based on workpiece hardness and edge-radius specifications. Power deburring tools command the largest revenue share due to throughput requirements in high-volume automotive and metalworking environments, while ultrasonic technology represents the fastest-expanding segment as electronics manufacturers adopt cavitation-based finishing for fragile substrates. Manual deburring tools retain entrenched demand in job shops and prototype work where setup flexibility outweighs cycle-time optimization.
The EPA governs metalworking fluid emissions and waste classification in the United States, directly influencing tool selection and coolant system design, while REACH and the EU Machinery Directive shape material restrictions and operator safety requirements across European manufacturing. ISO 9001 and AS9100 quality certifications function as de facto market-access filters, particularly for aerospace and medical device supply chains. Stakeholders must monitor evolving dual-carbon regulations in China and tightening surface-finish specifications from medical OEMs, as these forces will determine which technology platforms capture the next wave of specification-driven replacement demand.
Market Dynamics
Automotive and aerospace OEMs are consolidating their supplier bases around certified deburring protocols, forcing tool vendors to absorb compliance costs while defending margin positions through captive abrasive supply and automated cell integration.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on abrasive composition are accelerating migration toward ultrasonic and electrochemical finishing platforms in German precision engineering clusters.
- AS9100 certification requirements:Aerospace tier-1 suppliers in the United States now specify documented edge-radius protocols, creating specification-driven replacement cycles for carbide-insert tools.
- Automotive stamping automation:High-volume press shops are retrofitting robotic deburring cells to eliminate secondary finishing stations and reduce work-in-process inventory.
Market Restraints
- Ceramic grain supply concentration:Synthetic abrasive feedstock production clusters in China's Henan province expose Western toolmakers to export control volatility and freight cost spikes.
- Ultrasonic equipment capex thresholds:Cavitation generator systems require substantial upfront investment, limiting adoption among sub-$10M revenue job shops.
- EPA waste classification friction:Metalworking fluid disposal regulations in the United States extend coolant system payback periods, dampening enthusiasm for closed-loop ultrasonic installations.
Strategic Opportunities
- Medical device miniaturization:Swiss and German orthopedic implant manufacturers are specifying sub-10-micron edge-radius tolerances for titanium spinal hardware, opening specification windows for diamond-impregnated micro-tools.
- EU Green Deal capital subsidies:Closed-loop coolant recovery systems qualify for national recovery-fund grants in Italy and Spain, reducing effective equipment costs for mid-size metalworking operations.
- Electronics substrate fragility:Semiconductor packaging facilities in South Korea and Taiwan are adopting cavitation-based finishing to replace mechanical abrasion on glass-reinforced epoxy laminates.
Industry Challenges
- Multi-axis programming competency gaps:Automated deburring cell deployment requires CAM specialists fluent in robotic path optimization, a skill set scarce in traditional tool-and-die regions.
- ISO 9001-to-AS9100 certification timelines:Aerospace supplier qualification processes extend 14-18 months, freezing out vendors lacking prior tier-1 exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deburring Tool Market |
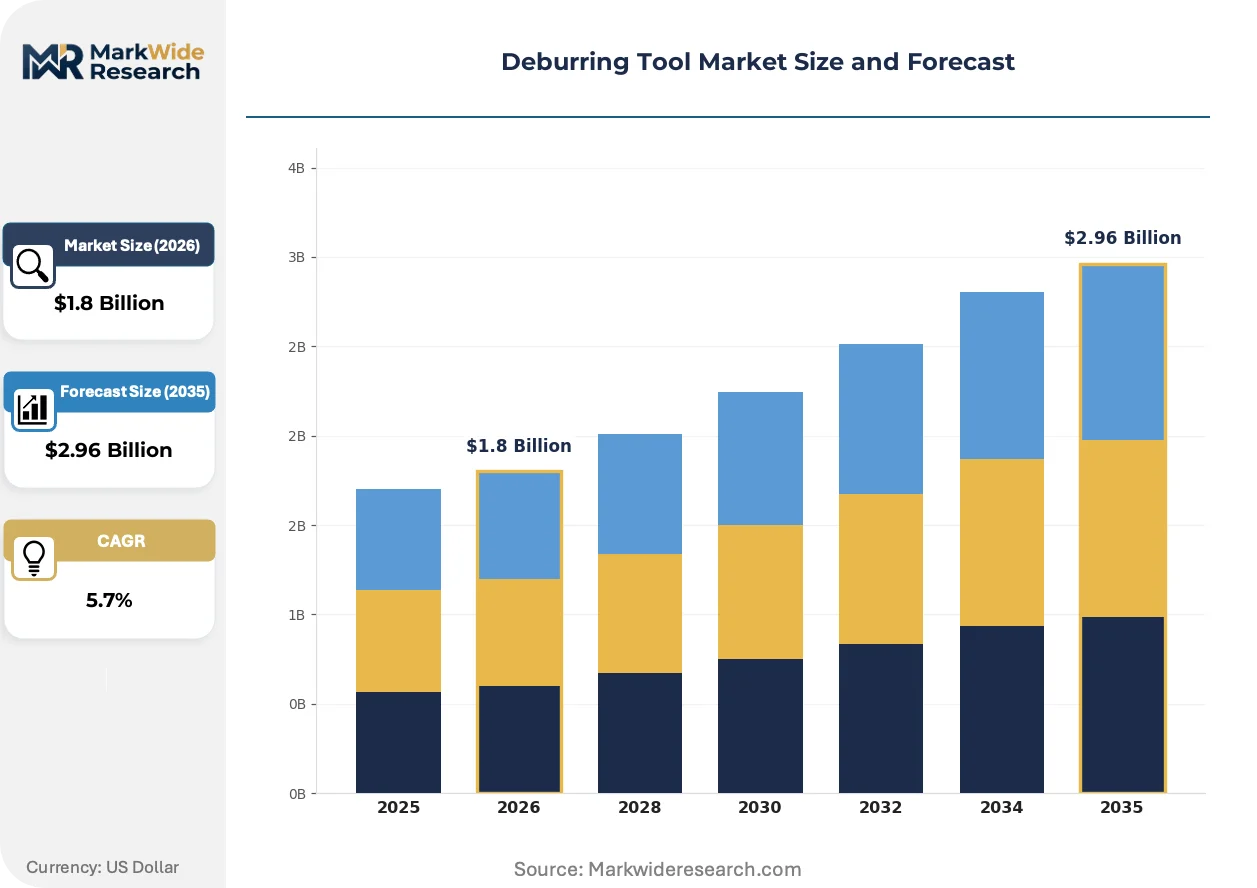
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Deburring Tools, Power Deburring Tools, Abrasive Deburring Tools, Non-Abrasive Deburring Tools Technology: Mechanical, Pneumatic, Electrical, Ultrasonic End User: Automotive, Aerospace, Electronics, Metalworking Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Nitto Kohki U.S.A., Inc., BORIDE Engineered Abrasives, ATI Industrial Automation, Noga Engineering & Technology Ltd., Vargus Ltd., Cogsdill Tool, APEX, Heule, Assfalg GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deburring Tool Market Evolving Landscape
Process automation and regulatory chemistry restrictions are converging to compress the viable technology set, favoring vendors who control both abrasive formulation and robotic integration capabilities.
Ultrasonic cavitation finishing is decentralizing precision deburring from centralized job shops to captive in-house operations. Electronics manufacturers in South Korea and Taiwan now deploy compact tabletop units for real-time substrate conditioning. This technology is decentralizing quality control responsibility from specialized subcontractors to OEM production engineers.
REACH Annex XVII restrictions on crystalline silica content are forcing bonded abrasive reformulations across European supply chains. Tool manufacturers must recertify product lines with ECHA-notified bodies before market re-entry. German automotive stamping plants are responding by accelerating trials of diamond-impregnated polymer bonds that bypass silica entirely.
Buyer consolidation among tier-1 aerospace suppliers is compressing vendor qualification cycles and unbundling after-sales service from equipment procurement. United States-based landing-gear manufacturers now separate tooling capital expenditure from consumables contracts, forcing deburring specialists to compete on abrasive cost-per-part rather than system integration. This pattern is most visible in Connecticut and Ohio machining corridors where Boeing and Airbus supply chains overlap.
Deburring Tool Market Segmentation
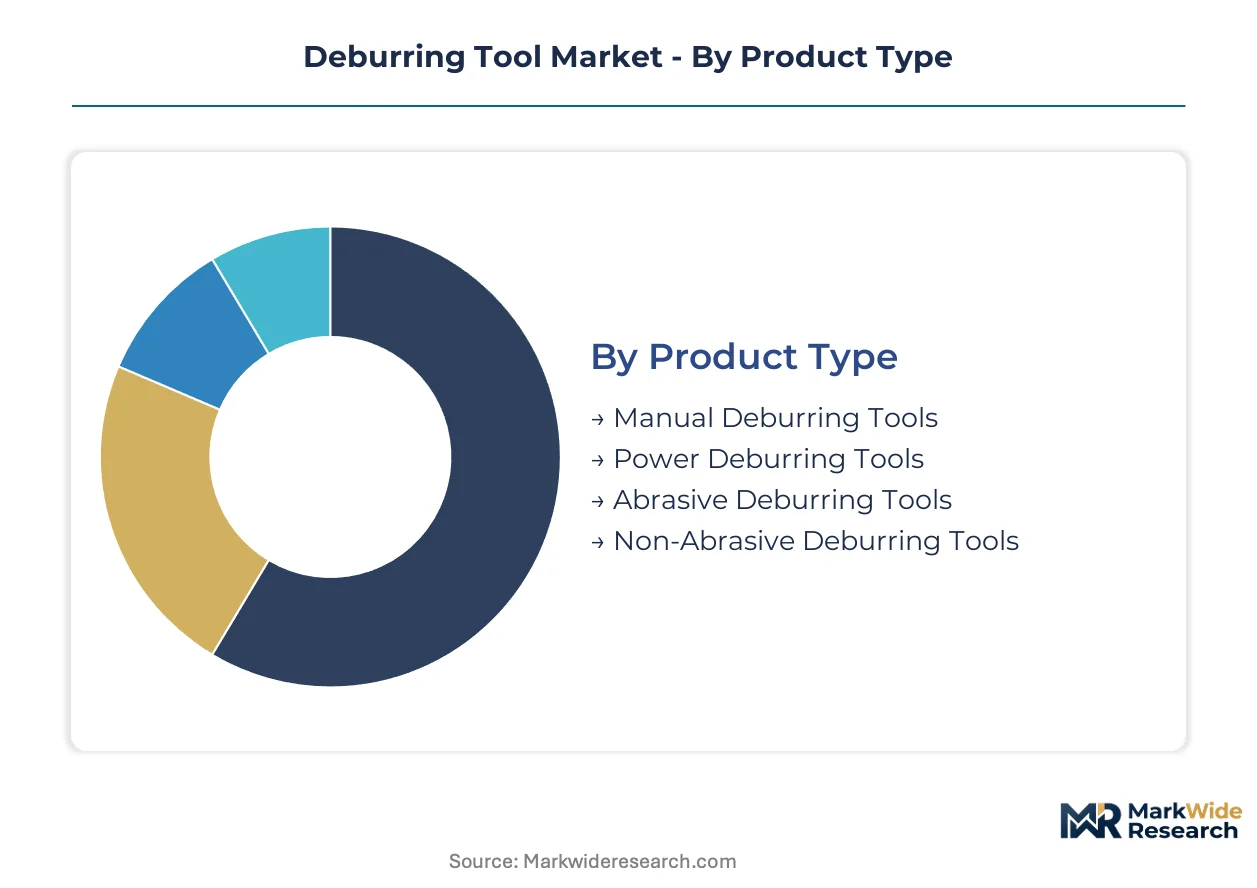
Technology selection in deburring tools determines capital intensity, regulatory exposure, and automation compatibility. Specification-driven buyers in aerospace and medical device supply chains now segment vendors by certification depth rather than catalog breadth alone.
Product Type:
Rotational speed and cutting-edge composition define the performance envelope across manual, power, abrasive, and non-abrasive platforms.
- Power Deburring Tools:These units operate at 3,000 to 50,000 RPM with carbide or diamond-impregnated cutting surfaces. Automotive stamping plants in Germany and the United States specify these for high-volume edge-radius consistency under AS9100 protocols.
- Non-Abrasive Deburring Tools:Electrochemical and ultrasonic platforms dissolve or cavitate burrs without mechanical contact. REACH Annex XVII compliance in Europe is accelerating replacement of bonded abrasives with these chemistries in precision engineering corridors.
- Manual Deburring Tools:Hand-held scrapers, files, and blade tools dominate prototype work and job shops where setup flexibility outweighs cycle-time optimization.
- Abrasive Deburring Tools:Bonded stones and points using ceramic grain or diamond grit remain entrenched in metalworking environments with established coolant recovery systems.
Mature deployment sits with abrasive and manual tools in legacy metalworking. Newer deployment is concentrated in non-abrasive platforms for REACH-compliant European operations.
Technology:
Energy transfer mechanism determines surface integrity, substrate compatibility, and operator safety classification under EU Machinery Directive.
- Mechanical:Direct-contact cutting edges using high-speed steel or carbide inserts. These systems dominate aerospace through-hole finishing where documented edge-radius protocols are mandatory for tier-1 supplier qualification.
- Ultrasonic:Cavitation generators produce microscopic bubble collapse for fragile substrate finishing. Electronics manufacturers in South Korea and Taiwan deploy compact tabletop units for real-time glass-reinforced epoxy laminate conditioning.
- Pneumatic:Compressed-air-driven rotary tools deliver portable deburring for field maintenance and on-site aerospace MRO operations.
- Electrical:Corded and battery-powered units bridge the gap between pneumatic portability and mechanical precision in mid-volume metalworking shops.
Mechanical technology retains the broadest installed base. Ultrasonic systems are climbing the fastest as semiconductor packaging facilities replace mechanical abrasion.
End User:
Surface-finish specifications and production scale create distinct procurement patterns across automotive, aerospace, electronics, and general metalworking.
- Automotive:High-volume stamping and powertrain operations require robotic deburring cells with documented process control. OEM consolidation around certified suppliers is compressing vendor lists in German and US manufacturing corridors.
- Aerospace:AS9100 certification and FAA traceability requirements favor vendors with prior tier-1 exposure. Landing-gear manufacturers in Connecticut and Ohio now separate tooling capital expenditure from consumables contracts.
- Electronics:Miniaturization and substrate fragility drive demand for non-contact finishing. Swiss and German orthopedic implant manufacturers specify sub-10-micron edge-radius tolerances for titanium spinal hardware.
- Metalworking:General job shops and contract manufacturers balance flexibility against throughput, sustaining demand for manual and power tool portfolios.
Automotive represents the largest procurement volume by unit count. Electronics is gaining share fastest as cavitation technology penetrates semiconductor packaging.
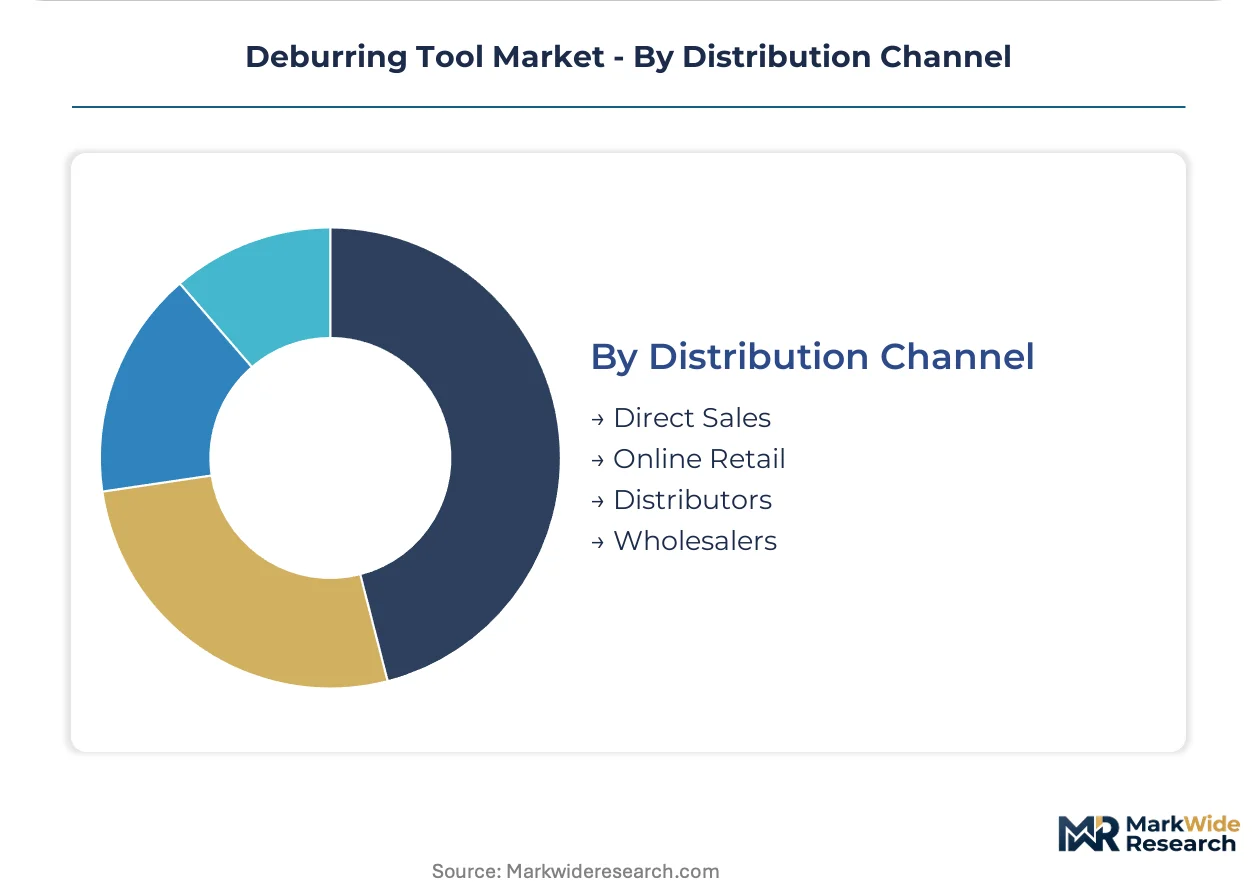
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and inventory velocity in consumables replenishment.
- Distributors:Regional industrial supply houses provide same-day availability and application engineering for mid-size metalworking operations. These intermediaries dominate abrasive consumables replenishment in fragmented job shop markets.
- Direct Sales:System integrators and robotic cell vendors engage OEMs and tier-1 suppliers for specification-driven equipment procurement. Aerospace landing-gear manufacturers in the United States prefer direct engagement for AS9100-compliant documentation packages.
- Online Retail:E-commerce platforms capture standard manual tools and replacement consumables for small job shops and maintenance departments.
- Wholesalers:Volume aggregators serve secondary distributors and export markets with limited technical support requirements.
Direct sales commands the highest value per transaction for automated cells. Distributors handle the greatest transaction frequency in abrasive consumables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering corridors and US aerospace machining clusters concentrate specification-driven procurement, while East Asian electronics manufacturers accelerate non-abrasive platform adoption. Regulatory chemistry restrictions and automation mandates are redrawing competitive access across manufacturing geographies.
United States
Automotive stamping plants in Michigan and Ohio retrofit robotic deburring cells to eliminate secondary finishing stations. EPA metalworking fluid emissions guidelines extend coolant system payback periods, dampening closed-loop ultrasonic enthusiasm. Connecticut landing-gear manufacturers now separate tooling capital expenditure from consumables contracts under Boeing and Airbus supply chain protocols.
Germany
Automotive and medical device OEMs in Baden-Württemberg and Bavaria specify certified deburring protocols with sub-10-micron edge-radius tolerances. REACH Annex XVII crystalline silica restrictions force bonded abrasive reformulations through ECHA-notified bodies. Stuttgart-area precision engineering clusters accelerate trials of diamond-impregnated polymer bonds that bypass silica entirely.
China
Synthetic abrasive feedstock production concentrates in Henan province, exposing Western toolmakers to export control volatility and freight cost spikes. Dual carbon regulations tighten energy intensity requirements for ceramic grain furnaces. Yangtze River Delta metalworking operations balance cost pressures against incoming environmental compliance deadlines.
South Korea
Semiconductor packaging facilities in Gyeonggi-do deploy compact tabletop ultrasonic units for real-time glass-reinforced epoxy laminate conditioning. MFDS medical device surface-finish specifications drive specification windows for precision finishing equipment. Seoul Capital Area electronics manufacturers displace mechanical abrasion with cavitation-based finishing for fragile substrates.
Switzerland
Orthopedic implant manufacturers in the Jura Arc and Lake Geneva region specify sub-10-micron edge-radius tolerances for titanium spinal hardware. Swissmedic quality certifications function as de facto market-access filters for medical device supply chains. Swiss precision machining clusters source diamond-impregnated micro-tools for miniaturized component finishing.
Deburring Tool Market Competitive Landscape
German and Swiss producers anchor one tier with precision-engineered mechanical systems; Japanese specialists hold another through compact power tool portfolios. The vendor base splits between consolidated robotic cell integrators and fragmented consumables suppliers. Three archetypes dominate: automated cell specialists, bonded abrasive formulators, and ultrasonic platform developers. Competitive moves center on captive abrasive supply and strategic partnerships with CAM software vendors.
Among precision-engineered mechanical specialists, Heule exemplifies the automated aerospace tier through patented back-spotfacing architectures, while BORIDE Engineered Abrasives occupies a position within bonded abrasive formulation through in-house ceramic grain supply. ATI Industrial Automation represents the robotic integration archetype, anchoring automated deburring cells in high-volume automotive environments. These three entities illustrate how control over either abrasive chemistry or robotic path optimization determines specification-driven procurement access.
| Leading Market Players |
|---|
| Nitto Kohki U.S.A., Inc. |
| BORIDE Engineered Abrasives |
| ATI Industrial Automation |
| Noga Engineering & Technology Ltd. |
| Vargus Ltd. |
| Cogsdill Tool |
| APEX |
| Heule |
| Assfalg GmbH |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between aerospace-qualified and general metalworking tiers splits both pricing power and sourcing configurations across the deburring tool landscape. AS9100-compliant carbide-insert systems command substantial premiums through documented edge-radius protocols, while commodity abrasive consumables compete on cost-per-part metrics in fragmented job shop markets. REACH-driven reformulation costs in Europe and ceramic grain supply volatility from China concentrate margin pressure on mid-tier bonded abrasive suppliers.
Pricing Analysis
High-volume automotive contracts trade margin for throughput guarantees, while precision aerospace procurement separates equipment capital expenditure from consumables contracts. Pricing stratifies across premium, standard, and economy tiers based on certification depth and automation compatibility. Cost compression in commodity abrasives is intensifying because of synthetic grain supply concentration in Henan province. Tier-1 aerospace suppliers exhibit lowest price sensitivity due to specification-driven replacement cycles; sub-$10M revenue job shops remain most price-sensitive, deferring ultrasonic system adoption.
Supply Chain Analysis
Synthetic ceramic grain production rests on Chinese furnace operations in Henan province, German precision machining clusters, and Japanese bonded abrasive formulators. Critical inputs span silicon carbide feedstock, diamond-impregnated polymer bonds, and cavitation generator electronics. Single-source vulnerability concentrates in Chinese abrasive feedstock exposed to export control volatility and dual carbon regulation compliance costs. Distribution runs through regional industrial supply houses for consumables replenishment, with direct sales dominating automated cell procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deburring tool sector sits in a technology-transition phase as ultrasonic cavitation displaces mechanical abrasion for fragile substrate finishing. This shift reconfigures competitive access around chemistry control and robotic integration capabilities.
For Market Incumbents: Cement specification-driven procurement access through captive abrasive supply and AS9100 certification maintenance. Absorb REACH compliance costs via closed-loop coolant system integration to defend margin positions against non-abrasive platform entrants. Prioritize robotic path optimization partnerships with CAM software vendors to lock in automotive stamping plant retrofits.
For New Entrants and Emerging Players: Swiss orthopedic implant manufacturers represent an underserved buyer archetype demanding sub-10-micron edge-radius tolerances for titanium spinal hardware. Target South Korean semiconductor packaging facilities adopting tabletop ultrasonic units for real-time substrate conditioning. Pursue specification windows in medical device miniaturization through diamond-impregnated micro-tool development.
For Investors and Strategic Acquirers: Re-rating potential sits with ultrasonic platform developers given electronics substrate fragility trends and REACH Annex XVII chemistry restrictions. Long-term viability over a five-to-ten-year window favors vendors controlling both abrasive formulation and robotic integration capabilities. Watch for dual carbon regulation enforcement in China as an inflection indicator for ceramic grain supply restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grain Supply | Henan province feedstock concentration creates vulnerability for Western bonded abrasive formulators. |
| AS9100 Certification Investment | Connecticut and Ohio landing-gear manufacturers require documented edge-radius protocols for tier-1 access. |
| Ultrasonic Platform Development | South Korean semiconductor packaging facilities adopt cavitation-based finishing for glass-reinforced epoxy laminates. |
| Closed-Loop Coolant System Deployment | EU Green Deal capital subsidies in Italy and Spain reduce effective equipment costs for mid-size metalworking operations. |
| CAM Software Partnership | Multi-axis programming competency gaps constrain automated deburring cell deployment in traditional tool-and-die regions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this deburring tool analysis. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners combined with ECHA regulatory databases, EPA emissions guidelines, ISO certification registries, and aerospace tier-1 supplier qualification documents. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling operated at product type, technology platform, end-user industry, and distribution channel dimensions. CAGRs derived from shipment volume trajectories and value-per-unit trends across power, non-abrasive, manual, and abrasive tool categories. Forecast inputs incorporated REACH Annex XVII reformulation timelines, automotive stamping automation retrofit rates, and electronics substrate miniaturization specifications.
Revisions become necessary when dual carbon regulation enforcement accelerates in China, REACH restrictions expand beyond crystalline silica, or aerospace supplier consolidation triggers vendor list compression. Forecasts reflect assumptions about regulatory compliance cost absorption and technology substitution elasticities. A small set of named triggers—ceramic grain export controls, ultrasonic equipment capex thresholds, and EPA waste classification friction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Machine Vise Market
Tools
Post Drivers Market
Tools
Automated Plasma Beveller Market
Tools
Tool Pliers Market
Tools
Sanding Machine Market
Tools
Industrial Plate Bending Machines Market
Tools
Portable Boring Machines Market
Tools
Floor Saw Market
Tools
Woodworking Circular Saw Blades Market
Tools
Leather Cutting Machine Market
Tools
Wood-Sanding Machine Market
Tools
Clamps Market
Tools
Gear Cutting Machines Market
Tools
Telescopic Tool Boxes Market
Tools
Global Sandblasting Media Market
Tools
Water Pump Pliers Market