
 Compression Garments and Stockings Market | 2026-2036
Compression Garments and Stockings Market Size, Share, and Industry Trends Forecast 2026-2036
Compression Garments and Stockings Market Analysis
Asset-light contract manufacturing and private-label leasing arrangements is narrowing the capital barrier for new entrants in compression textiles. SIGVARIS GROUP leverages its Swiss manufacturing heritage to sustain premium positioning across European and North American hospital channels. Juzo anchors its competitiveness through in-house knitting operations that control yarn tension and graduated compression precision. JOBST competes on brand recognition among lymphedema therapists and vascular clinics.
Compression garments and stockings are elastic textile products engineered with graduated pressure gradients, typically measured in millimeters of mercury (mmHg), designed to enhance venous return and reduce peripheral edema through controlled mechanical compression. Manufacturing employs circular knitting machines with programmable needle selection to create zoned compression profiles that taper from distal to proximal limb segments. Stockings dominate hospital procurement budgets, while sleeves capture expanding share among athletic recovery programs. Wraps occupy a niche in adjustable compression for post-operative patients with fluctuating limb volume. The material dimension stratifies sharply: nylon-spandex blends lead clinical-grade output, while cotton-elastic hybrids serve consumer wellness segments.
FDA Class I device exemptions shape US market access timelines, while the EU MDR recertification process tightens clinical evidence requirements for compression products sold in Germany and France. ISO 13485 quality management standards govern supplier qualification for OEM relationships. Stakeholders must monitor reimbursement code revisions by Medicare and parallel national health systems, as compression therapy coverage determinations directly influence physician prescribing behavior and patient out-of-pocket exposure.
Market Dynamics
The compression garments sector faces structural pressure from the EU MDR recertification timeline, which compresses five-year compliance windows and forces manufacturers to consolidate clinical evidence portfolios ahead of May 2027 deadlines.
Growth Catalysts
- Post-surgical rehabilitation protocols:Orthopedic wards in Germany and the United States now mandate graduated compression as standard discharge protocol. Hospital procurement teams embed compression garments into bundled payment structures for knee and hip replacement pathways.
- FDA Class I device exemptions:Streamlined 510(k) clearance pathways accelerate manufacturer entry into vascular therapy segments. The exemption category eliminates premarket notification requirements for non-powered compression garments.
- Circular knitting automation:Programmable needle selection technology enables zoned compression profiles with single-machine production runs. Medical textile converters reduce changeover downtime between stocking and sleeve specifications.
Market Restraints
- Spandex price volatility:Polyurethane fiber costs fluctuate with crude oil derivatives and textile chemical feedstock markets. Manufacturers lack long-term hedging instruments for elastomer inputs.
- Clinical evidence concentration:Large-scale randomized trials for lymphedema outcomes cluster in Swiss and Dutch research hospitals. Smaller manufacturers cannot sponsor independent compression efficacy studies.
- Garment substitution by pneumatic devices:Intermittent pneumatic compression systems capture share in acute care settings with adjustable pressure algorithms. Pneumatic units offer real-time pressure monitoring that static garments cannot match.
Strategic Opportunities
- Athletic recovery programs:Professional cycling teams and marathon training facilities in Colorado and Arizona procure compression sleeves as recovery infrastructure. Sports medicine clinics represent uncaptured volume outside hospital procurement channels.
- PLA biodegradable yarns:Polylactic acid fiber development enables compostable compression garments for single-use post-operative applications. Material science partnerships with agricultural biopolymer suppliers open sustainability positioning.
- Telehealth prescription integration:Remote patient monitoring platforms in the United States incorporate compression adherence tracking. Digital therapeutics vendors seek garment partnerships for venous insufficiency management programs.
Industry Challenges
- Graduated compression calibration expertise:Precision knitting technicians who understand mmHg gradient engineering remain scarce in Southeast Asian manufacturing hubs. Training programs for circular machine programming lag demand.
- ISO 13485 certification timelines:Quality management system audits for medical device textiles extend 14-18 months with notified body backlogs. New entrants face working capital strain during pre-revenue compliance phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compression Garments and Stockings Market |
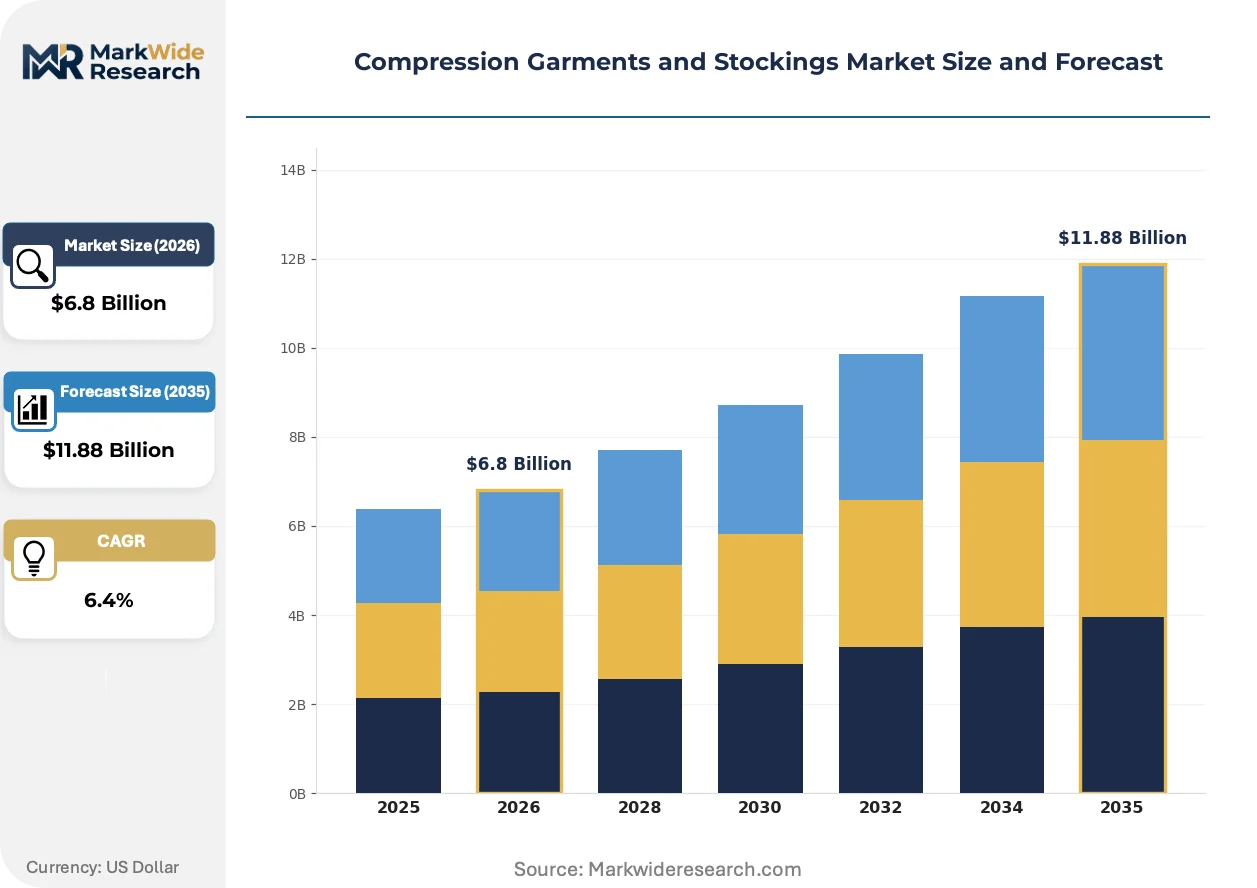
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stockings, Sleeves, Tights, Wraps End User: Medical Professionals, Athletes, Pregnant Women, General Consumers Material: Elastic Fibers, Nylon, Spandex, Cotton Compression Level: Low, Moderate, High, Extra High |
| Companies Covered | SUN POLAR, AeroFlex Dynamics, SIGVARIS GROUP, FlexiBiome Labs, EvolveSkin Tech, Juzo, PhysioWeave Pro, NeoFit Systems, JOBST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compression Garments and Stockings Market Emerging Trajectories
Material science convergence with digital health infrastructure is redefining how compression garments deliver and document therapeutic value. Three developments dominate strategic planning cycles.
Sensor-embedded textile technology is hybridizing passive compression with biometric feedback. Knitted conductive yarn arrays measure limb circumference changes and transmit edema data to clinician dashboards. Vascular clinics in the United States pilot these systems for heart failure patients with remote monitoring mandates. The convergence collapses the distinction between garment and medical device categories.
EU MDR Article 61 clinical evidence requirements are tightening post-market surveillance obligations for compression class devices. Manufacturers must submit periodic safety update reports with real-world performance data. German notified bodies demand extended follow-up periods for lymphedema treatment claims. The regulatory burden favors firms with existing clinical trial infrastructure.
Direct-to-patient subscription models are displacing durable medical equipment distributor networks. Compression garment brands bypass orthotics shops and deliver monthly stocking replacements to chronic venous insufficiency patients. California and Florida demonstrate highest subscription penetration where Medicare Advantage plans cover home-delivered compression therapy. Channel control shifts margin capture from retailers to manufacturers.
Compression Garments and Stockings Market Segmentation
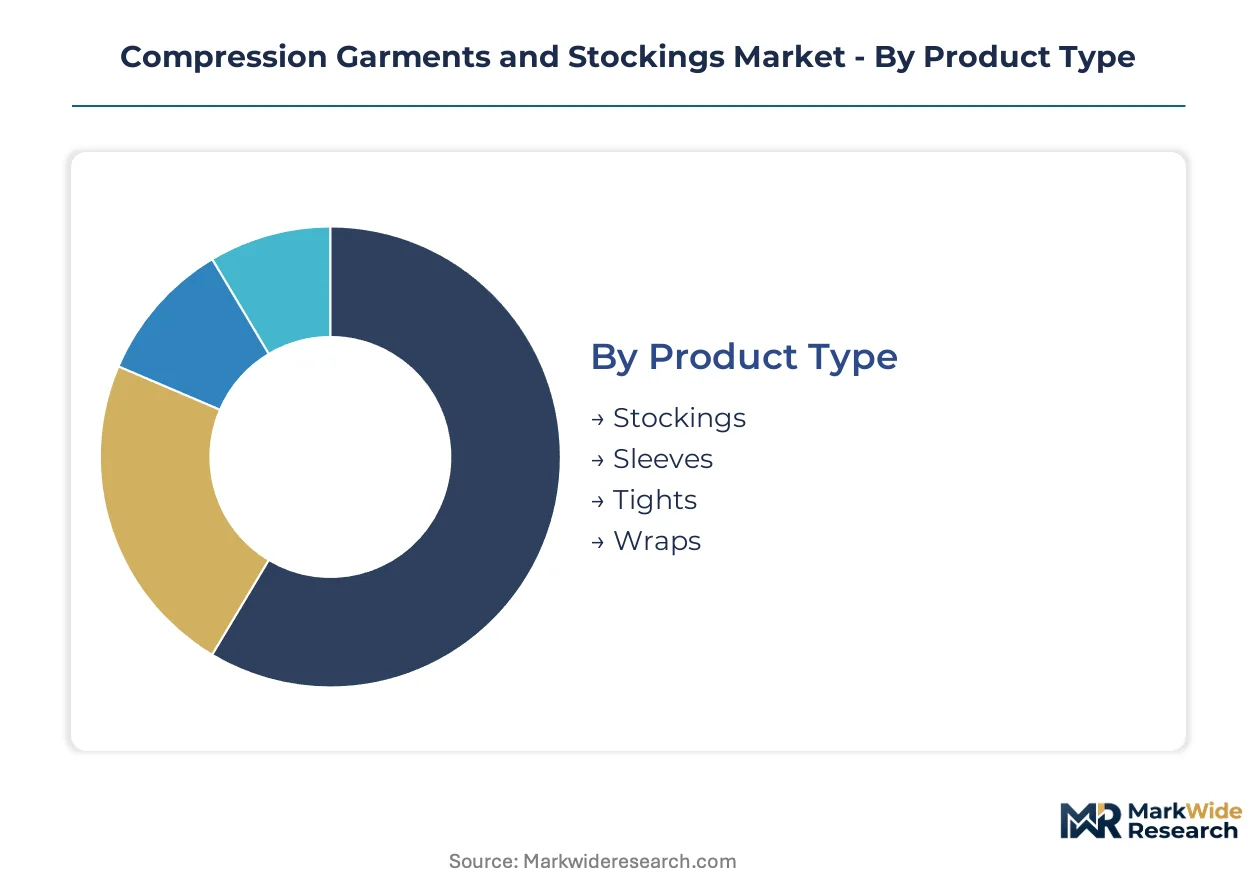
Compression garment segmentation determines reimbursement pathways, manufacturing equipment selection, and channel strategy. Product form factor dictates knitting machinery configuration, while compression level calibration governs clinical indication matching and regulatory classification.
Product Type:
The use-case spectrum spans acute hospital discharge through chronic condition management and athletic recovery protocols.
- Stockings:Full-length leg garments engineered with distal-to-proximal pressure gradients for venous insufficiency and post-thrombotic syndrome. Hospital procurement teams in the United States bundle stockings into orthopedic surgery discharge kits, driving volume through bundled payment structures.
- Sleeves:Arm and calf variants serving lymphedema management and athletic recovery programs. Professional cycling teams in Colorado and marathon training facilities in Arizona procure compression sleeves as dedicated recovery infrastructure outside clinical reimbursement channels.
- Tights:Full lower-body coverage garments addressing pregnancy-related venous congestion and occupational standing fatigue. Occupational health programs for retail and hospitality workers in Germany specify tights for shift-based compression therapy.
- Wraps:Adjustable compression systems with hook-and-fastener closure for post-operative patients experiencing fluctuating limb volume. Surgical wards in Swiss hospitals deploy wraps during the immediate post-operative window before transitioning to fitted garments.
The dominant share belongs to Stockings, while Sleeves is closing the gap fastest.
End User:
Cost tier stratification separates reimbursed clinical prescribing from direct-to-consumer wellness purchasing.
- Medical Professionals:Vascular surgeons, lymphedema therapists, and orthopedic discharge planners prescribing graduated compression under diagnosis codes. Medicare coverage determinations in the United States directly influence physician prescribing volume and patient out-of-pocket exposure.
- Athletes:Professional and amateur competitors seeking recovery acceleration and proprioceptive support. Sports medicine clinics represent uncaptured volume outside hospital procurement channels, with teams procuring directly from manufacturers.
- Pregnant Women:Obstetric patients managing venous congestion and edema during gestation. Maternity compression programs in France receive partial reimbursement through national health system preventive care allocations.
- General Consumers:Wellness-oriented purchasers seeking travel compression and occupational fatigue relief. Direct-to-patient subscription models in California and Florida demonstrate highest penetration where Medicare Advantage plans cover home-delivered therapy.
Medical Professionals command the largest revenue pool, though Athletes is expanding most quickly through sports medicine channel development.
Material:
Application requirements drive fiber selection between clinical durability and consumer comfort priorities.
- Elastic Fibers:Synthetic elastomer cores providing controlled stretch and compression retention. German circular knitting operations program needle selection to engineer zoned compression profiles with single-machine production runs.
- Nylon:High-tenacity polyamide delivering abrasion resistance and moisture management. Nylon-spandex blends dominate clinical-grade output for hospital procurement specifications.
- Spandex:Polyurethane-based stretch fiber enabling precise mmHg gradient engineering. Price volatility in crude oil derivatives and textile chemical feedstock markets constrains manufacturer margin stability.
- Cotton:Natural fiber hybrids serving consumer wellness segments with skin sensitivity requirements. Cotton-elastic hybrids occupy economy pricing tiers outside reimbursed clinical channels.
Elastic Fibers and Nylon combinations anchor clinical procurement, while Cotton blends are gaining share fastest in direct-to-consumer wellness segments.
Compression Level:
Regulatory classification and reimbursement eligibility hinge on calibrated pressure specifications.
- Low:Below 15 mmHg gradients for mild fatigue relief and travel comfort. General consumer segments purchase low-compression products without prescription requirements through retail and e-commerce channels.
- Moderate:15-20 mmHg ranges for varicose vein prevention and early venous insufficiency. FDA Class I device exemptions streamline manufacturer entry for moderate compression garments in the United States.
- High:20-30 mmHg specifications for documented venous disease and post-thrombotic syndrome. EU MDR recertification demands clinical evidence portfolios for high-compression claims ahead of notified body deadlines.
- Extra High:Above 30 mmHg gradients for severe lymphedema and post-surgical edema management. Swiss and Dutch research hospitals concentrate large-scale randomized trials for extra-high compression outcomes.
Moderate compression holds the dominant position by volume, while Extra High is climbing the fastest as post-surgical rehabilitation protocols mandate graduated compression standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compression garment trade flows reveal persistent import dependence in clinical-grade segments, with specialized knitting machinery and elastomer feedstocks driving cross-border procurement patterns. Export competitiveness clusters where circular knitting automation and textile chemical supply chains achieve density.
United States
Medicare Advantage plans in California and Florida now cover home-delivered compression therapy, expanding direct-to-patient subscription volume. FDA Class I device exemptions streamline 510(k) pathways for non-powered garments, accelerating manufacturer market entry. Hospital procurement teams in Colorado and Arizona embed graduated compression into orthopedic discharge protocols.
Germany
Occupational health programs for retail and hospitality workers specify compression tights for shift-based therapy, broadening reimbursement-eligible indications. EU MDR recertification deadlines through May 2027 compress compliance windows and consolidate clinical evidence requirements. Circular knitting operations in Baden-Württemberg program needle selection for zoned compression profiles.
Switzerland
Swissmedic maintains stringent post-market surveillance for compression devices marketed as lymphedema treatments. Research hospitals in Zurich and Basel concentrate large-scale randomized trials for extra-high compression outcomes. SIGVARIS GROUP leverages Swiss manufacturing heritage to sustain premium positioning across European hospital channels.
France
Maternity compression programs receive partial reimbursement through national health system preventive care allocations, expanding pregnancy-related indications. ANSM enforces extended follow-up periods for clinical evidence supporting lymphedema treatment claims. Medical textile converters in the Lyon region supply graduated compression garments to vascular clinics.
Japan
PMDA classification pathways distinguish between wellness-oriented and clinical-grade compression products, segmenting regulatory requirements. METI industrial policy supports textile machinery upgrades for precision knitting automation. Aging demographics in the Kanto region sustain demand for venous insufficiency management.
Compression Garments and Stockings Market Vendor Landscape
On the supply side, the industry is moderately concentrated with tiered differentiation between premium clinical-grade specialists and mass-market fabricators. Swiss and German heritage manufacturers anchor the premium tier through circular knitting expertise and ISO 13485 certification infrastructure. Asian contract manufacturers occupy volume positions with asset-light private-label arrangements. Dominant competitive moves include strategic partnerships with telehealth platforms and backward integration into elastomer yarn supply.
Within the heritage manufacturing tier, SIGVARIS GROUP and Juzo exemplify precision-focused positioning, with the former representing Swiss circular knitting tradition and the latter anchoring German in-house production control. JOBST occupies a distinct position in therapist-facing brand recognition. Among the technology-forward entrants, AeroFlex Dynamics and FlexiBiome Labs represent the sensor-embedded textile convergence, while NeoFit Systems and PhysioWeave Pro exemplify digital health integration archetypes. SUN POLAR and EvolveSkin Tech illustrate geographic diversification patterns in emerging manufacturing hubs.
| Leading Market Players |
|---|
| SUN POLAR |
| AeroFlex Dynamics |
| SIGVARIS GROUP |
| FlexiBiome Labs |
| EvolveSkin Tech |
| Juzo |
| PhysioWeave Pro |
| NeoFit Systems |
| JOBST |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors shape landed cost differentials for elastomer feedstocks, concentrating margin pressure on manufacturers without captive yarn supply while enabling three-tier pricing stratification across premium Swiss clinical-grade, mid-tier German precision-knit, and economy Asian contract-manufactured garments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with hospital procurement teams and GPOs negotiating annual volume commitments against spot-market spandex volatility. Price differentiation rests on ISO 13485 certification tier and graduated compression calibration precision, with FDA-cleared Class I devices commanding premiums over wellness-grade alternatives. Cost compression in the economy tier is intensifying because Asian contract manufacturers compete on asset-light private-label arrangements. General consumers through direct-to-patient subscription channels exhibit highest price sensitivity, while vascular clinic prescribing networks show lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Asset-light contract manufacturers in Vietnam, Bangladesh, and southern China hold dominant capacity for economy-tier garment production, while Swiss and German heritage manufacturers retain captive circular knitting operations for clinical-grade output. Raw material dependencies center on polyurethane elastomer fibers, high-tenacity nylon 6,6 yarns, and medical-grade latex cores. Single-source vulnerability concentrates in German precision needle-selection machinery suppliers. Distribution runs through durable medical equipment distributors in reimbursed channels, with direct-to-patient subscription models displacing orthotics retailers in Medicare Advantage-covered markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded textile convergence with remote patient monitoring platforms is disrupting traditional garment-device boundaries, creating first-mover advantages for manufacturers integrating biometric feedback ahead of EU MDR recertification deadlines.
For Market Incumbents: Insulate premium positioning by deepening backward integration into elastomer yarn supply and accelerating ISO 13485 certification infrastructure in Southeast Asian satellite facilities. Pneumatic compression device substitution in acute care settings threatens static garment share; defend through telehealth platform partnerships that embed adherence tracking into clinician workflows. For New Entrants and Emerging Players: Athletic recovery programs in Colorado and Arizona represent underpenetrated white-space where professional cycling teams and marathon training facilities procure directly outside hospital procurement channels. Target sports medicine clinics with subscription-based sleeve replenishment models, leveraging PLA biodegradable yarn positioning for sustainability differentiation in single-use post-operative applications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical textile parents seeking to divest compression-focused divisions ahead of EU MDR compliance cost concentration. Five-to-ten-year viability favors manufacturers with existing clinical trial infrastructure and notified body relationships. Watch FDA 510(k) clearance velocity for sensor-embedded garments as inflection signal for category convergence timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Supply | Captive polyurethane fiber production insulates margin stability against crude oil derivative volatility. |
| Sensor-Embedded Textile Development | Knitted conductive yarn arrays enable biometric feedback convergence with remote patient monitoring mandates. |
| Direct-to-Patient Subscription Launch | California and Florida Medicare Advantage penetration demonstrates channel control shifting margin capture from retailers. |
| EU MDR Clinical Evidence Portfolio Build | German notified body deadlines through May 2027 compress compliance windows for lymphedema treatment claims. |
| Sports Medicine Channel Partnership | Professional cycling and marathon training facilities in Colorado and Arizona represent uncaptured volume outside hospital procurement. |
Methodological Framework
Cross-validation between hospital procurement database analysis and compression garment prescribing pattern surveys anchors the qualitative findings. Primary interviews with vascular surgeons, lymphedema therapists, GPO contracts managers, and biomedical engineers combined with secondary validation against FDA 510(k) filings, CMS Medicare coverage determinations, EU MDR notified body guidance documents, and hospital supply chain expenditure records. Bottom-up segmentation modeling and top-down macroeconomic adjustment triangulate volume estimates.
Calibration against historical penetration curves and reimbursement code revision timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, compression level calibration, end-user cost tier, material fiber composition, and regional regulatory cluster. CAGRs derived from slope-matching to documented adoption inflection points in post-surgical rehabilitation protocol standardization and sports medicine channel development.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pneumatic compression device manufacturers or digital therapeutics platforms would shift outcomes. Quarterly review of FDA 510(k) clearance velocity, EU MDR recertification completion rates, and Medicare Advantage compression therapy coverage expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Safety Needles Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
IV Infusion Gravity Bags Market