

Emergency Transfer Vacuum Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Transfer Vacuum Mattress Market Insights
Buyer concentration among emergency medical services is restructuring procurement patterns across the sector. PAX Company leverages its manufacturing scale to serve centralized purchasing consortia in European healthcare systems. FERNO sustains channel control through direct relationships with municipal fire departments and ambulance operators. Hartwell Medical differentiates via product specialization in trauma rescue configurations that meet evolving clinical protocols.
An emergency transfer vacuum mattress is a medical evacuation device comprising multiple airtight cells filled with polystyrene beads that become rigid when air is evacuated, enabling full-body immobilization during patient transport. The device maintains spinal alignment and distributes pressure evenly across the patient's surface, primarily serving pre-hospital trauma care and disaster medical operations. Semi-rigid mattress variants dominate current procurement volumes due to their balance of immobilization performance and operational flexibility in confined spaces. Polyurethane material grades are capturing expanding share as manufacturers prioritize chemical resistance and extended service life in harsh field conditions. The trauma rescue application segment anchors premium pricing, though disaster response configurations represent the fastest-growing demand pool driven by civil defense preparedness investments.
The EU Medical Device Regulation and FDA 510(k) clearance pathways govern product standards and market access for vacuum mattress manufacturers serving Western healthcare systems. ISO 13485 quality management certification shapes supplier qualification criteria for institutional buyers, while EN 1865 patient handling equipment standards define dimensional and load-bearing specifications. Stakeholders must monitor evolving interoperability requirements between vacuum mattresses and automated loading systems as ambulance fleet modernization accelerates.
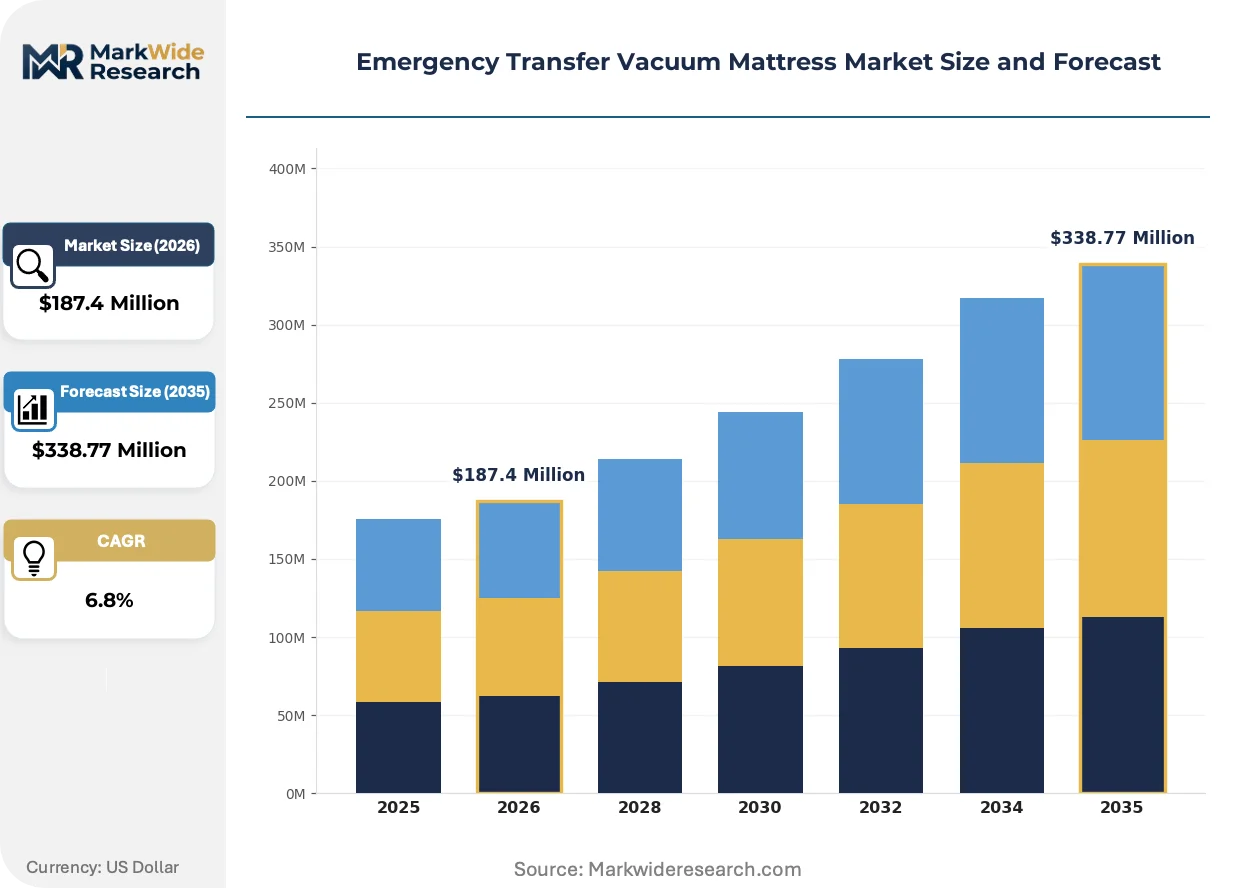
Market Dynamics
Federal emergency response modernization programs in Germany are compressing replacement cycles and forcing manufacturers to align product roadmaps with public procurement timelines. This demand concentration is restructuring competitive positioning around scale and certification speed.
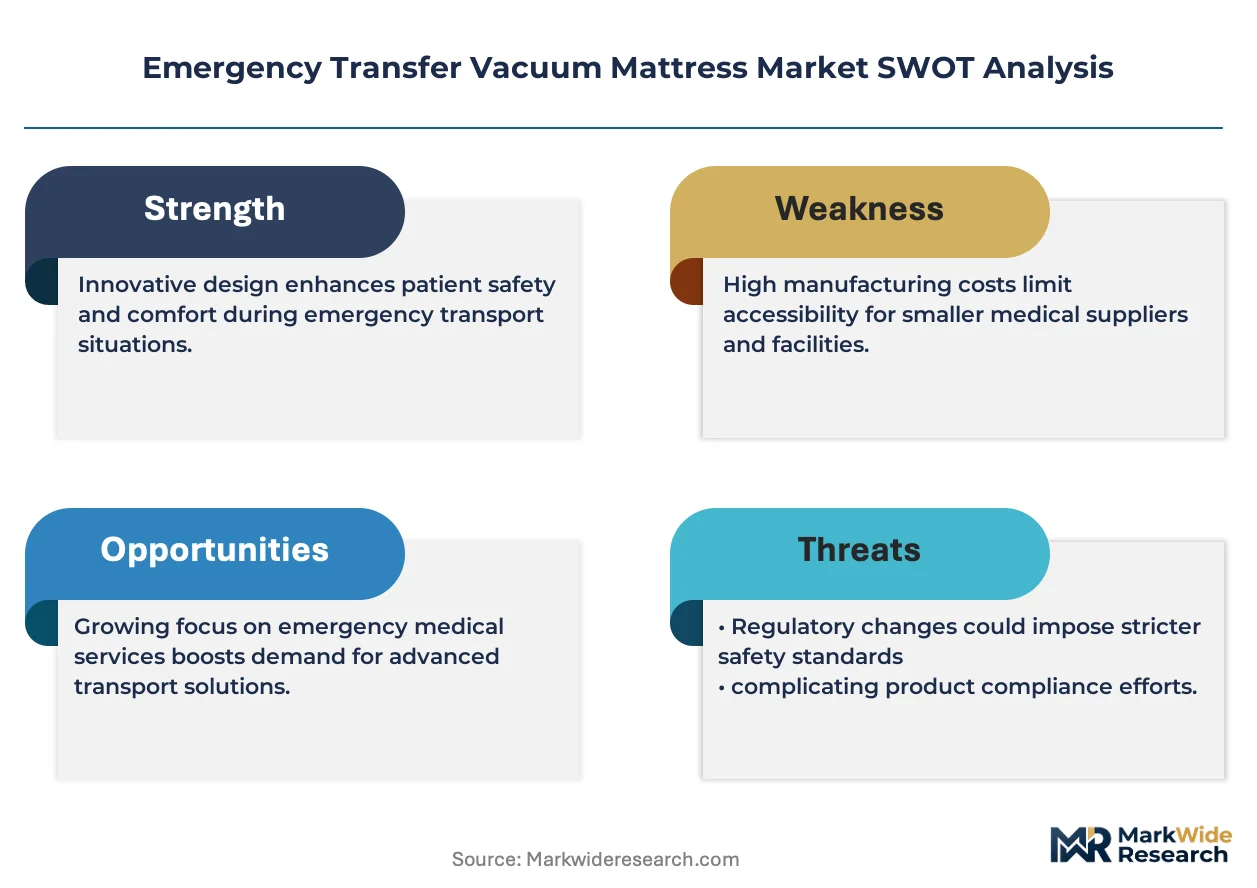
Growth Catalysts
- EU Medical Device Regulation:Tightened performance testing requirements for patient transport equipment are filtering out marginal suppliers and consolidating qualified vendor pools for institutional buyers.
- Military medical units:Expanded procurement of foldable vacuum mattresses for field operations is creating a specialized demand channel with distinct performance specifications.
- Polystyrene bead formulations:Advanced material grades are improving immobilization reliability under temperature stress, extending operational envelopes for disaster response teams.
Market Restraints
- Polyurethane input costs:Chemical feedstock volatility is pressuring margins for manufacturers prioritizing extended service life in harsh field conditions.
- Supplier concentration in Central European molding:Dependence on specialized polymer fabricators creates bottleneck risk for airtight cell production.
- Spinal board substitution:Rigid immobilization devices retain cost advantage in budget-constrained municipal systems, limiting vacuum mattress penetration in price-sensitive segments.
Strategic Opportunities
- Civil defense preparedness investments:Disaster response configurations represent expansion white space as national stockpiling programs accelerate across NATO member states.
- Interoperability with automated loading systems:Ambulance fleet modernization is creating demand for vacuum mattresses with standardized attachment interfaces.
- ISO 13485 certification acceleration:Quality management gaps among regional competitors create entry pathways for certified suppliers in underserved Eastern European markets.
Industry Challenges
- EN 1865 dimensional compliance:Load-bearing specification updates are forcing design revisions and retesting timelines that delay product launches.
- Integration with legacy stretcher mounts:Compatibility engineering consumes development resources for configurations serving mixed-age ambulance fleets.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Transfer Vacuum Mattress Market Trends and Innovations
Material science advances and regulatory harmonization pressures are compressing product development cycles while elevating performance verification standards. Manufacturers must now balance chemical resistance improvements against certification timeline risks.
Smart sensor integration is converging with vacuum mattress core designs to enable real-time pressure monitoring and automated firmness adjustment during prolonged patient transport. Emergency medical services in Scandinavian healthcare systems are piloting these configurations for inter-facility transfers. This convergence is compressing the traditional separation between immobilization devices and patient monitoring equipment, forcing suppliers to develop electronics partnerships or in-house capabilities.
REACH chemical compliance deadlines are accelerating substitution of legacy flame retardants in polyurethane formulations used for mattress covers. Industrial consequence includes reformulation costs and supply chain requalification for European manufacturers. Trauma rescue application segments are most affected, as these configurations face the strictest material safety scrutiny and are responding by sourcing from pre-certified polymer compounders.
Centralized purchasing consortia in European healthcare systems are consolidating procurement authority and compressing supplier lists to three-to-five approved vendors per category. Municipal fire departments and ambulance operators are losing direct purchasing autonomy to regional buying groups. Germany exhibits this pattern most visibly, where federal emergency response modernization programs mandate consortium participation for equipment replacement funding eligibility.
Emergency Transfer Vacuum Mattress Market Segmentation
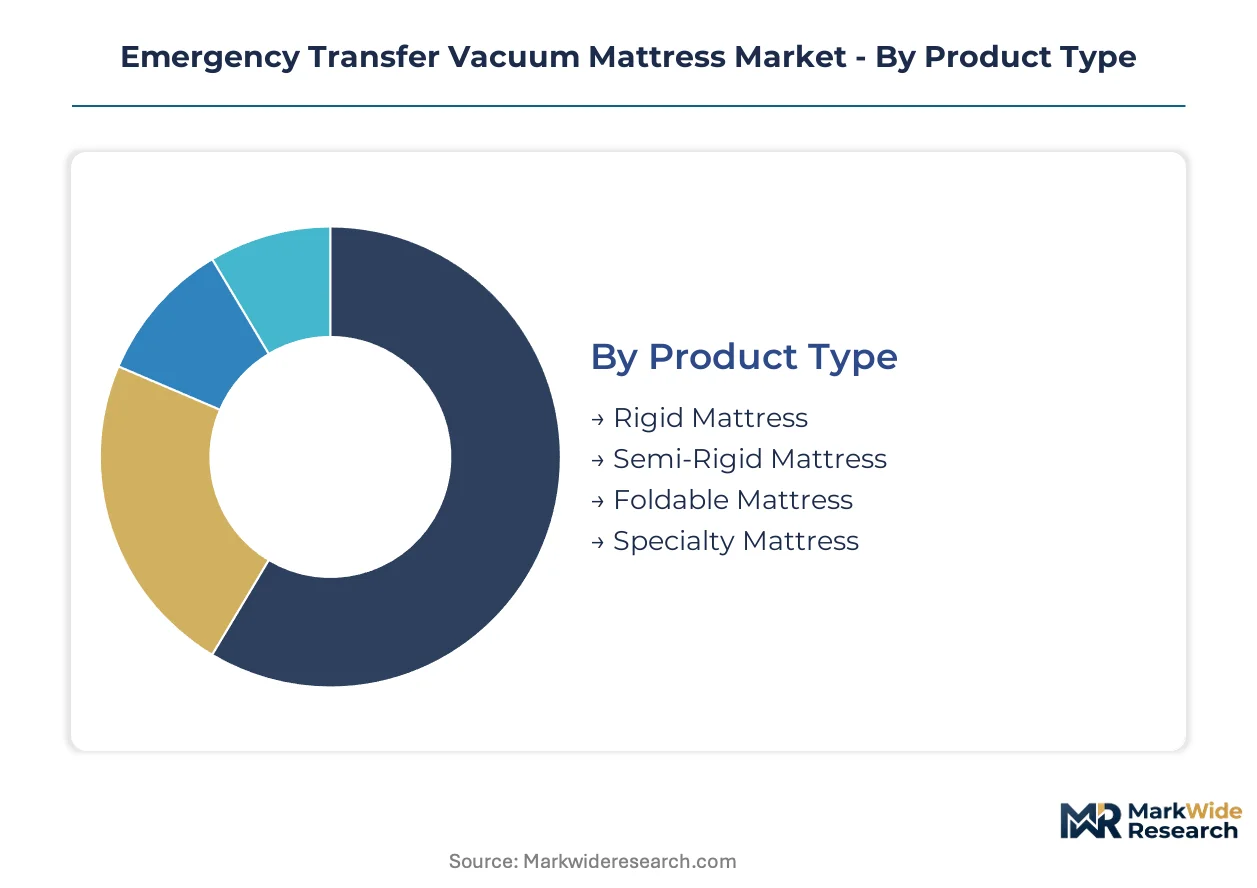
Procurement patterns for emergency transfer vacuum mattresses diverge sharply across product configurations and user environments. Military medical units prioritize foldable designs for field mobility, while municipal emergency services favor semi-rigid variants balancing immobilization performance with confined-space maneuverability.
Product Type:
Supply concentration in Central European molding operations favors manufacturers with captive production of semi-rigid and foldable configurations, locking out smaller competitors dependent on outsourced airtight cell fabrication.
- Rigid Mattress:Constructed from high-density polymer shells with fixed bead chambers that maintain structural integrity under extreme load stress. German federal emergency response modernization programs are driving replacement demand in municipal ambulance fleets, though procurement timelines compress margin flexibility for vendors.
- Semi-Rigid Mattress:Combines partial structural rigidity with segmented flexibility zones for spinal alignment in confined vehicle interiors. Captures dominant procurement volumes across European centralized purchasing consortia due to operational versatility in mixed-age ambulance configurations.
- Foldable Mattress:Features hinged chamber arrays enabling compact stowage for airborne and rapid deployment operations. NATO military medical units are expanding specifications for this category.
- Specialty Mattress:Custom-configured for bariatric patients or pediatric immobilization with modified bead density distributions. Addresses niche demand pools in specialized trauma centers.
Today's leader: Semi-Rigid Mattress. Tomorrow's challenger: Foldable Mattress.
Material:
Cost tier differentiation separates premium polyurethane grades from commodity polyvinyl chloride alternatives, with chemical resistance specifications determining qualification for institutional procurement lists.
- Polyurethane:Advanced elastomer formulations deliver superior abrasion resistance and extended service life under temperature stress. REACH chemical compliance deadlines are accelerating substitution of legacy flame retardants, forcing reformulation investments from European manufacturers.
- Polyvinyl Chloride:Standard-grade thermoplastic offering baseline chemical resistance at lower unit cost. Retains share in budget-constrained municipal systems where spinal board substitution pressure limits vacuum mattress penetration.
- Nylon:High-tensile woven substrates provide puncture resistance for disaster response field conditions. Gaining specification in Scandinavian civil defense stockpiling programs.
- Polyester:Lightweight textile covers with moisture-wicking properties for prolonged patient contact scenarios. Serves inter-facility transfer applications in hospital network logistics.
Volume concentrates in polyurethane. Margin expansion tracks nylon.
Application:
Application-driven demand splits between premium trauma rescue protocols and volume disaster response stockpiling, with interoperability requirements for automated loading systems reshaping specification standards.
- Trauma Rescue:Full-body immobilization configurations meeting EN 1865 load-bearing specifications for spinal injury protocols. Anchors premium pricing tiers due to clinical certification requirements and material safety scrutiny.
- Disaster Response:Rapid-deployment designs with standardized attachment interfaces for mass casualty incidents. Civil defense preparedness investments across NATO member states are expanding procurement volumes fastest.
- Patient Transport:Inter-facility transfer configurations integrating smart sensor monitoring for pressure distribution. Pilot programs in Scandinavian healthcare systems are validating automated firmness adjustment.
- Evacuation:Lightweight designs for vertical extraction and confined-space rescue operations. Serves search and rescue team specifications in alpine and urban environments.
Revenue pools in trauma rescue. Growth velocity in disaster response.
End User:
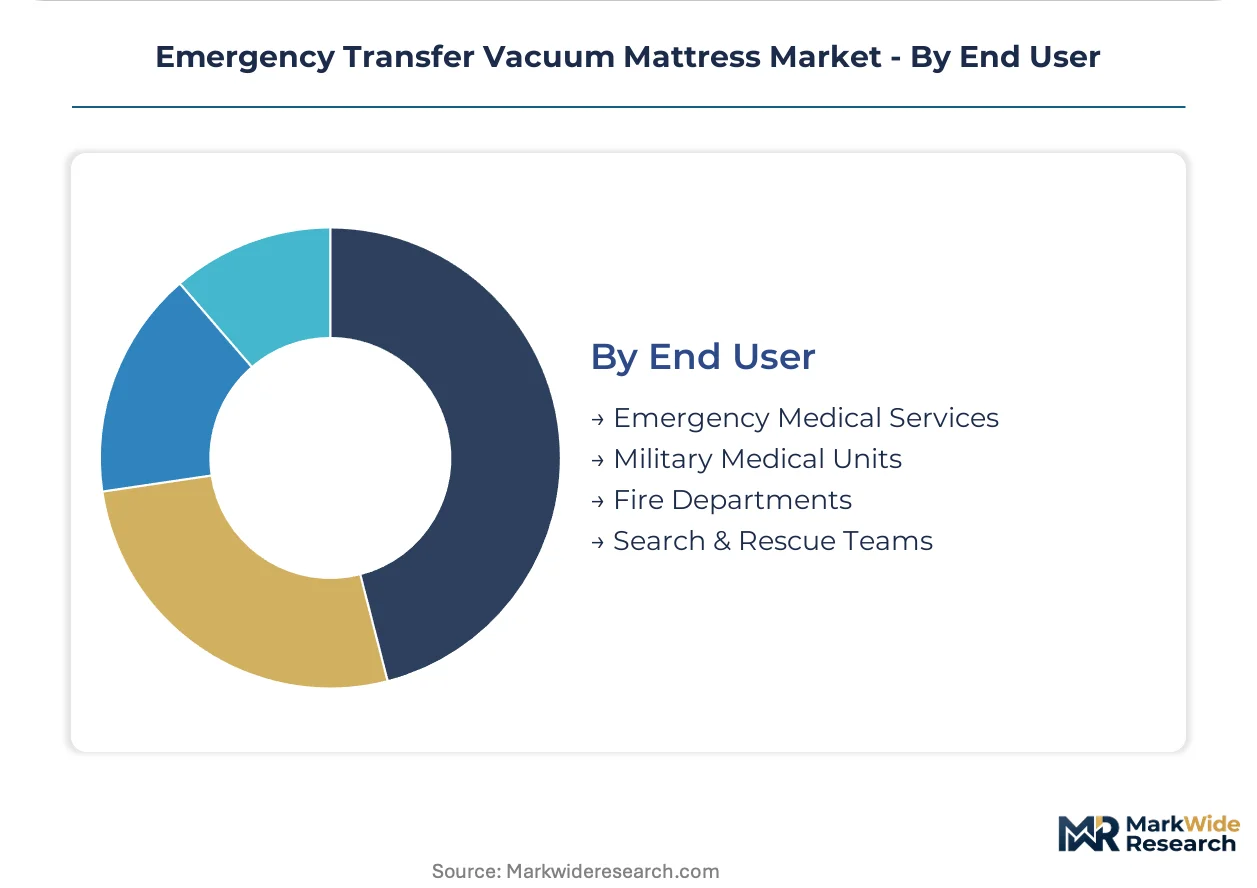
Customer-type procurement authority is centralizing, with municipal fire departments and ambulance operators losing direct purchasing autonomy to regional buying groups mandated by federal funding eligibility requirements.
- Emergency Medical Services:Centralized purchasing consortia in European healthcare systems are compressing approved vendor lists to three-to-five suppliers per category. ISO 13485 certification shapes qualification criteria.
- Military Medical Units:Specialized demand channel with distinct performance specifications for field operations and airborne deployment. Foldable mattress procurement is expanding with distinct tender timelines.
- Fire Departments:Municipal operators facing consortium participation mandates for equipment replacement funding. Direct relationships with manufacturers like FERNO are yielding to regional authority structures.
- Search & Rescue Teams:Specialized configurations for technical rescue and wilderness extraction. Smaller procurement volumes with high customization requirements.
Contract authority shifts to Emergency Medical Services. Specification influence persists with Military Medical Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands procurement volume through federal modernization mandates, while the United States concentrates military specification development. France and the United Kingdom follow with consortium-driven purchasing reforms, and Italy retains fragmented municipal autonomy.
United States
FDA 510(k) clearance pathways govern market access for vacuum mattress manufacturers serving civilian healthcare systems, while military medical units drive foldable configuration specifications. The Department of Defense maintains distinct tender timelines for field operations equipment. Boston-area medical device clusters supply component technologies for smart sensor integration pilots.
Germany
Federal emergency response modernization programs compress replacement cycles and mandate consortium participation for funding eligibility. EU Medical Device Regulation performance testing requirements filter supplier pools for institutional buyers. North Rhine-Westphalia manufacturing clusters specialize in polyurethane airtight cell fabrication for semi-rigid mattress production.
France
ANSM oversight aligns with MDR harmonization for patient transport equipment certification. Regional health agencies consolidate procurement authority through centralized purchasing consortia that compress approved vendor lists. Lyon-based polymer compounders supply REACH-compliant flame retardant formulations for trauma rescue configurations.
United Kingdom
NHS Supply Chain centralization transfers purchasing autonomy from municipal ambulance trusts to national frameworks. MHRA post-Brexit regulatory divergence creates parallel certification requirements for manufacturers. West Midlands manufacturing clusters produce evacuation configurations for search and rescue team specifications.
Italy
Fragmented municipal fire department procurement persists alongside emerging regional consolidation in northern provinces. Ministry of Health circulars on patient handling equipment guide local purchasing decisions. Emilia-Romagna industrial districts maintain specialized molding capabilities for rigid mattress shell production.
Emergency Transfer Vacuum Mattress Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated supply relationships with Central European polymer fabricators favor manufacturers with captive production or long-term supply agreements. Three strategic archetypes dominate: scale-driven suppliers serving centralized purchasing consortia, relationship-based vendors maintaining direct municipal fire department channels, and specialization-focused players targeting trauma rescue certification requirements. Competitive moves center on ISO 13485 certification acceleration for Eastern European market entry and interoperability engineering for automated ambulance loading systems.
Among German-based fabricators, PAX Company exemplifies scale-driven positioning for consortium procurement, while HUM GmbH occupies a specialized tier. Hartwell Medical anchors the trauma rescue specialization archetype. These three represent distinct competitive vectors: manufacturing scale, regional supply integration, and clinical protocol alignment respectively.
| Leading Market Players |
|---|
| PAX Company |
| FERNO |
| Hartwell Medical |
| Kohlbrat & Bunz |
| Cramer |
| EGO Zlín |
| MeBer |
| Oscar Boscarol |
| HUM GmbH |
| Others |
Pricing and Supply Chain Analysis
Federal emergency response modernization programs in Germany are compressing replacement cycles and forcing manufacturers to accelerate ISO 13485 certification timelines, which tightens qualified supplier pools and elevates price floors for compliant configurations.
Pricing Analysis
Capacity additions in North Rhine-Westphalia are reshaping price floors for polyurethane-based semi-rigid mattresses. Three-tier pricing structure across premium trauma rescue, standard municipal EMS, and economy spinal board-competing tiers separates certified suppliers from marginal competitors. Price differentiation rests on EN 1865 load-bearing certification tier and REACH-compliant flame retardant material grades. Cost compression in the economy tier is intensifying because polyvinyl chloride input volatility pressures budget-constrained municipal fire departments.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Czech Republic form a hub-and-spoke pattern serving NATO military medical units and European healthcare consortia. Airtight cell fabrication draws from specialized polymer molders in Central Europe, with polystyrene bead formulations and polyurethane cover materials anchoring raw material dependencies. Single-source vulnerability concentrates in North Rhine-Westphalia molding clusters for semi-rigid configurations. Distribution runs through GPO-contracted medical equipment distributors and direct municipal fire department channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Western European certification-heavy procurement and Eastern European ISO 13485 certification gaps, with quality management investment costs diverging sharply across the frontier.
For Market Incumbents: Anchor consortium relationships through captive polyurethane molding capacity in Germany. Defend against spinal board substitution by embedding smart sensor interoperability into premium trauma rescue configurations. Accelerate backward integration into REACH-compliant flame retardant compound sourcing to neutralize reformulation cost spikes. For New Entrants and Emerging Players: Capture civil defense stockpiling white space in Poland and Romania where NATO preparedness investments outpace local supplier certification. Target foldable mattress specifications for military medical units with distinct tender timelines separate from municipal EMS procurement cycles. Pursue ISO 13485 certification acceleration as the primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized trauma rescue fabricators holding EN 1865 certification and clinical protocol relationships. Long-term viability hinges on interoperability engineering for automated ambulance loading systems as fleet modernization capital deployment extends. Monitor civil defense budget appropriations across NATO member states as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Qualifies suppliers for German federal emergency response modernization program funding eligibility. |
| REACH-Compliant Flame Retardant Reformulation | Preserves trauma rescue segment access as ECHA deadlines eliminate legacy polyurethane additives. |
| Smart Sensor Integration Partnership | Positions configurations for Scandinavian inter-facility transfer pilot programs and automated firmness adjustment demand. |
| Automated Loading System Interoperability Engineering | Aligns product roadmaps with ambulance fleet modernization specifications in NHS Supply Chain frameworks. |
| Civil Defense Stockpiling Channel Development | Captures fastest-growing demand pool as NATO member states accelerate mass casualty preparedness investments. |
Research Methodology
Direct dialogue with emergency medical services procurement directors, biomedical engineers at trauma centers, GPO contracts managers, and military medical logistics officers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, EN 1865 standard revision records, and hospital equipment procurement contracts. Bottom-up and top-down triangulation cross-checked manufacturer capacity disclosures against institutional buying group tender volumes.
Bottom-up modeling built from product configuration shipments across rigid, semi-rigid, foldable, and specialty mattress types, material grade tiers, and application segments including trauma rescue, disaster response, patient transport, and evacuation. Top-down verification anchored against federal emergency response modernization program budget appropriations and NATO civil defense preparedness investment disclosures. CAGRs were derived from segmented volume trajectories and pricing tier evolution across the analysis window.
Regulatory timeline acceleration, polymer feedstock cost volatility, and military procurement cycle shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding consortium purchasing consolidation velocity and REACH compliance deadline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.