
 Italy Ultrasound Devices Market | 2026-2036
Italy Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Ultrasound Devices Market Foresight
Aftermarket service revenue is reshaping profitability dynamics for Italian ultrasound vendors. Siemens Healthineers leverages its extensive service network across northern Italy to capture recurring maintenance contracts. Esaote SpA anchors its competitive stance through specialized musculoskeletal and cardiovascular imaging systems designed for Mediterranean patient profiles. GE Healthcare extends its presence via strategic partnerships with major university hospitals in Rome and Milan.
Ultrasound devices generate acoustic images through piezoelectric transducers operating at frequencies between two and fifteen megahertz, enabling real-time visualization of soft tissue structures without ionizing radiation. Cart-based systems dominate hospital procurement budgets due to superior image resolution and multi-probe configurability, while portable and handheld segments attract ambulatory clinics seeking point-of-care flexibility in underserved provinces. Doppler technology commands premium positioning in cardiology applications where hemodynamic assessment drives clinical decision-making.
Italy's national medical device regulator, the Ministry of Health's Directorate General for Medical Devices, enforces CE marking compliance under the EU Medical Device Regulation alongside ISO 13485 quality management standards for domestic manufacturers. Regional health authorities in Lombardy and Veneto layer additional procurement specifications that favor devices with integrated artificial intelligence diagnostic aids. Stakeholders must monitor how Italy's transposition of the EU AI Act into medical device software classification reshapes product registration pathways and competitive access conditions.
Market Dynamics
Italy's ultrasound market pivots on reimbursement recalibration favoring non-invasive cardiac screening, compressing demand toward portable systems while regional procurement authorities in Lombardy and Veneto layer AI-integration requirements atop EU Medical Device Regulation compliance.
Growth Catalysts
- EU AI Act transposition:Italy's Ministry of Health is embedding artificial intelligence diagnostic aids into regional procurement specifications, creating preferential access for vendors with CE-marked software modules.
- Cardiovascular screening expansion:Diagnostic centers in Milan and Rome are scaling capacity for early cardiac detection, pulling demand for Doppler-capable systems into ambulatory settings.
- Point-of-care migration:Clinics in underserved southern provinces are adopting handheld ultrasound for rural outreach, extending service coverage beyond hospital radiology departments.
Market Restraints
- Piezoelectric crystal supply concentration:Italian manufacturers rely on East Asian suppliers for high-frequency transducer materials, exposing procurement to shipping volatility and input cost swings.
- CE marking friction under MDR:The EU Medical Device Regulation's expanded clinical evidence requirements are extending registration timelines for software-integrated systems by twelve to eighteen months.
- CT and MRI substitution:Hospital budgets in Emilia-Romagna are redirecting capital toward magnetic resonance systems for orthopedic imaging, constraining ultrasound share in musculoskeletal diagnostics.
Strategic Opportunities
- Sicily and Calabria penetration:Southern Italy's diagnostic infrastructure gap creates first-mover advantage for vendors offering lease-to-own portable systems with bundled training.
- Telemedicine convergence:Integration of ultrasound with 5G-enabled remote consultation platforms opens subscription revenue models for cardiology networks spanning multiple regions.
- Regional AI procurement mandates:Veneto's health authority is piloting outcome-based reimbursement for AI-assisted cardiac screening, rewarding vendors who demonstrate diagnostic accuracy improvements.
Industry Challenges
- Sonographer training bottlenecks:Italian universities produce fewer certified ultrasound technicians than replacement demand requires, forcing clinics to compete for talent or absorb training costs.
- Legacy PACS integration:Hospital information systems in Rome and Milan run on decade-old architectures, complicating seamless data flow from new ultrasound platforms into electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Ultrasound Devices Market |
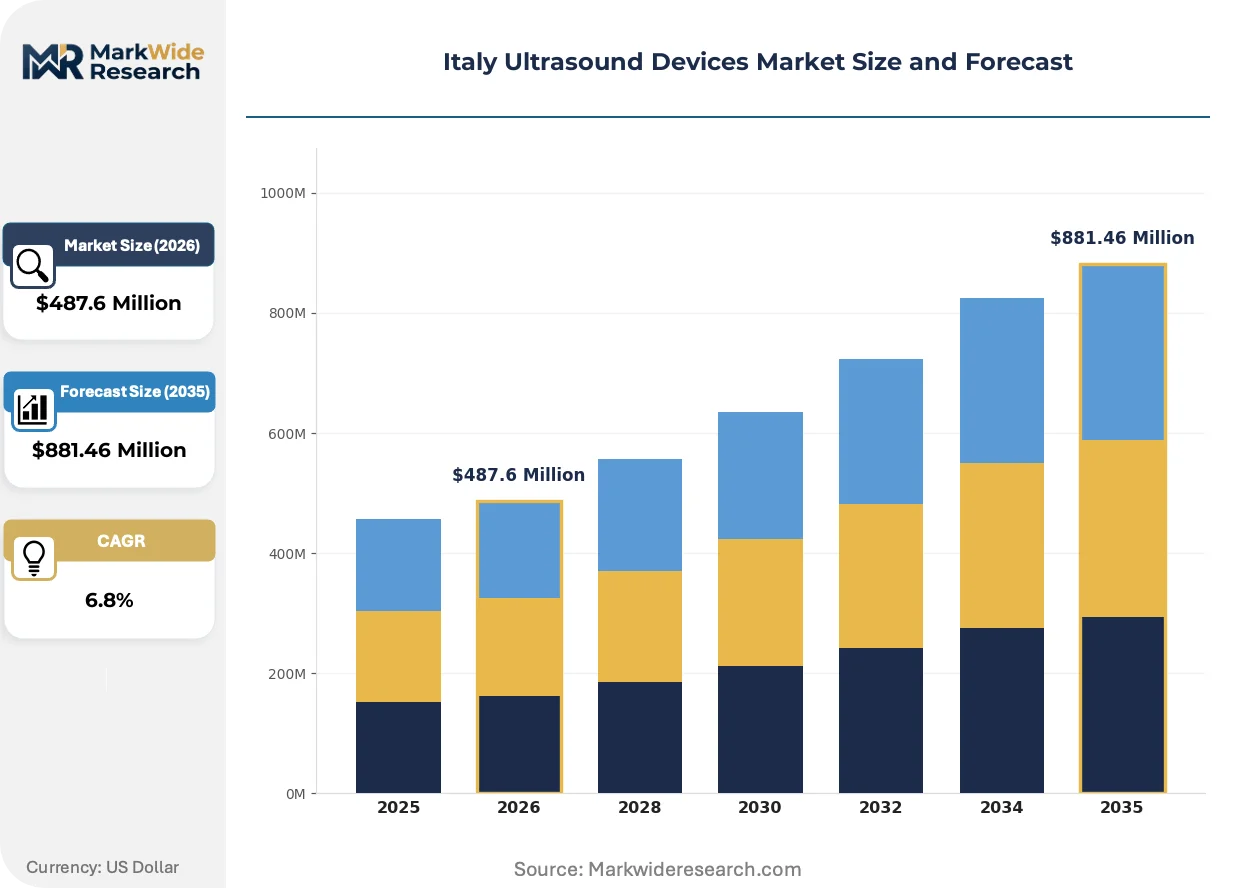
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Handheld, Cart-based, Console End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Technology: 2D, 3D, 4D, Doppler Application: Obstetrics, Cardiology, Abdominal, Musculoskeletal |
| Companies Covered | Siemens Healthineers, Fujifilm Holdings Corporation, GE Healthcare, Mindray Medical International Limited, Samsung Medison, Philips Healthcare, Canon Medical Systems, SonoScape Medical Corp, Esaote SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Ultrasound Devices Market Shifts & Advancements
Artificial intelligence is compressing diagnostic workflows while hardware miniaturization and regulatory software reclassification are rewriting competitive access rules across Italian procurement channels.
Single-crystal silicon transducer technology is rendering obsolete conventional ceramic piezoelectric arrays in high-frequency cardiovascular applications. University hospitals in Milan are piloting these probes for pediatric echocardiography, attracted by improved penetration depth at frequencies above ten megahertz. The shift is compressing upgrade cycles for cart-based systems as buyers defer replacement until silicon-native platforms reach commercial scale.
Italy's transposition of the EU AI Act into medical device software classification is forcing vendors to re-register diagnostic algorithms as Class IIa or higher risk devices. The Ministry of Health's Directorate General for Medical Devices is requiring clinical performance studies for AI-assisted cardiac wall-motion analysis. Vendors with existing CE-marked hardware are responding by modularizing software updates to isolate regulatory exposure from core system approvals.
Aftermarket service unbundling is disrupting traditional procurement in Lombardy's diagnostic center networks. Buyers are separating equipment acquisition from maintenance contracts, awarding multi-year service agreements to third-party specialists with faster response times than manufacturer networks. The practice is most visible in Emilia-Romagna's independent imaging chains, where total-cost-of-ownership modeling now dominates capital committee decisions.
Italy Ultrasound Devices Market Segmentation
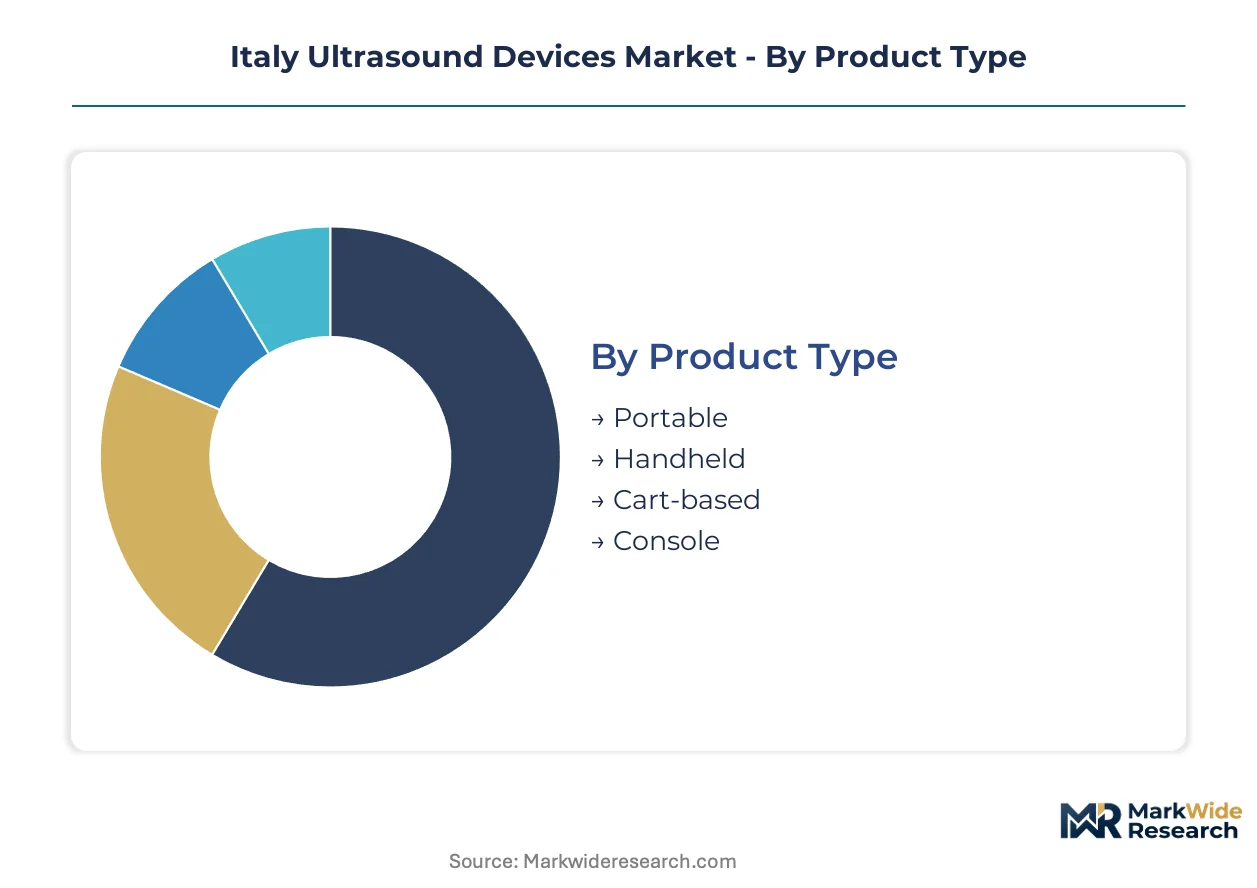
Ultrasound device segmentation in Italy reflects divergent procurement priorities across hospital networks, ambulatory clinics, and regional health authorities. Product configuration, imaging technology, and end-user setting each shape vendor access conditions and pricing power in distinct ways.
Product Type:
Cost tier stratification separates premium institutional systems from flexible point-of-care formats serving budget-constrained settings.
- Cart-based:These systems integrate multi-probe switching, high-channel-count beamforming processors, and motorized transducer positioning for complex cardiac and abdominal protocols. Lombardy's university hospitals in Milan anchor procurement volume, driven by reimbursement schedules favoring high-resolution diagnostic output for tertiary referrals.
- Portable:Battery-powered units with wireless probe connectivity enable ward-based and outpatient deployment without fixed infrastructure. Diagnostic centers across Rome's public hospital network are rotating toward these systems to expand screening capacity within existing floor space constraints.
- Handheld:Smartphone-tethered or tablet-integrated probes prioritize extreme portability for rural outreach and emergency triage.
- Console:Fixed-installation platforms with dedicated hardware architecture serve high-throughput radiology departments requiring sustained operational uptime.
Cart-based systems hold installed capacity. Portable formats are rotating up the share rankings.
End User:
Customer type determines purchasing authority structure, with regional health authorities, private imaging chains, and academic medical centers operating under divergent capital allocation rules.
- Hospitals:Tertiary centers in Milan and Rome command multi-million-euro capital budgets, consolidating procurement through centralized technical committees that evaluate total-cost-of-ownership over seven-to-ten-year depreciation cycles. Veneto's regional health authority layers AI-integration mandates atop EU MDR compliance for these buyers.
- Diagnostic Centers:Independent imaging chains across Emilia-Romagna and Lombardy prioritize throughput-per-square-meter, driving preference for systems with automated measurement protocols and rapid patient turnaround. These operators are unbundling equipment acquisition from service contracts, awarding maintenance to third-party specialists.
- Clinics:Ambulatory settings in southern provinces face capital constraints that favor lease-to-own structures and bundled training packages.
- Research Institutions:University hospitals pilot emerging transducer technologies and AI diagnostic algorithms under ministry-funded innovation programs.
Hospitals dominate capital deployment. Diagnostic centers are climbing fastest in unit volume.
Technology:
Imaging modality maturity spans established 2D platforms through computationally intensive real-time volumetric rendering.
- 2D:Conventional grayscale imaging remains the workhorse for abdominal and superficial structure assessment, with hardware costs lowest and operator training requirements most standardized. Provincial clinics in Calabria and Sicily rely on 2D systems for basic screening where specialist sonographer availability is limited.
- Doppler:Spectral and color flow mapping enables hemodynamic quantification for cardiac valve assessment and vascular patency evaluation. Milan's cardiovascular centers are scaling Doppler-capable system deployment following Ministry of Health reimbursement recalibration favoring non-invasive cardiac screening.
- 3D:Static volumetric acquisition reconstructs anatomical surfaces for fetal facial imaging and complex cardiac spatial relationships.
- 4D:Real-time volumetric rendering adds temporal dimension to 3D acquisition for dynamic fetal movement assessment and live procedural guidance.
2D maintains the broadest installed base. Doppler is expanding most quickly on cardiology demand.
Application:
Clinical use case concentration shapes transducer frequency selection and software module configuration.
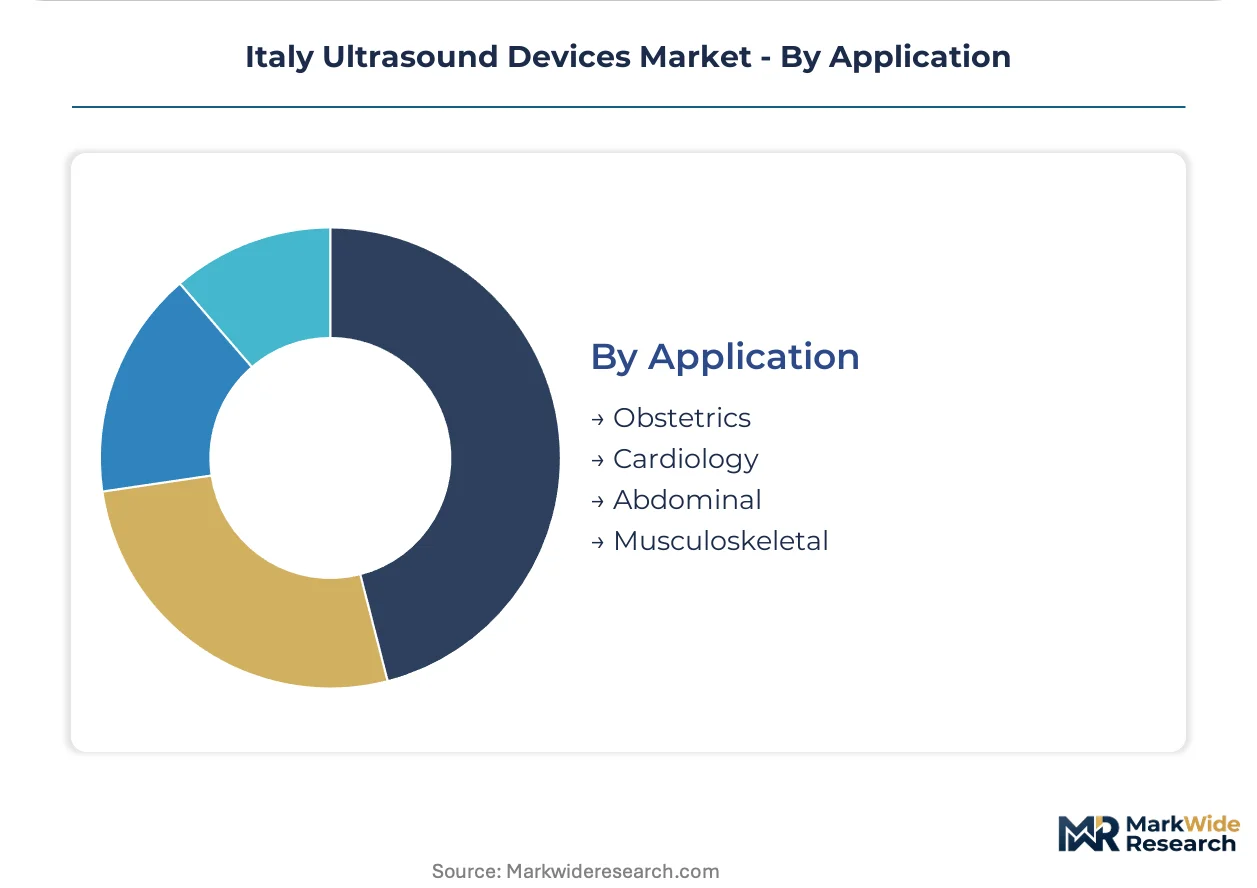
- Cardiology:Echocardiography demands phased-array probes at two-to-four megahertz for thoracic penetration, combined with continuous-wave and pulsed-wave Doppler for pressure gradient calculation. Regional screening programs in Lombardy and Veneto are pulling demand toward systems with AI-assisted wall-motion analysis.
- Obstetrics:Fetal imaging requires convex and linear probes spanning five-to-eight megahertz for gestational age dating, anomaly detection, and biophysical profiling. Rome's maternal-fetal medicine units anchor procurement for advanced 4D-capable platforms.
- Abdominal:General-purpose convex probes serve liver, renal, and gallbladder assessment across emergency and outpatient settings.
- Musculoskeletal:High-frequency linear arrays above ten megahertz visualize tendon, ligament, and peripheral nerve pathology, though CT and MRI substitution is constraining ultrasound share in Emilia-Romagna's orthopedic centers.
Cardiology commands premium system pricing. Obstetrics retains stable procedural volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's ultrasound consumption pattern diverges sharply from neighbors, with northern industrial regions favoring premium cart-based systems for tertiary cardiac screening while southern provinces drive handheld adoption for rural outreach.
Lombardy
Milan's university hospitals anchor procurement volume for AI-integrated Doppler systems under Veneto-influenced regional mandates. The Ministry of Health's reimbursement recalibration for non-invasive cardiac screening channels capital toward tertiary echocardiography capacity. Diagnostic center networks across the industrial corridor are unbundling equipment acquisition from service contracts.
Lazio
Rome's public hospital network rotates toward portable systems to expand screening capacity within fixed floor space constraints. The Directorate General for Medical Devices enforces CE marking compliance under EU MDR for all new installations. Maternal-fetal medicine units in the capital anchor procurement for advanced 4D-capable obstetric platforms.
Emilia-Romagna
Independent imaging chains prioritize throughput-per-square-meter with automated measurement protocols. Regional hospital budgets redirect capital toward MRI systems for orthopedic imaging, compressing ultrasound share in musculoskeletal diagnostics. Bologna's procurement committees now dominate total-cost-of-ownership modeling across seven-to-ten-year depreciation cycles.
Veneto
The regional health authority layers AI-integration mandates atop EU Medical Device Regulation compliance for hospital procurement. Outcome-based reimbursement pilots for AI-assisted cardiac screening reward vendors demonstrating diagnostic accuracy improvements. Verona and Padua anchor cardiovascular center scaling for early detection programs.
Sicily and Calabria
Southern provinces present infrastructure gaps that favor lease-to-own portable systems with bundled training packages. Ambulatory clinics adopt handheld ultrasound for rural outreach beyond hospital radiology departments. Procurement constraints here diverge sharply from northern premium-system preferences.
Italy Ultrasound Devices Market Competitive Landscape
Capability concentration sits with specialized cardiovascular imaging developers; scale advantage sits with diversified medical technology conglomerates. The vendor base separates into three tiers: global imaging majors with full modality portfolios, regional specialists with Mediterranean-market focus, and emerging Asian manufacturers competing on portable system economics. Strategic moves center on modular software registration to isolate AI regulatory exposure from hardware approvals, plus aftermarket service unbundling to capture recurring revenue streams.
Among diversified imaging majors, Siemens Healthineers and GE Healthcare occupy positions anchored by extensive service networks and university hospital partnerships across Milan and Rome. Esaote SpA exemplifies the regional specialist archetype with Italy-rooted development of musculoskeletal and cardiovascular systems. These three represent distinct competitive vectors: scale-driven platform breadth, recurring service revenue capture, and localized clinical application specialization.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| GE Healthcare |
| Mindray Medical International Limited |
| Samsung Medison |
| Philips Healthcare |
| Canon Medical Systems |
| SonoScape Medical Corp |
| Esaote SpA |
| Others |
Supply & Pricing Matrix
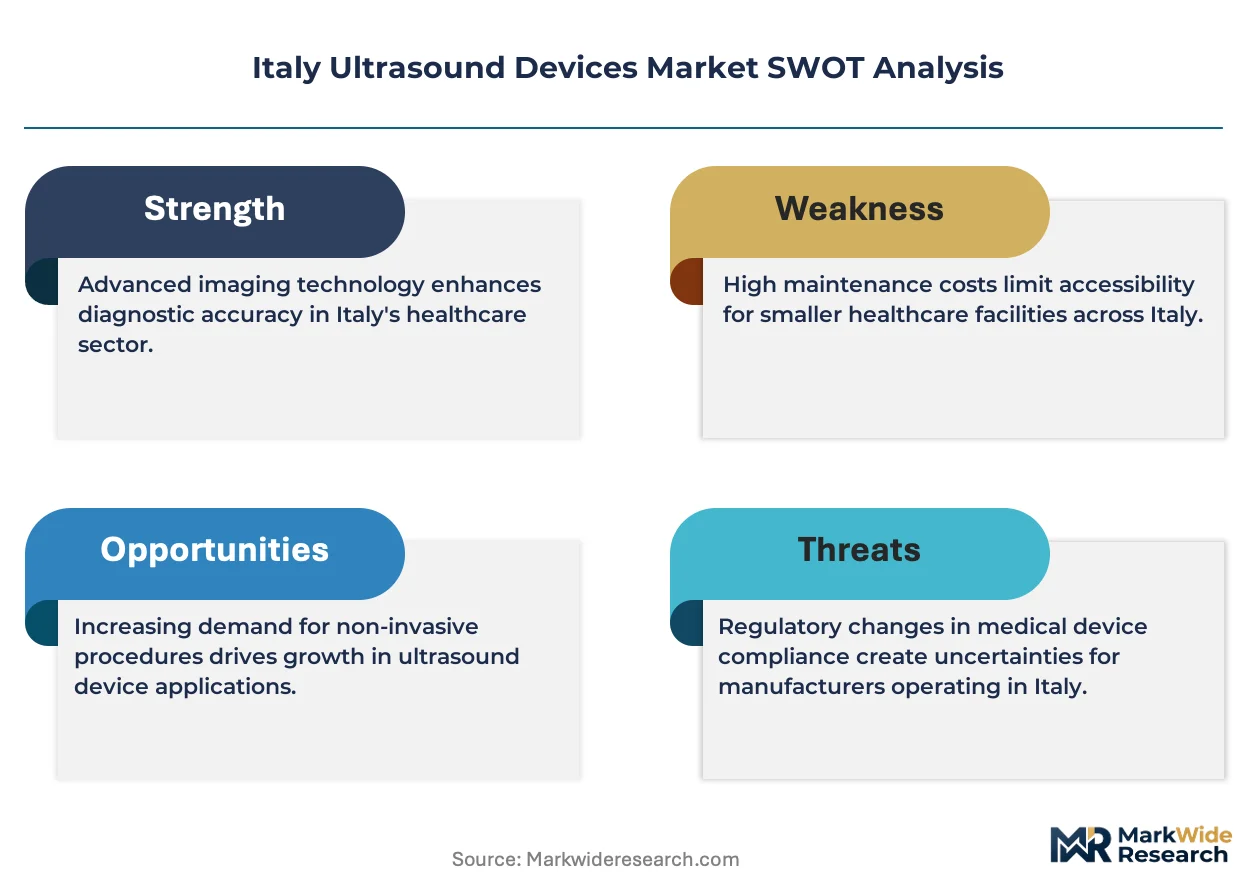
The Genoa-Milan logistics corridor shapes cost dynamics across Italian ultrasound procurement, with freight volatility from East Asian component hubs amplifying price differentiation between premium cart-based systems and economy portable units while compressing margins on mid-tier configurations.
Pricing Analysis
Long-term service contracts dominate hospital procurement in Lombardy and Veneto, with seven-to-ten-year total-cost-of-ownership agreements separating premium AI-integrated platforms from standard CE-marked systems and economy handheld devices lacking diagnostic software modules. Price differentiation hinges on certification tier under EU MDR and after-sales service bundling, with unbundled maintenance contracts gaining share in Emilia-Romagna's independent imaging chains. Pricing pressure stems from CT and MRI substitution in orthopedic applications, forcing ultrasound vendors to absorb training costs for sonographer-deficient clinics. Ambulatory settings in southern provinces exhibit highest price sensitivity, while Milan's university hospitals prioritize diagnostic accuracy over acquisition cost.
Supply Chain Analysis
Piezoelectric crystal feedstock concentrates in Chinese and Japanese specialty material suppliers, with Italian manufacturers drawing from South Korean wafer processing facilities for high-frequency transducer arrays. Single-crystal silicon substrates, ceramic piezoelectric composites, and specialized acoustic lens polymers constitute critical input dependencies. Single-source vulnerability from East Asian shipping chokepoints exposes procurement to input cost swings and extended lead times. Distribution runs through regional health authority tenders in northern Italy and direct manufacturer relationships for southern clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified sonographer shortages constrain service expansion across Italian diagnostic networks, creating a capability gap that vendors must address through embedded training or automated AI protocols to unlock latent demand in underserved provinces.
For Market Incumbents: Pre-empt service contract defection in Lombardy by modularizing software updates to isolate AI regulatory exposure from hardware CE approvals, while accelerating backward integration into transducer material supply to offset East Asian shipping volatility. Siemens Healthineers and GE Healthcare should leverage existing university hospital partnerships to pilot outcome-based reimbursement models before Veneto's mandates spread regionally. For New Entrants and Emerging Players: Establish a beachhead in Sicily and Calabria through lease-to-own portable systems with bundled sonographer training, exploiting the infrastructure gap that northern vendors overlook. Target ambulatory cardiology screening in southern provinces where capital constraints exclude premium cart-based competition, using 5G-enabled telemedicine integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core imaging divisions amid MDR compliance cost escalation. Long-term viability favors vendors with modular AI software architectures and captive service networks. Monitor Italy's transposition of the EU AI Act into medical device classification as the inflection signal for regulatory-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance timelines for AI-integrated systems determine competitive access to Lombardy and Veneto procurement channels. |
| Hospital System Partnership | University hospital alliances in Milan and Rome anchor reference sites for cardiovascular screening expansion. |
| Software Companion Development | AI-assisted wall-motion analysis modules attract premium positioning under regional outcome-based reimbursement pilots. |
| Reimbursement Strategy | Alignment with Ministry of Health non-invasive cardiac screening schedules shapes capital committee priorities. |
| Backward Integration | In-house transducer material production mitigates East Asian supply concentration and shipping cost volatility. |
Research Methodology
Desk research of EU Medical Device Regulation filings, Italian regional health authority procurement databases, and ISO 13485 quality management records preceded structured interviews with hospital biomedical engineers, diagnostic center operations directors, GPO contracts managers, and Ministry of Health regulatory officials. Secondary validation drew from CE marking documentation, reimbursement schedule updates, and trade flow data for piezoelectric material imports. Bottom-up installation base modeling triangulated against top-down market sizing from capital expenditure disclosures.
Assumptions held fixed across the analysis window include EU MDR enforcement intensity and Ministry of Health reimbursement schedules for non-invasive cardiac screening, while variables tested included AI Act transposition timing and sonographer training pipeline expansion. Segmentation dimensions modeled encompass product configuration, end-user setting, imaging technology, and clinical application. CAGRs derived from installed base replacement cycles and capacity expansion in Milan and Rome cardiovascular centers, with sensitivity analysis on portable system penetration rates in southern provinces.
Macroeconomic conditions sit as an overlay; deviation in euro-yen exchange rates or East Asian shipping costs would shift the trajectory. Forecasts reflect these assumptions alongside regulatory implementation schedules. Cross-checking against Italian hospital capital expenditure surveys and regional health authority budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Light Therapy Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Deaver Retractor Market
Medical Devices
Patellar Implant Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Infusion Management Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Global Micro Guide Catheters Market