
 Europe Beta-Glucan Market | 2026-2036
Europe Beta-Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Beta-Glucan Market Foresight
The capability gap between integrated biotech refiners and commodity extractors is collapsing as purification costs fall and toll manufacturing spreads. Kerry Group PLC leverages its yeast fermentation infrastructure to anchor supply security for European nutraceutical customers. DSM-Firmenich AG sustains premium positioning through its synthetic biology investments in precision beta-glucan structures. Leiber GmbH dominates brewing-derived beta-glucan segments through captive access to spent yeast streams across German and Czech facilities.
Beta-glucan comprises a class of glucose polymers linked by beta-glycosidic bonds, with yeast sources typically carrying beta-1,3/1,6 branching patterns that trigger immune cell receptor recognition while cereal variants exhibit linear beta-1,3/1,4 structures valued for cholesterol modulation. Yeast beta-glucan commands the largest revenue pool in nutraceutical applications where immune claims carry premium pricing power. Mushroom beta-glucan posts the fastest growth trajectory as adaptogenic positioning gains traction among European wellness brands seeking differentiation from conventional supplements.
EFSA novel food assessments and EMA pharmacovigilance frameworks govern ingredient safety substantiation and health claim validation across European jurisdictions, with national regulators such as Germany's BfR adding layer-specific requirements for fermented derivatives. REACH compliance obligations and the EU Green Deal bioeconomy targets increasingly filter raw material sourcing decisions toward circular feedstocks. Stakeholders must monitor how EFSA's evolving guidance on immune-related health claims reshapes permissible product positioning and reformulation investments.
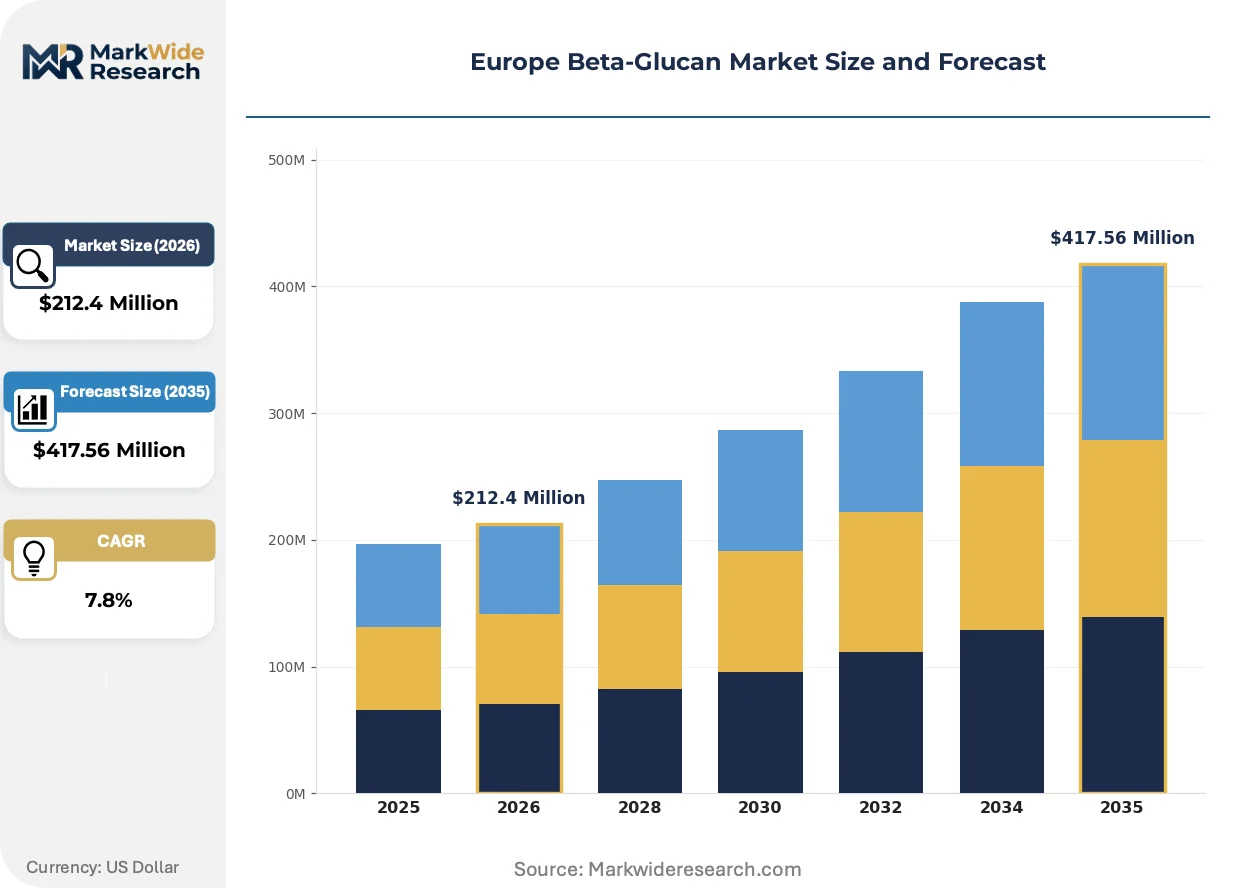
Market Dynamics
Purification cost compression and toll manufacturing diffusion are collapsing the historical capability gap between integrated biotech refiners and commodity extractors across European beta-glucan supply chains.
Growth Catalysts
- EU Green Deal bioeconomy targets:Circular feedstock mandates redirect raw material sourcing toward spent yeast and brewing residues, expanding viable supply bases for nutraceutical manufacturers.
- Germany's functional ingredient cluster density:The concentration of formulators and supplement manufacturers in Bavaria and Baden-Württemberg creates localized demand pull for immune-health positioning.
- EFSA novel food pathway maturation:Streamlined safety substantiation procedures accelerate time-to-market for mushroom-derived beta-glucan entrants seeking adaptogenic differentiation.
Market Restraints
- Input cost volatility in yeast fermentation:Molasses and dextrose price swings compress margin predictability for biotech refiners dependent on carbohydrate feedstocks.
- Supply concentration in German brewing corridors:Captive access to spent yeast streams by integrated players creates bottleneck risk for independent extractors seeking cereal-alternative sources.
- Technical limitation in branching pattern precision:Synthetic control over beta-1,3/1,6 versus beta-1,3/1,4 linkages remains constrained, limiting structure-specific immune claim substantiation.
Strategic Opportunities
- Underpenetrated Polish and Romanian markets:Eastern European wellness retail channels show minimal beta-glucan SKU penetration relative to Western European pharmacy density.
- Regulatory tailwind from EFSA immune claim guidance evolution:Pending clarification on permissible phrasing creates first-mover advantage for dossier-ready applicants.
- Technology convergence of precision fermentation and synthetic biology:Microbial chassis engineering enables de novo production of rare mushroom beta-glucan structures without agricultural cultivation cycles.
Industry Challenges
- Specialized bioprocess engineering talent scarcity:European universities produce insufficient graduates with combined fermentation science and downstream purification expertise.
- REACH compliance timeline compression:Registration dossier preparation for novel beta-glucan derivatives demands 18-24 month lead times that misalign with product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Beta-Glucan Market |
| Market Size in 2026 | $212.4 Million |
| Market Size in 2035 | $417.56 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Beta-Glucan, Mushroom Beta-Glucan, Cereal Beta-Glucan, Grain Beta-Glucan Application: Nutraceuticals, Food & Beverages, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores End User: Healthcare Industry, Food Manufacturers, Cosmetic Companies, Nutritional Supplements |
| Companies Covered | Tate & Lyle PLC, Kerry Group PLC, DSM-Firmenich AG, The Merck Group, Lesaffre Group, Kemin Industries, Lallemand Inc., Leiber GmbH, BENEO GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Beta-Glucan Market Shifts & Advancements
Continuous processing technologies and modular bioreactor systems are compressing capital requirements and enabling distributed production footprints across European beta-glucan manufacturing.
Precision fermentation platforms using engineered yeast strains are miniaturizing the production economics of beta-glucan with specific branching patterns. Nutraceutical contract manufacturers in the Netherlands and Denmark are adopting these systems at pilot scale. The technology is miniaturizing the minimum viable scale for immune-active ingredient production from 10,000-liter to 2,000-liter bioreactor volumes.
REACH authorization requirements for novel extraction solvents are tightening purity specifications for beta-glucan isolates entering cosmetic and pharmaceutical applications. ECHA's expanded substance evaluation workload is extending registration timelines for fermentation-derived variants. German and French formulators are responding by qualifying alternative aqueous extraction processes that preempt authorization risk.
Pharmacy channel consolidation across Southern Europe is compressing the number of stocking decisions for immune supplements. Independent pharmacy networks in Spain and Italy are ceding shelf space to centralized purchasing consortia. This consolidation is most visible in Milan and Barcelona, where category managers now demand clinical dossiers that smaller beta-glucan suppliers cannot assemble.
Europe Beta-Glucan Market Segmentation
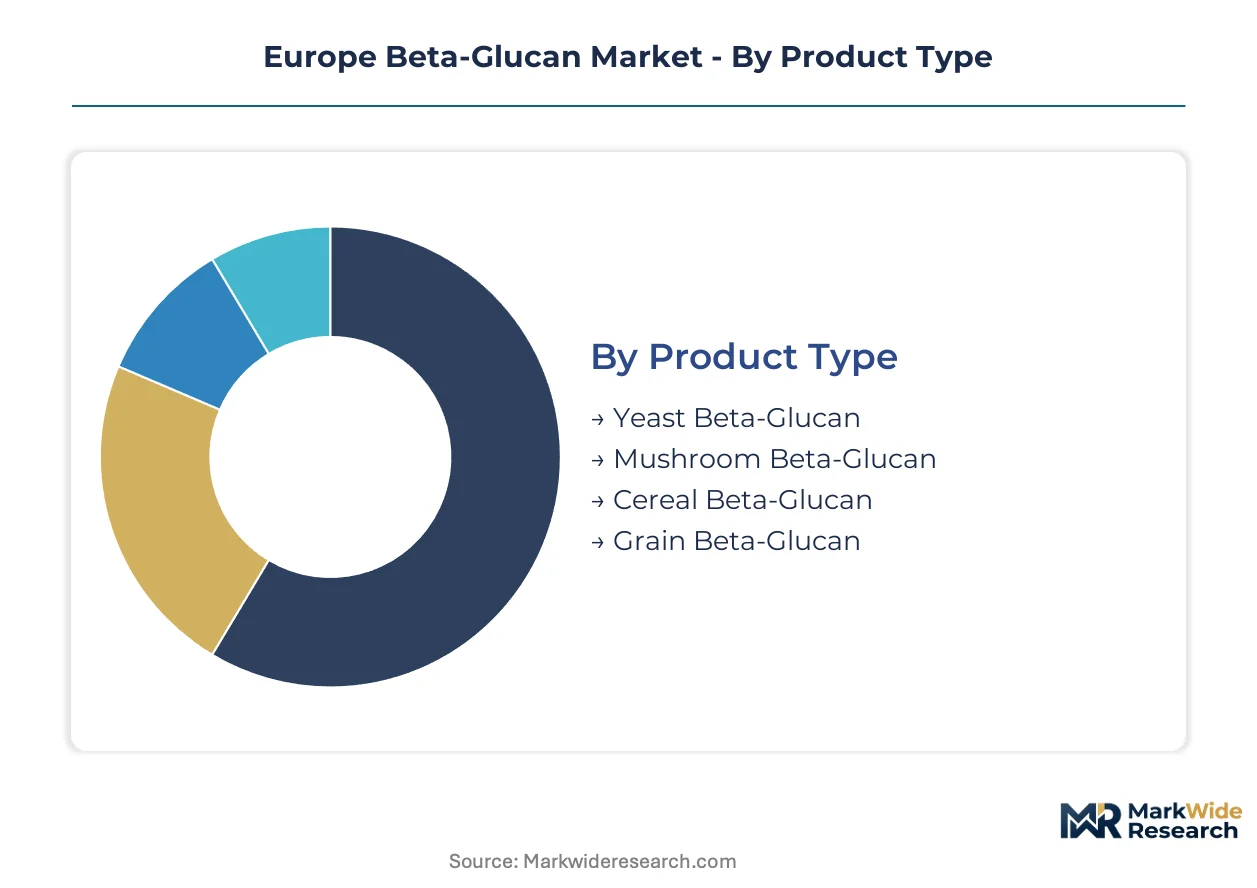
Beta-glucan sourcing decisions in Europe hinge on branching pattern specificity and EFSA substantiation pathways, with each product type carrying distinct immune-modulation or metabolic health credentials. Application-level segmentation reveals how pharmacy channel consolidation and wellness retail fragmentation create divergent margin structures across customer touchpoints.
Product Type:
Yeast-derived segments face intensifying substitution pressure from precision-fermented alternatives as synthetic biology platforms collapse production cost differentials.
- Yeast Beta-Glucan:Beta-1,3/1,6 branched glucan polymers extracted from Saccharomyces cerevisiae cell walls trigger Dectin-1 receptor binding for immune cell activation. Bavarian supplement manufacturers concentrate procurement through Kerry Group's fermentation infrastructure to secure supply continuity for immune-positioned SKUs.
- Mushroom Beta-Glucan:Lentinan and schizophyllan structures from Lentinula edodes and Schizophyllum commune carry adaptogenic positioning that commands premium pricing in German wellness retail. EFSA novel food pathway maturation accelerates dossier submissions from Dutch and Danish contract manufacturers seeking differentiation from conventional yeast sources.
- Cereal Beta-Glucan:Linear beta-1,3/1,4 structures from oat and barley fractions target cholesterol-reduction claims in functional food applications across Scandinavian markets.
- Grain Beta-Glucan:Wheat and rye-derived variants serve cost-sensitive bakery fortification segments where soluble fiber labeling drives formulation decisions.
Yeast Beta-Glucan anchors the volume base while Mushroom Beta-Glucan climbs the fastest as adaptogenic positioning gains traction among European wellness brands.
Application:
Margin concentration follows health claim substantiation rigor, with segments bearing EFSA-approved immune or metabolic claims capturing pricing premiums over general wellness positioning.
- Nutraceuticals:Capsule and tablet formats delivering standardized beta-glucan doses dominate immune health positioning in German and Austrian pharmacy channels. DSM-Firmenich's synthetic biology investments enable precision structures that support structure-function claims for premium supplement tiers.
- Food & Beverages:Functional dairy and beverage fortification leverages cereal beta-glucan solubility for cholesterol management claims in Nordic markets. Finland's Valio and Sweden's Skånemejerier drive formulation adoption through established consumer trust in oat-derived ingredients.
- Pharmaceuticals:Parenteral-grade beta-glucan isolates for oncology adjuvant therapy face EMA pharmacovigilance oversight and GMP manufacturing requirements that limit supplier qualification.
- Cosmetics:Topical formulations emphasizing skin barrier repair and anti-inflammatory positioning source ultra-pure yeast extracts through REACH-compliant aqueous extraction processes.
Nutraceuticals capture the dominant revenue pool while Pharmaceuticals present the steepest regulatory barrier to entry for non-integrated suppliers.
Distribution Channel:
Channel selection determines customer acquisition economics, with digital-native brands bypassing traditional pharmacy gatekeepers to reach immune-conscious consumers directly.
- Online Retail:Direct-to-consumer platforms and Amazon Marketplace enable subscription-based immune supplement models that bypass Southern European pharmacy consolidation pressures. Dutch fulfillment centers serve cross-border demand into underpenetrated Polish and Romanian markets.
- Supermarkets:Mass-market functional food placement depends on retailer-specific clean-label requirements and slotting fee negotiations that favor suppliers with established EFSA health claim portfolios.
- Specialty Stores:Independent health food retailers in Germany and Switzerland maintain curated beta-glucan assortments emphasizing organic and non-GMO certifications.
- Health Food Stores:Pharmacy-adjacent chains in Austria and Belgium stock clinically positioned yeast beta-glucan alongside practitioner-grade supplement lines.
Online Retail expands most quickly while Health Food Stores retain the highest customer lifetime value through practitioner recommendation dependencies.
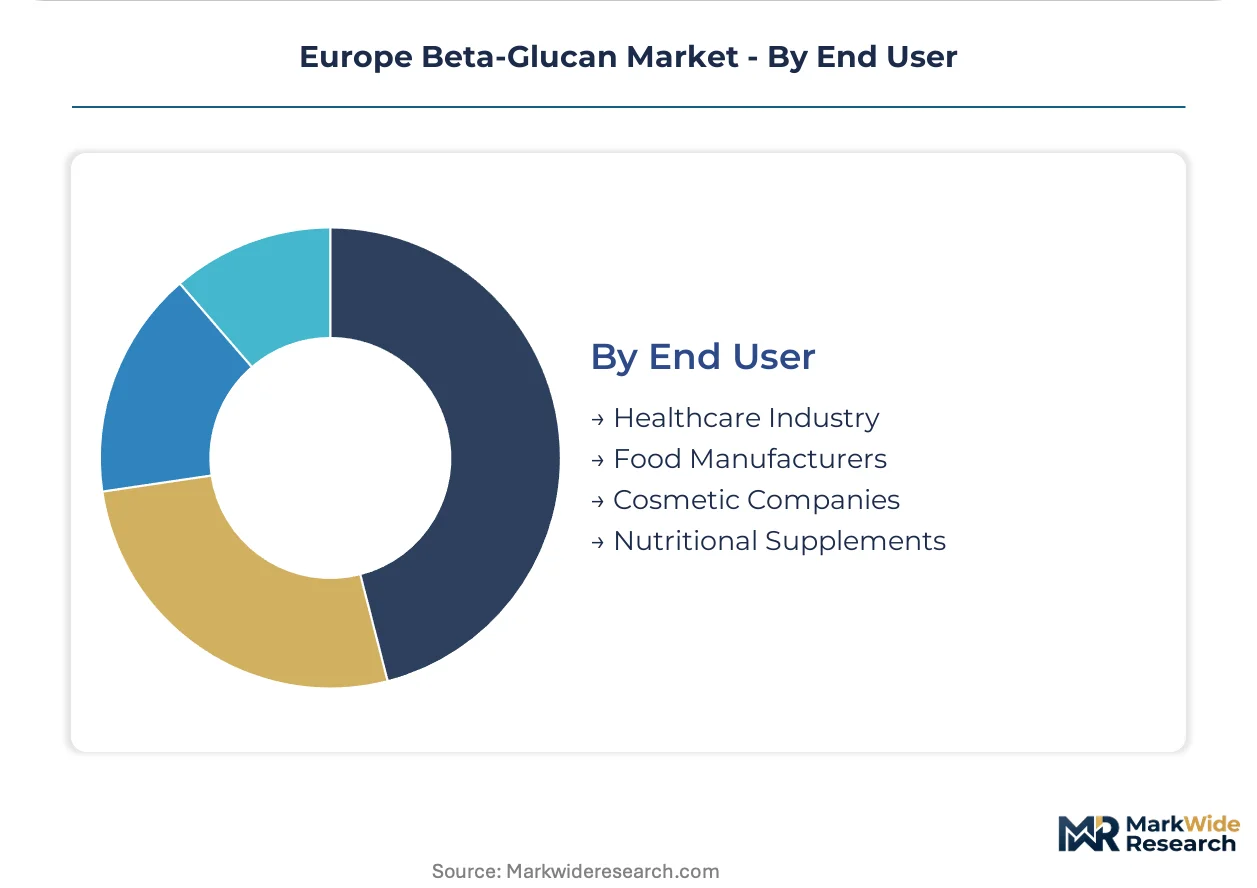
End User:
Procurement sophistication varies sharply, with pharmaceutical and nutraceutical buyers demanding batch-specific purity certificates that commodity food manufacturers rarely require.
- Healthcare Industry:Hospital and clinic procurement of immune-modulating beta-glucan for oncology and post-surgical applications requires EMA-compliant pharmacovigilance documentation and cold-chain logistics capabilities.
- Food Manufacturers:Industrial buyers prioritize cost-per-functional-unit metrics and supply security through multi-sourcing strategies across German and Nordic ingredient distributors.
- Cosmetic Companies:Formulation houses in France's Île-de-France cluster specify low-molecular-weight beta-glucan fractions for skin penetration optimization in anti-aging serums.
- Nutritional Supplements:Contract manufacturers in Bavaria and Baden-Württemberg consolidate volume through toll-processing agreements with Leiber GmbH and other spent-yeast processors.
Nutritional Supplements generate the highest transaction frequency while Healthcare Industry contracts deliver the longest-term revenue visibility through multi-year supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmacy channels while Polish and Romanian markets trade at structural discounts due to lower health claim substantiation requirements and fragmented retail distribution.
Germany
Bavarian and Baden-Württemberg formulator clusters drive concentrated demand for immune-positioned beta-glucan ingredients. BfR adds layer-specific requirements for fermented derivatives atop EFSA novel food assessments. Leiber GmbH anchors supply security through captive spent yeast processing across German and Czech facilities.
Netherlands
Contract manufacturers near Rotterdam and Amsterdam adopt precision fermentation platforms at pilot scale for adaptogenic mushroom beta-glucan production. REACH compliance obligations filter raw material sourcing toward circular feedstocks under EU Green Deal targets. Dutch fulfillment centers serve cross-border e-commerce demand into underpenetrated Eastern European markets.
France
Cosmetic formulators in the Île-de-France cluster specify low-molecular-weight beta-glucan fractions for skin barrier repair applications. ANSM oversight of topical ingredient safety substantiation runs parallel to ECHA registration requirements for novel extraction solvents. Paris-based formulation houses increasingly qualify aqueous extraction processes to preempt authorization risk.
Poland
Warsaw and Kraków wellness retail channels show minimal beta-glucan SKU penetration relative to Western European pharmacy density. EFSA novel food pathway maturation accelerates dossier submissions from regional distributors seeking immune claim differentiation. Local supplement brands exploit regulatory arbitrage by sourcing unstandardized cereal beta-glucan for cost-positioned product lines.
Sweden
Nordic functional food manufacturers leverage consumer trust in oat-derived ingredients for cholesterol management positioning. Valio and Skånemejerier drive cereal beta-glucan adoption through established dairy fortification partnerships. Stockholm-based ingredient distributors consolidate procurement volumes across Scandinavian markets to secure supply continuity.
Europe Beta-Glucan Market Competitive Landscape
Concentration sits with integrated biotech refiners possessing captive fermentation infrastructure and toll manufacturing networks. The capability gap between these operators and commodity extractors collapses as purification costs fall. Three archetypes dominate: yeast fermentation specialists with brewing residue access, synthetic biology platforms engineering precision structures, and toll processors serving contract manufacturing demand. Competitive moves center on backward integration into spent yeast streams and technology licensing for modular bioreactor deployment.
Among integrated fermentation specialists, Kerry Group PLC and Leiber GmbH exemplify the yeast-derived supply archetype through their positioning within European nutraceutical value chains. DSM-Firmenich AG occupies the precision-structure tier, representing synthetic biology investments in beta-glucan engineering. These three anchors illustrate how supply security and claim substantiation capabilities separate premium-positioned ingredient suppliers from commodity processors competing on cost-per-functional-unit metrics alone.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group PLC |
| DSM-Firmenich AG |
| The Merck Group |
| Lesaffre Group |
| Kemin Industries |
| Lallemand Inc. |
| Leiber GmbH |
| BENEO GmbH |
| Others |
Supply & Pricing Matrix
Scale economies in spent yeast processing anchor price floors across German and Czech supply corridors, concentrating margin capture among integrated biotech refiners with captive fermentation infrastructure while toll manufacturers compete on throughput efficiency rather than structural cost advantage. This scale dynamic compresses pricing power for independent extractors lacking backward integration into brewing residue streams.
Pricing Analysis
Configured-to-order pricing for precision-fermented beta-glucan with specific beta-1,3/1,6 branching patterns commands substantial premiums over standard yeast-derived grades. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-substantiated immune claim products from general wellness positioning and unstandardized cereal alternatives. Pricing pressure stems from precision fermentation cost compression as modular bioreactor systems reduce minimum viable scale thresholds. Food manufacturers exhibit highest price sensitivity through cost-per-functional-unit procurement metrics, while pharmaceutical buyers prioritize batch certification over unit economics.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade beta-glucan isolates extend through EMA pharmacovigilance documentation and GMP batch release protocols. Supply concentrates in Germany, Netherlands, and Denmark, with German brewing corridors anchoring spent yeast availability. Raw material dependencies center on molasses and dextrose feedstocks for fermentation, aqueous extraction solvents for purification, and specialized chromatography resins for branching pattern separation. Single-source vulnerability runs through Leiber GmbH's captive spent yeast access across Bavarian and Czech facilities. Distribution runs through Rotterdam and Amsterdam contract manufacturing hubs serving cross-border nutraceutical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as precision fermentation infrastructure enables de novo production of rare mushroom beta-glucan structures, collapsing traditional agricultural cultivation cycles and creating interoperability between synthetic biology platforms and nutraceutical contract manufacturing networks.
For Market Incumbents: Shield premium positioning through EFSA dossier pre-positioning ahead of immune claim guidance evolution, while deepening captive access to spent yeast streams across German and Czech brewing corridors to forestall toll manufacturing encroachment. Precision fermentation entrants threaten structure-specific claim differentiation; respond with synthetic biology licensing partnerships that preserve margin architecture. For New Entrants and Emerging Players: Differentiate on adaptogenic positioning through EFSA novel food pathway submissions for mushroom-derived lentinan and schizophyllan structures, exploiting the fastest-growing segment trajectory. Polish and Romanian wellness retail channels present the most penetrable geography given minimal SKU density relative to Western European pharmacy concentration. Pursue direct-to-consumer subscription models via Dutch fulfillment centers to bypass Southern European pharmacy consolidation gatekeepers. For Investors and Strategic Acquirers: Synthetic biology platforms with precision fermentation capabilities and EFSA-ready dossier portfolios represent the highest-conviction acquisition archetype for exposure to immune claim premiumization. Long-term viability hinges on regulatory tailwinds from EFSA immune claim clarification and technology convergence timelines for microbial chassis engineering. Watch for EFSA guidance publication as the definitive inflection signal for premium pricing power reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spent Yeast Streams | Captive feedstock access secures supply continuity against molasses price volatility for Kerry Group and Leiber GmbH. |
| EFSA Novel Food Dossier Submission | Accelerated pathway maturation enables Dutch and Danish contract manufacturers to claim adaptogenic differentiation ahead of competitors. |
| Precision Fermentation Platform Deployment | Modular bioreactor adoption at 2,000-liter scale miniaturizes minimum viable production economics for immune-active ingredients. |
| REACH-Compliant Aqueous Extraction Qualification | French and German formulators preempt ECHA authorization risk for cosmetic-grade beta-glucan isolates. |
| Cross-Border E-Commerce Fulfillment Expansion | Dutch centers serve underpenetrated Polish and Romanian markets with subscription-based immune supplement models. |
Research Methodology
Cross-validation between primary interviews with fermentation scientists, nutraceutical contract manufacturing executives, and EFSA regulatory consultants anchors the qualitative findings, while secondary validation draws from EFSA novel food register entries, EMA pharmacovigilance databases, and REACH registration dossiers. Bottom-up triangulation across ingredient supplier production disclosures and top-down reconciliation with EU Green Deal bioeconomy implementation reports ensure dimensional consistency. Primary fieldwork encompassed technical R&D directors at German biotech refiners, procurement leads at Bavarian supplement manufacturers, and downstream distribution channel partners in Netherlands and Denmark.
Sensitivity analysis around molasses feedstock cost assumptions, EFSA approval timeline distributions, and precision fermentation yield curve maturation informs the analytical framework across the analysis window. Segmentation dimensions modeled include beta-glucan source type, branching pattern specificity, application-grade purity tier, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical novel food approval velocity and pharmaceutical-grade qualification timelines. Industry-specific forecast inputs encompass ECHA substance evaluation workload projections and EU Green Deal circular feedstock mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside EFSA immune claim guidance evolution, REACH authorization timeline compression, or precision fermentation yield breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway maturation and technology cost curves. Specific risk factors that could revise projections include EMA pharmacovigilance framework tightening for oncology adjuvant applications and raw material sourcing disruption from EU Green Deal feedstock mandate acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
North America Bovine Lactoferrin Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Food Grade Beta-Alanine Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market