
 Global Malt Ingredients Market | 2026-2036
Global Malt Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Malt Ingredients Market Analysis
Market Context
Premium specialty malt specification upgrades is unwinding commodity pricing structures across the supply base. Viking Malt leverages its Nordic barley sourcing to dominate high-enzyme diastatic malt production for craft distillers. Muntons PLC anchors its position through integrated malting and extract manufacturing at its Suffolk facilities. Malteurop Group competes on geographic scale, operating maltings across France, Germany, and Australia to serve regional brewing clusters.
Technical Definition and Segment Structure
Malt ingredients comprise germinated cereal grains—principally barley and wheat—kilned to develop enzymatic activity, color, and flavor compounds measured by diastatic power and Lovibond ratings, serving as fermentable substrates and flavor carriers in food and beverage production. Malt extract leads value contribution due to its concentrated utility in bakery and confectionery applications where consistency and shelf stability outweigh raw grain handling costs. Malted barley dominates brewing volume, though crystal malt commands margin premiums from craft brewers seeking caramel and toffee flavor profiles. Powdered form captures pharmaceutical and nutraceutical demand where precise dosing and dry blending compatibility matter.
Regulatory Environment
REACH governs chemical inputs in European malt processing, while FDA food safety standards dictate mycotoxin thresholds and labeling for U.S.-destined extracts. The EU Green Deal's Farm to Fork strategy is tightening nitrogen fertilizer allowances, pressuring malting barley growers toward precision agriculture. Stakeholders must monitor carbon border adjustment mechanisms and evolving organic certification standards to secure contract renewals with sustainability-minded brewers and food manufacturers.
Market Dynamics
The EU Green Deal's Farm to Fork nitrogen restrictions are forcing malting barley growers toward precision agriculture protocols, compressing traditional procurement networks while specialty malt specifications fragment pricing structures across brewing and distilling supply bases.
Growth Catalysts
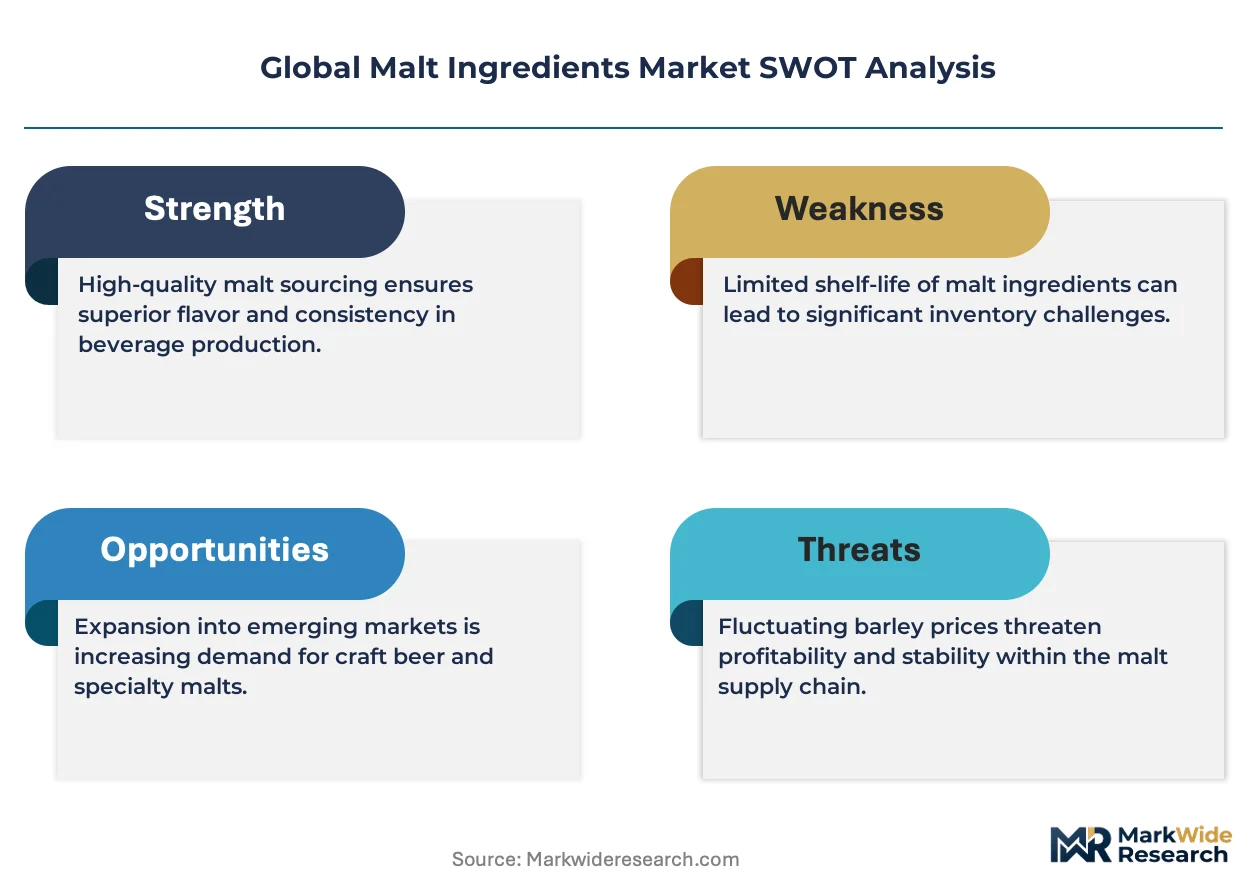
- EU Green Deal agricultural criteria:Lower-carbon barley cultivation protocols are redirecting contract flows toward certified growers in Germany and France, creating sourcing premiums for sustainability-minded craft brewers.
- Heritage malt variety demand:United Kingdom premium ale producers are commanding specialty volumes of Maris Otter and Golden Promise varieties, absorbing higher-cost kilned malts for flavor differentiation.
- High-enzyme diastatic malt:Craft distillers in Scotland and Kentucky are specifying elevated diastatic power for efficiency gains in mashing, pulling Nordic barley strains into premium positioning.
Market Restraints
- Barley input cost volatility:Fertilizer price swings tied to natural gas markets compress malting margins, particularly for smaller floor-malting operations lacking long-term grain contracts.
- Supply concentration in Nordic sourcing:High-enzyme malt production depends on specific Scandinavian barley genetics, creating geographic chokepoints for craft distilling supply security.
- REACH chemical input compliance:ECHA registration requirements for processing aids add fixed compliance costs that disadvantage smaller regional maltsters against integrated multinationals.
Strategic Opportunities
- India craft brewing emergence:Mumbai and Bangalore microbreweries are importing specialty crystal and roasted malts as domestic base malt production remains commodity-focused.
- Carbon border adjustment positioning:Early certification under evolving EU carbon accounting rules will secure contract renewals with multinational brewers facing Scope 3 disclosure mandates.
- Pharmaceutical maltodextrin applications:Powdered malt extract specifications for tablet binding and dry blending are opening technical partnerships with nutraceutical formulators in Switzerland and Germany.
Industry Challenges
- Kilning specialist skill scarcity:Traditional floor malting expertise for heritage variety processing is retiring faster than apprenticeship programs in Suffolk and Bamberg can replenish.
- Legacy equipment retrofit costs:Converting germination-kilning vessels for energy recovery and emissions compliance requires capital outlays that strain family-owned malting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Malt Ingredients Market |
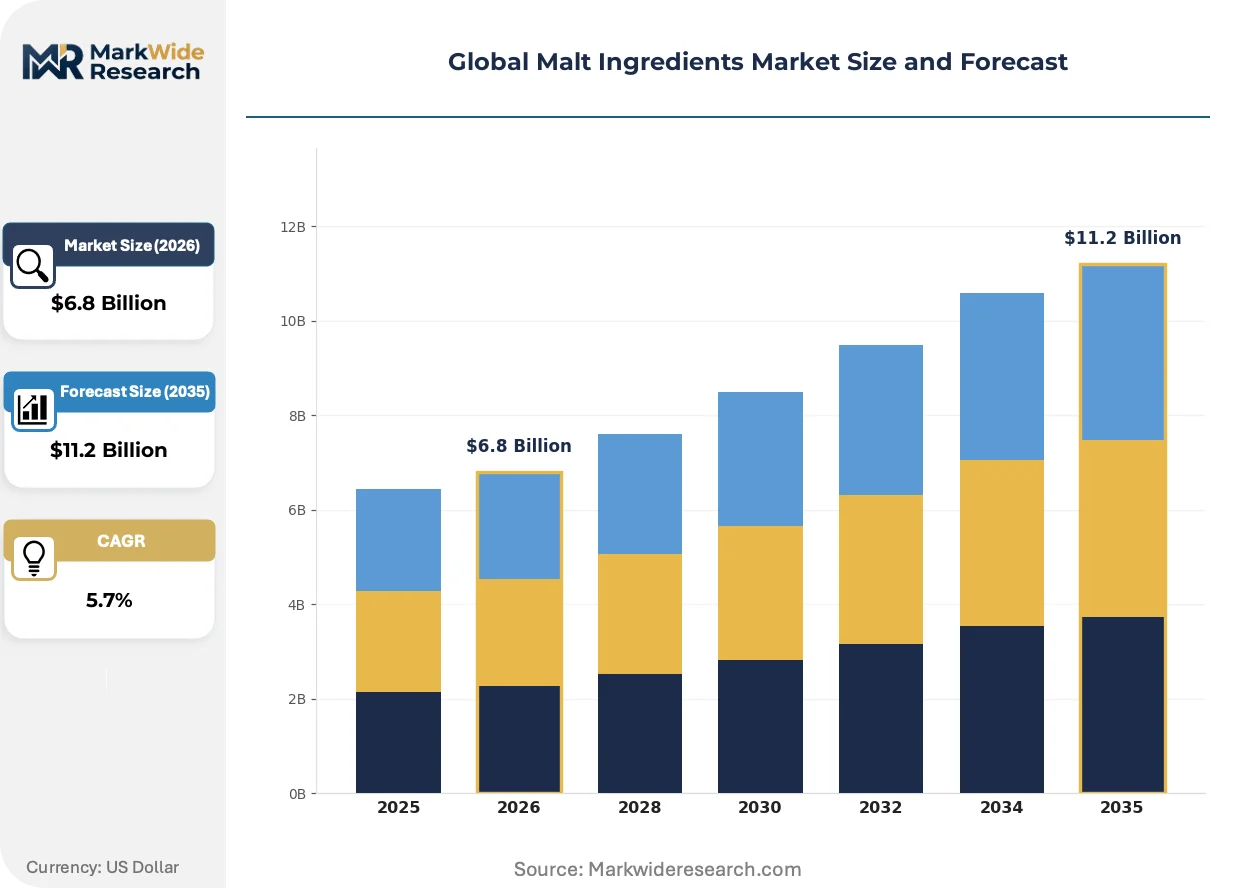
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Extract, Malted Barley, Malted Wheat, Crystal Malt Application: Brewing, Distilling, Baking, Confectionery End User: Food Industry, Beverage Industry, Pharmaceutical Industry, Nutraceuticals Form: Powdered, Liquid, Pelleted, Flaked |
| Companies Covered | Viking Malt, Muntons PLC, Malteurop Group, Cargill Malt, GrainCorp Limited, Boortmalt, Rahr Corporation, United Malt, Soufflet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Malt Ingredients Market Emerging Trajectories
Processing technology and sustainability verification are fragmenting traditional malt categories, as brewers and distillers demand traceable provenance alongside enzymatic performance guarantees that commodity specifications cannot deliver.
Precision kilning control systems using real-time moisture sensing and automated airflow modulation are bifurcating the market between standardized commodity malts and micro-lot specialty productions. Scottish and Japanese whisky distillers are adopting these systems for batch consistency in heritage variety processing. This technology is compressing the viable scale range for mid-tier regional maltsters unable to justify automation investment against craft premiums.
REACH authorization requirements for glyphosate residues in imported grain are tightening mycotoxin surveillance protocols across European malting facilities. FDA parallel standards for U.S.-destined extracts are forcing dual-track testing investments at integrated extract manufacturers. Small German floor-malting operations are responding through cooperative laboratory sharing arrangements to distribute compliance costs.
Direct contracting between craft brewers and named barley farms is displacing merchant-mediated grain procurement in heritage variety sourcing. United Kingdom cask ale producers and Colorado farmhouse breweries are specifying individual field provenance on packaging. This pattern is most visible in organic and biodynamic certification tiers where storytelling value commands finished-product pricing power.
Global Malt Ingredients Market Segmentation
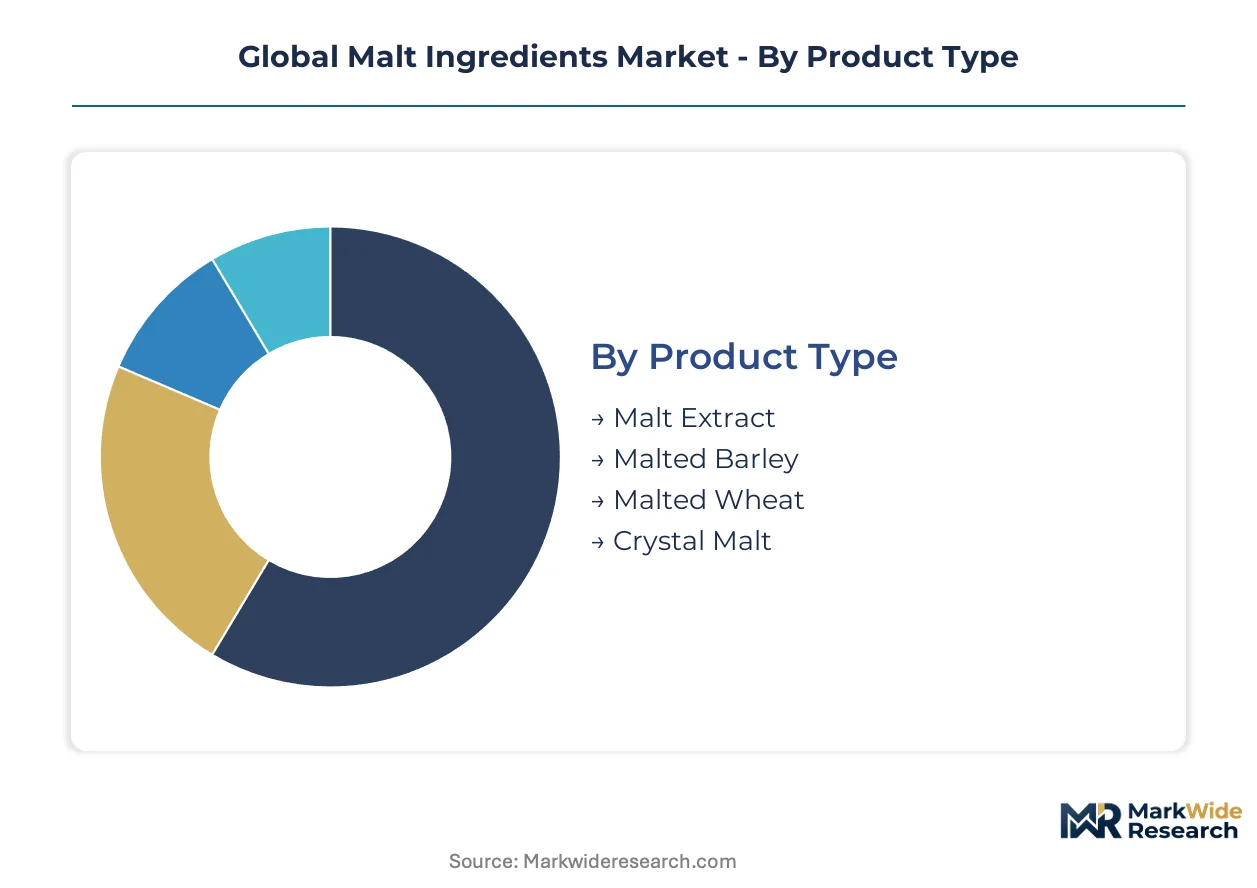
Segmentation in malt ingredients reveals how regulatory regimes, processing technologies, and end-use specifications create divergent value capture across supply tiers. Understanding these splits exposes where procurement premiums concentrate and where commodity pressures erode margins.
Product Type:
REACH authorization thresholds for processing residues and FDA mycotoxin standards split this category into compliance-heavy extracts versus raw grain segments with lighter regulatory overhead.
- Malt Extract:Concentrated enzymatic and carbohydrate solutions produced through mashing, filtration, and vacuum evaporation. Bakery and confectionery manufacturers in Germany and Switzerland absorb volumes where batch consistency and extended shelf stability justify liquid handling infrastructure and documentation burdens.
- Malted Barley:Kilned germinated barley delivering diastatic power measured in degrees Lintner and color in Lovibond units. Craft brewers across Colorado, Oregon, and Bavaria specify heritage varieties like Maris Otter, absorbing higher per-kilogram costs for provenance storytelling and flavor differentiation in premium ale portfolios.
- Malted Wheat:Lower enzyme activity than barley malt with distinctive protein contributions to mouthfeel. Belgian witbier producers and German Weissbier breweries anchor demand.
- Crystal Malt:Stewed and kilned specialty malt delivering caramelized sugars without enzymatic activity. Scottish distillers and American craft brewers specify for color and toffee notes.
Malted Barley handles the majority of throughput; Malt Extract is expanding most quickly on share as food manufacturers consolidate liquid ingredient sourcing.
Application:
End-use processing intensity and finished-product margin structures determine whether buyers absorb specialty premiums or default to commodity specifications.
- Brewing:Largest volume sink with fragmented demand across macro-lagers, craft ales, and non-alcoholic alternatives. German Reinheitsgebot traditions and American craft brewing movements pull divergent malt specifications.
- Distilling:Premiumization in Scotch whisky and American bourbon drives heritage variety contracting. Kentucky and Scottish distillers specify high-diastatic Nordic barley for mashing efficiency in high-gravity fermentations.
- Baking:Malt extracts and diastatic malt powders replace sugar and enhance crust color in artisan European bakeries.
- Confectionery:Malt extract provides viscosity and Maillard precursors in chocolate and caramel applications.
Brewing commands absolute volume; Distilling climbs fastest on value per kilogram as aged-spirit premiums sustain specialty malt contracting.
End User:
Documentation requirements and formulation precision separate pharmaceutical-grade buyers from commodity food and beverage processors.
- Food Industry:Bakery, confectionery, and savory applications consuming malt extracts and specialty malts for flavor and color. European organic certification tiers command sourcing premiums.
- Beverage Industry:Brewing and distilling operations with divergent specifications for enzymatic activity, color development, and provenance traceability.
- Pharmaceutical Industry:Maltodextrin and extract specifications for tablet binding, coating, and dry blend carriers. Swiss and German formulators demand batch-level certificate of analysis documentation.
- Nutraceuticals:Malt-based carriers and prebiotic formulations in sports nutrition and digestive health products.
The Beverage Industry moves the largest absolute tonnage; Pharmaceuticals posts the steepest expansion trajectory as excipient sourcing regionalizes away from Asian suppliers.
Form:
Handling economics and shelf stability requirements determine whether buyers absorb conversion premiums or tolerate raw grain logistics.
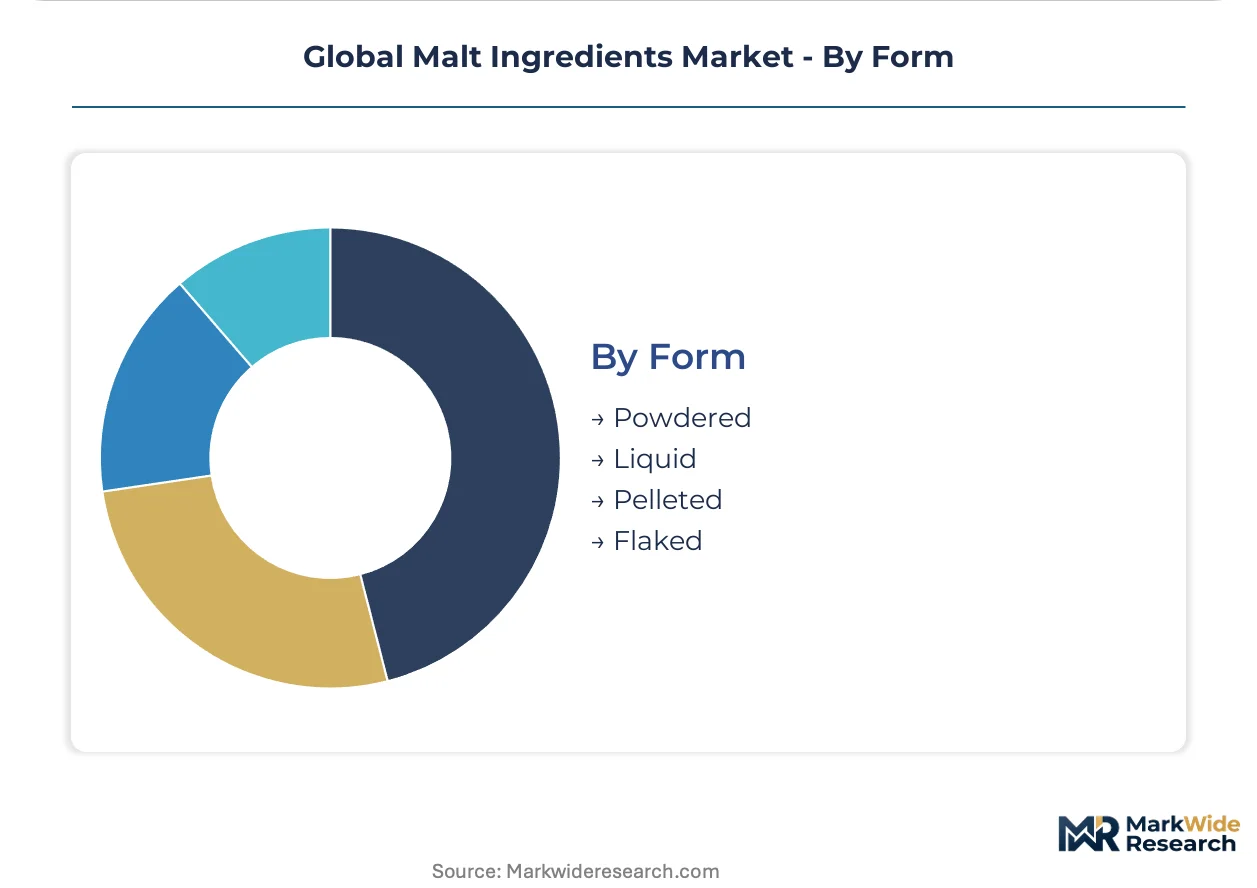
- Powdered:Spray-dried or roller-dried extracts with precise moisture specifications for dry blending compatibility. Pharmaceutical and nutraceutical formulators in Switzerland and Germany specify for tablet production.
- Liquid:Concentrated extracts with viscosity controlled for pumping and metering. Large bakeries and confectionery manufacturers in France and Italy prefer for continuous processing.
- Pelleted:Agglomerated malt products for controlled dissolution in brewing. Regional maltsters in Bamberg and Edinburgh supply craft brewers.
- Flaked:Pre-gelatinized malt for direct use in mashing without milling. Homebrew and small-scale craft operations in Portland and Manchester absorb volumes.
Liquid form dominates industrial throughput; Powdered form gains share fastest as pharmaceutical excipient demand regionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brewers in Germany and the United Kingdom absorb specialty malt premiums with minimal price elasticity, while commodity-focused buyers in Brazil and India default to base malt specifications where sourcing costs dominate supplier selection.
United States
Craft brewers in Colorado and Oregon specify heritage varieties like Maris Otter for flavor differentiation in premium ale portfolios. FDA mycotoxin thresholds and labeling requirements for malt extracts dictate dual-track testing investments at integrated manufacturers. Kentucky bourbon distillers anchor demand for high-diastatic Nordic barley strains in high-gravity fermentation protocols.
Germany
Reinheitsgebot traditions pull divergent malt specifications toward base malt purity, though Bavarian craft movements now absorb specialty crystal and roasted volumes. EU Green Deal nitrogen fertilizer restrictions pressure malting barley growers toward precision agriculture. Bamberg floor-malting operations supply regional craft brewers with heritage-processed kilned malts.
United Kingdom
Heritage malt varieties command sourcing premiums from cask ale producers specifying Maris Otter and Golden Promise for provenance storytelling. REACH chemical input registrations govern processing aids across Suffolk malting facilities. Scottish whisky distillers adopt precision kilning control systems for batch consistency in heritage variety processing.
India
Mumbai and Bangalore microbreweries import specialty crystal and roasted malts as domestic base malt production remains commodity-focused. FSSAI food safety standards regulate mycotoxin surveillance in imported grain shipments. Maharashtra and Karnataka brewing clusters absorb volumes where storytelling value supports finished-product pricing power.
Australia
Integrated malting operations serve regional brewing clusters across New South Wales and Victoria with geographic scale advantages. TGA-equivalent state-level food safety protocols govern extract manufacturing for pharmaceutical and nutraceutical applications. Sydney and Melbourne pharmaceutical formulators specify powdered malt extract for tablet binding and dry blending compatibility.
Global Malt Ingredients Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision kilning specialists commanding craft premiums while scale-integrated multinationals capture commodity volume. The vendor base spans Nordic barley geneticists, Anglo-Saxon heritage processors, and Antipodean geographic consolidators. Three archetypes dominate: heritage variety specialists with floor-malting expertise, integrated extract manufacturers with pharmaceutical-grade certification, and continental-scale grain handlers with backward barley procurement control. Competitive moves concentrate on cooperative laboratory sharing for REACH compliance cost distribution and direct farm contracting for provenance traceability.
Within the heritage processing tier, Muntons PLC anchors integrated malting and extract manufacturing capabilities, while Viking Malt exemplifies Nordic barley genetic specialization for high-enzyme diastatic production. Malteurop Group occupies the geographic scale position, operating maltings across multiple continental clusters to serve regional brewing demand.
| Leading Market Players |
|---|
| Viking Malt |
| Muntons PLC |
| Malteurop Group |
| Cargill Malt |
| GrainCorp Limited |
| Boortmalt |
| Rahr Corporation |
| United Malt |
| Soufflet Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting certification gates both supplier qualification and price differentiation simultaneously, as brewers and distillers now demand documented Scope 3 emissions data that only precision-agriculture barley growers can deliver. This bifurcation splits procurement flows between premium-contract heritage varieties and commodity base malts.
Pricing Analysis
Contracted malt supply agreements with multi-year service and technical support components capture lifetime value exceeding spot-market transactions. Three-tier pricing structure across premium heritage varieties, certified sustainable base malts, and commodity specifications reflects enzymatic performance, provenance documentation, and carbon intensity scores. Cost compression in commodity base malt is intensifying because fertilizer price volatility feeds through from natural gas markets. Macro-lager brewers exhibit highest price sensitivity, while Scotch whisky distillers absorb premiums for named-field Nordic barley with minimal elasticity.
Supply Chain Analysis
Inventory cycles for high-enzyme Nordic barley strains extend lead times beyond commodity grain procurement windows, forcing distillers to contract harvests eighteen months ahead. Supply concentrates in Germany, France, and Australia for malting capacity, while Nordic barley genetics for diastatic production centers on Denmark and Sweden. The chain rests on natural gas-dependent nitrogen fertilizers, precision agriculture equipment, and specialized kilning infrastructure. Single-source vulnerability in Scandinavian barley genetics creates chokepoint exposure for craft distilling. Distribution runs through integrated maltsters with direct brewery relationships rather than merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as craft brewing specification diversity outpaces integrated maltsters' standardization incentives, creating niches for heritage processors and carbon-certified specialists.
For Market Incumbents: Compound geographic coverage advantages by securing long-term Nordic barley genetics contracts before carbon border adjustments tighten sourcing. Acquire floor-malting operations in Suffolk and Bamberg to capture retiring specialist expertise. Vertical integration into precision agriculture advisory services locks in grower loyalty against emerging sustainability-focused competitors. For New Entrants and Emerging Players: Carbon accounting and Scope 3 disclosure services for small brewers represent the most penetrable service-layer gap, as incumbents under-serve this documentation burden. Target India's Mumbai and Bangalore microbrewery clusters with direct-import specialty crystal and roasted malt portfolios. Partner with European organic certification bodies to accelerate market access. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward early-certified maltsters with documented supply chain emissions. Five-to-ten-year viability favors integrated extract manufacturers with pharmaceutical-grade certification over pure-play commodity maltsters. Watch for consolidation signals when REACH compliance costs force cooperative laboratory sharing into formal merger discussions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Genetics | Nordic barley strain control secures high-enzyme diastatic malt positioning for Kentucky and Scottish distillers. |
| Carbon Certification Program | EU Green Deal compliance documentation opens contract renewals with multinational brewers facing Scope 3 mandates. |
| Specialty Extract Manufacturing Scale-Up | Pharmaceutical-grade maltodextrin capacity captures Swiss and German nutraceutical formulator demand. |
| Precision Kilning Technology Deployment | Real-time moisture sensing systems enable heritage variety micro-lot production for Japanese whisky distillers. |
| Direct Farm Contracting Network | Named-field provenance traceability supports United Kingdom cask ale packaging storytelling and pricing power. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with malting plant managers, craft brewer procurement leads, distillery technical directors, and agricultural barley cooperative representatives; and secondary validation through customs trade databases, EU ETS carbon registry filings, FDA food safety guidance documents, and SEC filings of integrated malt extract manufacturers. Bottom-up volume modeling from individual malting facility capacities triangulated against top-down demand estimates from brewing and distilling production statistics.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application intensity, end-user documentation requirements, and regional regulatory cluster. CAGRs derived from segment-level growth rate differentials weighted by base-year value shares. Key inputs included nitrogen fertilizer price indices, craft brewery formation rates in Germany and the United States, and pharmaceutical excipient sourcing regionalization patterns.
Forecasts assume regulatory continuity in EU Green Deal implementation and REACH authorization timelines; material policy shifts in carbon border adjustment scope or glyphosate residue thresholds would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Modified Flour Market
Ingredients
Liquid Feed Market
Ingredients
Plant-Based API Market
Ingredients
Chicory Root Fiber Market
Ingredients
Maracuja Oil Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Mirepoix Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Omega 9 Market
Ingredients
Energy Ingredients Market
Ingredients
Rooster Comb Extract Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Cocoa Processing Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Bleached Flour Market