
 Specialty Malt Market | 2026-2036
Specialty Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Malt Market Intelligence
Craft distilleries is broadening the addressable base for specialty malt beyond traditional beer applications. Simpsons Malt leverages its heritage kilning expertise to serve premium whiskey producers in Scotland and Ireland. Muntons sustains R&D intensity around low-color, high-enzyme malts for adjunct brewing. Briess Malt & Ingredients Company anchors North American supply through its Wisconsin malting campus and direct farm partnerships.
Specialty malt denotes barley or other cereal grains subjected to controlled germination, kilning, or roasting to develop specific color, enzyme, flavor, and aroma profiles for food and beverage manufacturing. The process requires precise moisture management, temperature profiling, and diastatic power calibration to achieve target specifications ranging from pale base malts to highly roasted chocolate malts exceeding 500 EBC color units. Caramel malt occupies the largest margin pool as brewers pay premiums for consistent Maillard reaction products that deliver body and sweetness without adjunct sugars. Roasted malt categories show the fastest volume trajectory as dark beer styles and stout-inspired distillations gain traction across craft segments. Chocolate malt remains a mature niche with stable demand from seasonal brewing cycles and confectionery applications.
REACH and the EU Green Deal shape European malting through carbon accounting requirements and energy efficiency mandates for thermal processing stages. The EPA and OSHA frameworks in the United States govern dust exposure limits and emissions from roasting operations, raising compliance costs for smaller kilning facilities. Stakeholders must monitor how evolving sustainability disclosure rules affect raw barley sourcing premiums and customer procurement criteria across brewery and distillery supply chains.
Market Dynamics
EU Green Deal carbon accounting requirements and the F-Gas Regulation are compressing thermal processing margins across European malting operations, forcing capital reallocation toward heat recovery systems and electrified kilning infrastructure.
Growth Catalysts
- Craft Distillery Expansion:Premium whiskey producers in Scotland and Ireland are diversifying supplier relationships beyond traditional Scotch malt sources, creating new volume channels for specialty kilners.
- REACH Compliance Premiums:European brewers are paying sourcing premiums for malts with verified supply chain carbon disclosures, rewarding early adopters of kilning energy audits.
- Roasted Malt Process Intensification:Advances in drum roasting temperature profiling enable consistent chocolate and black malt outputs at scales previously restricted to batch craft production.
Market Restraints
- Barley Input Volatility:Malting-grade barley availability fluctuates with protein specifications and harvest quality, compressing margin predictability for specialty color malt production.
- Single-Region Kilning Concentration:Heritage roasting expertise concentrates in Belgium and Scotland, creating supply vulnerability for dark malt categories during energy price spikes.
- Diastatic Power Trade-offs:High-roast malts above 400 EBC inherently sacrifice enzymatic activity, limiting formulation flexibility for all-malt breweries seeking color without adjunct brewing.
Strategic Opportunities
- US Craft Adjunct Brewing:Low-color, high-enzyme specialty malts enable American brewers to experiment with alternative grains while maintaining fermentable sugar yields.
- Confectionery Colorant Substitution:Clean-label chocolate malt extracts are displacing synthetic caramel colorants in premium baked goods and ice cream formulations.
- EPA Emissions Incentives:US roasting facilities capturing volatile organic compounds through thermal oxidizer upgrades qualify for accelerated depreciation under IRA clean manufacturing provisions.
Industry Challenges
- Kilning Operator Scarcity:The specialized craft of moisture curve management and Maillard reaction timing lacks formal training pipelines, constraining facility expansion timelines.
- Legacy Equipment Integration:Victorian-era floor malting heritage sites face mechanical incompatibility with automated carbon monitoring systems required for EU sustainability disclosures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Malt Market |
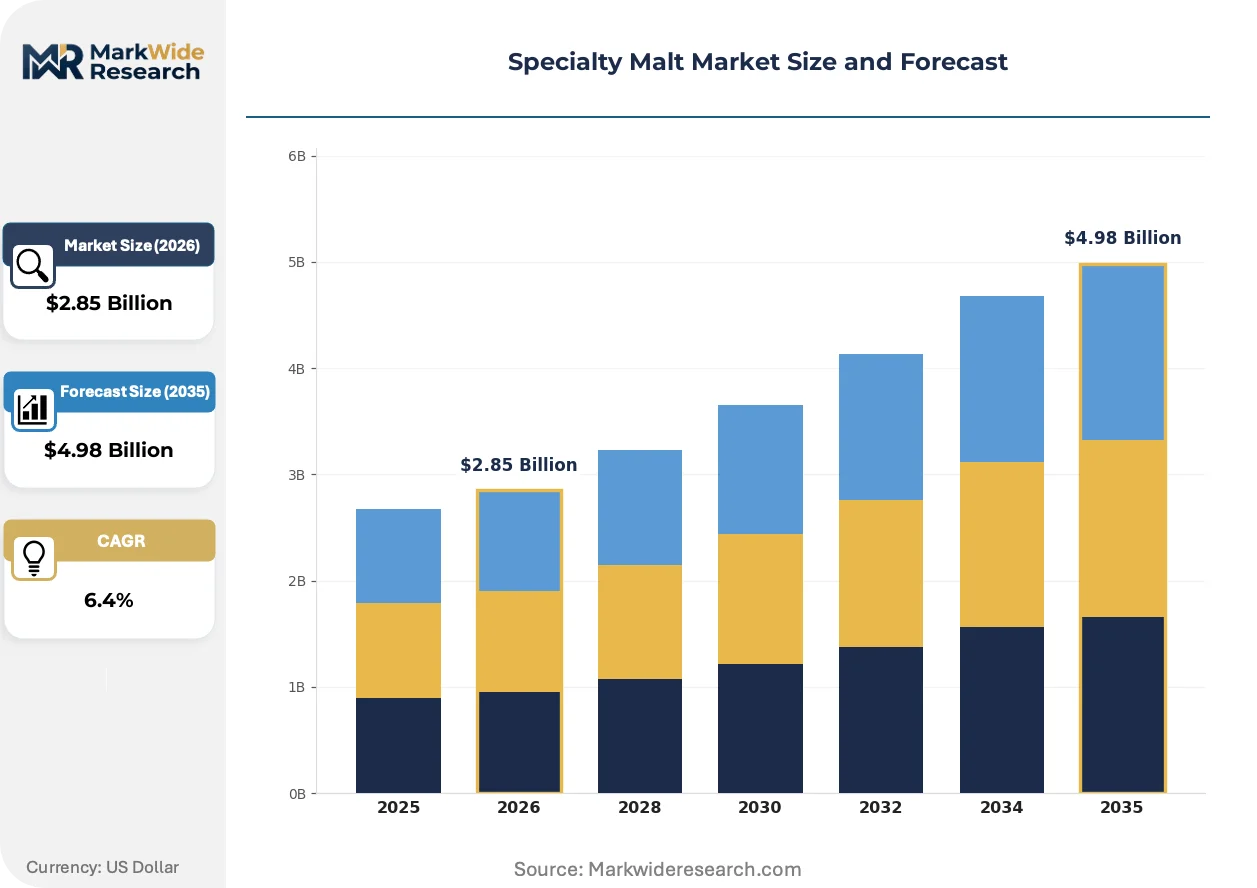
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pale Malt, Caramel Malt, Roasted Malt, Chocolate Malt End Use: Breweries, Distilleries, Food Manufacturers, Homebrewers Grade: Organic, Conventional, Premium, Standard Application: Beer Production, Whiskey Production, Baking, Confectionery |
| Companies Covered | Malteurop Groupe, Boortmalt, Simpsons Malt, Viking Malt, Soufflet Group, Muntons, Cargill Malt, Briess Malt & Ingredients Company, Crisp Malting Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Malt Market Strategic Shifts & Innovations
Precision kilning control systems and alternative grain malting are restructuring how specialty malt specifications are developed, tested, and scaled across brewing and distilling applications.
Sensor-integrated kilning platforms are automating moisture extraction curves through real-time airflow modulation and temperature gradient feedback loops. Mid-size craft malting operations in Germany and the United States are retrofitting these systems to reduce batch-to-batch color variation. The technology is automating quality control labor while compressing the time required to achieve target EBC specifications.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based refrigeration in malt storage and germination control systems. Malting groups operating across Belgium and the Netherlands are transitioning to ammonia-based or transcritical CO2 cooling infrastructure. Dark malt roasting facilities face the steepest retrofit timelines given their reliance on precise humidity management during extended kilning cycles.
Direct farm contracting is displacing spot barley purchasing among premium specialty malt producers. Breweries in Denmark and the Czech Republic are specifying heritage barley varieties with traceable provenance for seasonal releases. This procurement pattern concentrates most visibly in countries with protected geographical indication frameworks for beer styles.
Specialty Malt Market Segmentation
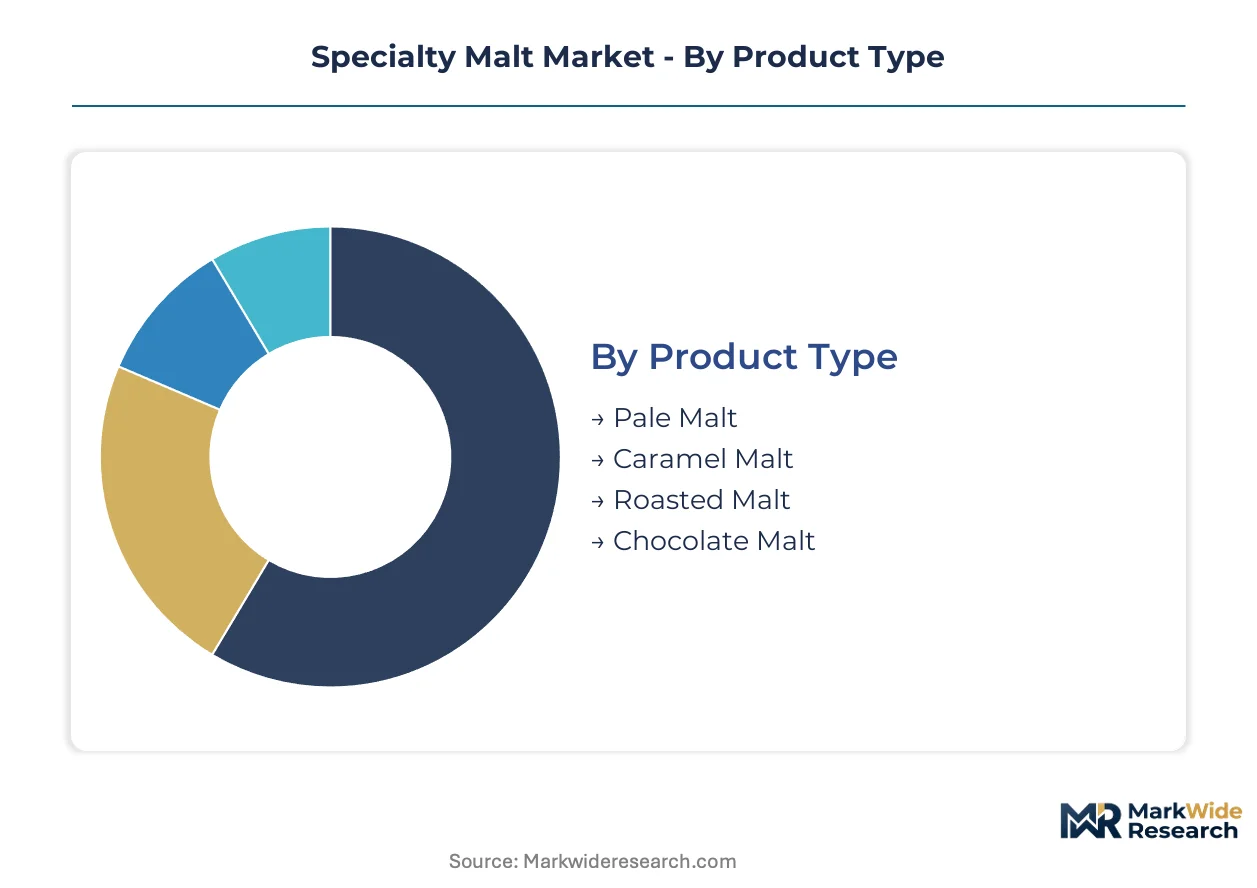
Specialty malt segmentation reveals how kilning intensity and end-use specifications fragment manufacturing capabilities across distinct equipment profiles and operator skill requirements. Each dimension carries implications for margin structure, regulatory exposure, and capital allocation priorities.
Product Type:
Supply concentration in kilning infrastructure varies sharply across roast intensity levels, with dark malt production clustering in heritage facilities possessing century-old drum roasting expertise.
- Caramel Malt:Maillard reaction products develop through controlled stewing of green malt before final kilning, producing unfermentable sugars that enhance body and foam stability. German and Belgian craft breweries absorb the bulk of premium caramel malt output, driven by seasonal bock and dubbel production cycles.
- Roasted Malt:Drum roasting at temperatures exceeding 200°C generates intense color and bitter chocolate notes for stouts and porters. Scottish and Irish distilleries are expanding procurement of roasted specialty malts for premium whiskey finishing programs, creating new volume channels beyond traditional beer applications.
- Pale Malt:Low-color base malts with minimal kilning modification serve as enzymatic foundations for adjunct brewing formulations.
- Chocolate Malt:Highly roasted variants exceeding 400 EBC color units deliver concentrated flavor for seasonal brewing and confectionery colorant substitution.
Caramel malt absorbs the bulk of installed capacity; roasted malt is expanding most quickly.
End Use:
Customer type determines specification stringency, with commercial breweries demanding batch-to-batch color consistency that homebrew channels rarely enforce.
- Breweries:Commercial brewing operations specify tight EBC tolerances and diastatic power certificates for recipe reproducibility at scale. Craft breweries in Denmark and the Czech Republic are driving heritage barley variety procurement through direct farm contracting for traceable seasonal releases.
- Distilleries:Whiskey producers prioritize fermentable extract yields and low nitrogen content to maximize alcohol conversion efficiency. Premium Scotch and Irish whiskey distillers are diversifying beyond traditional malt suppliers, creating qualification opportunities for specialty kilners with proven roasting consistency.
- Food Manufacturers:Clean-label chocolate malt extracts displace synthetic caramel colorants in premium baked goods and ice cream formulations.
- Homebrewers:Small-batch enthusiasts purchase pre-packaged specialty malts through retail channels with relaxed specification requirements.
Breweries command the dominant share of volume; distilleries are climbing the fastest as whiskey capacity expands.
Grade:
Certification tier separates pricing bands through input cost differentials and audit burden rather than functional performance alone.
- Organic:Barley cultivation without synthetic pesticides or fertilizers, verified through third-party certification bodies. EU Green Deal carbon accounting requirements are compressing margins for organic malting operations due to extended supply chain documentation obligations.
- Premium:Heritage barley varieties with traceable provenance and extended germination periods for enhanced enzyme development. Belgian and German brewers pay sourcing premiums for premium grades with verified kilning energy disclosures under REACH compliance frameworks.
- Conventional:Standard agricultural inputs with conventional pest management and nitrogen fertilization protocols.
- Standard:Commodity-grade malts meeting basic analytical specifications without provenance guarantees or extended modification.
Conventional grade dominates production volume; organic is gaining share fastest on clean-label demand.
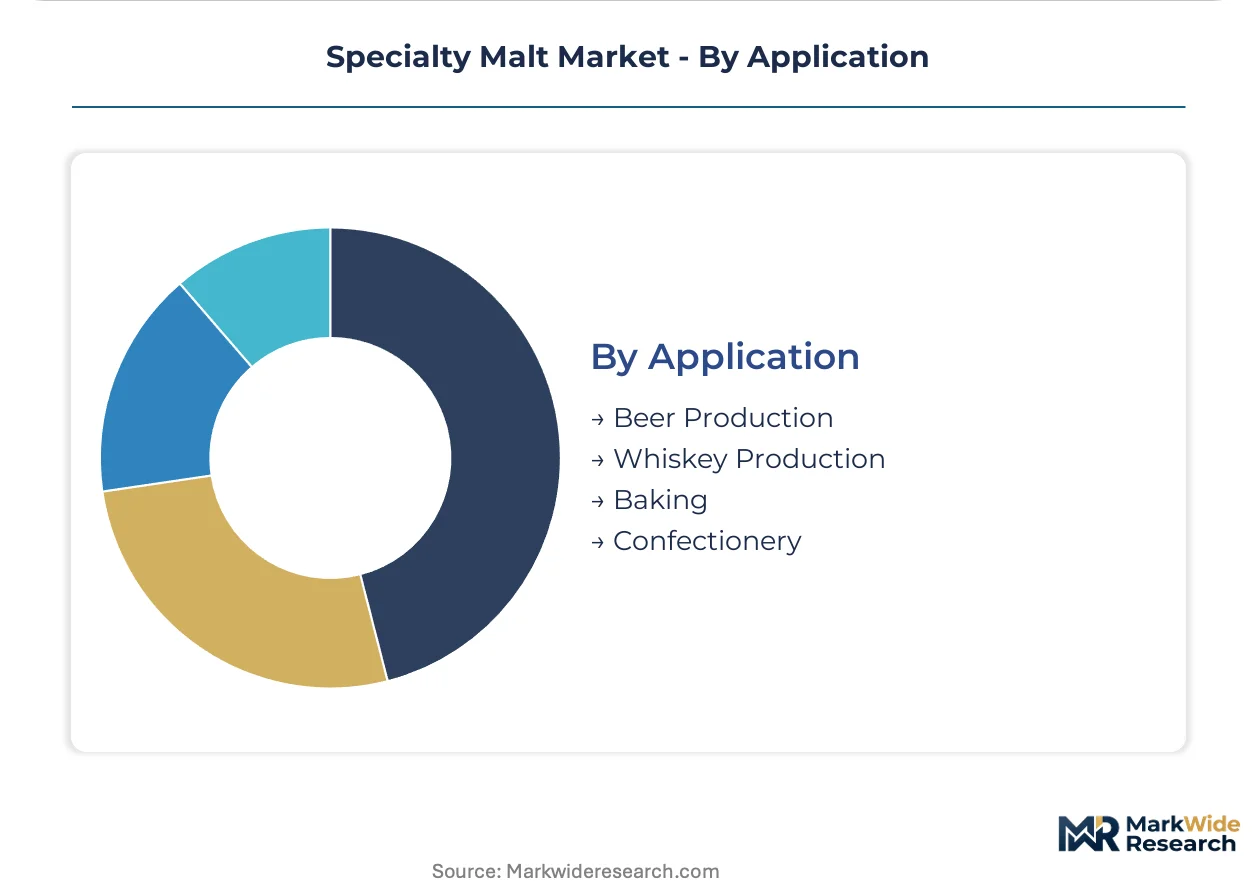
Application:
End-use formulation requirements dictate diastatic power thresholds and color contribution limits that kilning protocols must calibrate precisely.
- Beer Production:All-malt and adjunct brewing formulations require precise enzyme activity balance between base and specialty additions. American craft brewers are experimenting with low-color, high-enzyme specialty malts to maintain fermentable sugar yields while incorporating alternative grains.
- Whiskey Production:Distilling malts prioritize maximum extract yield with minimal husk content to prevent lautering problems in mash tuns. Scottish distilleries anchor demand for lightly peated specialty malts with specific phenol specifications for regional style compliance.
- Baking:Malt extracts and diastatic malt powders enhance fermentation and crust color in artisan bread production.
- Confectionery:Chocolate malt powders provide natural coloring and mild roasted flavor notes for premium candy and dessert applications.
Beer production retains the largest capacity allocation; whiskey production shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty malt production concentrates in heritage kilning regions while consumption spreads across craft brewing and distilling clusters. Germany and Belgium anchor European supply through century-old roasting expertise. The United States and United Kingdom absorb premium volumes through expanding craft segments.
Germany
Bavarian craft breweries drive caramel malt consumption for seasonal bock and weizenbock production cycles. The EU Green Deal carbon accounting requirements compress margins for malting operations in Lower Saxony and North Rhine-Westphalia. Munich-area kilning facilities are retrofitting heat recovery systems to meet F-Gas Regulation phase-down timelines for hydrofluorocarbon refrigeration.
Belgium
Heritage abbey and Trappist brewing traditions sustain demand for premium roasted malt varieties in Flanders and Wallonia. REACH compliance frameworks reward malters with verified supply chain energy disclosures through brewery procurement premiums. Drum roasting expertise concentrates in Pajottenland and the Scheldt Valley, where Victorian-era floor malting sites face automation challenges.
United States
Wisconsin and Colorado craft brewing clusters absorb North American specialty malt output through direct farm contracting arrangements. EPA emissions frameworks govern dust exposure limits and thermal oxidizer requirements for roasting operations. The Wisconsin malting campus anchors regional supply through heritage barley variety programs and adjunct brewing formulation partnerships.
United Kingdom
Scottish and Irish whiskey distilleries diversify supplier relationships beyond traditional malt sources, creating qualification opportunities for English specialty kilners. The UK's departure from EU regulatory alignment complicates carbon disclosure verification for cross-border brewery contracts. Norfolk and Suffolk malting barley regions supply heritage varieties to London craft brewing operations seeking traceable provenance.
Denmark
Copenhagen-area craft breweries specify heritage barley varieties with protected geographical indication frameworks for seasonal releases. National sustainability disclosure rules align with EU Green Deal carbon accounting requirements for thermal processing stages. Sealand and Funen malting operations are transitioning to ammonia-based cooling infrastructure under F-Gas Regulation compliance timelines.
Specialty Malt Market Key Industry Players
Top-tier vendors anchor heritage kilning expertise, while mid-scale craft malters compete on direct farm contracting and specialty roasting consistency. The vendor base stratifies across integrated agricultural conglomerates, regional kilning specialists, and ingredient-focused formulators. Three archetypes dominate: heritage floor malting operations with century-old drum roasting capabilities, large-scale agricultural processors with integrated barley supply chains, and ingredient technology firms developing enzyme-optimized specialty grades. Competitive moves center on capacity expansion in low-color high-enzyme segments and strategic partnerships with craft distillery qualification programs.
Within the heritage specialist tier, Simpsons Malt and Muntons exemplify contrasting geographic and technical positioning. Simpsons Malt represents Scottish kilning expertise serving premium whiskey producers through heritage roasting consistency. Muntons occupies a position within English malting tradition, anchoring R&D intensity around formulation-grade specialty products. Briess Malt & Ingredients Company sits within the North American ingredient technology archetype, exemplifying direct farm partnership models and campus-based supply consolidation. Cargill Malt and Malteurop Groupe represent agricultural integration archetypes with captive barley sourcing and continental European production scale.
| Leading Market Players |
|---|
| Malteurop Groupe |
| Boortmalt |
| Simpsons Malt |
| Viking Malt |
| Soufflet Group |
| Muntons |
| Cargill Malt |
| Briess Malt & Ingredients Company |
| Crisp Malting Group |
| Others |
Cost & Logistics Intelligence
Captive barley sourcing through direct farm contracting anchors supply position and pricing power for heritage malting groups in Germany and Belgium. This integration pattern compresses input cost volatility while enabling provenance premiums that spot-market dependent competitors cannot match under EU Green Deal carbon accounting requirements.
Pricing Analysis
Short lead-time premiums dominate specialty malt pricing as craft breweries in Denmark and the Czech Republic pay surcharges for heritage barley varieties with traceable seasonal release timelines. Three-tier pricing structure across premium, standard, and economy levels separates certified organic grades with full supply chain documentation from conventional commodity malts. Cost compression in caramel malt categories is intensifying because drum roasting capacity concentrates in Victorian-era Belgian facilities with limited automation retrofit feasibility. Commercial breweries exhibit lowest price sensitivity due to recipe lock-in requirements, while homebrew channels absorb economy-tier spot inventory with minimal specification enforcement.
Supply Chain Analysis
REACH compliance certification gates supplier qualification for European brewery procurement contracts, forcing documentation investments that smaller kilning operations cannot sustain. Supply concentrates in Belgium, Scotland, and Germany where heritage drum roasting expertise resides. Raw material flows draw from malting-grade barley regions in Lower Saxony, Norfolk, and Pajottenland with protein specifications tightening harvest-to-harvest. Single-source vulnerability runs through concentrated dark malt roasting capacity in Flanders and the Scheldt Valley during energy price spikes. Distribution runs through direct mill-to-brewery contracts for premium grades alongside merchant channels for standard-tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty malt markets are consolidating as EU F-Gas Regulation compliance costs force sub-scale kilning facilities into distressed exit scenarios. Carbon disclosure mandates and refrigeration retrofit timelines compress margins for operators lacking captive barley supply or heat recovery infrastructure.
For Market Incumbents: Hedge margin exposure by deepening backward integration into heritage barley variety programs in Bavaria and Lower Saxony. Prioritize heat recovery system deployment ahead of F-Gas Regulation phase-down deadlines to capture REACH compliance premiums from Danish and Belgian brewery procurement officers. Defensive capacity positioning in low-color high-enzyme segments protects against adjunct brewing formulation shifts in North American craft segments. For New Entrants and Emerging Players: IRA clean manufacturing provisions in the United States open a window for thermal oxidizer-equipped roasting facilities serving Wisconsin and Colorado craft brewing clusters. Target whiskey distillery qualification programs in Scotland and Ireland where supplier diversification creates white-space for proven roasting consistency. Lead with direct farm contracting narratives that mirror heritage malting group procurement models without century-old infrastructure burdens. For Investors and Strategic Acquirers: Exit pathways concentrate in agricultural conglomerates seeking kilning expertise for beverage ingredient platform expansion. Five-to-ten year viability favors operators with ammonia-based cooling infrastructure already deployed under F-Gas Regulation compliance timelines. Watch ammonia refrigeration retrofit completion rates across Belgian and Dutch malting groups as inflection indicator for competitive cost structure separation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery System Deployment | EU Green Deal carbon accounting requirements reward early adopters with brewery procurement premiums. |
| Ammonia-Based Cooling Transition | F-Gas Regulation phase-down timelines force infrastructure decisions that separate compliant from stranded assets. |
| Direct Farm Contracting Expansion | Heritage barley variety programs in Denmark and the Czech Republic enable traceable seasonal release positioning. |
| Whiskey Distillery Qualification | Scottish and Irish premium producers diversify beyond traditional malt sources for finishing program consistency. |
| Thermal Oxidizer Upgrade Capture | IRA clean manufacturing provisions accelerate depreciation for EPA-compliant roasting facility investments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this specialty malt market analysis. Primary interviews with malting plant managers, brewery procurement leads, distillery sourcing directors, and barley cooperative representatives combined with ECHA REACH submissions, EU F-Gas Regulation compliance databases, and SEC 10-K filings for agricultural conglomerates. Bottom-up volume triangulation across kilning capacity utilization rates and top-down value reconciliation through brewery and distillery procurement expenditure patterns validated segment outputs.
Granularity-level modeling disaggregated volume and value across product type, end use, grade certification, and application dimensions throughout the forecast period. Caramel, roasted, pale, and chocolate malt categories were modeled separately with EBC color specification thresholds. CAGRs were derived from regression analysis against craft brewery and distillery capacity expansion indicators. Kilning energy cost trajectories under EU Green Deal carbon pricing assumptions and ammonia refrigeration adoption curves informed margin compression scenarios.
The model assumes a particular technology adoption path for electrified kilning infrastructure; alternative pathways for heat pump-based thermal processing would alter the outlook for fossil fuel-dependent heritage facilities. Forecasts reflect assumptions about REACH compliance enforcement consistency and F-Gas Regulation phase-down adherence timelines. A model refresh is warranted upon material change in EU carbon border adjustment mechanism coverage for imported malt or sudden barley harvest quality deterioration in major malting-grade production regions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
PHO Oils Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Food Colors Market
Ingredients
United States Avocado Oil Market
Ingredients
Grape Seed Extracts Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Sea Salt Market
Ingredients
US Choline Bitartrate Market
Ingredients
Glucosylglycerol Market
Ingredients
Cocoa Butter Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Ximenia Oil Market
Ingredients
North America Plant Protein Ingredients Market