
 Bean Ingredients Market | 2026-2036
Bean Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Bean Ingredients Market Analysis
Soy protein isolate is rebalancing toward navy bean and fava bean concentrates as formulators seek cleaner-label alternatives with comparable emulsification. Cargill Incorporated leverages its North American oilseed infrastructure to anchor bean protein extraction at scale. Olam International competes through integrated origination networks spanning African and Latin American bean belts. Archer Daniels Midland Company specializes in fractionation technology that isolates functional proteins for meat alternative applications.
Bean ingredients comprise processed legume derivatives—whole, milled, or extracted—that deliver protein, fiber, and starch functionality to formulated foods, with protein content typically ranging from 20% to 40% depending on species and processing intensity. Primary commercial purpose centers on partial or complete replacement of animal-derived and cereal-based proteins in human and pet nutrition systems. Dried beans and bean flours currently occupy the largest value share within product type categories, reflecting established supply chains and shelf-stable logistics. Bean snacks represent the fastest-growing product type as CPG brands target protein-forward portable nutrition. Food manufacturers dominate end-user demand, though restaurants are gaining share through bean-based menu innovation.
The USDA's dietary guidelines and FDA nutrition labeling requirements collectively elevate bean ingredients in reformulation decisions, while the EPA's biofuel mandates indirectly tighten competing oilseed availability. Brazil's ANVISA and the EU's EFSA both enforce pesticide residue thresholds that shape which bean varieties enter ingredient supply chains. Stakeholders must monitor how carbon accounting standards and deforestation-linked sourcing regulations redefine competitive access to premium bean protein markets.
Market Dynamics
The FDA's updated dietary guidelines emphasizing legume consumption are forcing food manufacturers to reformulate protein sources, redirecting procurement toward bean-derived ingredients and away from soy isolates.
Growth Catalysts
- Plant-based meat analogs:Food manufacturers are reformulating with navy bean and fava bean concentrates to achieve cleaner-label positioning while maintaining emulsification performance comparable to legacy soy systems.
- USDA dietary guidelines:Federal nutrition recommendations elevate beans as core protein alternatives, embedding legume consumption targets into institutional foodservice procurement specifications.
- Brazil processing capacity:Domestic bean processing infrastructure and export-oriented ingredient production continue scaling, anchoring supply security for North American and European formulators.
Market Restraints
- Input cost volatility:Drought cycles in the Black Sea region and Argentine bean belts create price instability for fava and lupin feedstocks entering protein extraction.
- Supply concentration risk:Premium bean protein fractionation capacity clusters among a limited set of North American oilseed processors, creating bottleneck vulnerability.
- Pesticide residue thresholds:Brazil's ANVISA and the EU's EFSA enforce divergent maximum residue limits that exclude certain bean varieties from cross-border ingredient trade.
Strategic Opportunities
- Pet nutrition expansion:Bean protein concentrates are penetrating premium pet food formulations as brands seek novel protein sources to differentiate in the humanization trend.
- Carbon accounting standards:Emerging Scope 3 disclosure requirements favor bean ingredients with verified low-carbon origination, creating premium market segmentation.
- Bean snacks channel:CPG brands are building direct-to-consumer protein-forward portable nutrition lines that bypass conventional retail slotting constraints.
Industry Challenges
- Fractionation talent scarcity:The specialized protein isolation and functionalization expertise required for meat analog applications outpaces current technical training pipeline output.
- Legacy system integration:Food manufacturers face reformulation complexity when substituting bean proteins into existing production lines optimized for soy or wheat gluten functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bean Ingredients Market |
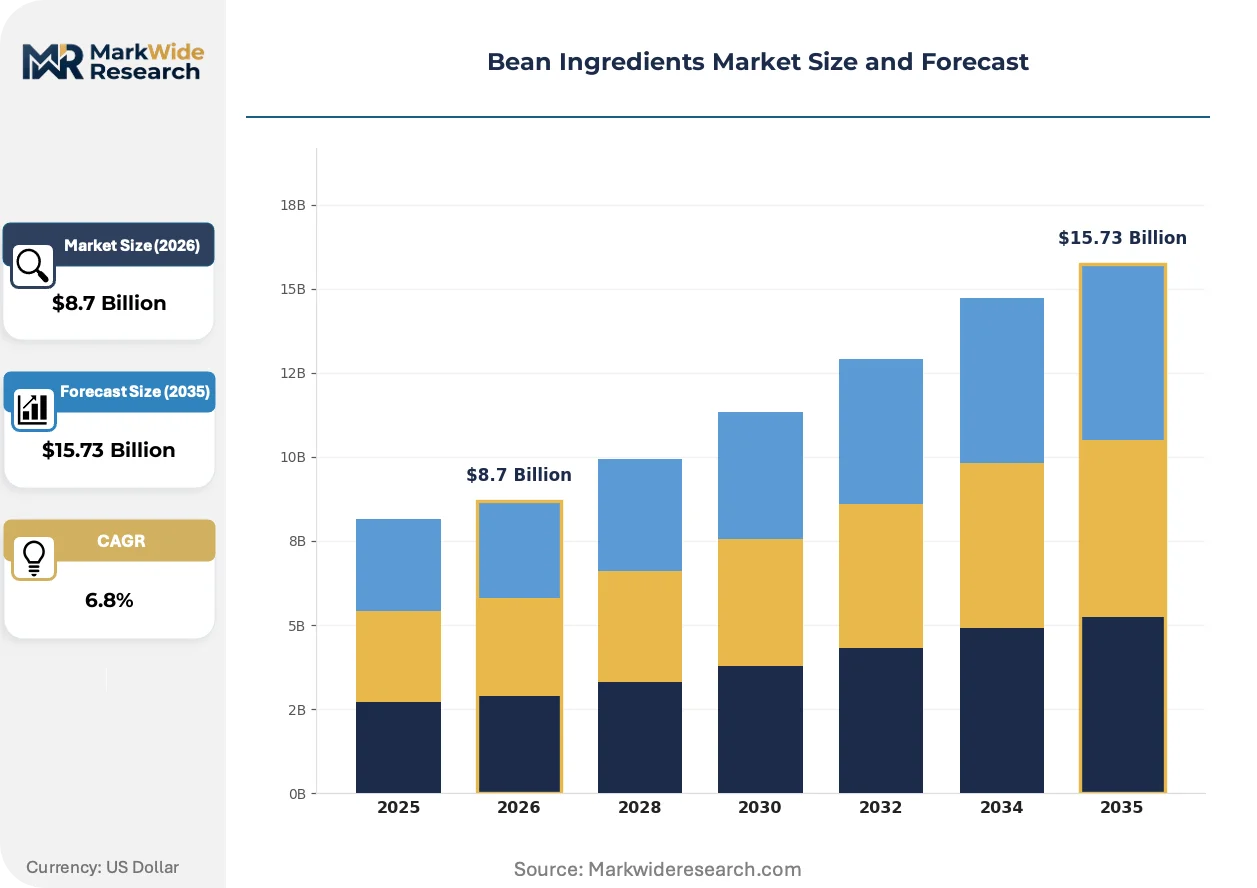
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Beans, Canned Beans, Bean Flours, Bean Snacks Application: Food Products, Beverages, Nutritional Supplements, Animal Feed End User: Food Manufacturers, Restaurants, Retailers, Households Form: Whole Beans, Split Beans, Powdered Beans, Extracts |
| Companies Covered | Cargill Incorporated, Olam International, Archer Daniels Midland Company, MARA Global Foods, Faribault Foods, Inc., Globeways Canada, Inc., The Organic Collective Limited, BETTER BEAN COMPANY, Vermont Bean Crafters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bean Ingredients Market Emerging Trajectories
Formulation science and regulatory disclosure requirements are converging to reshape ingredient selection criteria, with functionality, provenance transparency, and carbon intensity now jointly determining procurement decisions.
Dry-fractionation technology is overtaking wet-extraction methods for bean protein concentration. Food technologists at meat alternative manufacturers are adopting air-classification systems that preserve native protein functionality while eliminating water-intensive processing steps. This shift is compressing capital requirements for mid-scale ingredient producers and enabling regional sourcing models that reduce transportation emissions.
The EU's Corporate Sustainability Reporting Directive is mandating supply chain disclosure for large food manufacturers. CSRD compliance is forcing ingredient suppliers to document deforestation-free origination and embedded carbon metrics. Bean protein processors with verified traceability systems are capturing preferential contracting positions with European formulators facing 2026 disclosure deadlines.
Buyer concentration among contract food manufacturers is consolidating procurement leverage. Large co-manufacturers serving multiple CPG brands are standardizing bean protein specifications across client portfolios, displacing brand-specific custom formulations. This pattern is most visible in Brazil, where domestic processing giants are negotiating multi-year supply agreements that lock in volume commitments and price bands.
Bean Ingredients Market Segmentation
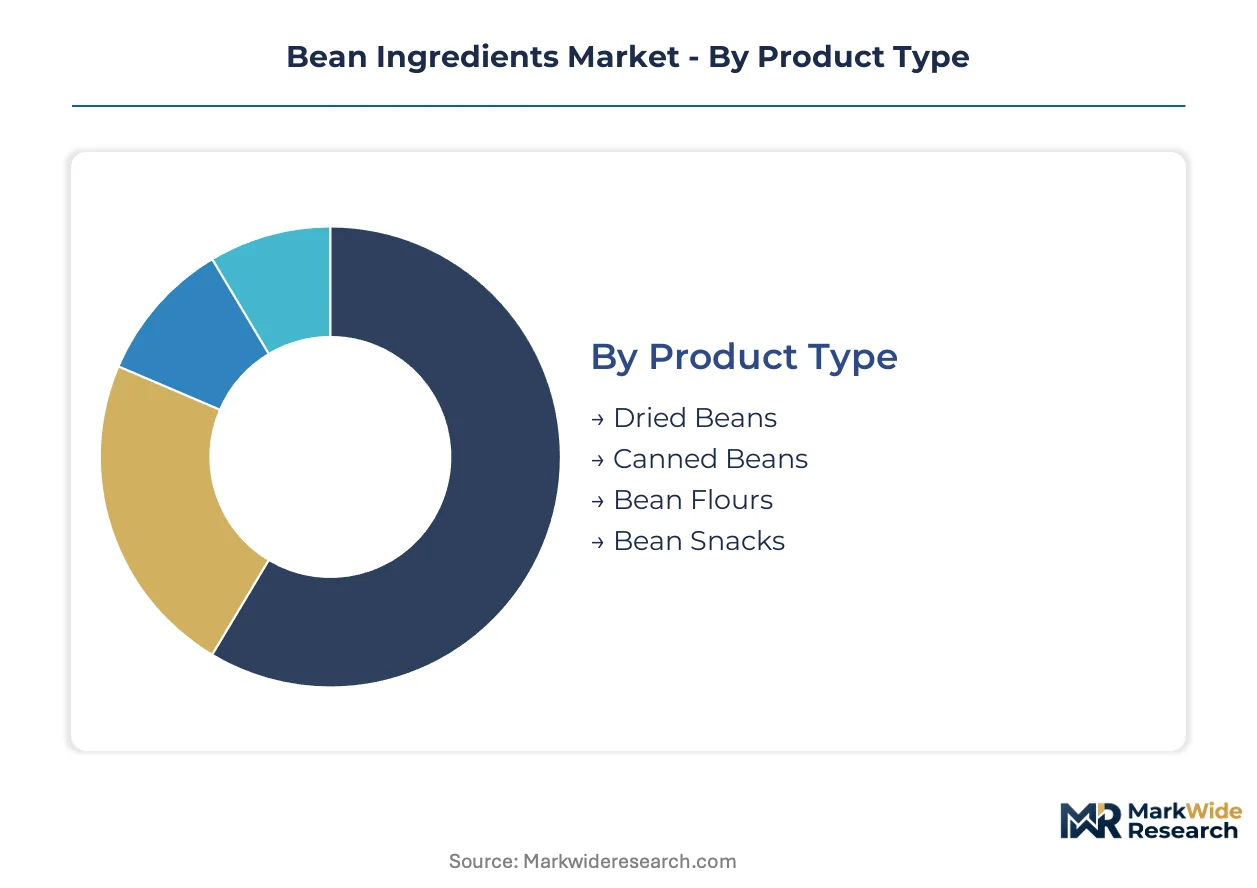
Bean ingredient procurement varies sharply by segment, with food manufacturers demanding certified protein specifications while retail channels prioritize shelf-stable logistics. Understanding these divergent requirements illuminates where formulation complexity concentrates and where margin compression threatens.
Product Type:
FDA nutrition labeling and shelf-life certification burdens fall heaviest on bean snacks and canned beans, while dried beans and flours navigate simpler GRAS self-affirmation pathways.
- Dried Beans:Whole or split legumes dehydrated to 10-14% moisture content for extended ambient storage. Demand concentrates in Brazilian export corridors and North American foodservice distribution, where USDA procurement specifications for institutional feeding drive volume. ANVISA phytosanitary certificates govern cross-border movement into processing facilities.
- Bean Flours:Milled legume products ranging from coarse meal to fine powder with protein content typically between 20-30%. Food manufacturers in the plant-based meat sector are reformulating with navy bean and fava bean varieties to achieve cleaner-label positioning while maintaining emulsification performance.
- Canned Beans:Thermally processed legumes in brine or sauce with commercial sterility validation. Retailers and restaurants dominate procurement, with EFSA additive regulations shaping which preservative systems enter European supply chains.
- Bean Snacks:Roasted, puffed, or extruded legume products targeting portable protein consumption. CPG brands are building direct-to-consumer lines that bypass conventional retail slotting constraints, expanding most quickly among all product types.
Leading the category by volume: Dried Beans. Growing fastest: Bean Snacks.
Application:
Cost tiers stratify sharply, with nutritional supplements commanding premium extraction-grade specifications while animal feed absorbs lower-protein byproduct streams.
- Food Products:Formulated goods including meat alternatives, baked items, and pasta where bean proteins replace wheat gluten or soy isolates. Wet-extraction and dry-fractionation methods compete for share in this application.
- Beverages:Protein-fortified drinks and dairy alternatives utilizing bean protein isolates with solubility specifications above 80%. EPA water discharge regulations elevate processing costs for wet-extraction facilities supplying this segment.
- Nutritional Supplements:High-purity protein concentrates and isolates for sports nutrition and clinical feeding. EFSA health claim substantiation requirements create entry barriers for novel bean protein sources.
- Animal Feed:Dehulled or processed legume meals for pet food and livestock rations. Premium pet food brands are penetrating this segment as they seek novel protein sources to differentiate in the humanization trend.
Highest margin capture: Nutritional Supplements. Steepest volume expansion: Food Products.
End User:
Customer concentration patterns determine contract structures, with food manufacturers consolidating procurement leverage while households remain price-sensitive and fragmented.
- Food Manufacturers:Industrial formulators of packaged goods and ingredients for further processing. Large co-manufacturers serving multiple CPG brands are standardizing bean protein specifications across client portfolios.
- Restaurants:Foodservice operators incorporating bean-based menu items for protein-forward positioning. Menu innovation is gaining share through bean-based formulations in casual dining and fast-casual channels.
- Retailers:Supermarkets and specialty grocers sourcing private-label bean ingredients and finished goods. Slotting fee structures disadvantage smaller bean snack entrants against established brands.
- Households:Direct consumer purchasers of dried, canned, or minimally processed beans for home preparation. Price elasticity remains acute in this segment amid inflationary pressure on staple proteins.
Dominant procurement volume: Food Manufacturers. Fastest contract growth: Restaurants.
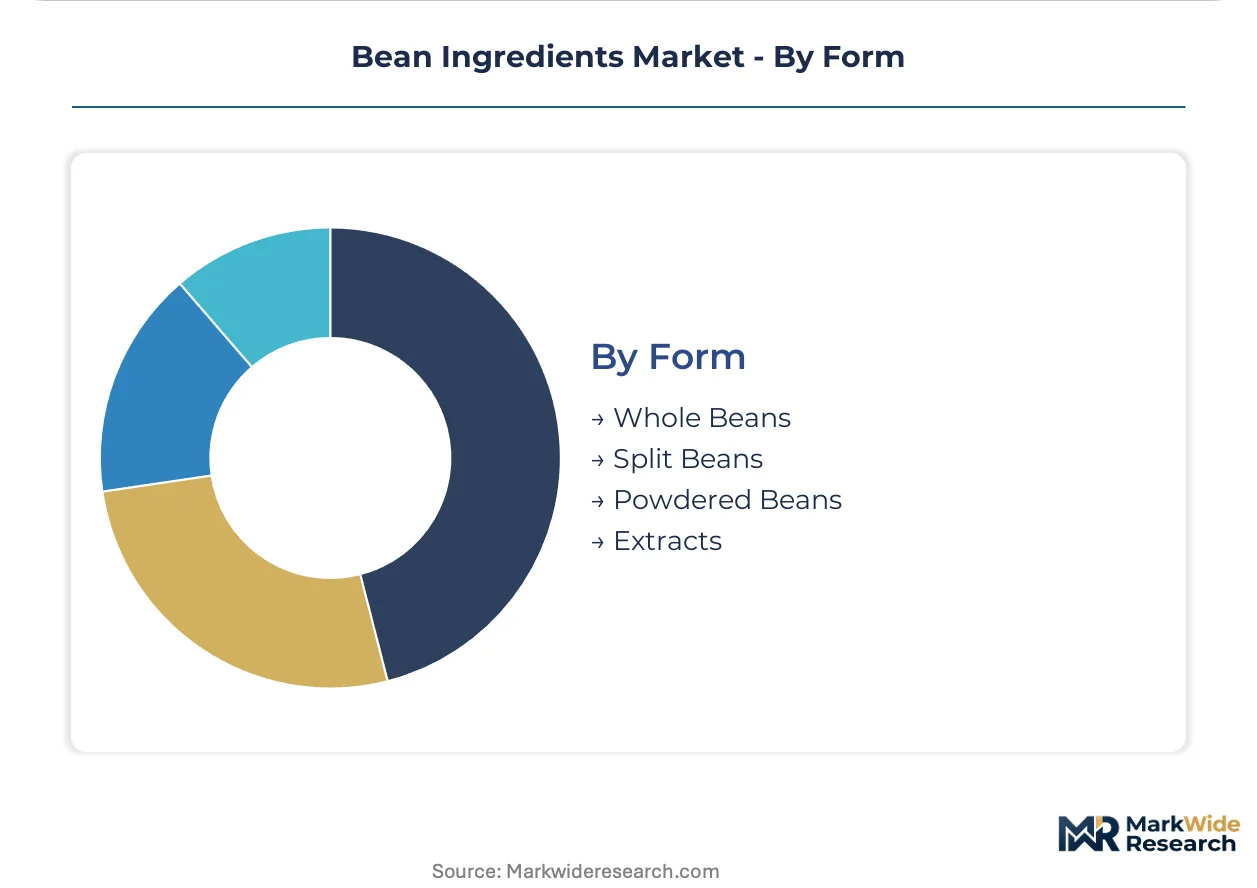
Form:
Supply concentration clusters around whole bean processing, with extraction capacity for isolates and concentrates bottlenecked among specialized fractionation facilities.
- Whole Beans:Intact legumes requiring hydration and cooking prior to consumption or further processing. Brazil's domestic processing infrastructure anchors supply security for North American and European formulators.
- Split Beans:Dehulled and divided legumes with reduced cooking time and altered texture profiles. South Asian and Middle Eastern cuisines drive specialized demand for specific split varieties.
- Powdered Beans:Fine-milled products with particle size distributions tailored to reconstitution behavior. Dry-fractionation technology is overtaking wet-extraction methods for protein concentration in this form.
- Extracts:Protein isolates, starches, and fiber fractions separated through aqueous or mechanical processing. Fractionation talent scarcity constrains capacity expansion for meat analog applications.
Volume leadership: Whole Beans. Gaining share fastest: Extracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bean ingredients concentrates most visibly in Brazil, where domestic processing capacity and export-oriented ingredient production continue to scale, while North American and European formulators redirect procurement toward navy bean and fava bean concentrates.
Brazil
ANVISA pesticide residue thresholds shape which bean varieties enter ingredient supply chains, while domestic processing giants negotiate multi-year supply agreements. São Paulo anchors the country's bean protein fractionation infrastructure, with export corridors scaling capacity to serve North American meat alternative manufacturers.
United States
USDA dietary guidelines embed legume consumption targets into institutional foodservice procurement specifications, redirecting reformulation decisions. FDA updated nutrition labeling requirements elevate beans as core protein alternatives. Cargill leverages North American oilseed infrastructure to anchor bean protein extraction at scale in Minnesota and Iowa processing clusters.
Germany
EFSA health claim substantiation requirements create entry barriers for novel bean protein sources entering nutritional supplements. The EU's Corporate Sustainability Reporting Directive mandates supply chain disclosure, forcing ingredient suppliers to document deforestation-free origination. Hamburg and Bremen harbor the largest European bean import and fractionation terminals.
India
FSSAI food safety standards govern split bean and flour processing for domestic consumption and Middle East export. The country's central agricultural regulator monitors pesticide maximum residue limits for chickpea and mung bean varieties. Gujarat and Maharashtra concentrate dehulling and milling infrastructure for global pulse ingredient supply.
Canada
Health Canada and PMRA jointly enforce pesticide residue thresholds that determine which bean varieties qualify for cross-border ingredient trade into US processing facilities. Prairie Provinces, particularly Saskatchewan and Manitoba, anchor North American pea and fava bean origination for protein extraction.
Bean Ingredients Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with large co-manufacturers consolidating procurement leverage through standardized specifications while ingredient innovators compete on fractionation technology. The market structure concentrates premium protein fractionation capacity among North American oilseed processors, creating bottleneck vulnerability for meat analog supply chains. Three archetypes dominate: integrated agribusiness conglomerates with origination-to-extraction control, specialized bean protein fractionators with dry-processing capabilities, and regional millers serving foodservice and retail channels. Capacity expansion and backward integration into bean origination networks represent the dominant competitive moves as formulators seek supply security.
Among integrated agribusiness conglomerates, Cargill Incorporated and Archer Daniels Midland Company occupy positions that exemplify scale-driven extraction infrastructure, while Olam International represents the origination-network archetype spanning African and Latin American bean belts. These three entities anchor the competitive landscape through distinct strategic positions—Cargill through North American oilseed infrastructure, Archer Daniels Midland through fractionation technology specialization, and Olam through integrated sourcing networks—without any single player commanding definitive market control.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Olam International |
| Archer Daniels Midland Company |
| MARA Global Foods |
| Faribault Foods, Inc. |
| Globeways Canada, Inc. |
| The Organic Collective Limited |
| BETTER BEAN COMPANY |
| Vermont Bean Crafters |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap millers across the American Midwest and Brazilian interior anchor origination-to-processing control, tightening pricing discipline through captive bean supply while limiting spot-market liquidity for North American meat alternative formulators.
Pricing Analysis
Volume leaders in dried beans and flours trade on thin margins while extraction-grade protein concentrates command premium-mid-economy pricing differentiation based on functional specifications and carbon-verified origination. USDA institutional procurement specifications and EFSA residue thresholds create certification-driven price spreads between commodity and ingredient-grade supply. Cost compression in standard-tier bean flours is intensifying because Brazilian processors are scaling export capacity faster than North American demand absorption. Household direct purchasers exhibit acute price sensitivity, whereas nutritional supplement manufacturers prioritize functional performance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Minnesota, Iowa, and São Paulo protein fractionation clusters are compressing expansion timelines for dry-fractionation facilities serving meat analog applications. Supply concentrates in Brazil, the United States, and Canada, with Prairie Provinces anchoring fava and pea bean origination for cross-border processing. Raw material dependencies rest on pesticide-compliant seed varieties, specialized air-classification equipment, and food-grade packaging films. Single-source vulnerability runs through the limited set of North American oilseed processors with validated fractionation capacity. Distribution runs through co-manufacturer consolidation, with large contract producers standardizing specifications across CPG brand portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry-fractionation technology is displacing water-intensive wet-extraction methods, compressing capital barriers for regional bean protein producers and enabling carbon-accounting advantages that reshape procurement criteria.
For Market Incumbents: Acquire regional origination networks in Saskatchewan and Manitoba to lock in pesticide-compliant fava bean supply before Health Canada tightens cross-border residue thresholds. Invest in air-classification capacity expansion to defend margin position against emerging Brazilian processors scaling export-oriented fractionation infrastructure. For New Entrants and Emerging Players: Launch via direct-to-consumer bean snack channels that bypass conventional retail slotting fees and capture protein-forward portable nutrition demand. Target pet nutrition formulations as the most penetrable application, where novel protein positioning commands premium pricing and formulation flexibility exceeds human food regulatory burden. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized dry-fractionation specialists with validated EU deforestation-free certification in Germany and the Netherlands, as CSRD disclosure deadlines force European formulators toward traceable supply. Monitor ANVISA residue limit harmonization negotiations as the signal indicating when Brazilian-origin bean proteins regain premium market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination Networks | Cargill and ADM are securing pesticide-compliant bean supply in Prairie Provinces to reduce cross-border regulatory exposure. |
| Dry-Fractionation Capacity Expansion | Mid-scale processors in Minnesota and Iowa are eliminating water-intensive steps to meet EPA discharge constraints. |
| Carbon-Verified Certification Investment | Suppliers with Scope 3 disclosure systems capture preferential contracting with European formulators facing CSRD deadlines. |
| Pet Nutrition Formulation Partnerships | Premium pet food brands are integrating navy bean concentrates to differentiate in the humanization trend. |
| Direct-to-Consumer Channel Development | CPG brands are building protein-forward portable nutrition lines that bypass retail slotting constraints. |
Methodological Framework
Independent corroboration across formulation scientists at meat alternative manufacturers, procurement directors at contract food manufacturers, and regulatory affairs specialists at ingredient processors underwrites the qualitative findings. Primary interviews with bean protein fractionation engineers, sustainability officers at CPG brands, and ANVISA compliance consultants combined with secondary validation from USDA dietary guideline publications, FDA GRAS notification databases, EFSA pesticide residue assessments, and Brazilian export trade statistics. Bottom-up volume modeling across product type, application, and form segments triangulates against top-down macroeconomic anchoring.
Comparable-period anchoring to historical protein substitution trends and institutional foodservice procurement cycles structured the projection horizon across the analysis window. Segmentation dimensions modeled include product type, application, end user, and form, with regional regulatory cluster and carbon-accounting compliance tier as cross-cutting variables. CAGRs derive from trend extrapolation adjusted for technology adoption curves and policy implementation timelines, with dry-fractionation penetration rates and CSRD disclosure compliance as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for wet-extraction retention in beverage-grade protein isolates would alter the outlook. Forecasts reflect assumptions regarding ANVISA-EFSA residue limit convergence, drought frequency in Black Sea origination belts, and co-manufacturer consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
India Gelatin Market
Ingredients
Codonopsis Extract Market
Ingredients
Eucalyptus Oil Market
Ingredients
Black Cumin Seed Oil Market
Ingredients
Carrot Fiber Market
Ingredients
Animal-Derived Ingredients Market
Ingredients
Pet Food Premix Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Organic Edible Oil Market
Ingredients
Rice Starch Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Torula Yeast Market
Ingredients
Avocado Oil Market
Ingredients
Canola Oil Market
Ingredients
Sunflower Oil Market