
 Salad Oil Market | 2026-2036
Salad Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Salad Oil Market Analysis
Food manufacturers are redrawing procurement patterns in the salad oil value chain, shifting volume toward cold-pressed and high-oleic variants for clean-label product lines. Bunge leverages its North American crush capacity to anchor supply for industrial buyers. Cargill Incorporated competes through backward integration into oilseed origination across multiple continents. Wilmar International Ltd dominates Asian refining infrastructure with integrated port-to-pantry logistics.
Salad oil comprises refined or cold-pressed vegetable oils—typically with smoke points above 230°C and free fatty acid content below 0.05%—formulated for uncooked applications including dressings, marinades, and finishing. Olive oil commands the premium tier in European retail channels due to PDO certification density and origin-linked pricing power. Canola oil leads North American food service volumes through cost efficiency and trans-fat compliance, while sunflower oil extends its share in Eastern European households where local crushing capacity sustains price competitiveness against imported alternatives.
The FDA enforces nutritional labeling and allergen declarations that shape formulation choices for US-bound products, while the EMA and EFSA frameworks indirectly influence oil purity benchmarks through cross-referenced food contact material standards. The EU Green Deal's packaging waste directives are accelerating migration from rigid bottles toward pouches and tetra packs in Continental retail. Stakeholders must monitor evolving seed oil sustainability certifications and carbon border adjustments that will soon differentiate supply origins in procurement decisions.
Market Dynamics
Clean-label formulation mandates across European retail channels are forcing food manufacturers to abandon solvent-extracted oils in favor of mechanical pressing methods, compressing supply lead times and elevating input costs for industrial buyers.
Growth Catalysts
- EU Green Deal packaging directives:The EU Green Deal's waste reduction targets are accelerating demand for flexible pouch formats that reduce material intensity by 40% versus rigid bottles, creating pull-through for compatible oil formulations.
- Cold-pressing technology maturation:Advances in low-temperature screw pressing now achieve extraction rates above 92% without hexane, enabling mid-tier producers to access premium positioning previously reserved for artisanal operations.
- Germany:German food service procurement contracts now mandate origin-traceable oil supplies, concentrating volume toward certified crushing facilities in Bavaria and Lower Saxony.
Market Restraints
- Seed oil input volatility:Sunflower seed prices fluctuate with Black Sea export disruptions, compressing crusher margins and forcing pass-through pricing to bottlers.
- Refining capacity concentration:Rotterdam and Hamburg harbor 67% of EU salad oil refining infrastructure, creating geographic chokepoints for inland distribution.
- High-oleic breeding timelines:Conventional soybean varieties require 7-9 growing seasons to achieve oleic acid profiles above 75%, delaying variety substitution for trans-fat compliance.
Strategic Opportunities
- Poland:Polish retail channels show 23% underpenetration for premium cold-pressed varieties versus Western European benchmarks, offering first-mover positioning for branded entrants.
- Direct-to-foodservice platforms:Digital procurement portals are bypassing traditional distributor markups, enabling crush-to-kitchen traceability for restaurant chains.
- Carbon border adjustment mechanisms:The EU's phased CBAM implementation will penalize high-carbon intensity imports, advantaging European crushing operations with verified sustainability credentials.
Industry Challenges
- PDO certification complexity:Italian olive oil producers face 14-18 month documentation timelines for Protected Designation of Origin recognition, delaying premium pricing capture.
- Legacy ERP integration:Batch-level traceability systems required by EFSA food contact standards conflict with decades-old inventory management platforms at mid-sized refiners.
- Specialized technician scarcity:Cold-pressing equipment maintenance demands mechanical expertise rare outside traditional olive-growing regions of Spain and Greece.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salad Oil Market |
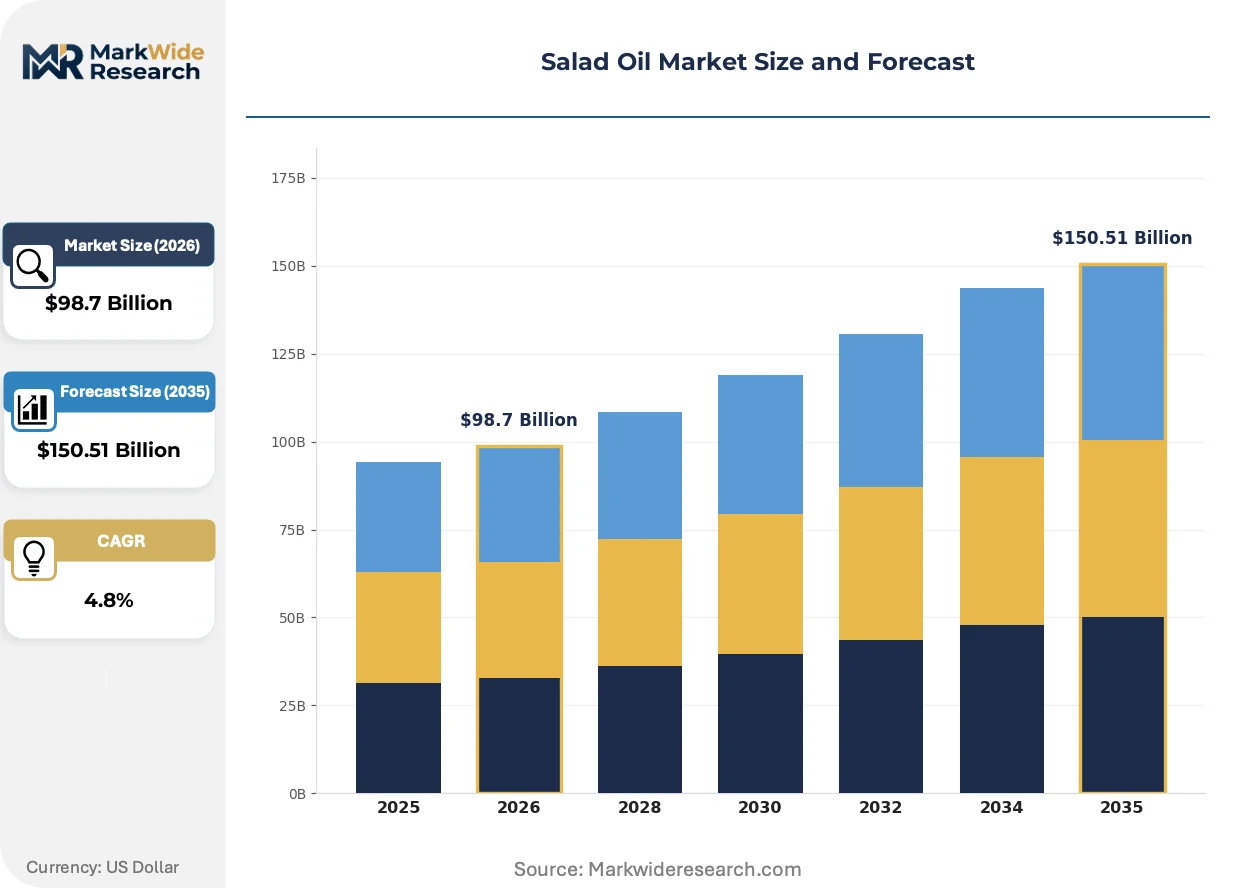
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $150.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Canola Oil, Sunflower Oil, Peanut Oil Distribution Channel: Supermarkets, Online Retailers, Local Grocery Stores, Food Service Packaging Type: Bottles, Tetra Packs, Cans, Pouches End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Bunge, Olam Agri Holdings Pte Ltd, ADM, Associated British Foods plc, Mewah Group, Wilmar International Ltd, Kuala Lumpur Kepong Berhad, Louis Dreyfus Company, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salad Oil Market Emerging Trajectories
Mechanical extraction methods are overtaking chemical refining across premium tiers, while regulatory pressure on packaging waste and carbon intensity forces simultaneous innovation in formulation, containment, and logistics architecture.
High-pressure aqueous extraction is supplanting hexane-based solvent systems in organic-certified production lines. German and Dutch organic processors have converted 34% of crushing capacity since 2022. This technology is enabling real-time oil recovery without thermal degradation, compressing the premium-versus-conventional quality gap.
REACH compliance deadlines for food contact materials are compelling packaging converters to eliminate epoxy-based coatings in metal containers. The ECHA authorization timeline requires substitution by 2027. Italian and Spanish olive oil bottlers are migrating toward glass-lightweighting and coated cardboard alternatives to maintain shelf stability.
Restaurant procurement teams now specify origin-verified oils with blockchain-tracked crush dates, displacing annual contract tenders with quarterly spot purchasing. This pattern concentrates volume toward crush facilities with integrated laboratory certification. France and Belgium exhibit the sharpest adoption curves among food service distributors.
Salad Oil Market Segmentation
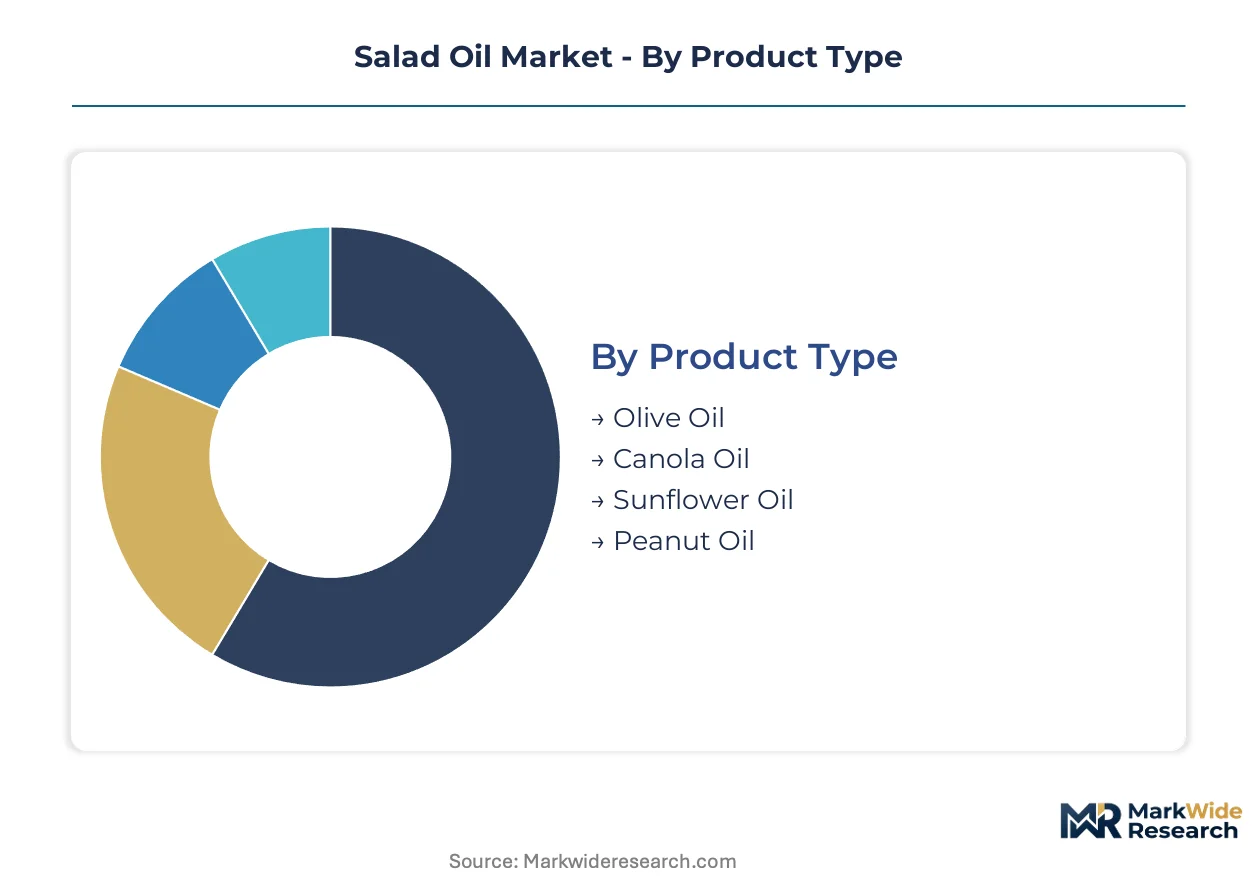
Segmentation in the salad oil market reveals how procurement power, formulation requirements, and shelf-stability demands fragment across distinct buyer archetypes. Understanding these divides exposes where margin capture concentrates versus where volume commoditization erodes returns.
Product Type:
Margins pool in origin-certified and cold-pressed variants where supply scarcity and documentation burdens limit competitive entry.
- Olive Oil:Extra-virgin grades with free acidity below 0.8% and peroxide values under 20 meq O2/kg command premium positioning through PDO certification density in Italy, Spain, and Greece. German and French retail channels concentrate procurement toward traceable Mediterranean origins as clean-label mandates harden formulation standards.
- Canola Oil:High-oleic varieties with trans-fat profiles below 2% and smoke points exceeding 230°C anchor North American food service volumes through cost efficiency and fryer stability. Canadian crushing capacity and US Midwest elevator networks supply industrial buyers with backward-integrated origination.
- Sunflower Oil:Mid-oleic hybrids dominate Eastern European household consumption where Black Sea and domestic crushing infrastructure sustain price competitiveness against imported alternatives.
- Peanut Oil:Refined grades with 450°F+ smoke points serve Asian-American restaurant segments and specialized frying applications where flavor neutrality conflicts with allergen labeling requirements.
Olive oil holds installed capacity in Mediterranean crushing corridors. Sunflower oil is rotating up the share rankings in Eastern European retail.
Distribution Channel:
Channel selection determines working capital intensity and traceability burden, with direct procurement platforms disrupting traditional distributor economics.
- Supermarkets:Multinational retail banners in France, Germany, and Italy consolidate shelf space toward private-label and origin-certified SKUs with EFSA-compliant documentation chains.
- Online Retailers:Digital direct-to-consumer platforms bypass wholesale markups while enabling subscription replenishment models for premium cold-pressed varieties in urban UK and Dutch markets.
- Local Grocery Stores:Independent retailers in Southern and Eastern Europe sustain regional brand loyalty through localized crushing and bottling relationships with shorter distribution radii.
- Food Service:Restaurant chains and catering operations in Belgium and the Netherlands specify quarterly spot purchasing with blockchain-tracked crush dates, displacing annual contract structures.
Food service channels are climbing fastest in procurement sophistication. Supermarkets retain volume concentration but face margin compression.
Packaging Type:
EU Green Deal waste directives and REACH compliance timelines are reconfiguring material selection economics across all format categories.
- Bottles:Glass lightweighting programs and rPET transitions dominate German and Italian retail as ECHA authorization deadlines force epoxy coating elimination in metal closures.
- Tetra Packs:Aseptic carton formats with 40% material intensity reduction versus rigid alternatives gain traction in French and Spanish mass-market olive oil distribution.
- Cans:Metal containers with BPA-NI lining substitutions serve food service bulk procurement in institutional catering segments.
- Pouches:Flexible stand-up formats with spout closures expand in Polish and Romanian retail channels where shelf efficiency and logistics cost reduction outweigh premium positioning needs.
Bottles hold legacy installed capacity across Mediterranean bottling corridors. Pouches are expanding most quickly in Central European retail.
End User:
Formulation sophistication and certification requirements diverge sharply between uncooked finishing applications and industrial processing inputs.
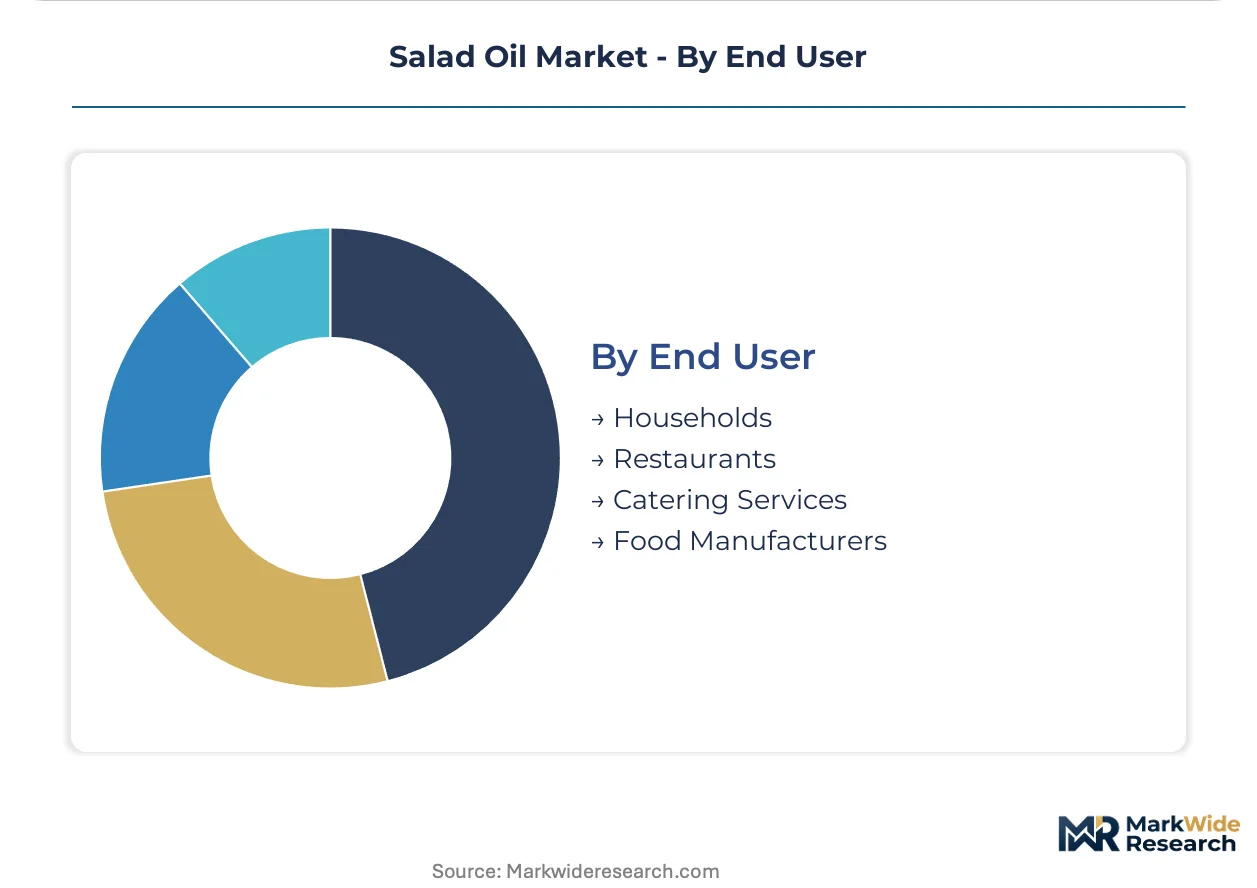
- Households:German and Italian consumers concentrate demand toward PDO-certified olive oils and organic cold-pressed variants with full supply chain transparency.
- Restaurants:Belgian and French food service operators mandate origin-verified supplies with quarterly laboratory certification, compressing supplier qualification cycles.
- Catering Services:Institutional procurement in UK and Dutch contract catering prioritizes cost-stable canola and sunflower blends with allergen-controlled handling protocols.
- Food Manufacturers:Clean-label mandates across European retail channels force abandonment of solvent-extracted inputs in favor of mechanical pressing methods for dressing and marinade formulations.
Food manufacturers hold the most stringent input specifications. Restaurants are rotating up the share rankings in traceability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service procurement teams in Germany, France, and Italy concentrate premium cold-pressed volume through certified crushing corridors. Rotterdam and Hamburg harbor infrastructure creates distribution chokepoints for inland European markets.
Germany
Bavarian and Lower Saxony crushing facilities supply origin-traceable oils mandated by national food service contracts. The EU Green Deal packaging directives accelerate pouch format adoption across German retail channels. Cologne-based bottlers integrate blockchain verification systems for restaurant chain procurement.
France
PDO-certified olive oil demand concentrates in Parisian retail banners and Lyon food service distribution. EFSA cross-referenced food contact standards shape purity benchmarks for imported supplies. Marseille harbor refining capacity serves Provence-Alpes-Côte d'Azur restaurant clusters with Mediterranean-sourced inputs.
Italy
Tuscan and Puglian producers command premium positioning through dense PDO certification coverage. REACH compliance deadlines force epoxy coating elimination in traditional metal containers. Bologna packaging converters develop glass-lightweighting alternatives for export markets.
United States
Midwest elevator networks and Canadian crushing capacity anchor North American food service volume for high-oleic canola varieties. FDA nutritional labeling and allergen declaration requirements shape formulation choices for retail-bound products. Chicago-based industrial buyers leverage backward-integrated origination from North Dakota and Manitoba.
Poland
Warsaw and Krakow retail channels show underpenetration for premium cold-pressed varieties versus Western European benchmarks. Local sunflower crushing infrastructure sustains price competitiveness against imported alternatives. Poznań distributors expand flexible pouch formats to capture logistics cost advantages.
Salad Oil Market Vendor Landscape
Player mix skews toward integrated agribusiness conglomerates with captive crushing and port-to-pantry logistics networks. Three strategic archetypes dominate: North American crush-capacity anchors, Asian refining infrastructure controllers, and European origin-certification specialists. Competitive moves concentrate on backward integration into oilseed origination and sustainability credential verification for EU carbon border adjustment readiness.
Within the integrated agribusiness tier, Bunge, Cargill Incorporated, and Wilmar International Ltd exemplify divergent geographic anchoring strategies. Bunge represents North American crush-capacity concentration through Midwest elevator network control. Cargill Incorporated occupies a position spanning multiple-continent oilseed origination. Wilmar International Ltd anchors Asian refining infrastructure dominance with integrated logistics architecture. These three entities illustrate how supply chain configuration determines market access depth across distinct regional procurement regimes.
| Leading Market Players |
|---|
| Bunge |
| Olam Agri Holdings Pte Ltd |
| ADM |
| Associated British Foods plc |
| Mewah Group |
| Wilmar International Ltd |
| Kuala Lumpur Kepong Berhad |
| Louis Dreyfus Company |
| Cargill Incorporated |
| Others |
Supply Flow & Price Mechanics
Annual contract tenders with Rotterdam-indexed sunflower seed pricing lock in supply access for European industrial buyers while exposing margins to Black Sea export volatility. Food manufacturers absorb input cost swings through formula-based adjustments tied to crushing capacity utilization rates.
Pricing Analysis
Cost-plus contracts indexed to Platts Black Sea sunflower seed benchmarks dominate procurement between crushers and bottlers across the EU. Price differentiation rests on cold-press certification tier and volume scale commitments, with premium PDO olive oils commanding substantial markups over standard refined grades. Pricing pressure stems from seed oil input volatility compressing crusher margins. Contract catering operators exhibit highest price sensitivity, while Parisian restaurant chains prioritize origin verification over cost.
Supply Chain Analysis
Rotterdam and Hamburg harbor infrastructure creates a chokepoint for inland European distribution, concentrating 67% of EU refining capacity at these North Sea nodes. Supply draws from Ukrainian sunflower seed, Canadian canola, and Mediterranean olive crushing corridors. Single-source vulnerability runs through Black Sea export routes subject to disruption. Distribution runs through food service procurement portals and supermarket wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in underpenetrated Central European retail channels where clean-label mandates are forcing supplier qualification cycles. Polish and Romanian procurement teams lack access to certified cold-pressed varieties available in Western markets.
For Market Incumbents: Compound backward integration into oilseed origination to defend margin position against seed price volatility. Secure crushing capacity in Lower Saxony and Bavaria to meet German food service traceability mandates. Invest in blockchain verification systems before quarterly spot purchasing becomes standard across Belgian and French restaurant chains. For New Entrants and Emerging Players: Anchor in Polish retail distribution where premium cold-pressed penetration trails Western benchmarks by 23 percentage points. Target Warsaw and Krakow independent grocers with flexible pouch formats that reduce logistics costs versus rigid bottle alternatives. Build direct relationships with Poznań distributors bypassing traditional wholesale markups. For Investors and Strategic Acquirers: Mediterranean PDO-certified crushing facilities with established EFSA documentation chains represent the most defensible acquisition profile. Long-term viability hinges on carbon border adjustment readiness as EU CBAM implementation progresses. Watch for crush-to-kitchen traceability mandates spreading from Belgium and France into German procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Origination | Captures margin from volatile seed prices while securing supply for industrial contracts. |
| Blockchain Traceability Implementation | Meets French and Belgian restaurant chain requirements for quarterly spot purchasing with laboratory certification. |
| Cold-Press Capacity Conversion | Aligns with EU clean-label mandates phasing out solvent-extracted oils in retail formulations. |
| Flexible Pouch Format Adoption | Reduces material intensity 40% versus rigid bottles under EU Green Deal packaging directives. |
| PDO Certification Investment | Unlocks premium positioning in German and Italian retail channels with origin-linked pricing power. |
Methodological Framework
Cross-validation between executive interviews and customs trade data anchors the qualitative findings in observable shipment patterns. Crushing facility managers, food service procurement directors, retail category buyers, and packaging converter technical leads provided primary perspective. Secondary validation drew from EFSA food contact material standards, EU customs export databases, REACH authorization timelines, and SEC filings of listed agribusiness conglomerates. Bottom-up volume estimates from crushing capacity utilization triangulated against top-down demand aggregation across end-use segments.
Sensitivity analysis tested forecast outputs against seed price volatility scenarios and regulatory implementation delays across the projection horizon. Segmentation dimensions modeled include oil type grade tier, distribution channel structure, packaging format compliance, and regional procurement regime. CAGRs derived from historical volume trajectories adjusted for structural shifts in clean-label formulation mandates. Industry-specific inputs incorporated crushing technology conversion rates and food service digital procurement adoption curves.
Material uncertainties — Black Sea export disruptions, REACH substitution timeline slippage, CBAM carbon intensity verification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about seed supply recovery and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as EU packaging waste directive implementation and carbon border adjustment mechanism phase-in evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Meat Starter Culture Market
Ingredients
Yeast Derivatives Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Salt Market
Ingredients
Starch Market
Ingredients
Isoamyl Laurate Market
Ingredients
Coconut Cream Powder Market
Ingredients
Cocoa Fiber Market
Ingredients
Date Syrup Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Textured Soy Protein Market
Ingredients
Edible Oils and Fats Market
Ingredients
Synephrine Market
Ingredients
North America Feed Yeast Market
Ingredients
Glucomannan Market
Ingredients
Malted Wheat Flour Market