
 France Soy Protein Market | 2026-2036
France Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
France Soy Protein Market Foresight
Premium-grade isolate specifications is rotating demand away from commodity soy flour across French formulation houses. Roquette Freres SA leverages its Picardy processing footprint to anchor supply for domestic nutraceutical customers. Kerry Group PLC competes through specialized texture systems for meat alternative applications. The Archer-Daniels-Midland Company extends its European origination network to sustain crush volumes into Rouen port operations.
Soy protein encompasses refined and textured preparations derived from dehulled, defatted soybean meal, with isolate grades achieving protein content exceeding 90 percent through alkaline extraction and isoelectric precipitation. These preparations function as functional binders, emulsifiers, and nutritional fortifiers across formulated foods and feed compounds. Textured soy protein and soy protein isolate capture divergent margin pools, with isolate commanding premium positioning in sports nutrition and infant formula while textured variants penetrate cost-sensitive meat extension applications. Dairy alternatives and meat alternatives represent the fastest-growing application channels as French retail chains expand private-label plant-based assortments.
ANSES monitors contaminant thresholds for soy-derived ingredients under French food safety protocols, while EFSA novel food evaluations govern emerging protein fractionation technologies entering European commerce. CE marking requirements and EU Green Deal protein diversification targets collectively elevate non-GMO and identity-preserved sourcing standards for market access. Stakeholders must track evolving F-Gas Regulation impacts on spray-drying energy costs and anticipate reformulation mandates from the EU Deforestation Regulation's traceability demands.
Market Dynamics
ANSES nutritional guidelines and EU protein diversification policy are compressing formulation windows for French food manufacturers, forcing rapid recertification of supply chains while Île-de-France processors absorb disproportionate compliance costs.
Growth Catalysts
- EU Green Deal protein diversification targets:Mandatory protein sourcing quotas for institutional foodservice channels are redirecting procurement toward domestic soy fractionation capacity.
- Plant-based meat alternatives:French retail chains expanding private-label assortments are pulling isolate-grade specifications through formulation houses at contracted volumes.
- Spray-drying energy efficiency improvements:F-Gas Regulation compliance investments are lowering unit processing costs for Picardy-based isolate production.
Market Restraints
- Identity-preserved non-GMO soybean premiums:Sourcing constraints from certified origination zones are elevating raw material costs above commodity crush spreads.
- Rouen port crush concentration:European origination network dependencies create single-point vulnerability for domestic protein supply security.
- Infant formula technical barriers:EFSA novel food evaluation timelines extend commercialization cycles for emerging protein fractionation technologies.
Strategic Opportunities
- Sports nutrition channel expansion:Premium isolate positioning in athletic recovery formulations remains underdeveloped relative to whey protein dominance.
- CE marking harmonization:Streamlined conformity assessment pathways are accelerating market access for textured protein ingredient suppliers.
- Alkaline extraction-isoelectric precipitation convergence:Process integration is enabling 90%+ protein content achievement at reduced water intensity.
Industry Challenges
- EU Deforestation Regulation traceability infrastructure:Farm-level geolocation documentation requirements are forcing supply chain IT system overhauls with 18-month implementation windows.
- Contaminant threshold monitoring protocols:ANSES laboratory certification backlogs are delaying new supplier qualification for nutraceutical customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Soy Protein Market |
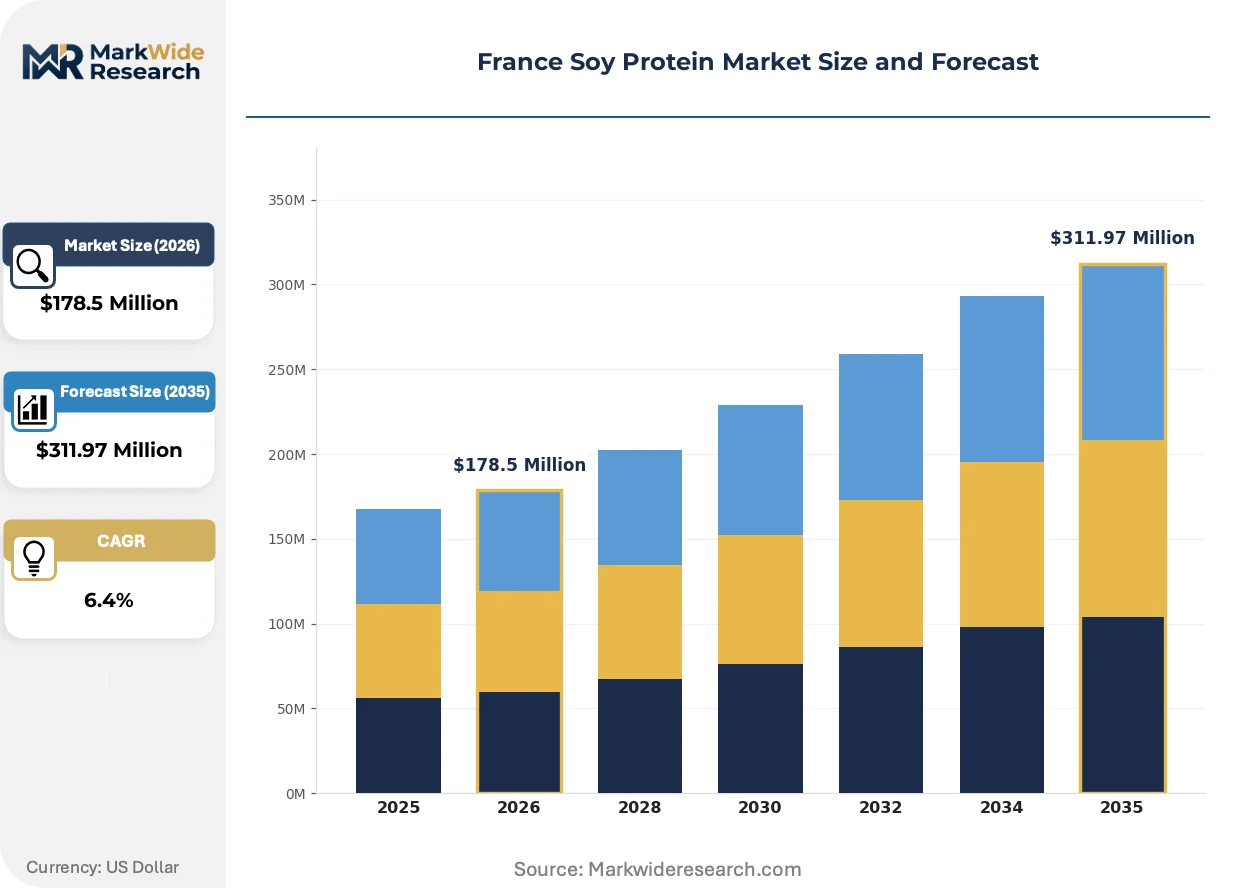
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $311.97 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Soy Protein, Soy Protein Concentrate, Soy Protein Isolate, Soy Flour, Soy Meal Application: Bakery, Meat Alternatives, Nutritional Supplements, Animal Feed, Dairy Alternatives End User Industry: Food & Beverage Manufacturers, Feed Producers, Nutraceutical Companies, Sports Nutrition, Cosmetic Industry Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Direct Sales, Wholesalers |
| Companies Covered | Kerry Group PLC, The Archer-Daniels-Midland Company, The Scoular Company, Bunge Limited, Roquette Freres SA, A. Costantino & C. SpA, Wilmar International Ltd, DuPont de Nemours Inc, International Flavors & Fragrances Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Soy Protein Market Shifts & Advancements
Fractionation technology advancement and regulatory traceability mandates are restructuring competitive advantage around processing sophistication rather than commodity scale alone.
Membrane filtration systems for protein isolate recovery are bifurcating the equipment supply base between European precision engineering specialists and Asian cost-optimized providers. French formulation houses are adopting hybrid configurations that blend ceramic microfiltration with spiral-wound ultrafiltration to achieve target purity thresholds. This technology trajectory is compressing margins for legacy spray-dryer-dependent operators while rewarding integrated process design capabilities.
F-Gas Regulation phase-down schedules are accelerating heat pump adoption for drying operations across French processing facilities. Industrial consequence includes capital reallocation toward refrigeration system retrofits and away from capacity expansion. Meat alternative manufacturers dependent on cost-competitive textured protein supplies are absorbing pass-through energy cost adjustments through reformulation flexibility.
Direct contracting between Île-de-France food manufacturers and Picardy processing clusters is displacing traditional ingredient distributor intermediation. Large retail chains are consolidating procurement through dedicated supply agreements with identity-preserved sourcing guarantees. This channel restructuring concentrates volume risk with processors while transferring traceability compliance costs upstream.
France Soy Protein Market Segmentation
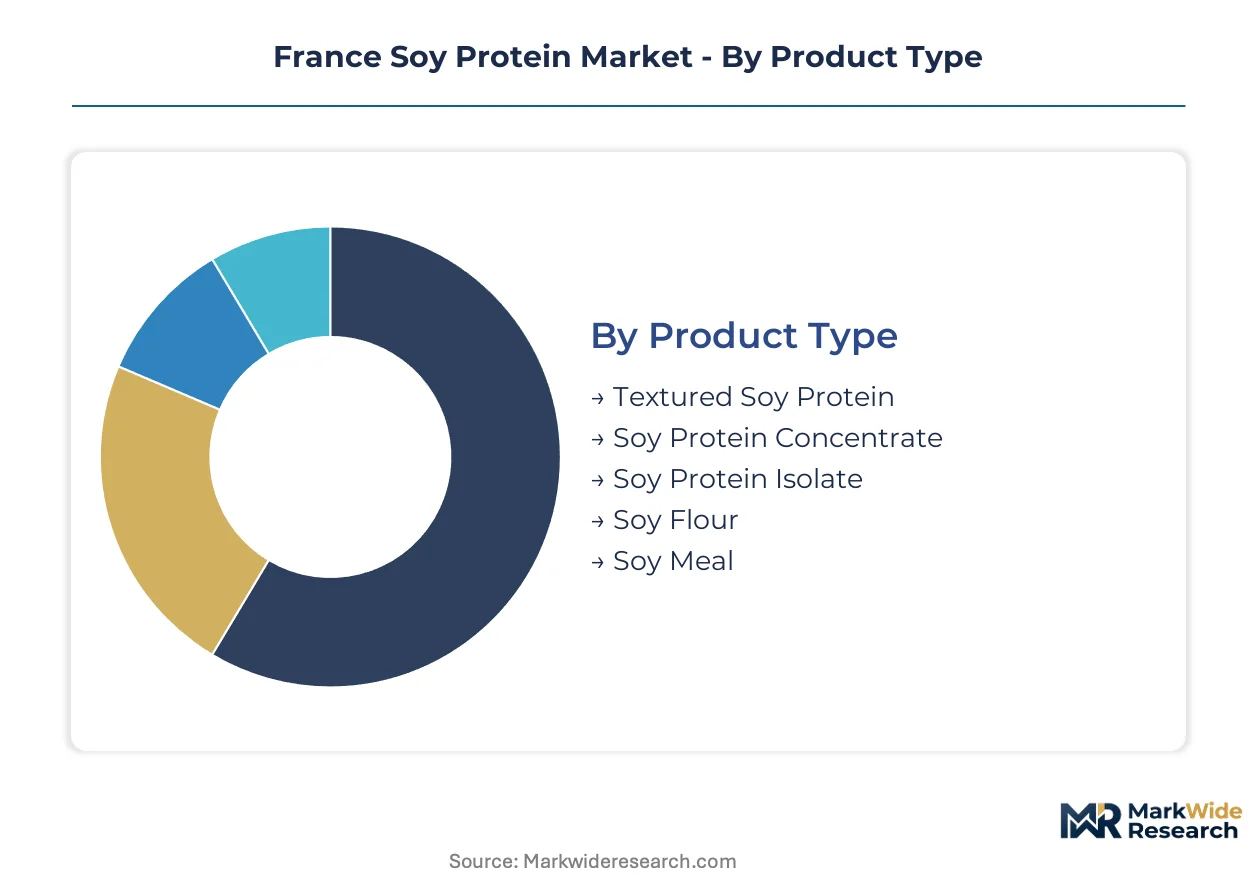
Soy protein segmentation in France reflects divergent margin pools across isolate-grade refinement and commodity meal processing. Channel specialization concentrates high-value isolate through direct sales to nutraceutical customers while textured variants flow through wholesale distribution to meat alternative formulators.
Product Type:
Isolate and concentrate grades command dedicated direct sales channels to Île-de-France formulation houses, while flour and meal segments distribute through agricultural wholesalers serving compound feed operations.
- Soy Protein Isolate:Alkaline extraction and isoelectric precipitation yield protein content exceeding 90 percent. Sports nutrition and infant formula manufacturers in the Paris basin specify this grade for amino acid completeness under ANSES monitoring protocols.
- Textured Soy Protein:Extruded fiber structures from defatted meal provide bite simulation for meat alternatives. French retail chains expanding private-label plant-based assortments pull contracted volumes through Rouen-port-adjacent processing clusters.
- Soy Protein Concentrate:Intermediate protein content (65-70 percent) serves cost-sensitive bakery fortification and emulsified meat extension applications.
- Soy Flour:Full-fat and defatted preparations function as nutritional binders in traditional French bakery formulations with lower functional requirements.
- Soy Meal:Standardized protein specification for animal feed compounding distributes through agricultural supply cooperatives.
Soy protein isolate dominates installed base value concentration. Textured soy protein is where expansion concentrates most steeply.
Application:
Application segmentation tracks the protein diversification policy mandate, with institutional foodservice quotas redirecting procurement toward meat and dairy alternative channels.
- Meat Alternatives:Textured protein extrusion and isolate binding systems enable plant-based burger, sausage, and deli slice replication. Kerry Group PLC texture systems compete for shelf space in French hypermarket chains.
- Dairy Alternatives:Isolate-grade emulsification supports yogurt analog and beverage creamer formulations. EFSA novel food evaluation timelines govern emerging fractionation technology adoption in this channel.
- Nutritional Supplements:Sports recovery and senior nutrition powders specify high-purity isolate for amino acid scoring completeness.
- Bakery:Concentrate and flour grades provide dough conditioning and protein fortification for industrial bread production.
- Animal Feed:Meal and lower-grade concentrate specifications serve poultry and aquaculture compound formulations.
Meat alternatives capture the steepest expansion trajectory. Dairy alternatives follow with comparable velocity as beverage applications proliferate.
End User Industry:
End user segmentation reveals procurement concentration among food and beverage manufacturers absorbing disproportionate EU Deforestation Regulation compliance costs.
- Food & Beverage Manufacturers:Industrial formulators in Île-de-France drive isolate and textured protein specification for retail brand production.
- Nutraceutical Companies:ANSES laboratory certification requirements delay new supplier qualification for this quality-sensitive segment.
- Sports Nutrition:Athletic recovery formulations represent underdeveloped isolate positioning relative to whey protein dominance.
- Feed Producers:Agricultural compounders source meal and lower-grade concentrates through Rouen port crush operations.
- Cosmetic Industry:Hydrolyzed protein fractions for hair and skin applications constitute a niche specification channel.
Food and beverage manufacturers dominate installed base volume. Nutraceutical companies concentrate expansion as clinical nutrition applications mature.
Distribution Channel:
Channel restructuring displaces traditional distributor intermediation as direct contracting between Picardy processors and Île-de-France manufacturers consolidates.
- Direct Sales:Identity-preserved sourcing agreements with geolocation documentation satisfy EU Deforestation Regulation traceability mandates for large retail chain procurement.
- Wholesalers:Agricultural supply cooperatives handle commodity meal and flour distribution to feed compounders and industrial bakeries.
- Online Retail:Sports nutrition isolate and specialty textured protein formats reach small-scale formulators and artisanal meat alternative producers.
- Supermarkets:Packaged consumer soy protein ingredients occupy limited shelf space in French hypermarket health food aisles.
- Specialty Stores:Organic and non-GMO certified preparations distribute through dedicated health food retail networks.
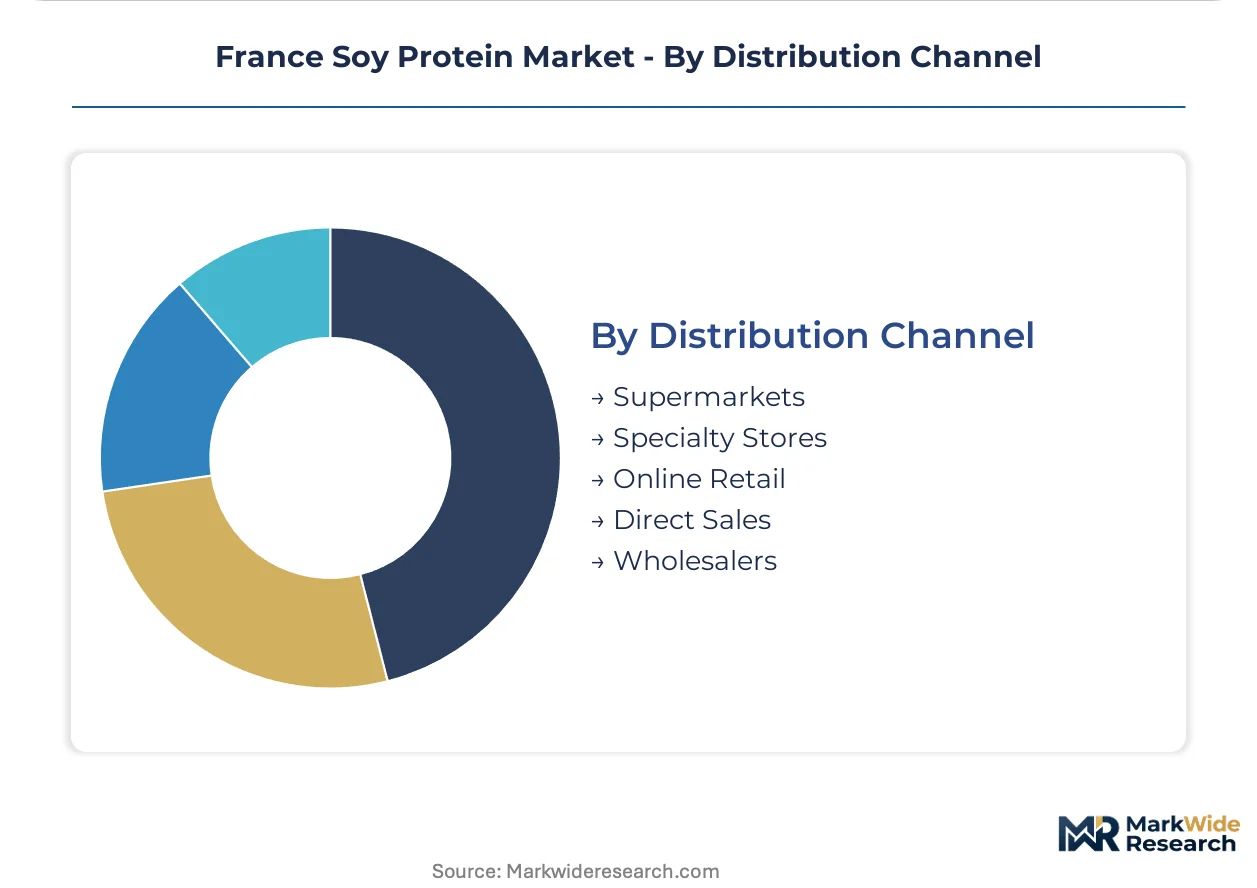
Direct sales dominates installed base value capture. Online retail is where expansion concentrates for small-batch formulator access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Picardy processing clusters and Rouen port crush operations concentrate domestic soy protein supply capacity. Île-de-France formulation houses absorb disproportionate compliance costs under EU Deforestation Regulation mandates. Regional procurement patterns are restructuring around identity-preserved sourcing corridors.
Île-de-France
Paris-basin food manufacturers drive isolate-grade specification for meat and dairy alternative production. ANSES nutritional guidelines force rapid reformulation certification cycles for retail brand suppliers. Saint-Denis and Gennevilliers industrial zones host concentrated extrusion and blending operations for plant-based meat analogs.
Hauts-de-France
Picardy processing infrastructure anchors domestic soy fractionation capacity for nutraceutical customers. F-Gas Regulation compliance investments are accelerating heat pump adoption for spray-drying operations in Lille-adjacent facilities. Roquette Freres SA leverages its regional footprint to supply identity-preserved isolate grades under direct contracting arrangements.
Normandy
Rouen port operations handle European origination network volumes for domestic crush and protein extraction. Seaborne soybean intake creates single-point vulnerability for supply security during logistics disruptions. Le Havre-adjacent storage terminals are expanding geolocation documentation capabilities for EU Deforestation Regulation traceability compliance.
Auvergne-Rhône-Alpes
Lyon-based food technology clusters are developing hybrid membrane filtration configurations for protein isolate recovery. CE marking harmonization is streamlining conformity assessment for textured protein ingredient suppliers targeting institutional foodservice channels. Saint-Étienne manufacturing zones are testing alkaline extraction-isoelectric precipitation process integration at reduced water intensity.
Nouvelle-Aquitaine
Bordeaux-region agricultural cooperatives are consolidating commodity meal distribution for poultry and aquaculture feed compounders. Non-GMO soybean premiums from certified origination zones are elevating raw material costs above standard crush spreads. Bayonne-adjacent port facilities are evaluating dedicated identity-preserved storage segregation for premium protein grades.
France Soy Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the French soy protein market. Integrated processors with captive origination networks compete against specialized fractionators with advanced extraction capabilities. The competitive structure bifurcates between multinational agricultural conglomerates and European precision-engineering specialists. Dominant competitive moves include direct contracting displacement of distributor intermediation and F-Gas Regulation-driven energy system retrofits.
Among Irish and US-based ingredient specialists, Kerry Group PLC and The Archer-Daniels-Midland Company occupy positions at opposite ends of the value chain spectrum. Roquette Freres SA exemplifies the European precision-engineering archetype with its Picardy processing footprint. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Kerry Group PLC |
| The Archer-Daniels-Midland Company |
| The Scoular Company |
| Bunge Limited |
| Roquette Freres SA |
| A. Costantino & C. SpA |
| Wilmar International Ltd |
| DuPont de Nemours Inc |
| International Flavors & Fragrances Inc |
| Others |
Supply & Pricing Matrix
Picardy processing clusters achieve scale economies through integrated spray-drying and membrane filtration operations that compress unit costs while elevating entry barriers for smaller fractionators. This concentration anchors price floors for isolate-grade specifications across Île-de-France formulation houses.
Pricing Analysis
EU Deforestation Regulation dictates the pricing tier structure through identity-preserved sourcing documentation requirements. Three-tier pricing structure across premium, standard, and economy levels separates non-GMO certified isolate from commodity concentrate and feed-grade meal. Cost compression in standard-tier concentrate is intensifying because F-Gas Regulation compliance investments are elevating energy pass-through charges. Feed producers demonstrate highest price sensitivity due to thin crush margins, while nutraceutical customers absorb premium-tier premiums for ANSES-certified isolate.
Supply Chain Analysis
France and Brazil anchor domestic soy protein supply through Rouen port crush operations and certified origination zone contracts. Raw material flows draw from identity-preserved non-GMO soybean stocks, defatted meal intermediates, and alkaline extraction chemicals. Single-source vulnerability concentrates in Rouen port logistics disruptions during Atlantic shipping constraints. Distribution runs through direct contracting between Picardy processors and Île-de-France manufacturers, displacing traditional agricultural wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France soy protein markets reward service-attach strategies where formulation technical support and traceability documentation generate recurring revenue streams expanding faster than commodity isolate sales.
For Market Incumbents: Consolidate Picardy processing capacity through membrane filtration technology upgrades that lock in nutraceutical customer loyalty. Capture backward integration into identity-preserved origination networks before EU Deforestation Regulation compliance windows close. Defend against Kerry Group PLC texture system encroachment by embedding formulation scientists within Île-de-France meat alternative development labs.
For New Entrants and Emerging Players: Lead with sports nutrition isolate positioning where whey protein dominance leaves white-space for amino acid-complete alternatives. Target Auvergne-Rhône-Alpes hybrid filtration technology clusters for cost-disadvantaged market entry. Pursue direct-to-formulator online channels that bypass established distributor relationships.
For Investors and Strategic Acquirers: European precision-engineering specialists with captive membrane filtration capabilities offer superior long-term viability through technology differentiation rather than commodity scale. Watch CE marking harmonization velocity as inflection indicator for textured protein ingredient supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Identity-Preserved Origination | EU Deforestation Regulation traceability mandates require farm-level geolocation documentation capabilities. |
| Membrane Filtration Technology Upgrade | Hybrid ceramic-spiral configurations achieve 90%+ protein purity thresholds at reduced water intensity. |
| Direct Contracting Channel Establishment | Large retail chains consolidate procurement through dedicated supply agreements displacing distributor intermediation. |
| Sports Nutrition Formulation Partnership | Athletic recovery applications remain underdeveloped relative to whey protein dominance in French markets. |
| F-Gas Regulation Heat Pump Retrofit | Refrigeration system investments lower unit processing costs for Picardy-based isolate production. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with soy protein plant managers, nutraceutical procurement leads, ANSES laboratory certification officers, and Rouen port logistics coordinators; and secondary validation through EFSA novel food evaluation filings, EU Green Deal protein diversification policy documents, French customs trade records, and SEC 10-K disclosures from multinational ingredient suppliers. Bottom-up volume triangulation across isolate, concentrate, and textured protein grades converged with top-down value estimates from formulation house procurement data.
Across the analysis window, projections integrated product type segmentation by protein content tier, application channel by meat alternative versus dairy alternative velocity, and end-user industry by food manufacturer versus nutraceutical qualification requirements. CAGRs derived from historical volume trajectories adjusted for EU Deforestation Regulation implementation pacing and F-Gas Regulation energy cost pass-through assumptions. Industry-specific forecast inputs included ANSES laboratory certification backlog durations and identity-preserved soybean premium spreads.
The analysis sits within stated boundaries; outcomes outside sustained EU protein diversification policy enforcement or Atlantic shipping route stability would require recalibration. Forecasts reflect documented assumptions regarding membrane filtration adoption curves and retail chain private-label expansion commitments. Recalibration cycles align with material shifts in EU Green Deal quota mandates and EFSA novel food evaluation timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Rose Hips Extract Market
Ingredients
Fermented Ingredients Market
Ingredients
Proteose Peptone Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Europe Soy Protein Market
Ingredients
Egg Albumin Protein Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
Interesterified Fats Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Collagen Casings Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Fonio Flour Market