
 Oat Beta-Glucan Market | 2026-2036
Oat Beta-Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Beta-Glucan Market Analytics
Pharmaceutical-grade purity specifications above seventy percent beta-glucan content is unwinding commodity pricing dynamics across the oat beta-glucan supply base. Cargill, Incorporated leverages its North American grain origination network to secure high-avenanthramide oat varieties for premium extracts. Tate & Lyle sustains European market presence through specialized beta-glucan isolates tailored to dairy texturizing applications. Swedish Oat Fiber AB dominates Scandinavian sourcing with vertically controlled milling operations near Malmö.
Oat beta-glucan comprises linear unbranched polysaccharides of mixed-linkage D-glucose units, with beta-(1,3) and beta-(1,4) glycosidic bonds conferring viscosity and gelation properties at concentrations above three percent in aqueous solution. Manufacturers extract these fibers through aqueous alkaline or enzymatic processes to achieve molecular weights between one hundred and three hundred kilodaltons for functional efficacy. Soluble oat beta-glucan occupies the dominant value position due to FDA-recognized cholesterol reduction claims, while powder formats lead volume throughput across nutraceutical and functional food channels. Liquid beta-glucan concentrates represent the fastest-growing format as beverage manufacturers seek clean-label viscosity without particulate suspension issues.
FDA authorized health claims under 21 CFR 101.81 and EFSA opinions on Article 13.1 and 14.1 submissions structure product positioning and substantiation costs for oat beta-glucan suppliers seeking differentiated label claims. BIS food additive standards in India and China's GB standards for dietary fiber labeling create additional compliance layers for exporters targeting Asia-Pacific formulation partnerships. Stakeholders must monitor evolving EFSA guidance on novel extraction solvents and FDA enforcement discretion on structure-function claims to anticipate reformulation requirements and competitive positioning shifts.
Market Dynamics
Pharmaceutical-grade purity thresholds above seventy percent beta-glucan content are compressing commodity pricing tiers and forcing suppliers to choose between volume scale and premium positioning. This structural bifurcation is accelerating capital deployment into specialized extraction infrastructure.
Growth Catalysts
- FDA 21 CFR 101.81 health claims:Cholesterol-reduction labeling authorizations in the United States sustain demand pull from functional food manufacturers seeking differentiated positioning.
- Enzymatic extraction methods:Precision hydrolysis technologies yield higher molecular-weight fractions with superior viscosity profiles for beverage applications.
- Germany:Soluble fiber labeling regulations and preventive nutrition preferences among aging consumers concentrate European demand in this market.
Market Restraints
- Oat raw material volatility:Weather-dependent grain harvests and protein crop competition constrain input cost predictability for extractors.
- EFSA novel solvent guidance:Evolving restrictions on extraction chemistry create compliance uncertainty and reformulation costs for European suppliers.
- Guar gum substitution:Lower-cost hydrocolloids with comparable viscosity properties threaten price-sensitive bakery and dairy applications.
Strategic Opportunities
- India BIS food additive standards:Emerging regulatory clarity for dietary fiber labeling opens formulation partnerships with domestic nutraceutical manufacturers.
- Liquid concentrate formats:Clean-label viscosity solutions for beverage channels address particulate suspension limitations of powder alternatives.
- Aqueous alkaline extraction:Convergence with membrane filtration technologies enables continuous processing at pharmaceutical purity grades.
Industry Challenges
- Analytical chemist scarcity:Specialized expertise in beta-glucan molecular weight characterization and bioactivity assay validation constrains quality control scaling.
- Multi-jurisdiction certification timelines:Sequential FDA, EFSA, and BIS approval processes extend product launch cycles and capital lockup periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Beta-Glucan Market |
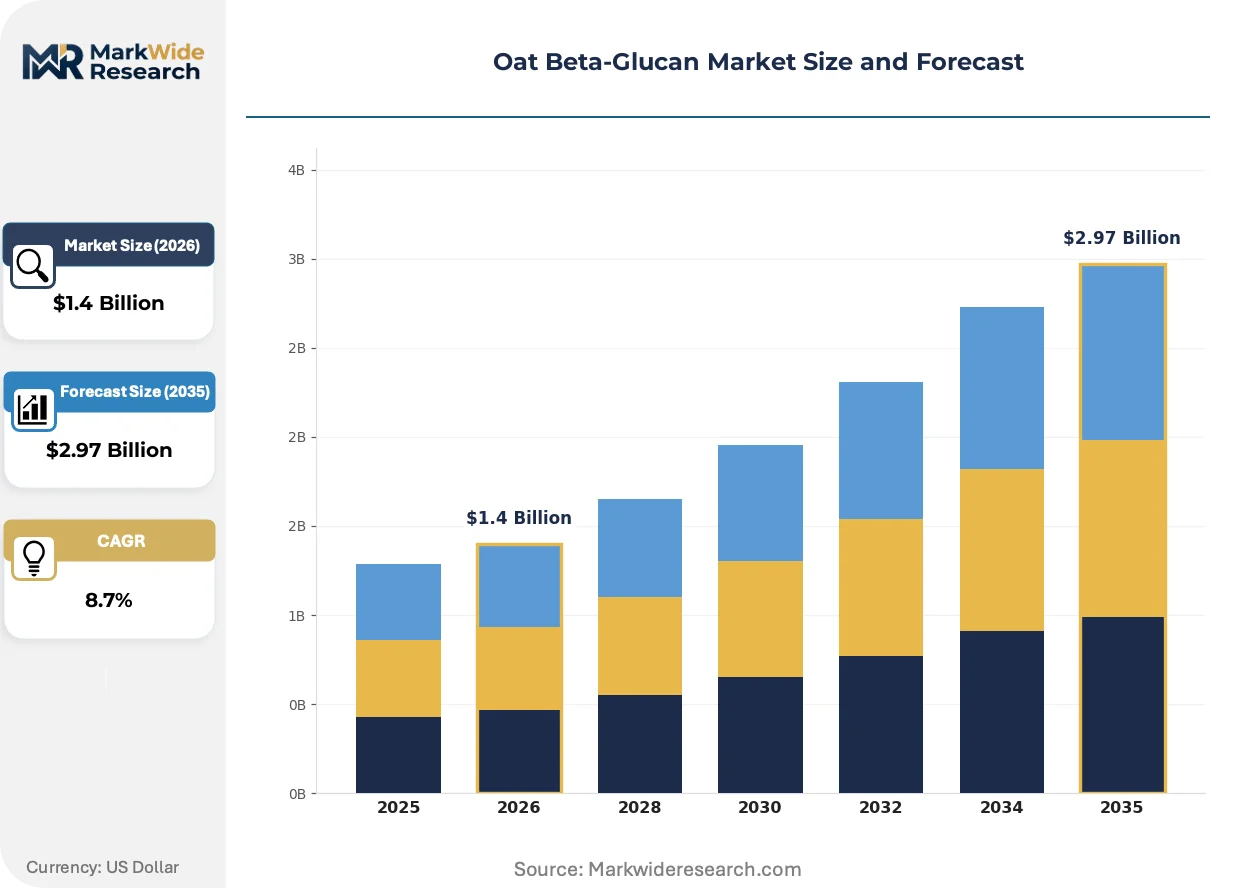
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble, Insoluble, Powder, Liquid Application: Nutraceuticals, Functional Foods, Dairy Products, Beverages End User: Food Manufacturers, Dietary Supplement Companies, Pharmaceutical Firms, Animal Feed Industry Distribution Channel: Online Retail, Supermarkets, Health Stores, Wholesalers |
| Companies Covered | Cargill, Incorporated, Tate & Lyle, Kerry Group plc, Lantmännen Biorefineries, Swedish Oat Fiber AB, Ceapro, Inc., Oy Karl Fazer Ab, Guangzhou Sinocon Food Co., Ltd., L&P Food Ingredient Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Beta-Glucan Market Evolving Landscape
Extraction technology diversification and regulatory claim expansion are simultaneously fragmenting supplier positioning and opening new formulation categories. These forces are reshaping competitive boundaries between commodity grain processors and specialized bioactive ingredient houses.
Membrane filtration systems paired with enzymatic hydrolysis are fragmenting the traditional aqueous alkaline extraction monopoly. Beverage manufacturers in the United States and Germany are adopting these methods to achieve molecular weight precision without solvent residues. The technology is fragmenting equipment supplier hierarchies as engineering firms from adjacent dairy filtration sectors enter oat beta-glucan system design.
EFSA opinions on Article 14.1 disease-risk reduction submissions are tightening substantiation requirements for cholesterol claims. European suppliers now face expanded clinical trial obligations and dossier preparation costs. Dairy texturizing applications in Scandinavia and the Netherlands are most affected, with several manufacturers retreating to generic fiber labeling.
Clean-label procurement mandates from retail chains are compressing acceptable ingredient lists and elevating traceability requirements. Functional food brands in Germany and the United States now require certified gluten-free oat sourcing and solvent-free extraction documentation. This pattern is most visible in private-label bakery launches targeting celiac-sensitive consumer segments.
Oat Beta-Glucan Market Segmentation
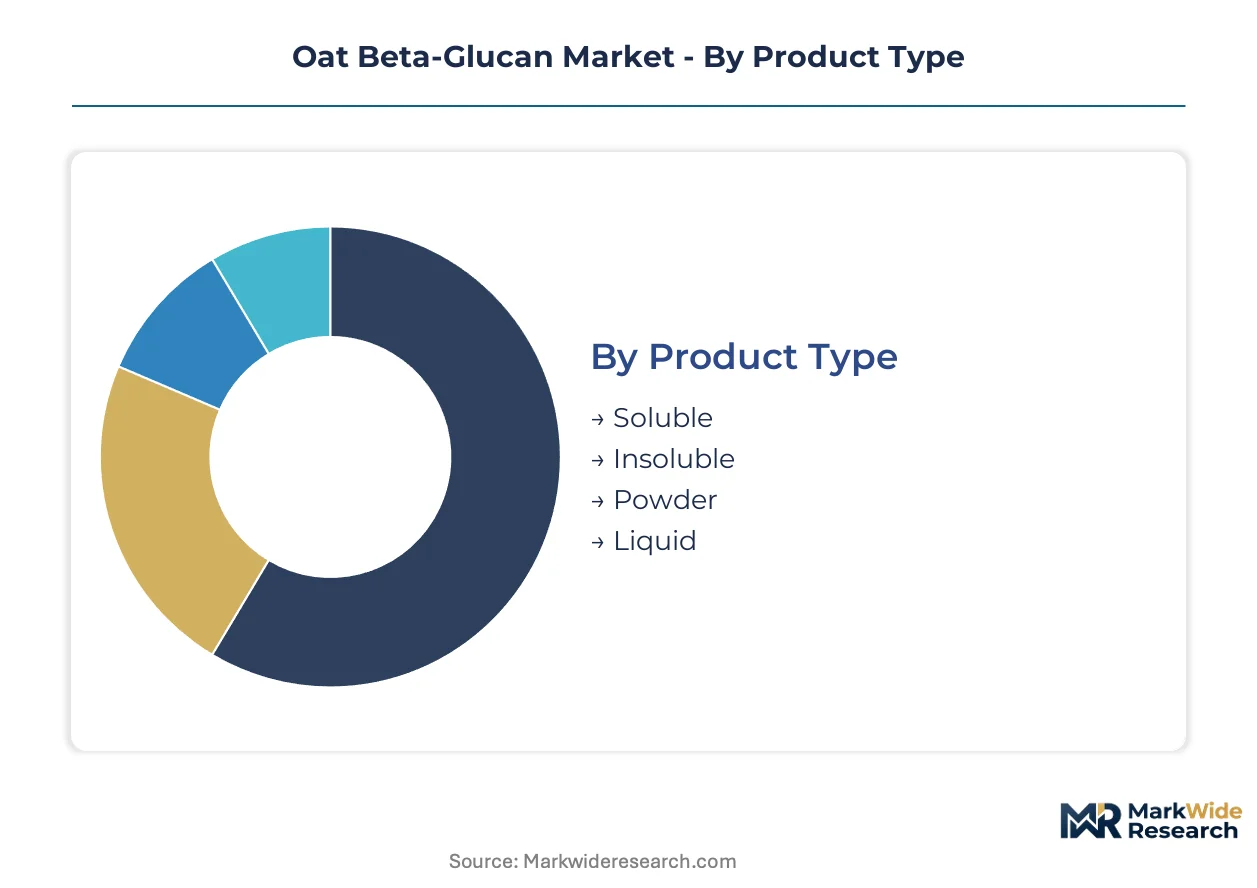
Segmentation in oat beta-glucan markets tracks how viscosity specifications, purity grades, and format requirements split demand across functional food, pharmaceutical, and feed applications. Suppliers must align extraction capabilities with the precise molecular weight and solubility thresholds each segment demands.
Product Type:
Guar gum and locust bean gum exert the strongest substitution pressure on lower-purity powder grades, while high-specification soluble extracts defend position through FDA-recognized health claims.
- Soluble:Linear mixed-linkage polysaccharides with beta-(1,3) and beta-(1,4) bonds deliver viscosity at concentrations above three percent in aqueous solution. Demand concentrates in the United States and Germany where FDA 21 CFR 101.81 and EFSA Article 14.1 claims require minimum beta-glucan thresholds for cholesterol-reduction labeling.
- Powder:Spray-dried or freeze-dried formats dominate nutraceutical encapsulation and bakery fortification due to shelf stability and handling convenience. Volume throughput runs highest across North American functional food channels where dry-blending operations favor particulate dispersibility.
- Insoluble:Cell wall-bound fractions with limited viscosity contribution serve fiber-enrichment applications in animal feed and conventional baked goods.
- Liquid:Concentrated aqueous solutions enable clean-label viscosity in beverage formulations without suspension issues.
Soluble oat beta-glucan anchors the volume base while liquid concentrates gain share at the steepest rate.
Application:
Cost-tier stratification separates premium clinical-grade positioning in nutraceuticals from commodity fiber fortification in conventional food manufacturing.
- Functional Foods:Cereal bars, breads, and pasta carry EFSA-approved disease-risk reduction claims in Europe and FDA-authorized health claims in the United States. German and US manufacturers lead formulation activity due to soluble fiber labeling regulations and aging consumer bases favoring preventive nutrition.
- Beverages:RTD smoothies and oat-based dairy alternatives require molecular weight precision to achieve viscosity without grit or precipitation. Enzymatic extraction methods with membrane filtration support this specification tier.
- Nutraceuticals:Capsule and tablet formats target cholesterol management with standardized beta-glucan content.
- Dairy Products:Yogurt and ice cream texturizing applications in Scandinavia and the Netherlands face EFSA substantiation cost pressures.
Functional foods anchor the volume base while beverages climb the fastest as clean-label viscosity solutions displace modified starches.
End User:
Customer-type concentration shows food manufacturers driving standard-grade volume while pharmaceutical firms absorb premium-grade supply at purity thresholds above seventy percent.
- Food Manufacturers:Multinational bakery and cereal brands in Germany and the United States specify certified gluten-free oat sourcing and solvent-free extraction documentation to meet retail chain procurement mandates.
- Dietary Supplement Companies:Capsule and softgel producers require batch-to-batch consistency in molecular weight distribution for label claim substantiation.
- Pharmaceutical Firms:Clinical trial material and prescription-grade fiber products demand pharmaceutical purity grades with full analytical characterization.
- Animal Feed Industry:Gut health and immune modulation applications in poultry and swine production utilize lower-purity fractions at price-sensitive tonnage.
Food manufacturers anchor the volume base while pharmaceutical firms expand most quickly as purity specifications compress commodity tiers.
Distribution Channel:
Supply concentration favors direct procurement relationships for bulk industrial buyers, while fragmented retail channels serve smaller formulation houses.
- Wholesalers:Ingredient distributors in the United States and Germany consolidate shipments from Scandinavian and North American extraction facilities to regional compounding operations.
- Online Retail:E-commerce platforms enable small-scale nutraceutical manufacturers and research institutions to access specialty grades without minimum order constraints.
- Supermarkets:Private-label functional food brands source through retail chain procurement mandates specifying traceability and clean-label documentation.
- Health Stores:Specialty retailers carry finished consumer products rather than bulk ingredients, limiting direct channel relevance for B2B suppliers.
Wholesalers anchor the volume base while online retail expands most quickly as small-batch formulation demand fragments procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows favor Scandinavian and North American extraction facilities supplying German and US formulation houses, while import dependence characterizes Asia-Pacific markets seeking pharmaceutical-grade supply. Trade balances reflect raw material proximity versus premium processing capability.
United States
Functional food manufacturers in Minneapolis and Chicago drive demand for cholesterol-reduction label claims under FDA 21 CFR 101.81. The FDA maintains strict substantiation requirements for soluble fiber health claims. Cargill leverages its North American grain origination network to secure high-avenanthramide oat varieties for premium extracts.
Germany
Aging consumer bases in Bavaria and North Rhine-Westphalia favor preventive nutrition ingredients with EFSA Article 14.1 disease-risk reduction approvals. EFSA opinions structure product positioning costs for European suppliers. Tate & Lyle sustains market presence through specialized beta-glucan isolates tailored to dairy texturizing applications.
Sweden
Scandinavian sourcing concentrates near Malmö with vertically controlled milling operations serving pharmaceutical-grade purity specifications. EFSA novel solvent guidance creates compliance uncertainty for extraction chemistry. Swedish Oat Fiber AB dominates regional supply with captive production infrastructure.
China
Domestic nutraceutical manufacturers in Shanghai and Guangzhou seek formulation partnerships as GB standards for dietary fiber labeling clarify import requirements. SAMR and GB standards create additional compliance layers for exporters. Guangzhou Sinocon Food and L&P Food Ingredient occupy positions in the specialty ingredients trade.
India
Emerging regulatory clarity through BIS food additive standards opens opportunities for dietary fiber labeling partnerships in Mumbai and Delhi-NCR. FSSAI and BIS frameworks govern food additive approvals. Local compounding operations increasingly source through wholesale distributors consolidating Scandinavian and North American shipments.
Oat Beta-Glucan Market Competitive Landscape
Concentration sits with diversified grain processors and specialized bioactive ingredient houses competing across purity tiers. The supplier base fragments between volume-scale commodity extractors and premium-grade pharmaceutical specialists. Three archetypes dominate: North American grain-origination conglomerates, European dairy-texturizing specialists, and Scandinavian vertically integrated millers. Competitive moves center on enzymatic extraction technology licensing and certified gluten-free sourcing partnerships.
Within the grain-origination tier, Cargill, Incorporated represents North American supply chain integration. Tate & Lyle exemplifies European formulation specialization. Swedish Oat Fiber AB anchors Scandinavian vertical control. Kerry Group plc and Lantmännen Biorefineries occupy positions in the diversified ingredients segment, while Ceapro and Oy Karl Fazer Ab sit within the premium extract archetype. Chinese specialists Guangzhou Sinocon Food and L&P Food Ingredient represent Asia-Pacific trading positions.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle |
| Kerry Group plc |
| Lantmännen Biorefineries |
| Swedish Oat Fiber AB |
| Ceapro, Inc. |
| Oy Karl Fazer Ab |
| Guangzhou Sinocon Food Co., Ltd. |
| L&P Food Ingredient Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at Scandinavian extraction facilities compress working capital flexibility while amplifying price volatility during oat harvest shortfalls. This lead-time exposure concentrates pricing power among vertically integrated millers with captive grain origination, forcing toll-dependent processors into defensive contract structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade extracts above seventy percent beta-glucan content command substantial premiums over commodity powder grades, with FDA 21 CFR 101.81 certification status and molecular weight consistency serving as primary differentiation drivers. Cost compression in standard-grade powders intensifies as guar gum substitution accelerates in price-sensitive bakery applications. Animal feed compounders exhibit highest price sensitivity, while pharmaceutical firms absorb premium tiers with limited elasticity.
Supply Chain Analysis
Sixty-day lead times from Swedish and Canadian milling operations to German and US formulation houses expose buyers to weather-driven oat harvest volatility. Supply concentrates in Sweden, Canada, and the United States, with raw material flows drawing from high-avenanthramide oat varieties and specialized enzymatic extraction inputs. Single-source vulnerability permeates pharmaceutical-grade supply where membrane filtration expertise remains geographically clustered. Distribution runs through wholesale ingredient distributors consolidating bulk shipments to regional compounding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in analytical testing and certification documentation expand faster than base extract sales, as pharmaceutical buyers outsource molecular weight validation and EFSA dossier preparation.
For Market Incumbents: Compound defensive positioning by securing certified gluten-free oat sourcing partnerships and licensing enzymatic extraction technology to beverage manufacturers seeking clean-label viscosity solutions. Guar gum substitution in bakery applications threatens volume tiers, making backward integration into captive grain origination essential for margin protection. For New Entrants and Emerging Players: Lead with liquid concentrate formats in Indian and Chinese beverage markets where BIS and GB standards are clarifying import pathways. Regulatory consulting services for EFSA Article 14.1 submissions represent the most penetrable white-space, with domestic nutraceutical manufacturers lacking in-house substantiation expertise. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified grain processors with underutilized extraction assets and dormant pharmaceutical-grade certifications. Long-term viability hinges on molecular weight precision capabilities and multi-jurisdiction approval infrastructure. Watch EFSA enforcement discretion on novel extraction solvents as the inflection signal for European supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Technology Licensing | Beverage manufacturers in Germany and the United States adopt precision hydrolysis for clean-label viscosity without solvent residues. |
| Certified Gluten-Free Sourcing Partnerships | Retail chain procurement mandates in the United States and Germany require traceability documentation for celiac-sensitive consumer segments. |
| Pharmaceutical-Grade Purity Expansion | Membrane filtration investments enable continuous processing at beta-glucan thresholds above seventy percent for clinical applications. |
| Regulatory Consulting Service Launch | EFSA Article 14.1 dossier preparation and FDA 21 CFR 101.81 substantiation support captures service-attach revenue from domestic manufacturers. |
| Backward Integration into Grain Origination | High-avenanthramide oat variety contracts secure input cost predictability against weather-dependent harvest volatility. |
Research Methodology
A spread of perspectives from extraction plant managers, procurement leads at functional food manufacturers, regulatory affairs directors, and wholesale ingredient distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 21 CFR 101.81 filings, EFSA Article 14.1 opinions, BIS food additive standards, and customs trade data. Bottom-up volume modeling triangulated against top-down value estimates across purity grades and application segments.
Segmentation dimensions modeled include product type, application category, end-user archetype, and distribution channel across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory claim expansion rates and substitution elasticity parameters. Forecast inputs incorporated oat harvest yield volatility, EFSA novel solvent guidance evolution, and enzymatic extraction technology adoption curves.
Underlying assumptions cover sustained FDA and EFSA health claim enforceability, with deviation risk concentrated in regulatory reinterpretation of extraction chemistry and raw material cost spikes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
RTD Protein Beverages Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
APAC Functional Food Ingredients Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Global Functional Mushrooms Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Fermented Protein Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Functional Soda Market