
 Kilned Malt Market | 2026-2036
Kilned Malt Market Size, Share, and Industry Trends Forecast 2026-2036
Kilned Malt Market Foresight
Specialty malt blending and custom roast profiles is fragmenting across mid-size craft brewers seeking proprietary flavor signatures. Rahr Malting Co. leverages its North American production footprint to supply consistent base malts at scale. Weyermann differentiates through heritage German roasting techniques that command premium positioning in export markets. Muntons Malted Ingredients Inc. anchors its competitive stance by supplying both brewing and food-grade malt extracts from UK facilities.
Kilned malt denotes barley germinated under controlled moisture and temperature, then dried in a kiln at 80–105°C to arrest enzymatic activity while developing color and flavor compounds through Maillard reactions; this thermal process yields diastatic malt for brewing conversion or roasted variants for color and taste contribution. Pilsner and Munich types dominate volume flows into lager and ale production globally, while Crystal malts capture expanding margin pools as craft distilleries adopt them for whiskey sweetness and body. The grade dimension shows Specialty and Premium tiers gaining traction as brewers pursue clean-label and provenance-marketed beers, though Standard grade still moves the bulk of commodity volume.
The EPA regulates kiln emissions under Clean Air Act provisions for particulate and volatile organic compound limits, while OSHA sets thermal process workplace exposure thresholds that shape facility design and automation investment. In Europe, ECHA REACH compliance governs chemical safety in malt processing aids and cleaning agents, with F-Gas Regulation increasingly relevant as maltsters transition kilning heat sources. Buyers and processors must monitor how carbon border adjustments and evolving malt specification standards reshape supplier qualification criteria across jurisdictions.
Market Dynamics
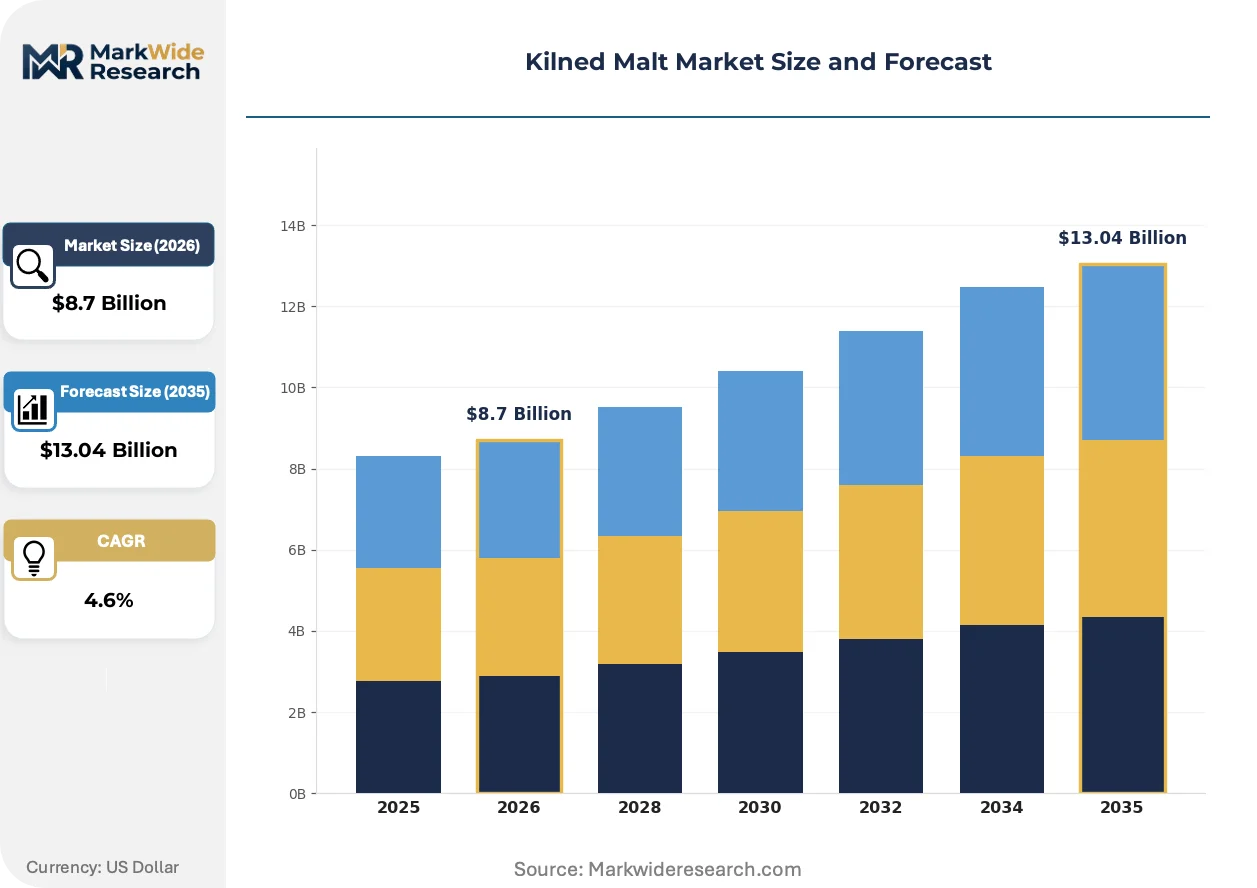
The EU Green Deal and national carbon border adjustments are forcing maltsters to reconfigure thermal infrastructure, redirecting capital toward heat-recovery kilns and biomass-fired systems that alter facility economics and supplier qualification thresholds.
Growth Catalysts
- REACH chemical safety mandates:ECHA compliance requirements are accelerating substitution of synthetic processing aids with enzyme-based alternatives, expanding certified-clean malt volumes.
- Whiskey distillation uptake:Crystal malt adoption by craft distilleries for sweetness and mouthfeel contribution is opening parallel demand channels beyond traditional brewing.
- Heat pump kilning:Electrified thermal systems are cutting Scope 2 emissions for maltsters serving carbon-accounting brewers in Germany and Denmark.
Market Restraints
- Barley input volatility:Climate-driven yield fluctuations in Australia and Canada are compressing margin predictability for non-integrated maltsters.
- Supply concentration:Premium Weyermann and Munich-type roasting capacity clusters in Bavaria, creating single-source vulnerability for specialty brewers.
- Natural gas dependency:Kiln operations remain tethered to fossil thermal inputs in regions lacking grid decarbonization, exposing processors to energy price spikes.
Strategic Opportunities
- India craft brewing emergence:BIS standards evolution and FSSAI licensing streamlining are lowering entry barriers for imported specialty malt distribution.
- Food-grade malt extract diversification:Bakery and confectionery applications are absorbing underutilized roasting capacity from brewing-seasonal facilities.
- EU F-Gas Regulation phase-down:Refrigerant constraints on traditional cooling systems are incentivizing ammonia-based heat pumps that simultaneously serve kilning and grain conditioning.
Industry Challenges
- Maillard reaction control expertise:Precision roasting for consistent flavor compound development requires scarce process engineering talent.
- Multi-jurisdiction certification lag:Organic and carbon-neutral malt claims face divergent verification timelines across USDA, EU organic, and private brewery audit schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kilned Malt Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pilsner, Munich, Vienna, Crystal End User: Brewery, Distillery, Snack Production, Food Industry Grade: Standard, Organic, Specialty, Premium Application: Beer Production, Whiskey Production, Baking, Confectionery |
| Companies Covered | Rahr Malting Co., Weyermann, Cargill Inc, Muntons Malted Ingredients Inc., Thomas Fawcett, Briess Malt & Ingredients Co., Bairds Malt, Gladfield Malting Company, Great Western Malting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kilned Malt Market Shifts & Advancements
Electrification of thermal processes and digitization of roast profiling are compressing the gap between craft-scale flexibility and industrial throughput, reshaping how flavor consistency is validated and priced.
Continuous inline moisture sensors coupled with AI-driven burner modulation are rendering obsolete batch-based kiln supervision that relied on operator sensory judgment. Mid-size craft maltsters in Belgium and the Netherlands are deploying these systems fastest. The shift is compressing skilled labor requirements while tightening specification bands for export-bound premium grades.
The EU F-Gas Regulation's staged refrigerant phase-down is compelling maltsters to abandon hydrofluorocarbon-based grain cooling in favor of ammonia or CO2 systems. Industrial consequence includes retrofitted facility downtime and capital reallocation. German and Czech processors with integrated malting and roasting operations face the steepest compliance timelines and are consolidating heat loops across process stages.
Brewery technical buyers are consolidating supplier rosters and demanding lot-level carbon intensity data, displacing spot-market purchasing for base malts. Direct contracting with named maltsters is replacing distributor intermediation for volume craft producers. This concentration is most visible in Scandinavian markets where brewery sustainability reporting obligations cascade upstream through supply agreements.
Kilned Malt Market Segmentation
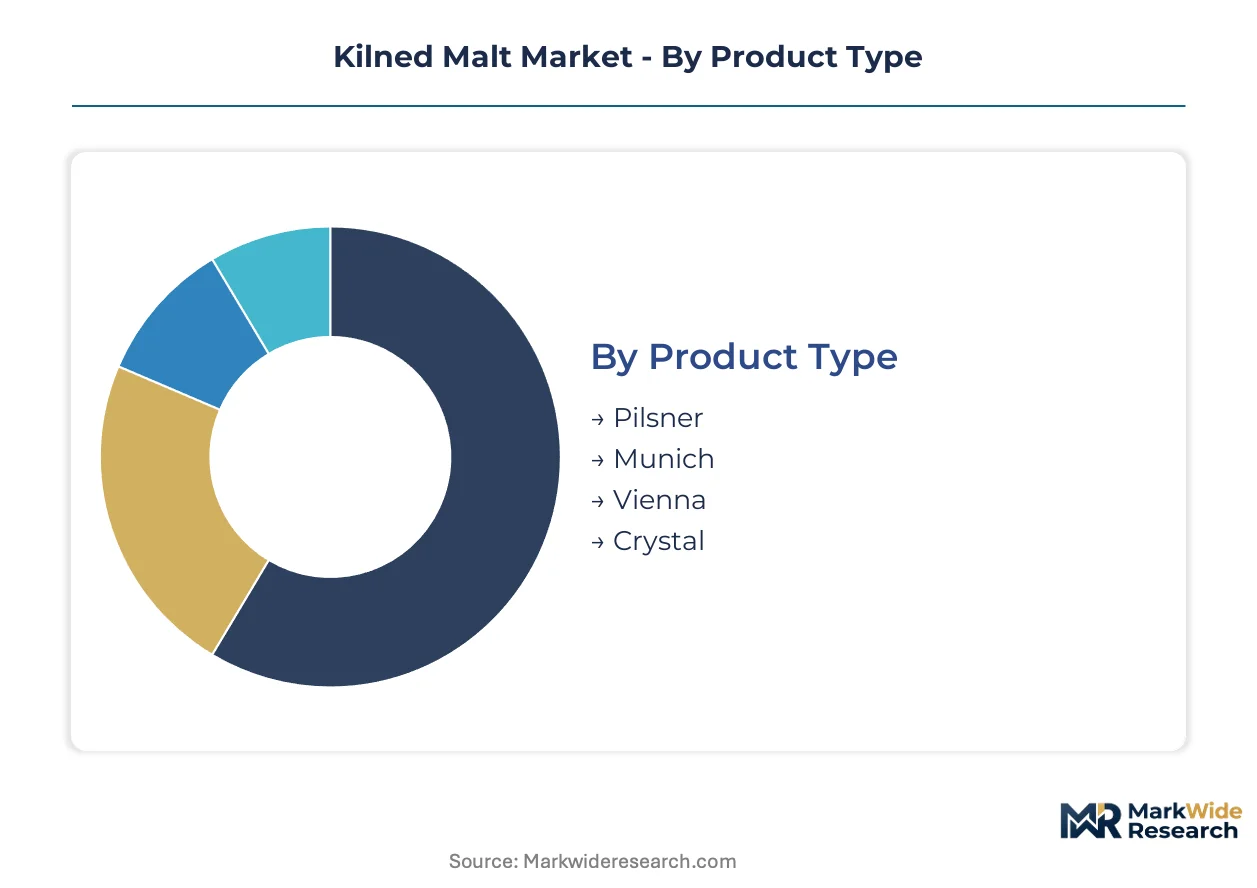
Kilned malt segmentation tracks how thermal processing intensity, enzymatic preservation, and color development map to distinct value pools across beverage and food manufacturing. Each dimension reveals divergent margin structures and supplier qualification thresholds.
Product Type:
Use-case spectrum spans delicate enzymatic base malts through heavily roasted specialty grains requiring precision Maillard control.
- Pilsner:Lightest kilning at 80-85°C preserves maximum diastatic power for starch conversion in lager brewing. German and Czech lager producers anchor procurement volumes, though craft pilsner revival in Denmark and the Netherlands is expanding spot demand.
- Crystal:Stewed then crystallized sugars create unfermentable dextrins that contribute body and caramel notes without additional roasting. American craft distilleries in Kentucky and Tennessee are adopting this for whiskey sweetness profiles, opening parallel channels beyond brewing.
- Munich:Higher kilning temperatures develop melanoidin complexity for bock and märzen styles. Bavarian maltsters dominate supply.
- Vienna:Moderate color malts bridging base and specialty functions for amber lagers. Austrian and German brewing traditions sustain niche demand.
The dominant share belongs to Pilsner, while Crystal is closing the gap fastest.
End User:
Customer type segmentation reflects divergent specification tolerances and contract structures across beverage alcohol and packaged food manufacturing.
- Brewery:Volume purchasers ranging from multinational lager producers to craft operators demanding lot-level traceability. German and Belgian breweries are consolidating supplier rosters and demanding carbon intensity data.
- Distillery:Whiskey producers seeking specific dextrin profiles for mouthfeel and fermentable sugar management. Scottish and American craft distillers are expanding specialty malt specifications.
- Snack Production:Malt extract and powder applications for flavor coating and browning agents. Seasonal demand patterns differ from beverage cycles.
- Food Industry:Bakery and confectionery applications utilizing malt extracts for natural sweetness and color. UK and German facilities absorb underutilized roasting capacity.
Brewery procurement commands volume leadership, though Distillery offtake is expanding most quickly.
Grade:
Certification tier segmentation separates commodity base malts from provenance-marked and carbon-accounted specialty grades commanding supplier premiums.
- Standard:Conventional barley sourcing with baseline quality specifications moves bulk commodity volume through distributor channels.
- Specialty:Custom roast profiles and blending protocols for proprietary flavor signatures. Mid-size craft brewers in Belgium and the Netherlands are fragmenting demand across bespoke specifications.
- Premium:Heritage roasting techniques and named provenance commanding export positioning. Weyermann's Bavarian operations anchor this tier.
- Organic:USDA and EU organic certification with divergent verification timelines creating multi-jurisdiction compliance lag.
Standard grade retains volume dominance, while Specialty is gaining share fastest.
Application:
Downstream process requirements dictate malt enzymatic activity, color contribution, and flavor compound specifications.
- Beer Production:Diastatic malt for starch conversion remains the foundational application with established supply chains.
- Whiskey Production:Crystal and roasted malts for sweetness and body contribution are expanding as craft distilleries proliferate.
- Baking:Malt extracts for browning and fermentation acceleration in artisan and industrial bread production.
- Confectionery:Malt-based flavoring and natural coloring applications in chocolate and candy manufacturing.
Beer Production anchors demand volume, while Whiskey Production shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty roasting capacity clusters in Bavaria and North American grain belts, creating geographic asymmetry between premium supply and craft demand expansion. Maltsters in Denmark and the Netherlands are deploying heat-recovery kilns fastest. Regulatory divergence across jurisdictions is fragmenting supplier qualification protocols.
Germany
Weyermann's Bamberg facility anchors heritage Munich and Weyermann malt production for export markets. ECHA REACH compliance mandates chemical safety documentation for processing aids, accelerating enzyme-based substitution. Bavarian maltsters are consolidating heat loops across malting and roasting stages to meet EU F-Gas Regulation timelines.
United States
Kentucky and Tennessee craft distilleries are expanding Crystal malt procurement for whiskey sweetness profiles. EPA Clean Air Act provisions govern kiln particulate emissions, shaping facility automation investment. North Dakota and Minnesota barley belts feed Rahr Malting Co.'s integrated operations serving lager producers.
United Kingdom
Muntons Malted Ingredients Inc. supplies brewing and food-grade extracts from Suffolk facilities. Divergent USDA and EU organic certification timelines create multi-jurisdiction compliance lag for export-bound malt. Scottish distillers are specifying roasted malts for mouthfeel complexity in single malt production.
Denmark
Carbon-accounting brewers in Copenhagen are demanding lot-level Scope 2 emissions data from malt suppliers. Heat pump kilning electrification is cutting fossil thermal dependence for maltsters serving Nordic markets. Danish craft pilsner revival is expanding spot demand for light-kilned base malts.
India
Maharashtra and Karnataka craft breweries are emerging as specialty malt importers as BIS standards evolve. FSSAI licensing streamlining is lowering entry barriers for European malt distribution. Mumbai and Bangalore brewing clusters are fragmenting procurement across bespoke roast specifications.
Kilned Malt Market Competitive Landscape
Heritage maltsters and integrated grain processors split the market between premium provenance and volume efficiency. Bavarian roasting specialists command export positioning through named techniques. North American integrated operators leverage captive barley supply for base malt consistency. Competitive moves center on thermal infrastructure retrofit and direct contracting displacement of distributor channels.
Among heritage European specialists, Weyermann exemplifies premium-tier positioning through geographic origin. Rahr Malting Co. and Muntons Malted Ingredients Inc. represent integrated processing archetypes spanning brewing and adjacent food applications. These three anchors illustrate how supplier qualification is diverging between carbon-accounting direct contracts and commodity distributor flows.
| Leading Market Players |
|---|
| Rahr Malting Co. |
| Weyermann |
| Cargill Inc |
| Muntons Malted Ingredients Inc. |
| Thomas Fawcett |
| Briess Malt & Ingredients Co. |
| Bairds Malt |
| Gladfield Malting Company |
| Great Western Malting |
| Others |
Supply & Pricing Matrix
Bavarian roasting capacity concentration around Weyermann's Bamberg facility anchors premium-tier margin pools in export markets, while commodity base malt flows through distributor channels at thinner spreads. This geographic asymmetry between heritage supply and dispersed craft demand creates divergent pricing power across the grade spectrum.
Pricing Analysis
ECHA REACH compliance dictates the pricing tier structure across the kilned malt market, with chemical safety documentation requirements widening spreads between certified-clean specialty grades and conventional base malts. Three-tier pricing stratifies across premium heritage techniques, custom roast profiles, and commodity standard grades. Cost compression in standard-tier base malts is intensifying because natural gas price volatility feeds directly into kiln operating economics. Multinational lager producers exhibit highest price sensitivity through volume contract negotiations, while craft distilleries in Kentucky and Tennessee show lowest sensitivity for Crystal malt specifications.
Supply Chain Analysis
Integrated maltsters including Rahr Malting Co. and Muntons Malted Ingredients Inc. hold dominant contract-manufacturing capacity across North Dakota, Minnesota, and Suffolk facilities. Geographic supply concentration clusters in Germany, the United Kingdom, and the United States, with barley input dependencies drawing from Australia, Canada, and domestic grain belts. Single-source vulnerability around Bavarian Munich-type roasting capacity exposes specialty brewers to disruption. Distribution runs through direct contracting displacement of distributor intermediation for volume craft producers, particularly in Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision Maillard reaction control expertise represents the critical capability gap constraining specialty grade expansion, with scarce process engineering talent limiting consistent flavor compound development at scale.
For Market Incumbents: Insulate heritage positioning by consolidating heat loops across malting and roasting stages to meet EU F-Gas Regulation timelines, while deepening backward integration into captive barley supply in North Dakota and Minnesota to buffer climate-driven yield volatility. Certification investment in dual USDA-EU organic pathways defends margin position against emerging clean-label competitors.
For New Entrants and Emerging Players: Establish a beachhead in India's Maharashtra and Karnataka craft brewing clusters, where BIS standards evolution and FSSAI licensing streamlining create the most penetrable import channel for European specialty malt distribution. Food-grade malt extract diversification into bakery and confectionery applications offers parallel white-space absorption of underutilized roasting capacity.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated processors with heat-recovery kiln retrofit completion and direct contracting relationships with carbon-accounting brewers, as these assets capture the structural shift away from spot-market purchasing. Heat pump kilning electrification penetration in Denmark and Germany signals the inflection indicator for Scope 2 emissions positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Recovery Kiln Retrofit | ECHA REACH and EU F-Gas Regulation compliance locks in supplier qualification for export markets. |
| Direct Contracting with Named Maltsters | Lot-level carbon intensity data satisfies brewery sustainability reporting obligations in Scandinavian markets. |
| Food-Grade Malt Extract Diversification | Bakery and confectionery applications absorb seasonal brewing capacity fluctuations in UK facilities. |
| Backward Integration into Barley Supply | Captive grain sourcing buffers margin predictability against climate-driven yield volatility in Australia and Canada. |
| AI-Driven Roast Profiling Deployment | Continuous inline moisture sensors compress skilled labor requirements while tightening specification bands for premium grades. |
Research Methodology
Desk research of trade customs data, ECHA regulatory filings, and industry association publications preceded structured interviews with maltster operations directors, craft brewery procurement managers, distillery technical buyers, and food-grade extract processors. Primary fieldwork across Bavarian roasting facilities, North American grain belts, and UK malting operations combined with secondary validation from SEC filings and EU emissions disclosures. Bottom-up volume triangulation against top-down value estimates anchored the analytical framework.
Assumptions held fixed include ECHA REACH compliance timelines, EU F-Gas Regulation phase-down schedules, and carbon border adjustment implementation across the projection horizon. Segmentation dimensions modeled encompass product type intensity, enzymatic preservation tiers, grade certification levels, and end-use application requirements. CAGRs derived from historical volume trajectories and pricing trend extrapolation, with whiskey distillation uptake and heat pump kilning electrification penetration as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, barley yield patterns, or craft brewery expansion rates would shift the trajectory. Quarterly review of kiln emissions compliance progress, carbon intensity disclosure adoption, and specialty malt import licensing in India is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sea Salt Market
Ingredients
Avocado Powder Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Omega 9 Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Global Natural Gum Market
Ingredients
Protein Ingredients Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
South America Spirulina Extract Market
Ingredients
Home Baking Ingredients Market
Ingredients
Italy Soy Protein Market
Ingredients
Alcohol Ingredients Market
Ingredients
Starch Market
Ingredients
Egg Albumin Protein Market