
 Europe CT Market | 2026-2036
Europe CT Market Size, Share, and Industry Trends Forecast 2026-2036
Europe CT Market Foresight
Imaging centers is redrawing the demand map as outpatient diagnostic networks expand capacity faster than traditional hospital radiology departments. Siemens Healthineers leverages its manufacturing footprint in Germany to sustain regional service density. GE Healthcare anchors its position through R&D intensity in spectral imaging architectures. Koninklijke Philips competes on integrated informatics that bridge scanner fleets with hospital IT ecosystems.
Computed tomography systems generate cross-sectional anatomical images through rotating X-ray tubes and detector arrays, with slice count determining temporal resolution and spatial fidelity; multidetector configurations now dominate new installations because they enable whole-organ perfusion studies in single breath-holds. Closed CT architectures lead installed base value due to shielding requirements and throughput economics in high-volume settings, while mobile CT units represent the fastest-growing configuration as health systems decentralize stroke and trauma triage to satellite locations. Oncology applications command the largest application share given staging protocols across lung, liver, and colorectal pathways, though cardiovascular CT angiography gains protocol share as calcium scoring and fractional flow reserve imaging expand reimbursement eligibility.
The EU Medical Device Regulation and CE marking framework administered by notified bodies reshape product registration timelines and clinical evidence requirements for new CT platform introductions. Germany's Federal Institute for Drugs and Medical Devices and France's ANSM enforce post-market surveillance obligations that elevate quality management system investments. Stakeholders must monitor reimbursement recalibration across national health technology assessment bodies as slice-count thresholds and radiation dose metrics enter purchasing criteria.
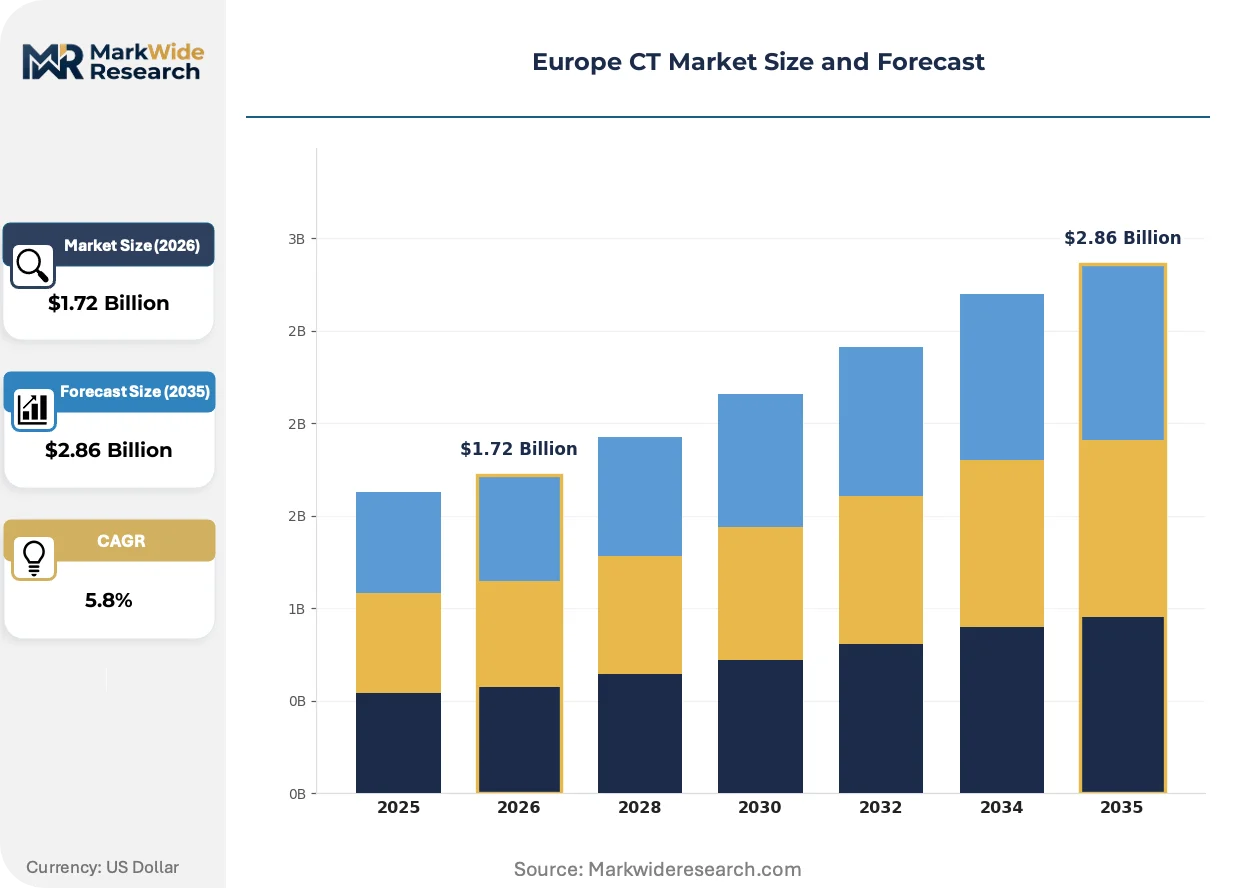
Market Dynamics
The EU Medical Device Regulation's clinical evidence requirements are compressing product registration timelines and forcing manufacturers to restructure quality management systems around notified body conformity assessments.
Growth Catalysts
- MDR Conformity Pathways:The EU Medical Device Regulation's stricter post-market surveillance obligations are accelerating hospital replacement cycles as facilities upgrade to compliant platforms.
- Outpatient Diagnostic Networks:Imaging centers across France and Germany are expanding capacity faster than traditional hospital radiology departments, redrawing demand geography.
- Spectral Imaging Architectures:Detector material advances are enabling quantitative tissue characterization that supports precision oncology staging protocols.
Market Restraints
- Helium Supply Concentration:Cryogen dependency for superconducting magnets creates vulnerability to Qatar and Russia supply disruptions.
- Notified Body Bottlenecks:CE marking queue delays under the MDR framework extend time-to-revenue for new platform introductions by 12-18 months.
- Interventional Radiology Substitution:MRI and ultrasound modalities capture share in musculoskeletal and pediatric applications where radiation dose concerns dominate purchasing criteria.
Strategic Opportunities
- Poland and Romania Infrastructure:Underpenetrated Central European markets present whitespace as EU structural funds modernize hospital capital equipment.
- Mobile Stroke Triage:Health system decentralization is creating demand for truck-mounted CT units that bypass fixed installation shielding requirements.
- AI-Enabled Dose Optimization:The EU AI Act's risk-based classification framework creates competitive differentiation for vendors with validated algorithmic reconstruction.
Industry Challenges
- Clinical Engineering Talent Scarcity:Specialized service technicians for high-slice systems command premium wages that compress aftermarket margin structures.
- Legacy PACS Integration:Hospital IT ecosystems require costly middleware development to bridge spectral imaging data formats with existing archive infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe CT Market |
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open CT, Closed CT, Mobile CT, Cone-Beam CT End User: Hospitals, Imaging Centers, Research Laboratories, Diagnostic Clinics Technology: 16-Slice, 32-Slice, 64-Slice, Multidetector Application: Oncology, Neurology, Cardiovascular, Orthopedic |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Hitachi Medical Systems, Fujifilm Holdings, Neusoft Medical Systems, United Imaging Healthcare, NeuroLogica, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe CT Market Shifts & Advancements
Photon-counting detector technology is restructuring competitive advantage around material discrimination capabilities, while regulatory pressure on radiation exposure is forcing reconstruction algorithm investments.
Photon-counting CT is displacing energy-integrating detectors in premium system configurations. Academic medical centers in Germany and the Netherlands are piloting installations for cardiac and pulmonary imaging. The technology is displacing conventional spectral methods by delivering simultaneous multi-energy data without dose penalty.
The EU Medical Device Regulation's clinical evaluation requirements now mandate post-market performance follow-up for all Class IIb and III devices. Manufacturers must maintain systematic procedures to collect and review experience from devices in use. French and Italian notified bodies are enforcing stricter scrutiny of software-as-a-medical-device components in reconstruction pipelines.
Hospital purchasing consortia are consolidating procurement authority across regional health systems. Independent imaging centers in Spain and Portugal now face standardized tender specifications that favor vendors with integrated informatics platforms. The shift is most visible in Catalonia and Lombardy where regional governments centralize capital equipment budgets.
Europe CT Market Segmentation
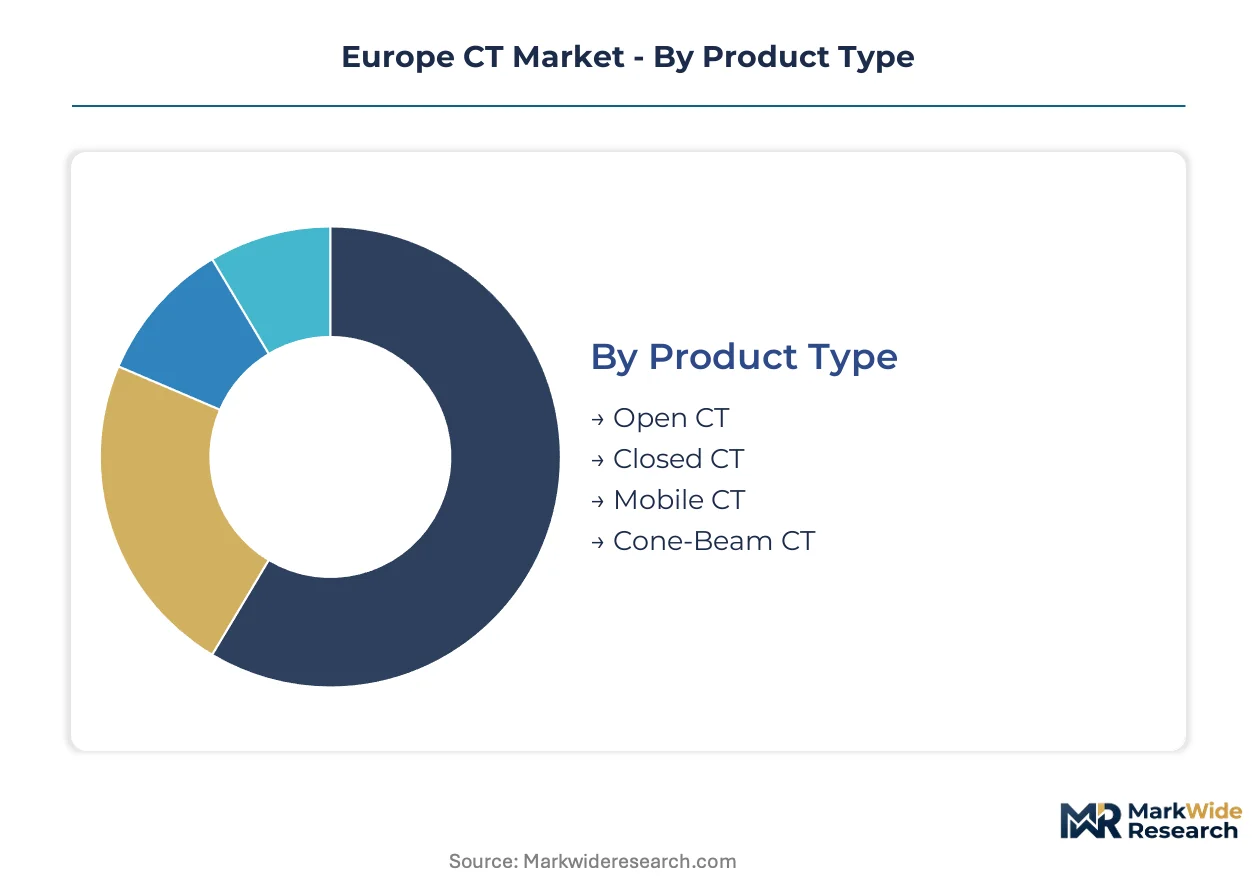
CT market segmentation reveals distinct procurement patterns across European health systems. Product architecture, slice capability, and site-of-care economics determine vendor selection criteria and reimbursement pathways differently in each category.
Product Type:
Closed CT systems dominate hospital procurement through centralized tender processes, while mobile configurations bypass fixed-installation capital cycles entirely. Distribution channels split between direct manufacturer relationships for premium systems and third-party leasing networks for mobile fleets.
- Closed CT:Fixed-room installations with integrated radiation shielding serve high-throughput hospital radiology departments. German university hospitals and French public hospital groups concentrate replacement demand here as MDR compliance deadlines approach.
- Mobile CT:Truck-mounted units with collapsible shielding enable decentralized stroke triage and trauma assessment. Spanish regional health authorities and Italian emergency networks are expanding mobile fleets fastest as pre-hospital care protocols evolve.
- Open CT:C-arm configurations with patient-accessible gantries accommodate bariatric and claustrophobic populations. Nordic hospital systems specify open architectures for specific patient demographics.
- Cone-Beam CT:Compact rotating-detector systems target dental and maxillofacial imaging with lower dose profiles. Private dental chains in Poland and Czech Republic drive outpatient adoption.
By volume, Closed CT leads. By growth pace, Mobile CT is ahead.
End User:
Customer type determines financing structure and service contract terms more than product specification. Hospital purchasing consortia negotiate multi-year service bundles, while independent imaging centers prioritize utilization-based payment models.
- Hospitals:Acute-care institutions with 24/7 emergency departments anchor installed base value through high-slice system procurement. German Klinikum networks and French CHU groups are consolidating radiology capital budgets regionally.
- Imaging Centers:Outpatient diagnostic facilities operate on volume-based reimbursement and demand rapid scan turnaround. Independent networks in Spain's Catalonia and Italy's Lombardy are expanding capacity faster than hospital departments.
- Diagnostic Clinics:Single-specialty facilities concentrate on musculoskeletal or cardiovascular applications with targeted protocol suites. Portuguese private clinic chains are upgrading from 16-slice to 64-slice platforms.
- Research Laboratories:Academic medical centers require spectral imaging capabilities for quantitative tissue studies. Dutch and Swedish university hospitals pilot photon-counting detector installations for translational research protocols.
Hospitals capture the largest revenue share. Imaging centers are climbing the fastest as outpatient networks expand.
Technology:
Slice-count tiers align with reimbursement thresholds and clinical indication breadth. National health technology assessment bodies in France and Germany are incorporating radiation dose metrics and temporal resolution standards into purchasing criteria.
- Multidetector:Configurations with 128+ simultaneous acquisition rows enable whole-organ perfusion and cardiac imaging without table movement. Academic medical centers in Germany and the Netherlands concentrate demand for cardiac CT angiography protocols.
- 64-Slice:Standard-of-care platforms balance throughput and capital cost for general hospital radiology. French hospital purchasing consortia specify 64-slice minimums for regional equipment standardization.
- 32-Slice:Mid-tier systems serve community hospitals and smaller diagnostic clinics with moderate scan volumes. Italian regional health systems deploy 32-slice units in provincial hospitals.
- 16-Slice:Entry-level configurations remain viable for specific orthopedic and lung screening applications. Eastern European markets with EU structural fund support are modernizing from single-slice to 16-slice platforms.
64-Slice holds the dominant installed position. Multidetector platforms are expanding most quickly as precision oncology protocols proliferate.
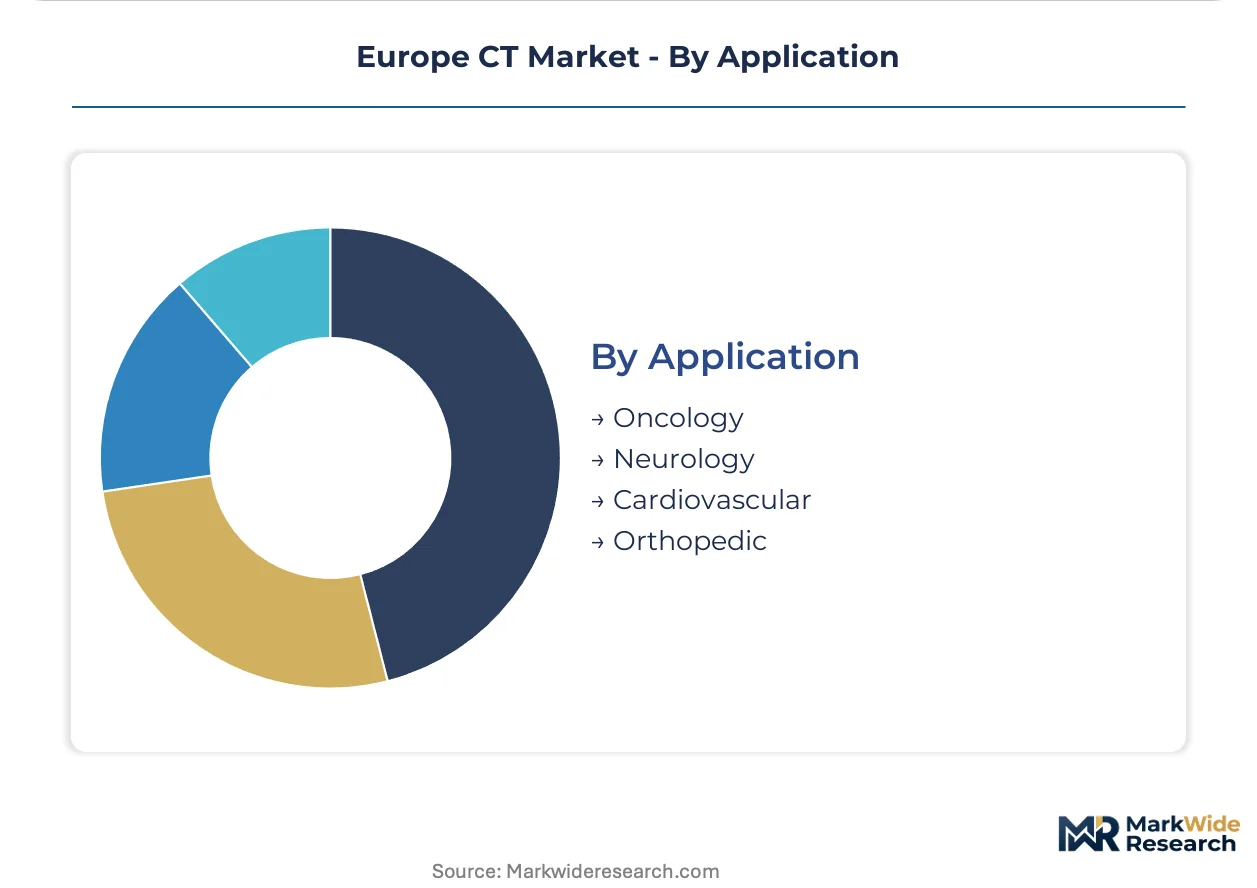
Application:
Clinical indication determines contrast protocol requirements, reconstruction algorithm specifications, and referral network integration needs. Oncology and cardiovascular pathways command premium system configurations due to staging protocol complexity.
- Oncology:Lung, liver, and colorectal cancer staging protocols demand thin-slice acquisition and multi-phase contrast enhancement. German oncology networks and French cancer centers drive spectral imaging adoption for tissue characterization.
- Cardiovascular:Coronary CT angiography, calcium scoring, and fractional flow reserve imaging require sub-millimeter spatial resolution and cardiac gating. Reimbursement expansion in Italy and Spain is accelerating 64-slice and multidetector procurement.
- Neurology:Stroke triage and perfusion imaging prioritize rapid acquisition and automated processing for treatment-window decisions. Mobile CT deployments target pre-hospital neurological assessment in regional emergency networks.
- Orthopedic:Trauma and joint replacement planning utilize lower-dose protocols with metal artifact reduction. Private orthopedic clinics in Switzerland and Austria specify cone-beam CT for extremity imaging.
Oncology generates the largest procedure volume. Cardiovascular applications are gaining share fastest as screening protocols expand reimbursement eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-slice CT systems to hospital networks across France, Italy, and the Netherlands, establishing a dominant trade corridor for premium radiology equipment.
Germany
University hospitals in Bavaria and Baden-Württemberg drive replacement demand for 128-slice and photon-counting platforms. The Federal Institute for Drugs and Medical Devices enforces stringent post-market surveillance under MDR requirements. Siemens Healthineers maintains manufacturing and R&D concentration in Erlangen and Forchheim, anchoring regional service density.
France
Public hospital groups and independent imaging centers in Île-de-France expand outpatient diagnostic capacity faster than traditional radiology departments. ANSM tightens scrutiny of software-as-a-medical-device components in reconstruction algorithms. The Paris-Saclay cluster concentrates academic medical center pilot programs for spectral imaging protocols.
Italy
Lombardy and Veneto regional health authorities centralize capital equipment budgets through consolidated procurement. Reimbursement expansion for coronary CT angiography and fractional flow reserve imaging accelerates multidetector adoption. Milan's Policlinico and Padua's university hospital anchor cardiac imaging protocol development.
Spain
Catalonia and Madrid deploy mobile CT fleets for decentralized stroke triage and pre-hospital emergency networks. Regional health authorities standardize tender specifications that favor vendors with integrated informatics platforms. Barcelona's Hospital Clínic pilots photon-counting installations for pulmonary imaging research.
Poland
EU structural funds modernize provincial hospitals from single-slice to 16-slice and 32-slice platforms. The national health technology assessment body incorporates radiation dose metrics into purchasing criteria. Warsaw and Kraków academic medical centers concentrate training programs for clinical engineering specialists.
Europe CT Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and service network density. The vendor base concentrates around three German-headquartered conglomerates with integrated healthcare portfolios, while Asian manufacturers penetrate on cost-optimized mid-tier configurations. Strategic archetypes include full-stack imaging conglomerates, component specialists in detector technology, and informatics-integrated platform vendors. M&A activity targets AI reconstruction software firms, and regional service partnerships expand coverage in underpenetrated Central European markets.
Within the full-stack conglomerate tier, Siemens Healthineers and GE Healthcare exemplify vertically integrated positioning through captive manufacturing and direct service organizations. Koninklijke Philips occupies a position bridging scanner hardware with enterprise informatics integration. These three anchors represent divergent strategic bets: German manufacturing proximity, American R&D intensity in spectral architectures, and Dutch software-ecosystem convergence.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Hitachi Medical Systems |
| Fujifilm Holdings |
| Neusoft Medical Systems |
| United Imaging Healthcare |
| NeuroLogica |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for photon-counting detector arrays concentrate pricing power with German and Dutch component specialists, compressing margins for system integrators while amplifying premium-tier markups for vendors with captive detector supply. This inventory bandwidth shapes how procurement consortia negotiate bundled service contracts across Western European hospital networks.
Pricing Analysis
Photon-counting platforms command substantial premiums over 128-slice energy-integrating systems, which themselves price above legacy 64-slice configurations nearing replacement end-of-life. Three-tier pricing structure across premium, standard, and economy levels stratifies by slice count and detector generation, with CE marking tier and spectral imaging certification driving additional differentiation. Cost compression in mid-tier configurations is intensifying because Asian manufacturers penetrate on cost-optimized platforms. Independent imaging centers exhibit highest price sensitivity due to volume-based reimbursement pressures, while German university hospitals prioritize performance specifications over capital cost.
Supply Chain Analysis
Helium liquefaction capacity concentrated in Qatar and Russia creates chokepoint vulnerability for superconducting magnet cooling systems essential to CT gantry stability. Manufacturing draws from Germany for precision mechanical assemblies, Japan for scintillator crystal production, and the Netherlands for photon-counting detector substrates. Single-source vulnerability in rare earth element processing for detector materials exposes vendors to export restriction risk. Distribution runs through direct manufacturer relationships for premium hospital installations and third-party leasing networks for mobile CT fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe CT Market represents a high-growth disruption as photon-counting detector technology restructures competitive advantage around material discrimination capabilities and MDR compliance deadlines force accelerated replacement cycles.
For Market Incumbents: Secure backward integration into photon-counting detector manufacturing to defend margin structures against Asian cost-optimized entrants. Anchor service density through regional clinical engineering training programs in Poland and Romania, addressing talent scarcity that threatens aftermarket profitability. For New Entrants and Emerging Players: Post-market surveillance compliance outsourcing represents a service-layer gap where incumbents under-serve smaller imaging centers facing MDR quality management burdens. Target independent diagnostic networks in Spain's Catalonia and Portugal with informatics-integrated platforms that bypass legacy PACS integration costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across photon-counting platform development, favoring scaled conglomerates with captive R&D infrastructure. Five-to-ten year viability hinges on spectral imaging patent portfolios and AI reconstruction algorithm validation. Acquisition candidates include AI-enabled dose optimization software specialists and regional service providers in Central Europe. The signal to watch is notified body CE marking queue lengths as a proxy for regulatory friction costs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity accelerates hospital replacement demand ahead of surveillance deadlines. |
| Hospital System Partnership | Consolidated procurement in Lombardy and Catalonia favors vendors with integrated informatics. |
| Software Companion Development | AI-enabled reconstruction algorithms differentiate offerings under EU AI Act risk classification. |
| Reimbursement Strategy | Cardiovascular CT angiography expansion in Italy and Spain opens multidetector procurement channels. |
| Geographic Manufacturing Footprint | German production proximity sustains service density for Western European hospital networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and imaging center operations executives. Secondary validation incorporated EU Medical Device Regulation filings, notified body conformity assessment records, hospital procurement databases, and national health technology assessment body reimbursement guidelines. Bottom-up installed base modeling triangulated against top-down market sizing across product architecture, slice capability, and site-of-care segments.
Across the analysis window, volume and value outputs reflect segmentation by product type, technology tier, end-user category, and clinical application, with CAGRs derived from replacement cycle timing and penetration rate trajectories in underpenetrated Central European markets. Forecast inputs incorporated MDR compliance deadline schedules, EU structural fund disbursement patterns for hospital modernization, and photon-counting detector adoption curves in academic medical centers.
Forecasts assume regulatory continuity in EU MDR and CE marking frameworks; material policy shifts in notified body designation or AI Act enforcement would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Hyperspectral Imaging Camera Market
Imaging
North America Digital Camera Market
Imaging
APAC Image Sensors Market
Imaging
Global Automotive Imaging Market
Imaging
Wide Field Imaging Devices Market
Imaging
Camera Stabilizer Market
Imaging
Global Digital Binoculars Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Digital Image Processing Market
Imaging
Cinematographic Camera Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Latin America IP Camera Market
Imaging
Industrial Computed Tomography Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Video Processing Solutions Market
Imaging
Automotive Compact Camera Module Market