
 Fiducial Markers Market | 2026-2036
Fiducial Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Fiducial Markers Market Intelligence
Oncology clinic procurement is realigning toward precision radiotherapy workflows that demand submillimeter localization accuracy. IZI Medical Products sustains technology leadership in radiopaque gel markers for soft tissue tracking. Medtronic leverages its interventional oncology platform to extend fiducial placement system adoption across hospital networks. Naslund Medical AB specializes in biodegradable marker formulations that reduce long-term implant complications.
Fiducial markers are implantable or surface-mounted reference points manufactured from gold, polymer, or biodegradable substrates, engineered to exhibit high radiopacity under CT, MRI, or X-ray fluoroscopy for spatial registration and target localization. Tumor markers dominate current revenue pools due to entrenched prostate and lung cancer protocols, while biodegradable materials represent the fastest-expanding material segment as clinicians prioritize resorbable implants that eliminate secondary retrieval procedures. Imaging markers anchor diagnostic imaging applications where multimodal visibility across modalities determines product selection criteria.
FDA 510(k) clearance requirements govern marker biocompatibility and radiopacity performance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence standards for implantable fiducials sold in Europe. ISO 10993 biocompatibility testing protocols and ASTM F2052 MRI safety standards further constrain material selection and manufacturing processes. Stakeholders must monitor evolving reimbursement codes for image-guided radiation therapy procedures and biodegradable implant categories to anticipate demand shifts.
Market Dynamics
Precision radiotherapy workflows demand submillimeter localization accuracy, forcing oncology departments to standardize fiducial-based image guidance across prostate, lung, and pancreatic cancer protocols. This accuracy imperative compresses procurement cycles and elevates biocompatibility requirements above cost considerations.
Growth Catalysts
- Image-Guided Radiation Therapy (IGRT) Protocols:Hospital systems with proton and cyberknife capabilities mandate fiducial implantation for motion tracking during fractionated treatment.
- FDA 510(k) Pathway Clarity:Premarket notification requirements for implantable radiopaque markers provide predictable regulatory timelines that accelerate product development cycles in the United States.
- Biodegradable Material Science:Resorbable polymer formulations eliminate secondary retrieval procedures, expanding addressable cases to patients contraindicated for permanent implants.
Market Restraints
- Gold Price Volatility:Conventional gold seed markers expose manufacturers to commodity input cost swings that compress margin stability.
- Supply Concentration in Precision Manufacturing:Specialized radiopaque gel production clusters in select North American medical device corridors create geographic dependency risk.
- EU MDR Clinical Evidence Burden:Strengthened post-market surveillance requirements for implantable fiducials extend certification timelines and elevate documentation costs for European market access.
Strategic Opportunities
- Underpenetrated Asia-Pacific Oncology Networks:Japan and South Korea proton therapy installations are expanding faster than fiducial placement training infrastructure, creating first-mover service integration potential.
- Pancreatic and Liver Cancer Protocol Expansion:Abdominal tumor tracking applications remain protocol-immature relative to prostate and lung, offering white space for indication-specific marker geometries.
- Carbon Ion Therapy Integration:Heavy particle treatment centers in Germany and Japan require specialized non-ferromagnetic markers that existing gold seeds cannot satisfy.
Industry Challenges
- Interventional Radiology Training Bottlenecks:Percutaneous fiducial placement under CT or ultrasound guidance demands specialized skills that residency programs address inconsistently.
- Cross-Modality Visibility Engineering:Optimizing radiopacity across CT, MRI, and X-ray fluoroscopy without compromising biocompatibility extends R&D iteration cycles.
- Legacy PACS Integration Friction:Marker localization software must interface with hospital imaging archives that vary in DICOM compliance and vendor architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiducial Markers Market |
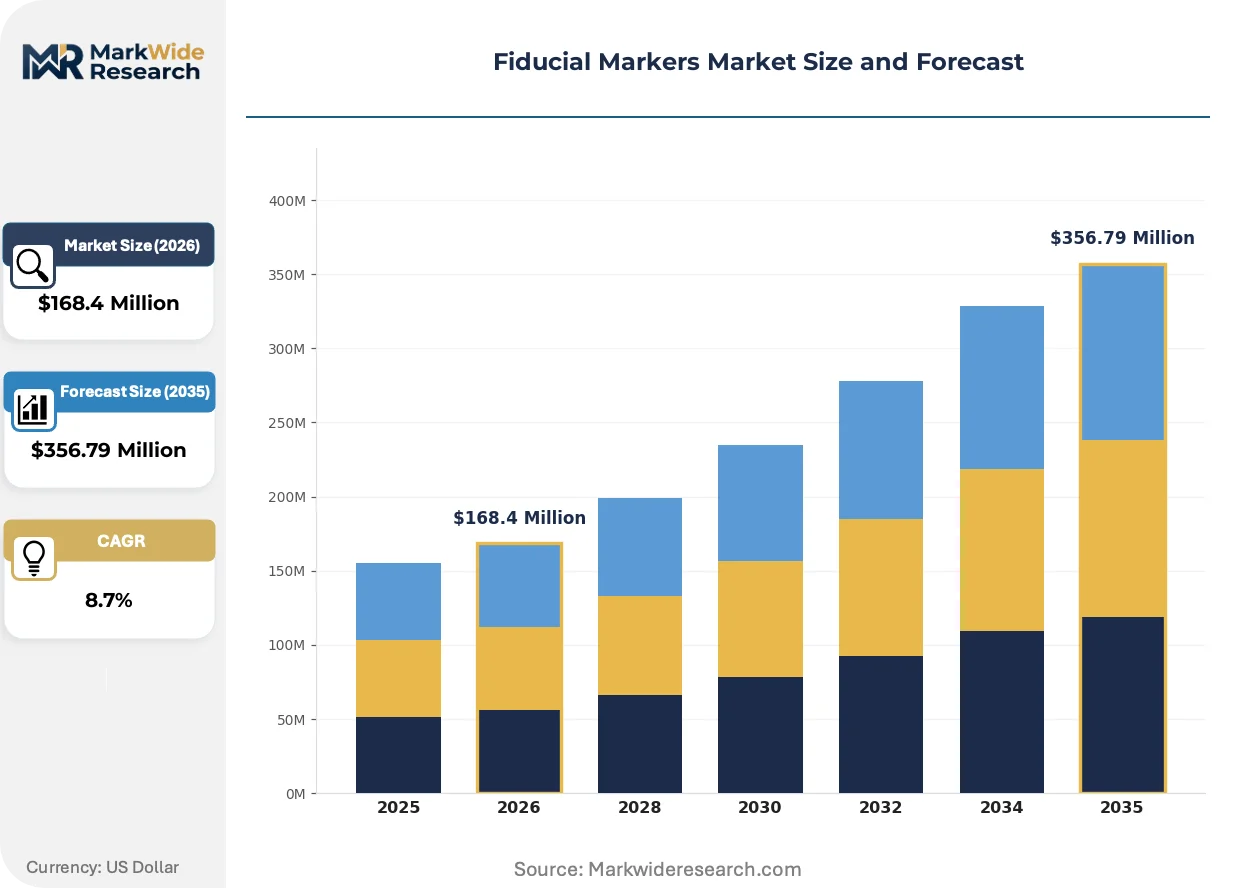
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $356.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tumor Markers, Surgical Markers, Imaging Markers, Biopsy Markers Application: Radiation Therapy, Image-Guided Surgery, Diagnostic Imaging, Research Studies End User: Hospitals, Diagnostic Centers, Research Institutions, Oncology Clinics Material: Plastic, Metal, Biodegradable Materials, Polymer |
| Companies Covered | CIVCO Radiotherapy, IZI Medical Products, Boston Scientific Corporation, Naslund Medical AB, Medtronic, Nanovi A/S, Eckert & Ziegler, IBA Dosimetry GmbH, QlRad Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiducial Markers Market Strategic Shifts & Innovations
Material science convergence with regulatory science is compressing the gap between implantable device approval and clinical protocol adoption. Three distinct vectors are restructuring how fiducial markers are engineered, validated, and procured.
Polyglycolic acid-lactide copolymer formulations are electrifying the biodegradable marker segment by providing complete resorption within 12-18 months without inflammatory residue. Academic medical centers in the United States and Germany are piloting these implants for pancreatic cancer cases where permanent foreign bodies complicate salvage surgery. The technology is electrifying competitive positioning by enabling manufacturers to bundle placement systems with resorbable markers as single-procedure kits.
EU Medical Device Regulation (MDR) Annex XVI classification expansion is redefining clinical evidence requirements for fiducials marketed across European Economic Area member states. Manufacturers must now submit post-market clinical follow-up data for implantable radiopaque devices, elevating documentation burdens above pre-2021 levels. Small and mid-cap marker specialists are responding by consolidating notified body relationships and pooling clinical data across product families.
Hospital procurement committees are consolidating vendor relationships for radiation oncology consumables, unbundling marker purchases from linear accelerator service contracts. Integrated delivery networks in Texas, California, and Florida are negotiating multi-year supply agreements that lock in volume commitments for biodegradable and permanent marker categories simultaneously. This concentration is most visible in United States proton therapy centers where capital equipment financing ties directly to consumable procurement terms.
Fiducial Markers Market Segmentation
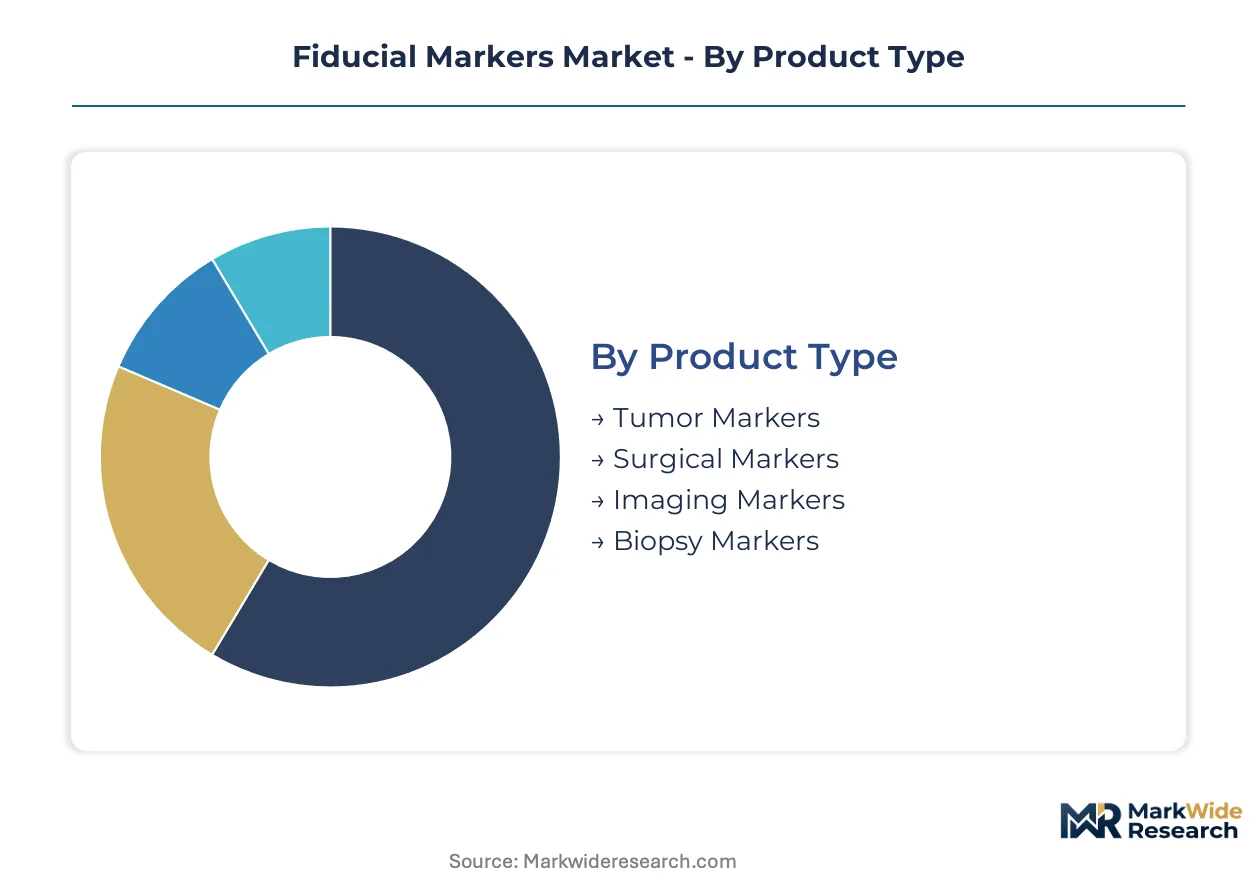
Fiducial marker procurement varies sharply by clinical integration depth. Standalone implantable markers for radiation oncology command premium positioning, while embedded surgical navigation systems bundle markers as disposable components. Understanding these structural divides clarifies where pricing power concentrates versus where volume scales.
Product Type:
Tumor markers function as standalone implants requiring percutaneous placement, while surgical and imaging markers embed into broader navigation systems with different procurement economics.
- Tumor Markers:Gold seeds and radiopaque gel implants designed for soft tissue tracking in prostate, lung, and pancreatic cancer protocols. Demand clusters in United States proton therapy centers and German university hospitals where CyberKnife and MR-Linac installations mandate submillimeter localization accuracy for fractionated treatment.
- Imaging Markers:Surface-mounted or ingestible reference points engineered for multimodal visibility across CT, MRI, and fluoroscopy without surgical implantation. Adoption concentrates in diagnostic imaging departments within large integrated delivery networks that prioritize cross-modality registration for complex abdominal cases.
- Surgical Markers:Stereotactic navigation aids integrated into neurosurgical and orthopedic tracking systems, typically procured as bundled consumables with navigation platform service contracts.
- Biopsy Markers:Tissue localization clips deployed during image-guided biopsy procedures to mark suspicious lesions for subsequent surgical excision, with demand tied to breast imaging and interventional radiology procedure volumes.
Volume placements concentrate in tumor markers; the faster expansion belongs to imaging markers.
Application:
Clinical workflow integration determines whether markers are reimbursed as standalone procedures or absorbed into bundled payments, reshaping vendor go-to-market strategies.
- Radiation Therapy:Image-guided radiation therapy (IGRT) mandates fiducial implantation for motion tracking during fractionated treatment of mobile tumors. United States hospital systems with proton and CyberKnife capabilities standardize marker-based protocols, while Japan's expanding heavy particle centers drive carbon-ion-compatible marker demand.
- Image-Guided Surgery:Real-time navigation systems for neurosurgery and spine procedures integrate markers as disposable reference arrays. German and Swedish academic medical centers lead protocol adoption for complex cranial base resections.
- Diagnostic Imaging:Multimodal registration applications in abdominal and pelvic imaging use markers to align sequential scans across modalities.
- Research Studies:Preclinical and clinical trial applications for novel imaging agents and therapeutic interventions.
Revenue tilts toward radiation therapy; research studies are climbing the fastest as trial sponsors mandate standardized localization protocols.
End User:
Procurement authority and reimbursement pathways diverge between capital-equipment-owning institutions and procedure-focused outpatient settings.
- Hospitals:Comprehensive cancer centers with in-house radiation oncology and interventional radiology departments control the majority of marker procurement through integrated delivery network supply agreements. Texas and California health systems negotiate multi-year contracts spanning biodegradable and permanent marker categories.
- Oncology Clinics:Freestanding radiation therapy centers with proton and stereotactic capabilities purchase markers through group purchasing organizations or direct manufacturer relationships.
- Diagnostic Centers:Outpatient imaging facilities without surgical or radiation therapy services.
- Research Institutions:Academic medical centers and contract research organizations procuring markers for investigator-initiated trials and sponsored studies.
Procurement volume aggregates in hospitals; oncology clinics are gaining share fastest as proton therapy installations proliferate outside hospital campuses.
Material:
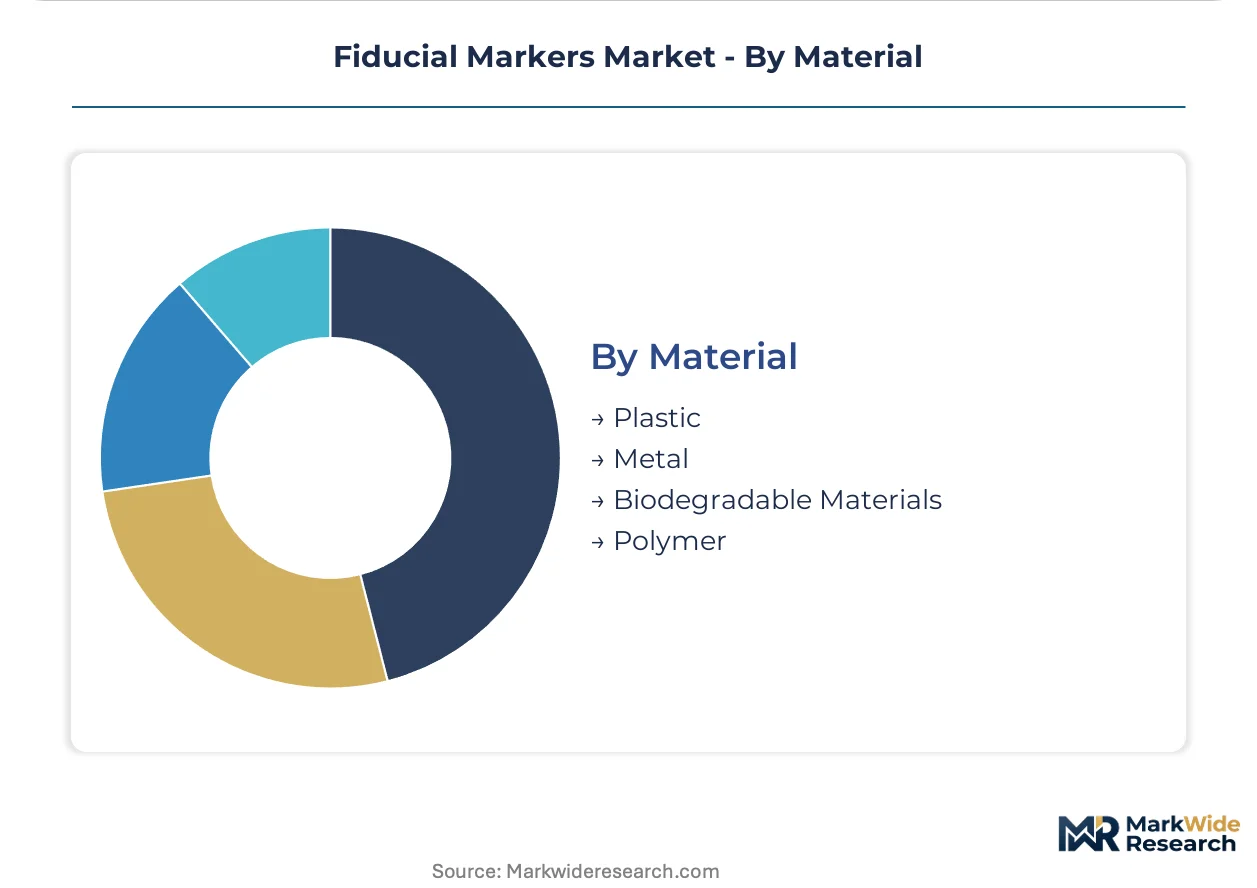
Material selection trades off radiopacity performance, biocompatibility certification burden, and retrieval economics, with permanent implants facing displacement from resorbable alternatives.
- Biodegradable Materials:Polyglycolic acid-lactide copolymers engineered for complete resorption within 12-18 months without inflammatory residue. United States and German academic centers pilot these for pancreatic cancer cases where permanent foreign bodies complicate salvage surgery, eliminating secondary retrieval procedures for patients contraindicated for permanent implants.
- Metal:Gold and platinum-iridium alloys providing maximal radiopacity under fluoroscopy and CT, with entrenched use in prostate brachytherapy and lung cancer protocols despite commodity price volatility.
- Polymer:Non-resorbable radiopaque plastics for imaging applications where permanent implantation is acceptable and metal artifacts must be avoided.
- Plastic:Standard non-radiopaque polymers for research and non-clinical applications.
Metal retains volume dominance; biodegradable materials show the steepest expansion trajectory as EU MDR and FDA 510(k) pathways mature for resorbable implant categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device manufacturing zones in the United States and Germany concentrate fiducial marker production, with tax incentives for radiopaque implant manufacturing accelerating facility clustering in designated health technology corridors.
United States
Proton therapy centers in Texas and Florida drive marker demand for motion-tracking protocols in fractionated treatment. FDA 510(k) premarket notification requirements provide predictable regulatory timelines that accelerate product development cycles. Baltimore-based IZI Medical Products anchors domestic radiopaque gel marker production, supplying integrated delivery networks across the Southeast and Southwest.
Germany
University hospitals in Munich and Heidelberg mandate submillimeter localization accuracy for CyberKnife and MR-Linac installations. EU Medical Device Regulation Annex XVI classification strengthens clinical evidence requirements for implantable radiopaque devices. The Baden-Württemberg medical technology corridor clusters precision manufacturing for carbon-ion-compatible marker development serving heavy particle therapy centers.
Japan
National Cancer Center hospitals in Tokyo and Kobe expand proton and heavy ion therapy capacity faster than fiducial placement training infrastructure. PMDA marketing approval pathways for implantable radiopaque devices align with international standards while maintaining national pharmacovigilance requirements. The Kansai region concentrates carbon ion therapy installations requiring specialized non-ferromagnetic markers.
South Korea
National Cancer Center Korea in Goyang and Samsung Medical Center in Seoul standardize image-guided radiation therapy protocols across major metropolitan hospitals. MFDS medical device registration requirements govern biocompatibility and radiopacity performance for implantable markers. The Seoul Capital Area clusters proton therapy installations driving procurement of biodegradable marker formulations for pancreatic cancer protocols.
Sweden
Karolinska University Hospital and Uppsala University Hospital pioneer MR-guided radiation therapy workflows demanding multimodal marker visibility. Swedish Medical Products Agency regulations enforce ISO 10993 biocompatibility testing protocols for implantable fiducials. The Stockholm-Uppsala life science corridor concentrates surgical navigation research driving demand for stereotactic tracking markers in neurosurgical applications.
Fiducial Markers Market Key Industry Players
Top-tier vendors anchor integrated radiation oncology platforms, while mid-cap specialists concentrate on biodegradable formulations and placement system innovation. The vendor base stratifies across three tiers: diversified medical technology conglomerates with interventional oncology portfolios, dedicated radiotherapy consumable manufacturers, and emerging resorbable implant specialists. Strategic archetypes include platform-integrated suppliers bundling markers with linear accelerator service contracts, biodegradable material science pioneers, and precision interventional device engineers. Competitive moves concentrate on multi-year supply agreement negotiations with integrated delivery networks and regulatory pathway consolidation for resorbable implant categories.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation occupy positions anchored by interventional oncology platform breadth. IZI Medical Products exemplifies the dedicated radiotherapy consumable archetype through sustained technology leadership in radiopaque gel formulations. Naslund Medical AB represents the biodegradable material science specialist tier with resorbable polymer expertise. These three companies collectively illustrate the competitive spectrum from platform-scale supply relationships to indication-specific material innovation.
| Leading Market Players |
|---|
| CIVCO Radiotherapy |
| IZI Medical Products |
| Boston Scientific Corporation |
| Naslund Medical AB |
| Medtronic |
| Nanovi A/S |
| Eckert & Ziegler |
| IBA Dosimetry GmbH |
| QlRad Inc. |
| Others |
Cost & Logistics Intelligence
Biodegradable polymer formulation advances are compressing production cost curves while concentrating manufacturing expertise in FDA-registered medical device corridors. This dual shift simultaneously reduces per-unit material costs and elevates barriers for suppliers lacking ISO 13485 certification and radiopaque gel processing capabilities.
Pricing Analysis
Short lead-time premiums command pricing advantages for biodegradable marker kits stocked in United States proton therapy centers, while spot inventory of conventional gold seeds trades at discounts. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and placement system bundling. Pricing pressure stems from hospital procurement committee consolidation negotiating multi-year supply agreements. Oncology clinics with proton capabilities show least price sensitivity; diagnostic imaging centers without radiation therapy services exhibit highest.
Supply Chain Analysis
Reverse-logistics flows for explanted gold seeds are negligible, yet biodegradable marker resorption eliminates retrieval entirely, simplifying downstream handling. Manufacturing concentrates in the United States, Germany, and Japan, drawing from gold bullion, polyglycolic acid-lactide copolymers, and radiopaque additive feedstocks. Single-source vulnerability in precision gel production clusters creates geographic dependency risk. Distribution runs through integrated delivery network contracts and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fiducial Markers Market functions as a cost-of-compliance arena where EU MDR Annex XVI classification and FDA 510(k) documentation burdens erect defensive moats. Players with established notified body relationships and biocompatibility testing infrastructure capture disproportionate procurement volume.
For Market Incumbents: Acquire biodegradable polymer formulation IP to anchor resorbable marker portfolios against gold price volatility. Consolidate placement system technology through targeted capability additions in Baltimore and Baden-Württemberg manufacturing corridors. Fortify multi-year supply agreements with Texas and California integrated delivery networks before procurement committee windows close. For New Entrants and Emerging Players: The premium-to-economy price gap in pancreatic cancer protocols offers white-space entry for indication-specific biodegradable geometries. Target South Korea's Seoul Capital Area proton installations where fiducial placement training infrastructure lags equipment deployment. Pursue carbon-ion-compatible marker development for Japan's Kansi region heavy particle centers as differentiated go-to-market anchor. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated radiation oncology suppliers with biodegradable material science capabilities. Long-term viability favors players with simultaneous FDA 510(k) and EU MDR certification for resorbable implant categories. Monitor PMDA marketing approval timelines for Japanese proton therapy centers as inflection signal for Asia-Pacific demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for biodegradable markers in United States proton centers. |
| CE Marking Pathway | Enables European Economic Area distribution under strengthened MDR clinical evidence standards. |
| Hospital System Partnership | Locks multi-year supply commitments with Texas and California integrated delivery networks. |
| Software Companion Development | Integrates marker localization algorithms with CyberKnife and MR-Linac treatment planning systems. |
| Reimbursement Strategy | Secures favorable coding for image-guided radiation therapy procedures with biodegradable marker categories. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases, complemented by interviews with radiation oncologists, interventional radiologists, biomedical engineers, and GPO contracts managers. Secondary sources included CMS Medicare reimbursement data, proton therapy center installation records, and ISO 10993 biocompatibility testing protocols. Bottom-up demand modeling and top-down market sizing triangulated volume estimates.
Cross-referencing historical adoption curves against expert panel inputs anchored projection parameters across the analysis window. Segmentation dimensions modeled include product type, application, end user, material, and regional regulatory cluster. CAGRs derived from weighted average of technology diffusion rates and capital equipment installation pipelines, incorporating proton therapy center expansion timelines and biodegradable material science maturation curves.
Inputs from FDA premarket notification databases and EU notified body certificates were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume forecasts. Practitioners should monitor PMDA approval timelines, EU MDR post-market clinical follow-up requirements, and gold commodity price movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Global Automotive Imaging Market
Imaging
Thermal Camera Market
Imaging
Micro Computed Tomography Market
Imaging
Digital Imaging Market
Imaging
Vintage Cameras Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Global Camera Module Market
Imaging
Photography Equipment Market
Imaging
Machine Vision Camera Market
Imaging
Machine Vision System and Services Market
Imaging
Mobile Imaging Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
PET Imaging Systems Market
Imaging
Multi Camera System Market
Imaging
Digital Microscope Market