
 Medical Textiles Market | 2026-2036
Medical Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Textiles Market Intelligence
The distribution channel through large group purchasing organizations is narrowing as major hospital networks pursue direct sourcing agreements. This shift benefits manufacturers with strong direct sales capabilities. Medtronic leverages its extensive portfolio to secure integrated contracts with healthcare providers. Meanwhile, DuPont differentiates through its material science innovations in proprietary fibers, supplying multiple downstream producers.
Medical textiles are specialized fabrics designed for healthcare applications, requiring biocompatibility and specific functional properties like antimicrobial activity or absorbency. These materials are engineered for uses ranging from infection control to tissue regeneration. Non-woven fabrics dominate the market due to their cost-effectiveness in disposable items like surgical gowns and drapes. In contrast, implantable textiles, including grafts, represent a high-margin niche driven by complex manufacturing and stringent regulatory requirements.
Market access hinges on compliance with stringent medical device regulations. Manufacturers must navigate frameworks such as the US FDA's premarket approval process, Europe's Medical Device Regulation (MDR), and China's NMPA standards. These regulations dictate material sourcing, testing protocols, and labeling requirements. Future success will depend on a company's ability to manage evolving standards for material traceability and sustainability across its supply chain.
Market Dynamics
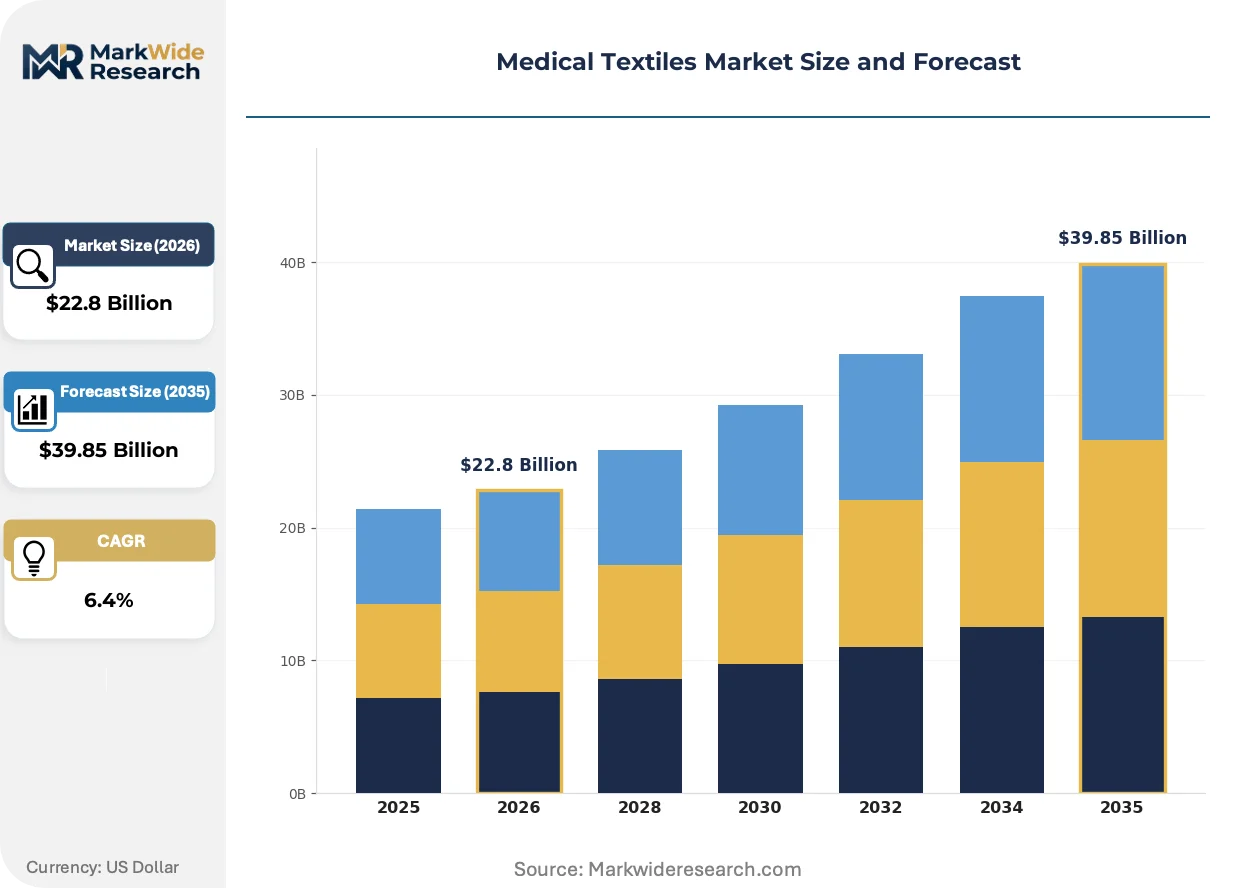
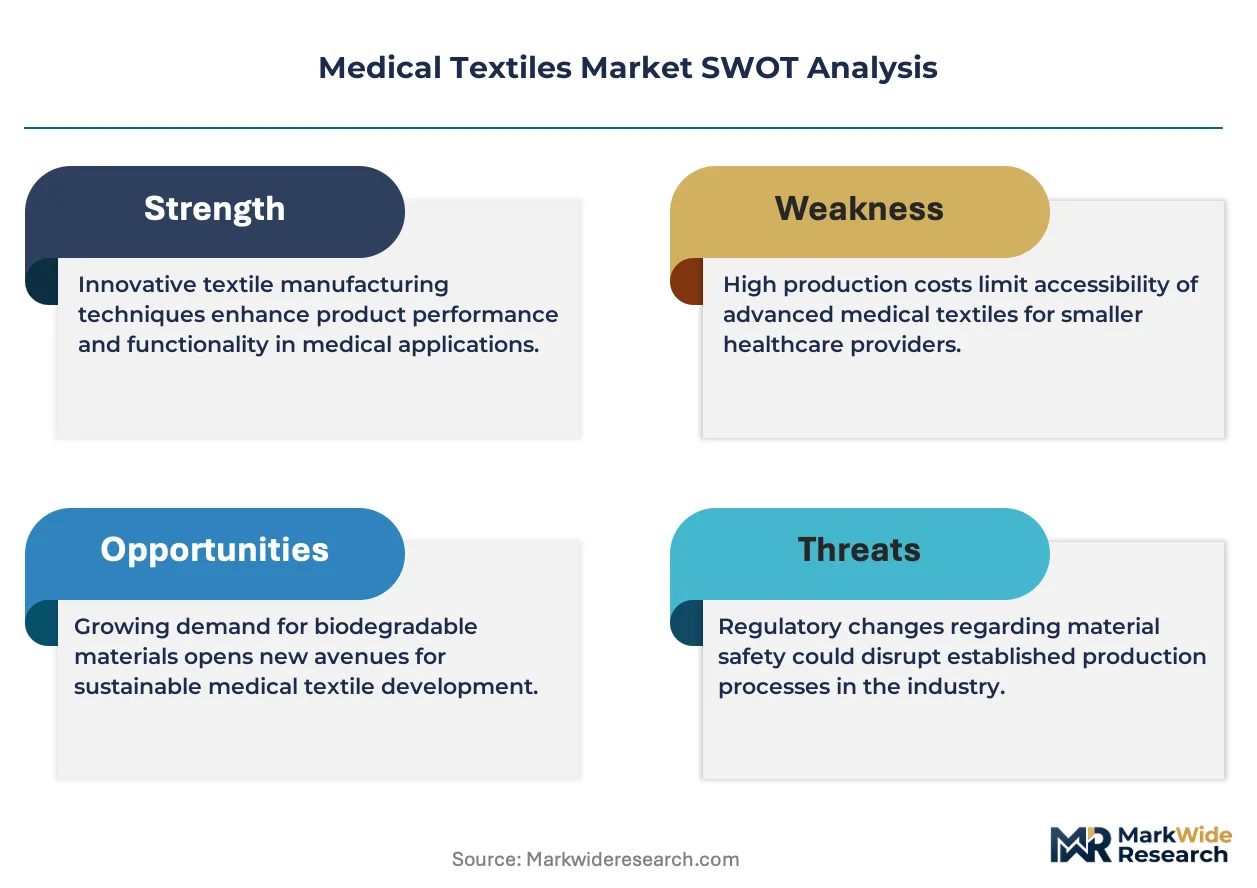
The central dynamic in the medical textiles market is the pressure to innovate materials with advanced therapeutic properties while navigating increasingly stringent and costly global regulatory frameworks. This force favors incumbent manufacturers who can absorb the high costs of compliance and R&D for next-generation biocompatible and antimicrobial fabrics.
Growth Catalysts
- Aging Demographics:Advanced economies like Japan and Germany have rising elderly populations, which elevates the need for chronic wound care products, orthopedic support textiles, and implantable devices like cardiovascular grafts, stimulating demand for high-performance materials.
- Infection Control Mandates:Hospital-acquired infections (HAIs) drive institutional demand for single-use non-woven textiles, such as surgical gowns and drapes with superior barrier properties, to comply with strict infection prevention protocols established by healthcare authorities.
- Regulatory Modernization:The implementation of Europe's Medical Device Regulation (MDR) creates a catalyst for premium, compliant textiles, as manufacturers upgrade their product lines to meet stricter standards for clinical evidence and material safety.
Market Restraints
- Raw Material Price Volatility:The market is exposed to price fluctuations in specialty polymers and natural fibers like cotton, which can compress margins for manufacturers, particularly in the high-volume, cost-sensitive disposable goods segment.
- Stringent Approval Timelines:The lengthy and expensive premarket approval (PMA) process required by regulators like the US FDA for Class III implantable textiles acts as a significant barrier to entry and can delay the commercialization of innovative products.
- Threat from Substitutes:Alternative technologies, such as advanced polymer films, hydrogel dressings, and spray-on sealants, present a substitution risk to traditional textile-based products in applications like wound management and surgical closure.
Strategic Opportunities
- Smart Textiles Integration:The convergence of textiles with microelectronics offers an opportunity to develop smart fabrics with integrated sensors for real-time monitoring of vital signs or wound healing, creating a new category of high-value diagnostic products.
- Biodegradable and Bioactive Materials:There is a significant opportunity in developing drug-eluting and biodegradable textiles for tissue engineering scaffolds and advanced wound care, which can improve patient outcomes by promoting healing and reducing intervention.
- Emerging Market Expansion:Rising healthcare expenditures and infrastructure development in countries across Southeast Asia and Latin America create untapped markets for a wide range of medical textiles, from basic disposables to more advanced surgical products.
Industry Challenges
- Supply Chain Traceability:Manufacturers face operational challenges in establishing the end-to-end material traceability required by new regulations like the EU MDR, demanding significant investment in supply chain management and documentation systems.
- Lack of Harmonized Standards:The absence of globally harmonized testing protocols for novel textile properties, such as specific antimicrobial or antiviral efficacy claims, creates compliance complexity and hurdles for manufacturers seeking access to multiple international markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Textiles Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Textiles, Implantable Textiles, Non-woven Fabrics, Woven Fabrics Application: Sutures, Bandages, Dressings, Grafts End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Knitting, Weaving, Coating, Finishing |
| Companies Covered | BSN medical, Molnlycke, Medtronic (Covidien), DuPont, Medline, Johnson & Johnson, Smith & Nephew, Cardinal Health, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Textiles Market Strategic Shifts & Innovations
Material science advancements are redefining the functional capabilities of medical fabrics, moving beyond passive barrier protection toward active therapeutic roles. This evolution is coupled with the digitalization of design and compliance processes, which is altering how new products are developed and brought to market.
Computational modeling is transforming the design of complex medical textiles. These digital tools allow for the simulation of a material's mechanical properties, fluid interactions, and biocompatibility before any physical prototypes are created. Research and development teams at specialized device firms are adopting this for creating intricate structures like woven vascular grafts and non-woven tissue scaffolds. This approach is virtualizing key parts of the material validation process, reducing development costs and compressing timelines for regulatory submission.
China's NMPA is implementing stricter oversight on high-risk medical devices, aligning its standards more closely with those in the US and Europe. This regulatory shift mandates more rigorous clinical data for product registration and enhances post-market surveillance requirements. Manufacturers of implantable textiles and other Class III devices targeting the Chinese market must now invest more heavily in local clinical trials and quality management systems to ensure compliance and maintain market access.
Direct-to-provider sourcing models are gaining traction among large healthcare systems. This behavioral shift sees major hospital networks and integrated delivery networks (IDNs) bypassing traditional distributors to secure contracts directly with textile manufacturers. The primary channel being disrupted is the group purchasing organization (GPO), as health systems seek greater control over their supply chain and product standardization. This trend is most visible in the United States, where cost containment is a primary objective for large-scale healthcare providers.
Medical Textiles Market Segmentation
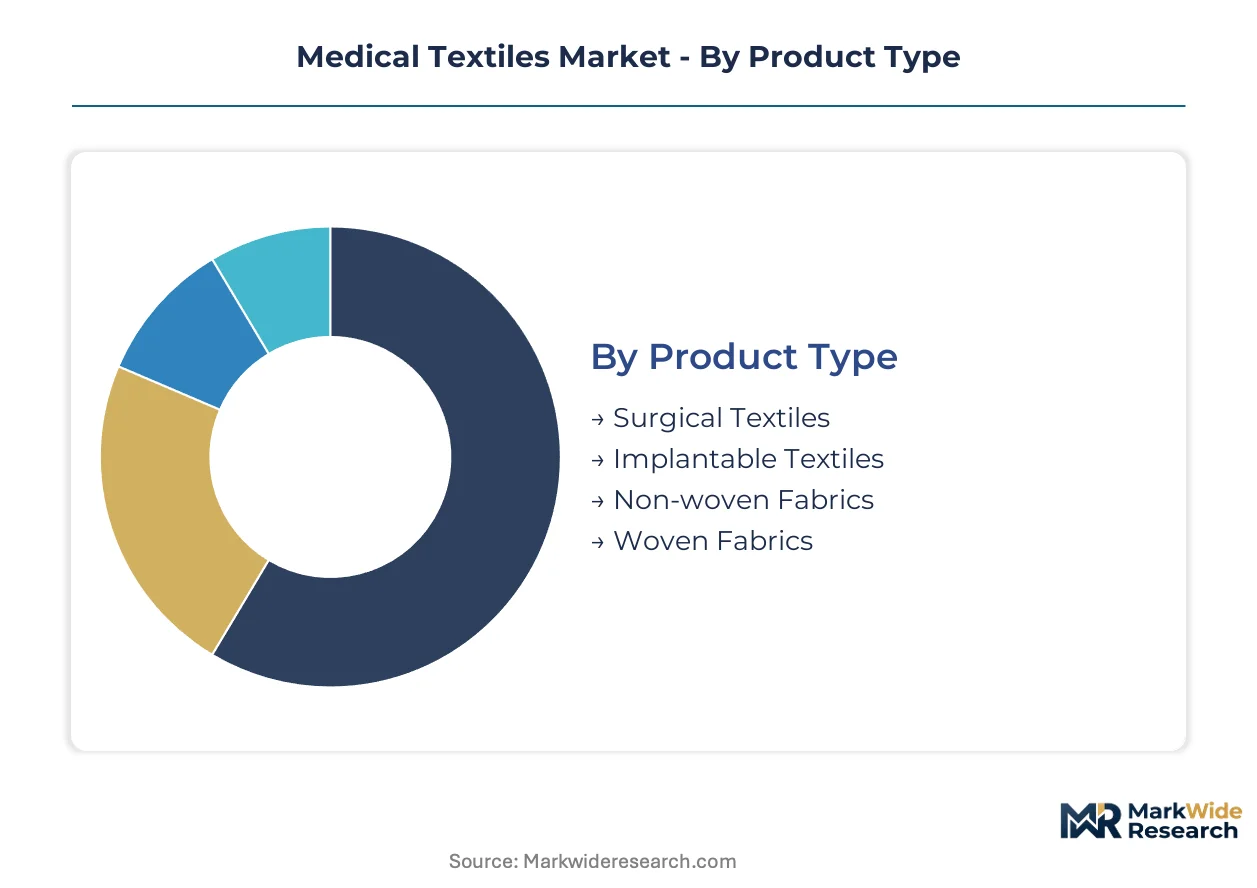
The segmentation of the medical textiles market illuminates the diverse functional requirements and end-user needs across the healthcare industry. This granular view helps manufacturers align product development with specific clinical applications and regulatory demands, ensuring material suitability for critical medical uses.
Product Type:
The product type segmentation highlights the diverse functional requirements of medical textiles, ranging from temporary barrier protection to permanent biological integration.
- Implantable Textiles:These specialized fabrics are designed for long-term integration within the human body, requiring exceptional biocompatibility, mechanical strength, and often porosity for tissue ingrowth. Demand concentrates in cardiovascular and orthopedic applications, driven by an aging global population and advancements in surgical techniques.
- Non-woven Fabrics:Comprising entangled fibers bonded by mechanical, thermal, or chemical means, these materials offer cost-effectiveness and superior barrier properties for single-use applications. Infection control mandates in countries like Germany and the United States drive significant demand for non-woven surgical gowns and drapes.
- Surgical Textiles:This category includes drapes, gowns, and masks, designed to create sterile fields and protect both patients and healthcare professionals during medical procedures.
- Woven Fabrics:Constructed by interlacing two or more sets of yarns, woven fabrics offer high tensile strength and durability, often used in reusable medical garments and specialized support structures.
Established volume favors Non-woven Fabrics; emerging adoption favors Implantable Textiles.
Application:
The application spectrum reveals how medical textiles cater to distinct patient care needs, from routine wound management to complex surgical interventions.
- Grafts:These implantable textiles are engineered to replace or support damaged blood vessels or other tissues, demanding precise structural integrity and long-term biocompatibility. Demand for cardiovascular grafts is particularly strong in advanced healthcare systems like those in the United States and Japan, where chronic diseases are prevalent.
- Dressings:Medical dressings are designed to protect wounds, absorb exudate, and promote healing, often incorporating antimicrobial agents or advanced polymers. The high frequency of minor injuries and post-surgical wound care drives consistent demand across all healthcare settings, including home care.
- Sutures:These thread-like materials are used to close wounds or surgical incisions, requiring specific tensile strength, knot security, and biodegradability depending on the application.
- Bandages:Used for wound compression, support, or immobilization, bandages encompass a wide range of woven and non-woven materials with varying elasticity and adhesive properties.
Demand for high-volume consumables drives the dressings segment; advanced surgical procedures expand the grafts segment.
End User:
The end user classification delineates how different healthcare settings utilize medical textiles, reflecting varying scales of operation and patient acuity.
- Hospitals:These large-scale facilities represent the primary consumers of medical textiles, requiring extensive volumes of surgical disposables, wound care products, and implantable devices. Strict infection control protocols in institutions across Europe and North America dictate material specifications and procurement patterns.
- Home Care:This segment encompasses medical textile use in non-institutional settings, driven by an increasing preference for at-home recovery and chronic disease management. Products like advanced wound dressings and support garments are gaining traction due to convenience and cost-effectiveness.
- Clinics:Smaller than hospitals, clinics utilize medical textiles for outpatient procedures, diagnostics, and routine medical examinations, focusing on sterile drapes, examination table covers, and basic wound care supplies.
- Rehabilitation Centers:These facilities focus on patient recovery and physical therapy, using medical textiles for orthopedic supports, compression garments, and specialized bedding materials.
Hospitals remain the primary consumption hub; the home care segment demonstrates significant expansion.
Technology:
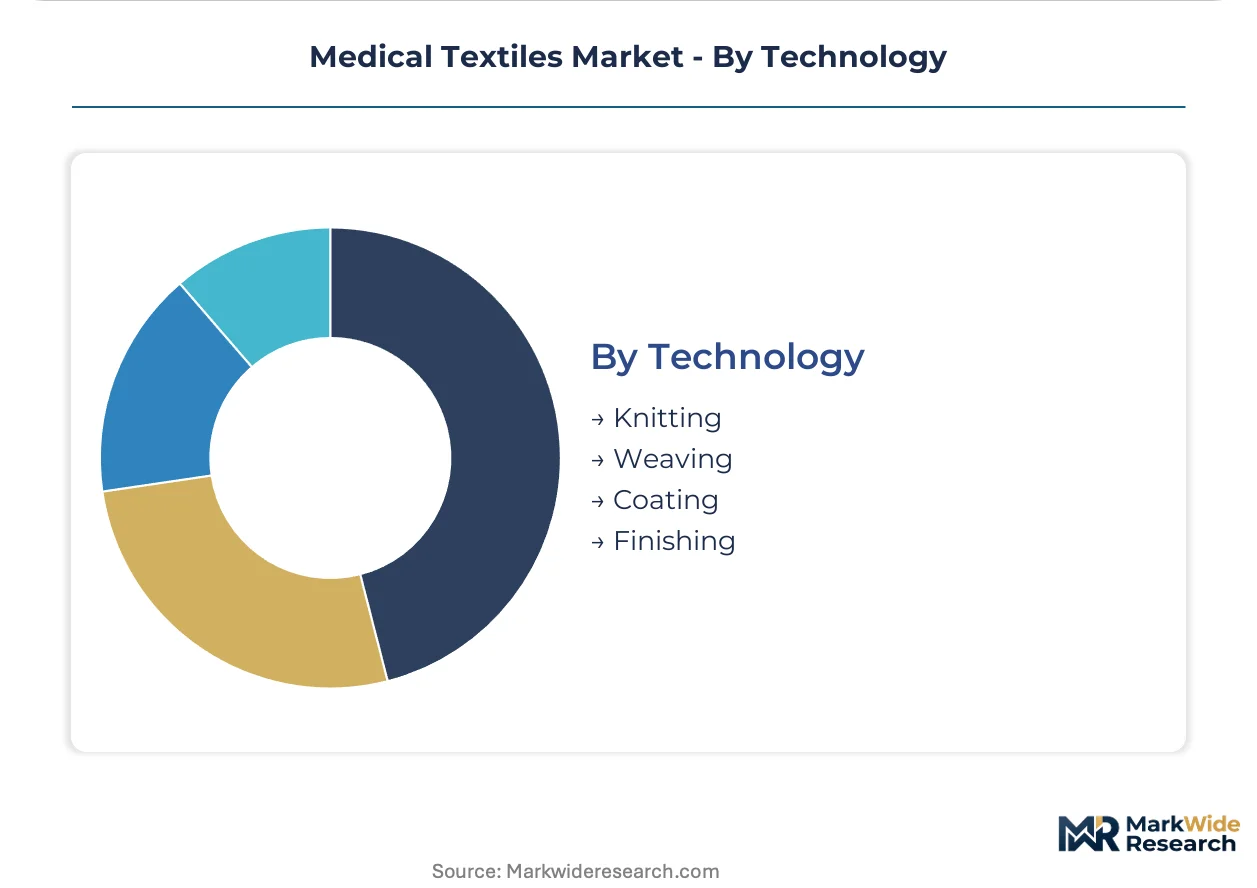
The technology segment illustrates the manufacturing processes that impart specific functional characteristics to medical textiles, influencing performance and production costs.
- Coating:This process involves applying a thin layer of material onto textile surfaces to impart enhanced properties such as antimicrobial activity, water repellency, or drug elution. Innovations in coating technologies are critical for developing next-generation surgical textiles and implantable devices, particularly in countries with stringent regulatory standards like the US FDA.
- Finishing:Finishing processes involve chemical or mechanical treatments applied to textiles to improve their feel, appearance, or functional attributes like flame retardancy or biocompatibility. Rigorous finishing ensures medical textiles meet the exacting standards for patient safety and comfort required by the EU MDR.
- Knitting:This textile formation method creates fabrics by interlacing loops of yarn, offering elasticity and conformability, commonly used in compression garments and some wound care products.
- Weaving:Weaving produces stable and strong fabrics by interlacing two sets of yarns at right angles, forming the basis for many surgical drapes, bandages, and some implantable structures.
Traditional textile formation methods like knitting maintain foundational importance; advanced surface treatments such as coating and finishing drive innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry characterizes the medical textiles market, with advanced economies like the United States and Germany commanding premium pricing for specialized, high-performance materials. Emerging markets such as China and India increasingly focus on cost-effective, high-volume disposable textiles. This dynamic influences investment in research and development and manufacturing capabilities across different geographies.
United States
The United States drives demand for advanced implantable textiles and high-performance surgical fabrics due to its sophisticated healthcare infrastructure and high surgical volumes. The US FDA's stringent premarket approval process ensures material safety and clinical efficacy for Class III devices. Major medical device clusters in places like Boston and Minneapolis foster innovation in biocompatible materials and smart textile integration.
Germany
Germany's aging demographics and robust healthcare system fuel consistent demand for chronic wound care products and orthopedic support textiles. Europe's Medical Device Regulation (MDR) mandates rigorous standards for clinical evidence and material traceability for market access. Advanced material science research in regions like Bavaria and North Rhine-Westphalia contributes to next-generation fabric development.
Japan
Japan's rapidly aging population creates a significant market for cardiovascular grafts and other implantable textiles, alongside support garments for geriatric care. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict regulatory requirements for medical devices, emphasizing product quality and patient safety. Tokyo's medical technology firms and research institutions lead in developing innovative tissue engineering scaffolds.
China
China's expanding healthcare sector and increasing focus on quality are driving demand for both basic disposable textiles and high-risk implantable devices. The National Medical Products Administration (NMPA) implements stricter oversight, requiring more rigorous clinical data for product registration. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta are adapting to these enhanced quality management systems.
India
India represents a substantial emerging market for medical textiles, propelled by rising healthcare expenditures and infrastructure development. The Bureau of Indian Standards (BIS) establishes quality benchmarks for medical devices, guiding local manufacturing and imports. Bengaluru and Hyderabad are becoming centers for medical technology innovation, attracting investment in advanced textile production.
Medical Textiles Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical raw materials and advanced fabric solutions to medical device manufacturers. The market exhibits a tiered structure, with large diversified healthcare conglomerates coexisting with specialized material science innovators. Dominant competitive moves include strategic partnerships for market access and continuous portfolio diversification into advanced materials.
Among diversified healthcare conglomerates, Medtronic exemplifies leveraging an extensive product portfolio to secure integrated contracts with healthcare providers, reinforcing its position across multiple medical device categories. Johnson & Johnson similarly operates with a broad spectrum of healthcare solutions, anchoring its presence in wound care and surgical textiles. DuPont, a material science innovator, differentiates through proprietary fiber technologies, supplying multiple downstream producers with specialized materials for demanding medical applications.
| Leading Market Players |
|---|
| BSN medical |
| Molnlycke |
| Medtronic (Covidien) |
| DuPont |
| Medline |
| Johnson & Johnson |
| Smith & Nephew |
| Cardinal Health |
| 3M |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost dynamics influence medical textile supply concentration in Asian manufacturing hubs, impacting price differentiation for high-volume disposables versus specialized implantable textiles.
Pricing Analysis
Customization-premium spreads define pricing across medical textiles, with configured-to-order implantable grafts commanding higher prices than standard non-woven disposables. Contract-based long-term offtake agreements characterize large hospital procurement, while smaller clinics rely on per-unit transactional models. Price differentiation stems from stringent regulatory certification, advanced material science innovation, and volume scale. Pricing softness runs through the high-volume disposable segment due to intense competition and raw material volatility. The home care segment is most price-sensitive for basic dressings, while hospitals are less sensitive for critical implantable textiles.
Supply Chain Analysis
Upstream feedstock availability for specialty polymers and natural fibers largely originates from China, India, and other Southeast Asian nations. These regions anchor global production for many basic medical textile components. Raw material dependencies include polypropylene, polyester, and medical-grade cotton. Commodity price volatility for these base materials presents a significant supply chain risk. Distribution runs increasingly through direct-to-provider models, particularly for large hospital networks bypassing traditional group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical textiles market is entering a cyclical recovery, driven by a post-pandemic rebound in elective surgeries and renewed focus on hospital infection control. This shift creates opportunities for strategic positioning across the value chain.
For Market Incumbents: Insulate core product lines by deepening vertical integration into proprietary fiber production, reducing reliance on external material suppliers. Acquire specialized material science firms to counter substitution risk from advanced polymer films and hydrogel dressings. Invest heavily in EU MDR certification processes to maintain market access and differentiate premium offerings. This approach fortifies competitive positioning against emerging alternative technologies.
For New Entrants and Emerging Players: Southeast Asia represents a geographic underpenetration for basic medical disposables, offering significant volume potential. Latin American markets show white-space opportunities for advanced wound care products with integrated therapeutic properties. The home care segment is most penetrable for routine dressings and support garments due to rising demand for at-home recovery. Partner with local distributors to leverage established networks and navigate regional regulatory landscapes effectively.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core medical textile assets. The market offers stable, long-term growth prospects over the next decade, driven by aging populations and expanding healthcare infrastructure. Vertically integrated mid-cap specialists in implantable textiles or smart fabrics represent an attractive acquisition archetype. Increased M&A activity among material science innovators signals a maturing investment landscape.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval (PMA) for Class III Devices | Secures market access for high-value implantable textiles in the United States. |
| EU MDR Compliance Upgrade | Ensures continued market access across European Union member states for medical devices. |
| Investment in Smart Textile R&D | Develops integrated sensor fabrics for real-time patient monitoring capabilities. |
| Direct-to-Provider Sales Channel Expansion | Bypasses traditional GPOs to secure integrated contracts with large hospital networks. |
| Biodegradable Material Development | Addresses sustainability mandates and expands applications in tissue engineering scaffolds. |
Research Approach
Operator-level perspectives from biomedical engineers, hospital procurement managers, R&D directors at textile manufacturers, and regulatory affairs specialists anchored the qualitative base. This primary research was validated through extensive secondary data, including US FDA filings, EU MDR guidance documents, NMPA announcements, and academic journals on biomaterials. Bottom-up data aggregation and top-down market sizing provided robust triangulation.
Scenario-bracketing established a plausible range for market evolution across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end user, technology, and regulatory compliance tier. Compound annual growth rates were derived from historical trends and projected future demand. Key industry-specific forecast inputs included elective surgery volumes, hospital-acquired infection rates, and geriatric population growth.
The forecast holds incumbent behavior within observed patterns; aggressive moves by material science disruptors or vertically integrated tech giants would shift outcomes. Unforeseen regulatory changes or significant raw material supply disruptions represent key risk factors. Cross-checking against national healthcare expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market