
 Global Healthcare Fabrics Market | 2026-2036
Global Healthcare Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Fabrics Market Foresight
A shift from single-source to multi-source raw material procurement is hardening across the healthcare fabrics value chain. Kimberly-Clark Corporation leverages its captive nonwoven capacity to insulate margin pools from polymer volatility. Freudenberg Group anchors its position through backward integration into spunbond meltblown composite lines. Berry Global Group Inc. competes by operating continent-scale manufacturing nodes that shorten logistics loops to hospital purchasing groups.
Healthcare fabrics encompass engineered textile structures—nonwoven, woven, knitted, laminated, and composite formats—designed to meet biocompatibility, barrier, and durability specifications for medical environments, typically manufactured through spunbond, meltblown, hydroentanglement, or thermal bonding processes to deliver infection control and patient protection functions. Nonwoven formats dominate volume flows given their disposability and cost efficiency in surgical drapes and medical masks, while laminated composites command premium positioning in wound care where moisture vapor transmission rates determine clinical outcomes. Application demand concentrates in surgical drapes and patient gowns as hospitals restock standard consumables, though disposable coveralls saw accelerated structural uplift from heightened isolation protocol adherence.
FDA medical device regulations, EPA chemical exposure thresholds, and EU MDR conformity requirements collectively elevate barrier-property testing and biocompatibility documentation burdens for market access. ISO 10993 biological evaluation standards and REACH substance restrictions further narrow the approved chemical formulation space for antimicrobial finishes and dye carriers. Stakeholders must monitor how ECHA substance-of-very-high-concern listings and impending PFAS restrictions reshape the feasible material technology set for next-generation healthcare textiles.
Market Dynamics
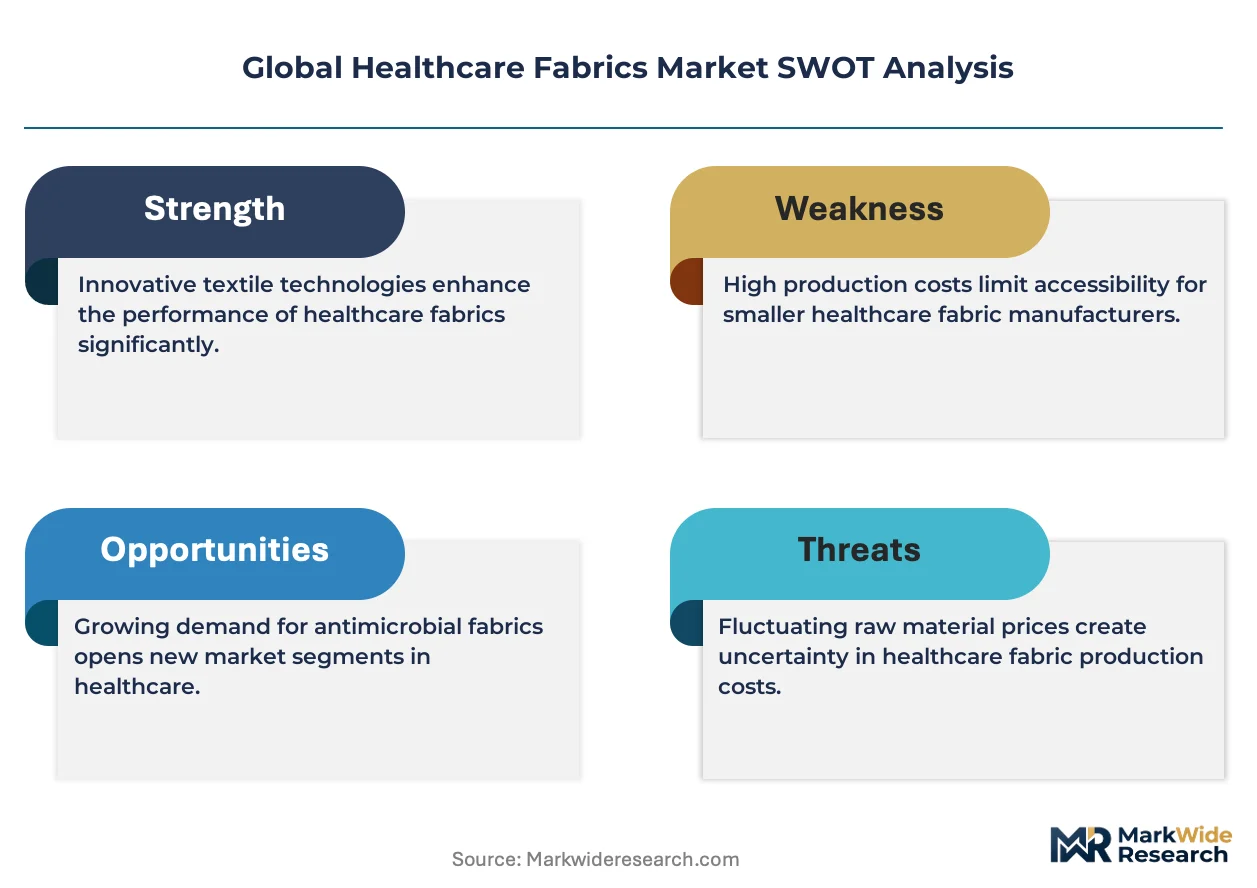
Healthcare fabric producers face intensifying pressure from ECHA's PFAS restriction roadmap, which threatens to invalidate existing antimicrobial finishes and force wholesale reformulation of barrier-layer chemistries across surgical drape and gown portfolios.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume in the United States is pulling disposable surgical pack consumption away from inpatient settings, creating dedicated demand for lighter-weight nonwoven configurations optimized for same-day discharge protocols.
- EU MDR conformity deadlines:Extended transition timelines for Class I medical device textiles are compressing supplier qualification windows, favoring incumbent manufacturers with established technical documentation and biocompatibility testing archives.
- Spunbond-meltblown-spunbond (SMS) composite lines:New capacity installations in India and Vietnam are absorbing regional demand for surgical masks and isolation gowns, displacing Chinese-origin supply in ASEAN hospital purchasing tenders.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer pricing tied to naphtha crackers and PDH units exposes nonwoven producers to margin compression that cannot be passed through to fixed-price hospital contracts.
- Spunbond concentration in Germany and China:Reicofil and STP lines dominate high-throughput SMS capacity, creating single-source equipment dependency for new entrants seeking barrier-grade fabric certification.
- REACH SVHC listing velocity:ECHA's expanding candidate list of substances of very high concern now captures multiple flame retardant and dye carrier chemistries, forcing proactive inventory obsolescence.
Strategic Opportunities
- India's PLI scheme for technical textiles:Production-linked incentives for nonwoven medical fabrics are attracting greenfield investment in Tamil Nadu and Gujarat, targeting export substitution for Middle East and African hospital supply chains.
- Wearable therapeutic textile integration:Convergence of conductive fiber knitting with moisture-wicking base layers is opening post-surgical recovery garment applications with embedded biosensor connectivity.
- Direct hospital group purchasing organization (GPO) channels:Bypassing traditional medical distributor markups through Premier and Vizient contract structures is capturing margin for manufacturers with US-based converting and sterilization assets.
Industry Challenges
- ISO 10993-5 cytotoxicity testing backlog:Contract laboratory capacity constraints are extending biocompatibility certification timelines for new antimicrobial finish formulations, delaying product launches by 8-14 months.
- Legacy ERP-to-UDI integration:FDA Unique Device Identification requirements are forcing mid-tier converters to replace traceability systems, straining IT capital budgets and disrupting lot-level inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Fabrics Market |
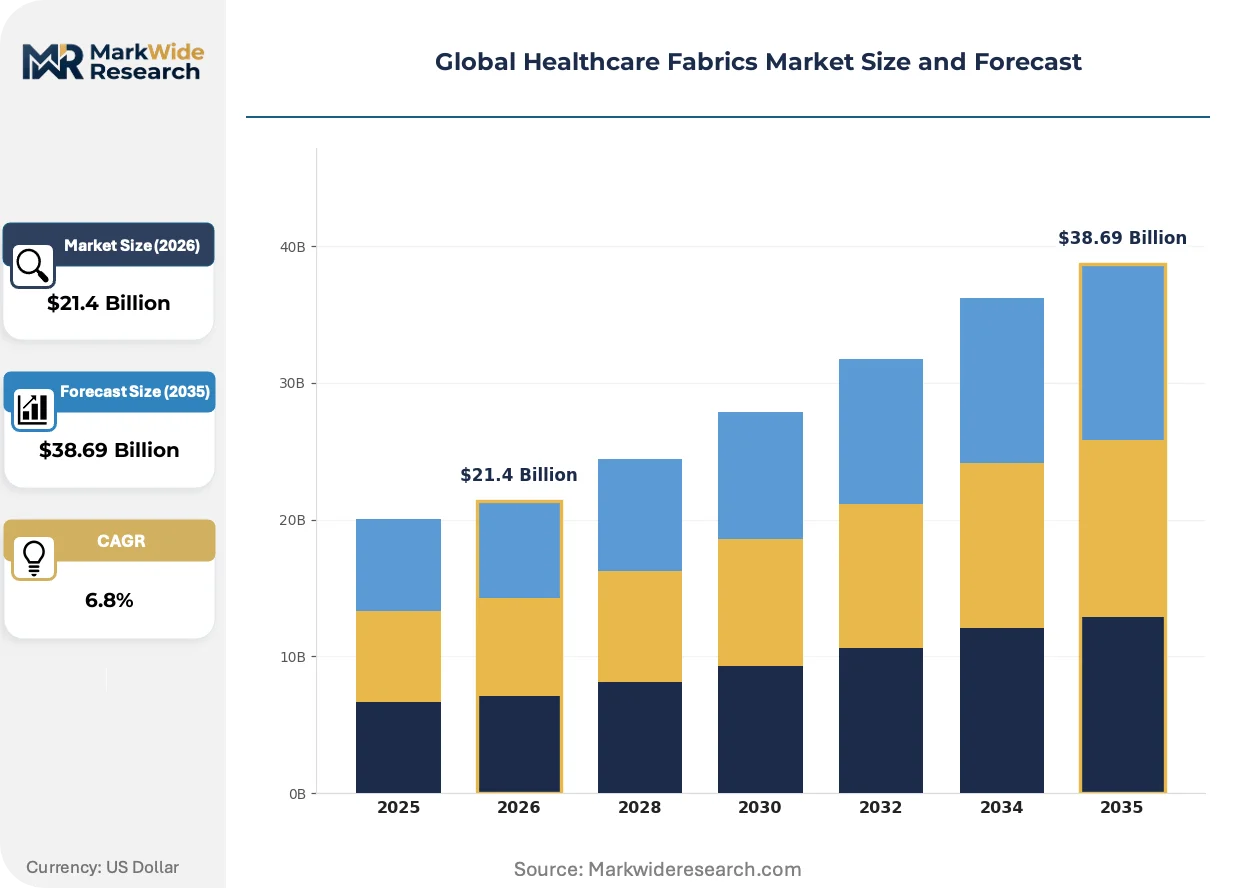
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonwoven, Woven, Knitted, Laminated, Composite Application: Surgical Drapes, Patient Gowns, Wound Care, Hospital Curtains, Medical Masks, Disposable Coveralls End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Long-Term Care Facilities, Rehabilitation Centers Technology: Spunbond, Meltblown, Airlaid, Hydroentanglement, Thermal Bonding |
| Companies Covered | Kimberly-Clark Corporation, Berry Global Group Inc., Freudenberg Group, Ahlstrom-Munksjo OYJ, Asahi Kasei Corporation, Avgol Ltd, Knoll Inc., Carnegie Fabrics LLC, Eximius Incorporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Fabrics Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to reshape how barrier properties are engineered into healthcare textiles, with sustainability mandates now co-equal with infection control performance in supplier selection criteria.
Bicomponent spunbond technology is absorbing the functional requirements previously delivered through chemical finishes, with sheath-core polypropylene-polyethylene structures providing inherent hydrophobicity without perfluorinated additives. German and Austrian nonwoven lines are retrofitting to this configuration to preempt ECHA restrictions. The structural consequence is a compression in the addressable market for topical antimicrobial treatments.
REACH substance restrictions are eliminating legacy halogenated flame retardants from operating room textile specifications, compelling reformulation around phosphorus-nitrogen intumescent systems that must pass EN ISO 15025 vertical flame testing. Woven curtain and drape producers in Portugal and Italy are absorbing the compliance burden through controlled polymer compounding partnerships. The segment most affected is reusable surgical linens, where launderability cycles must be revalidated with each chemistry change.
Hospital sustainability officers are consolidating supplier rosters around vendors with verified Scope 3 emissions data and closed-loop takeback programs for single-use textiles. Nordic hospital procurement clusters are piloting reusable surgical gown rental models with industrial laundering guarantees. The geography where this behavioral shift is most visible is the Netherlands, where carbon accounting mandates for healthcare institutions are accelerating contract renegotiations.
Global Healthcare Fabrics Market Segmentation
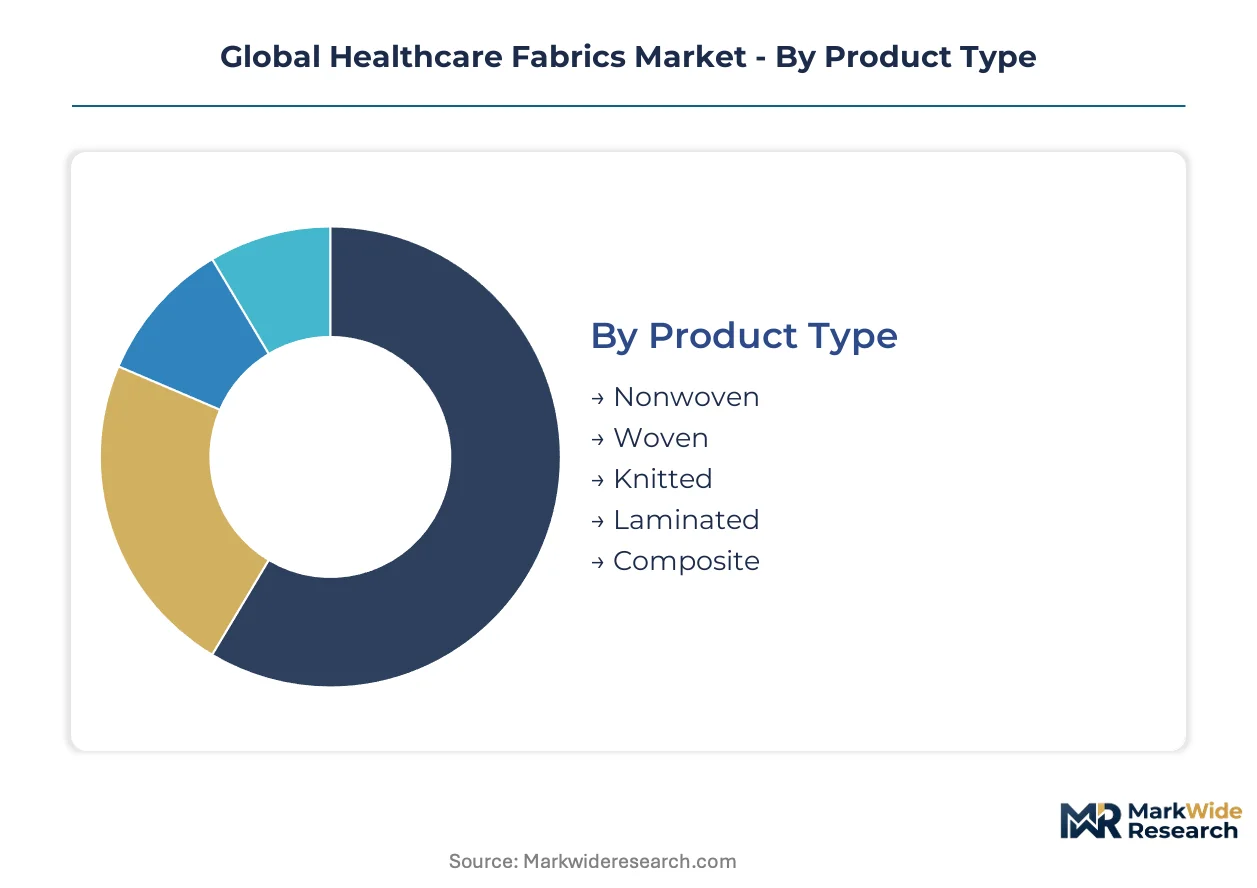
Healthcare fabrics demand fragments across material formats, clinical settings, and manufacturing technologies. Procurement specifications vary sharply between infection control disposables and reusable therapeutic textiles, creating distinct margin pools and certification burdens.
Product Type:
Hospital purchasing groups weigh disposability against total cost of ownership when selecting material formats for different clinical zones.
- Nonwoven:Spunbond and meltblown polypropylene structures dominate surgical pack volumes. Ambulatory surgical centers in the United States favor lighter-weight SMS configurations optimized for same-day discharge protocols where laundering economics collapse.
- Woven:Cotton-polyester blends persist in reusable surgical linens and operating room curtains. Portuguese and Italian converters absorb REACH-driven flame retardant reformulation costs through controlled polymer compounding partnerships with industrial laundries.
- Knitted:Stretch-conforming structures serve compression therapy and post-surgical recovery garments. Conductive fiber integration is opening biosensor-enabled applications in cardiac monitoring.
- Laminated:Multi-layer barrier films bonded to textile substrates command premium positioning in wound care. Moisture vapor transmission rates determine clinical outcomes and supplier qualification status.
- Composite:Hybrid structures combining nonwoven webs with breathable membranes address specialized isolation protocols. German and Austrian lines are retrofitting to bicomponent spunbond configurations to preempt ECHA PFAS restrictions.
Nonwoven leads on scale; composite leads on momentum.
Application:
Volume concentration tracks infection control protocol intensity and procedure setting migration.
- Surgical Drapes:Sterile barrier sheets for operating fields. Indian and Vietnamese SMS capacity installations are absorbing regional demand and displacing Chinese-origin supply in ASEAN hospital tenders.
- Patient Gowns:Disposable and reusable variants for general hospitalization. Nordic procurement clusters are piloting rental models with industrial laundering guarantees under carbon accounting mandates.
- Wound Care:Advanced dressings requiring precise moisture management. Laminated composites with tailored vapor transmission specifications capture premium pricing.
- Hospital Curtains:Privacy and contamination barriers in patient rooms. REACH SVHC listings are forcing proactive inventory obsolescence for legacy halogenated flame retardant chemistries.
- Medical Masks:Respiratory protection for healthcare workers. Spunbond-meltblown-spunbond lines installed during pandemic-era capacity expansion now face utilization pressure.
- Disposable Coveralls:Full-body isolation garments. Heightened protocol adherence created structural uplift now normalizing toward baseline surgical consumable demand.
Surgical drapes anchor volume; disposable coveralls expanded most quickly during protocol intensification.
End User:
Facility type determines pack configuration complexity and contract pricing structures.
- Hospitals:Integrated health systems with centralized materials management. Premier and Vizient GPO contract structures reward manufacturers with US-based converting and sterilization assets.
- Ambulatory Surgical Centers:Outpatient-focused facilities driving lighter-weight nonwoven adoption. Procedure volume migration from inpatient settings creates dedicated demand for streamlined surgical packs.
- Diagnostic Laboratories:Specimen handling and phlebotomy protection requirements. Lower barrier specifications than surgical settings permit cost-optimized material selection.
- Long-Term Care Facilities:Extended-stay environments with laundering economics favoring reusables. Pressure ulcer prevention drives specialized mattress and seating fabric demand.
- Rehabilitation Centers:Post-acute recovery settings with therapeutic textile integration opportunities. Wearable biosensor connectivity is emerging in garment specifications.
Hospitals dominate contract value; ambulatory surgical centers gain share fastest.
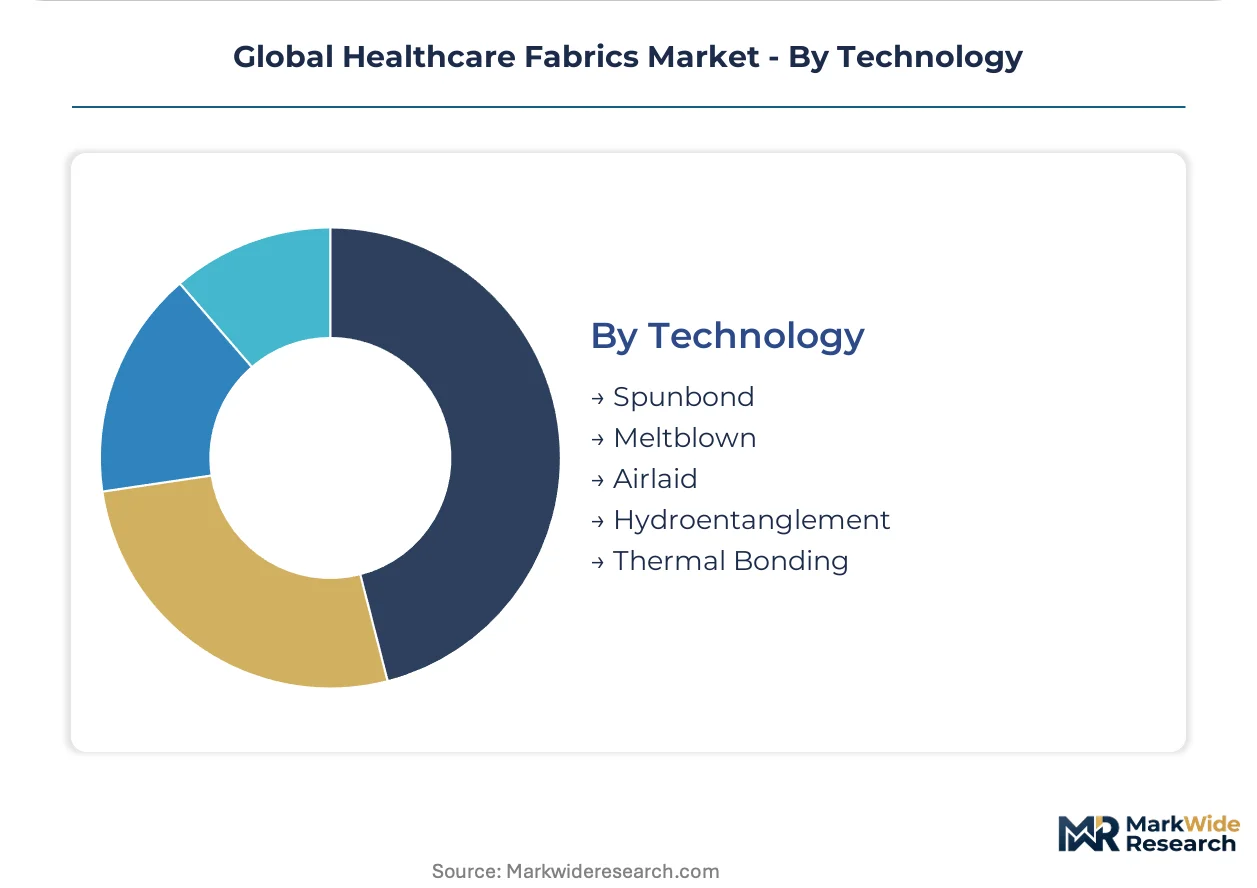
Technology:
Process selection locks in barrier properties, production economics, and regulatory compliance pathways.
- Spunbond:Continuous filament extrusion forming durable webs. Reicofil and STP line dominance in Germany and China creates equipment dependency for barrier-grade certification.
- Meltblown:Microfiber webs delivering filtration efficiency. Propylene monomer volatility tied to naphtha crackers and PDH units exposes margin compression risk.
- Airlaid:Pulp-based absorbent structures for incontinence and wound care. Lower capital intensity attracts regional producers serving price-sensitive markets.
- Hydroentanglement:High-pressure water bonding for soft, drapeable fabrics. India's PLI scheme for technical textiles is attracting greenfield investment in Tamil Nadu and Gujarat.
- Thermal Bonding:Heat-activated fiber fusion for dimensional stability. Energy cost exposure in European production locations is shifting capacity evaluation criteria.
Spunbond commands installed base; hydroentanglement climbs the fastest on sustainability-aligned process claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting healthcare fabric production toward jurisdictions with lower compliance burdens and stronger incentive frameworks. Manufacturers are relocating spunbond capacity to exploit gaps between EU REACH enforcement and emerging-market chemical standards.
United States
Ambulatory surgical centers in Texas and Florida are driving lighter-weight nonwoven consumption as outpatient procedures migrate from inpatient settings. FDA Unique Device Identification requirements are forcing mid-tier converters to modernize traceability systems. Premier and Vizient group purchasing organizations in the Midwest are consolidating supplier rosters around domestic converting assets.
Germany
Reicofil and STP line dominance in North Rhine-Westphalia creates equipment dependency for barrier-grade SMS certification. ECHA PFAS restriction roadmaps are compelling bicomponent spunbond retrofits across Bavarian and Baden-Württemberg facilities. Industrial laundries in the Ruhr region are absorbing REACH-driven flame retardant reformulation costs for reusable surgical linens.
China
Spunbond-meltblown-spunbond capacity expansion in Zhejiang and Jiangsu provinces is absorbing regional mask and isolation gown demand. NMPA medical device textile standards are elevating biocompatibility documentation burdens for export certification. Yangtze River Delta clusters are facing utilization pressure on pandemic-era meltblown lines.
India
Production-linked incentives for technical textiles are attracting greenfield investment in Tamil Nadu and Gujarat. CDSCO medical device regulations are compressing supplier qualification windows for domestic hospital tenders. Hydroentanglement capacity in the Delhi-NCR corridor is targeting Middle East and African export substitution.
Netherlands
Carbon accounting mandates for healthcare institutions are accelerating contract renegotiations around Scope 3 emissions data. Nordic hospital procurement clusters are piloting reusable surgical gown rental models with industrial laundering guarantees. Rotterdam-area distributors are consolidating logistics loops for Benelux hospital purchasing groups.
Global Healthcare Fabrics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustainability-aligned process claims and regional GPO bypass strategies. The market exhibits tiered concentration with integrated multinationals controlling barrier-grade certification archives while regional specialists capture price-sensitive volume. Three archetypes dominate: captive nonwoven producers insulating margin pools from polymer volatility, backward-integrated spunbond operators, and continent-scale manufacturers shortening logistics loops to hospital purchasing groups. Competitive moves center on SMS line retrofits for PFAS compliance and direct GPO contract structures that capture distributor margin.
Among North American hygiene and healthcare textile specialists, Kimberly-Clark Corporation and Berry Global Group Inc. exemplify divergent scale strategies. The former anchors its position through captive nonwoven capacity; the latter operates manufacturing nodes that compress delivery cycles to integrated health systems. Freudenberg Group represents the European backward-integration archetype, with German-based spunbond meltblown composite lines securing barrier-property consistency for surgical drape portfolios. These three entities collectively illustrate how geographic production footprint and supply chain control determine qualification status under tightening FDA and EU MDR documentation requirements.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Berry Global Group Inc. |
| Freudenberg Group |
| Ahlstrom-Munksjo OYJ |
| Asahi Kasei Corporation |
| Avgol Ltd |
| Knoll Inc. |
| Carnegie Fabrics LLC |
| Eximius Incorporation |
| Others |
Supply & Pricing Matrix
Hospital purchasing groups in the United States and Nordic clusters anchor contract negotiations around total cost-of-ownership metrics, compressing distributor markups and rewarding manufacturers with captive sterilization assets and direct GPO relationships. This buyer concentration privileges scale players with continental manufacturing footprints while squeezing mid-tier converters dependent on third-party logistics.
Pricing Analysis
Distributor margin layers in healthcare fabrics typically absorb 15-25 points before product reaches hospital receiving docks, though direct-to-GPO contracting by Kimberly-Clark and Berry Global captures this value for integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates SMS composite barrier grades from lighter-weight spunbond configurations and commodity meltblown inputs. Pricing pressure stems from propylene monomer volatility tied to naphtha cracker economics, which producers cannot fully pass through to fixed-price multi-year hospital contracts. Ambulatory surgical centers exhibit highest price sensitivity due to streamlined reimbursement protocols, while integrated health systems with Premier and Vizient memberships prioritize supply security over unit cost.
Supply Chain Analysis
Freight cost exposure from Zhejiang and Jiangsu province clusters to ASEAN hospital systems has accelerated regional capacity migration toward Tamil Nadu and Gujarat greenfield sites. Polypropylene resin supply concentrates in Saudi Arabia, South Korea, and the United States, with healthcare fabric producers drawing from regional petrochemical complexes to minimize working capital intensity. Single-source equipment dependency on Reicofil and STP spunbond lines in Germany and China creates qualification bottlenecks for new entrants seeking barrier-grade certification. Distribution runs through medical device distributors with regional sterilization partnerships, though direct GPO channels are consolidating logistics loops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare fabrics constitute a late-cycle quality story as infection control specifications harden and sustainability mandates elevate certified barrier grades above commodity alternatives. Demand is concentrating in bicomponent spunbond configurations that preempt ECHA PFAS restrictions.
For Market Incumbents: Deepen backward integration into polypropylene compounding to insulate margin pools from propylene monomer volatility at naphtha crackers and PDH units. Prioritize SMS line retrofits for bicomponent sheath-core configurations that eliminate perfluorinated additives before ECHA restriction deadlines. Secure GPO contract extensions with Premier and Vizient by embedding US-based converting and sterilization assets that shorten delivery cycles to Midwest hospital systems.
For New Entrants and Emerging Players: Enter via India's PLI scheme for technical textiles, targeting hydroentanglement capacity in Tamil Nadu and Gujarat for Middle East and African export substitution. Focus initial qualification efforts on lighter-weight nonwoven configurations for ambulatory surgical centers where barrier specifications remain less stringent than inpatient surgical settings. Pursue direct hospital system relationships in Texas and Florida outpatient markets to bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Nonwoven hygiene specialists with dormant healthcare certifications are the most active acquirer in this space, seeking FDA and EU MDR technical documentation archives that compress supplier qualification windows. The 5-10 year viability window favors producers with verified Scope 3 emissions data and closed-loop takeback programs as Nordic carbon accounting mandates spread. Monitor ECHA SVHC listing velocity as the critical inflection signal—accelerated flame retardant and dye carrier restrictions will force inventory obsolescence across Portuguese and Italian reusable surgical linen converters.
| Strategic Initiative | Industry Significance |
|---|---|
| SMS Line Retrofit for PFAS Compliance | Bicomponent spunbond conversion preempts ECHA restrictions and preserves barrier-grade certification status. |
| Direct GPO Contract Structuring | Premier and Vizient bypass strategies capture distributor margin for manufacturers with domestic sterilization assets. |
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin pools from propylene monomer volatility at naphtha crackers. |
| India PLI Scheme Capacity Buildout | Tamil Nadu and Gujarat greenfield sites target export substitution for Middle East and African hospital supply chains. |
| Reusable Surgical Gown Rental Model | Industrial laundering guarantees align with Netherlands carbon accounting mandates for healthcare institutions. |
Research Methodology
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and nonwoven plant operations directors grounded qualitative findings in procurement workflow realities. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, ECHA SVHC candidate list updates, and hospital procurement tender records across Benelux and ASEAN markets. Bottom-up patient procedure volume modeling and top-down healthcare expenditure elasticity estimates were triangulated against capacity utilization data from Reicofil and STP line installations.
Bottom-up demand modeling tracked surgical procedure migration from inpatient to ambulatory settings across the projection horizon, while top-down approaches calibrated healthcare textile intensity against national health expenditure growth. Segmentation dimensions included material format, application type, end-user facility category, and manufacturing technology process. CAGRs were derived from elasticity-adjusted procedure volume projections and substitution dynamics between disposable and reusable formats. Key inputs encompassed propylene monomer pricing correlations, ECHA regulatory timeline assumptions, and PLI scheme uptake rates in Indian technical textiles.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time meltblown line utilization data from Yangtze River Delta clusters introduce uncertainty bands around capacity absorption forecasts. Forecasts reflect documented assumptions regarding ECHA PFAS restriction implementation timing and FDA UDI compliance adoption curves. Stakeholders should weight assumptions against their own operating context, particularly regarding polymer feedstock hedging strategies and regional regulatory enforcement variance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Global Maternity Support Product Market