
 Global Biomedical Textiles Market | 2026-2036
Global Biomedical Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomedical Textiles Market Foresight
Cardiovascular surgical applications is decoupling from traditional wound care as the fastest-expanding demand vertical for biomedical textiles. Freudenberg Performance Materials leverages its European polymer research infrastructure to dominate high-performance vascular graft substrates. B. Braun SE anchors its competitive position through captive manufacturing of surgical mesh and suture textiles for European hospital networks. Cardinal Health competes aggressively on procurement scale across US hospital systems for disposable surgical drape fabrics.
Biomedical textiles comprise engineered fiber structures designed for implantation, tissue integration, or sterile barrier functions in clinical settings, typically manufactured through weaving, knitting, or melt-blowing processes with pore sizes calibrated between 10 and 500 microns for controlled cellular infiltration. These materials serve primarily to replace or support biological structures while maintaining mechanical integrity under physiological stress. Non-woven fabrics lead volume consumption in disposable surgical drapes and wound dressings where single-use protocols dominate procurement. Vascular grafts represent the fastest-growing application segment as polyester and polytetrafluoroethylene constructions displace biological conduits in aortic and peripheral bypass procedures. Woven fabrics retain the deepest margin pools in orthopedic implant reinforcement where tensile strength specifications exceed 50 MPa.
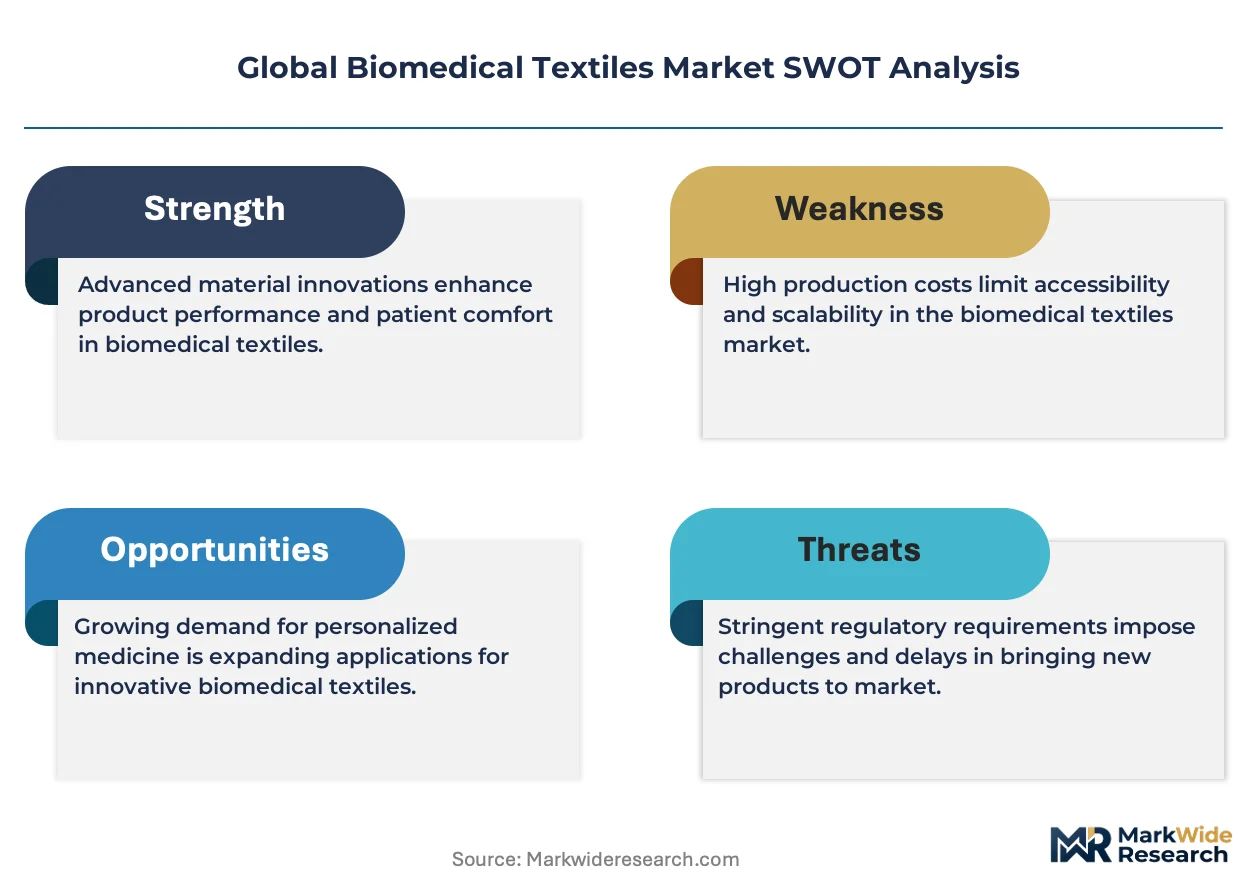
The FDA's Class III premarket approval pathway and the EU MDR's reinforced notified body oversight constrain market entry for novel implantable textile constructions, particularly for permanent blood-contacting devices. ISO 10993 biocompatibility testing series and REACH chemical substance registrations shape raw material selection across polyester, polyurethane, and silicone supply chains. Stakeholders must monitor evolving FDA guidance on absorbable polymer degradation profiles and the EU's forthcoming restrictions on per- and polyfluoroalkyl substances in implantable materials.
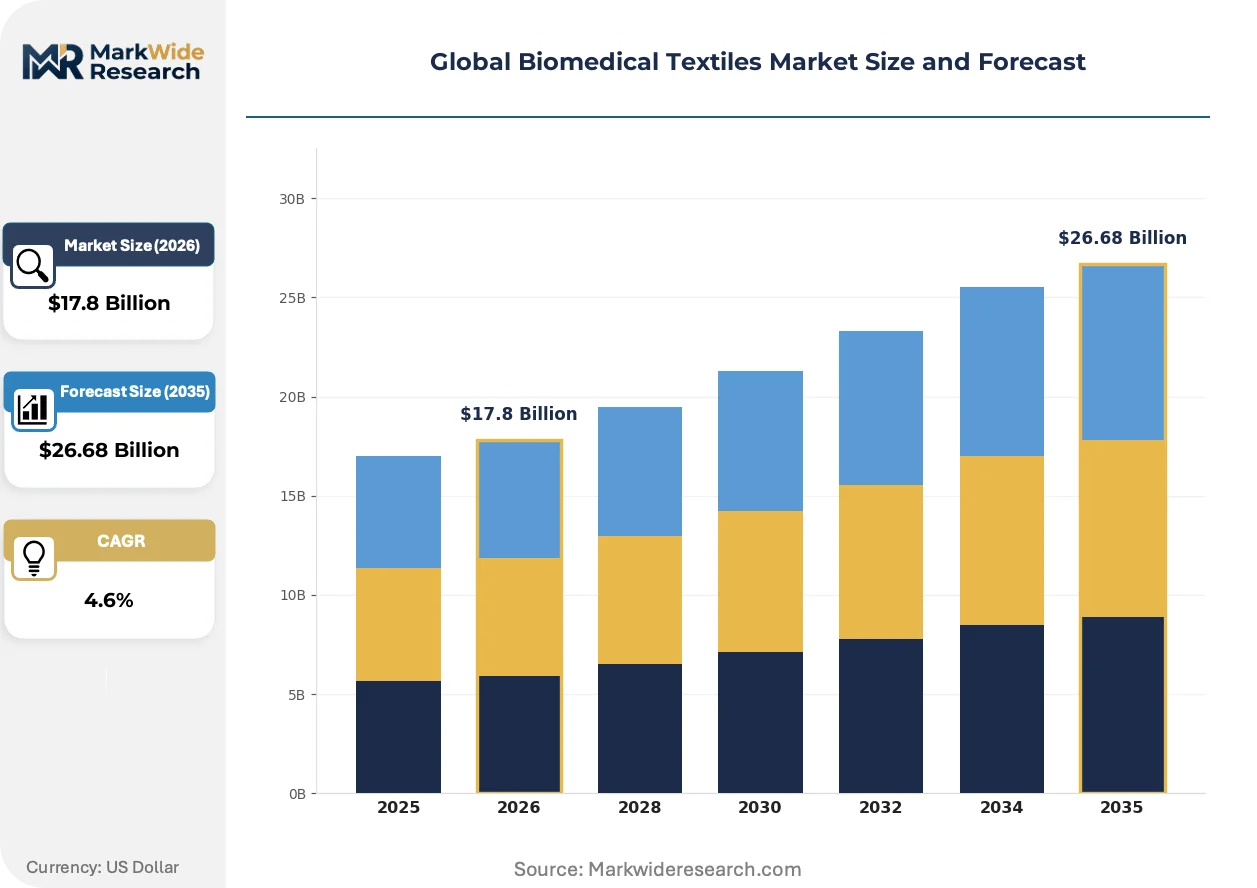
Market Dynamics
The EU MDR's reinforced notified body oversight and the FDA's Class III premarket approval pathway are compressing product development timelines for implantable textile constructions, forcing manufacturers to front-load biocompatibility testing and clinical validation costs before commercialization.
Growth Catalysts
- EU MDR compliance mandates:Stricter biocompatibility testing requirements under the Medical Device Regulation are accelerating material innovation cycles as manufacturers reformulate polymer substrates to meet enhanced safety standards for permanent implants.
- Vascular graft substitution:Polyester and polytetrafluoroethylene constructions are displacing biological conduits in aortic and peripheral bypass procedures, expanding addressable surgical volumes across cardiovascular service lines.
- German medical device cluster concentration:The Freudenberg polymer research infrastructure anchors high-performance vascular graft substrate development, drawing specialized talent and capital equipment investment to Baden-Württemberg.
Market Restraints
- Polymer feedstock volatility:Polyester and polyurethane raw material costs fluctuate with crude oil derivatives, compressing margin pools for non-woven surgical drape manufacturers operating on fixed hospital procurement contracts.
- Notified body capacity bottlenecks:EU MDR implementation has reduced the number of designated conformity assessment bodies, extending certification timelines for novel implantable textile constructions by 12-18 months.
- Biological conduit persistence:Autologous vein grafts retain preference in distal coronary and below-knee revascularization, limiting synthetic textile penetration in small-diameter vascular applications.
Strategic Opportunities
- Absorbable polymer degradation profiles:The FDA's evolving guidance on resorbable implantable materials creates first-mover advantage for manufacturers validating controlled degradation kinetics in orthopedic reinforcement applications.
- Swiss orthopedic textile hub expansion:The dsm-firmenich European operations cluster near Basel offers concentrated polymer science expertise for next-generation suture and mesh development targeting sports medicine.
- REACH-compliant fluoropolymer alternatives:Anticipated EU restrictions on per- and polyfluoroalkyl substances in implantable materials open substitution opportunities for silicone-coated and bioabsorbable barrier textiles.
Industry Challenges
- ISO 10993-18 chemical characterization expertise:The expanded testing matrix for extractables and leachables requires analytical chemistry capabilities scarce among mid-scale textile converters, forcing outsourcing or capability acquisition.
- Multi-site manufacturing qualification:FDA and EU MDR requirements for consistent process validation across production facilities complicate geographic diversification strategies for vascular graft substrate makers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomedical Textiles Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Coated Textiles Application: Wound Care, Orthopedic Implants, Surgical Drapes, Vascular Grafts End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutes Material Composition: Polyester, Polyurethane, Polyamide, Polytetrafluoroethylene, Silicone |
| Companies Covered | Freudenberg Performance Materials, B. Braun SE, Cardinal Health, Medline Industries LP, ATEX Technologies Inc., Bally Ribbon Mills, Cortland Biomedical, dsm-firmenich, Elkem ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomedical Textiles Market Shifts & Advancements
Electrospinning and 3D textile knitting architectures are transforming pore size calibration precision, enabling cellular infiltration control that was previously unattainable through traditional weaving processes.
Electrospun nanofiber scaffolds are automating the production of vascular graft substrates with pore sizes below 50 microns, eliminating manual layer assembly. Cardiovascular device manufacturers in Germany and Switzerland are adopting these systems at pilot scale. The technology is automating quality control throughput, compressing batch release timelines from weeks to days.
REACH chemical substance registrations are reshaping raw material selection across polyester, polyurethane, and silicone supply chains, forcing reformulation of legacy implantable textile constructions. ECHA's expanded authorization requirements for CMR substances are accelerating substitution programs for phthalate-based plasticizers in blood-contacting devices. Woven orthopedic reinforcement manufacturers are responding by qualifying bio-based polyester alternatives ahead of regulatory deadlines.
Hospital procurement consolidation is compressing supplier bases for disposable surgical drape fabrics, with US health systems centralizing contracts through group purchasing organizations. Cardinal Health and regional distributors are disintermediating smaller textile converters that lack scale to meet consolidated volume and compliance requirements. This concentration is most visible in the southeastern United States, where hospital network mergers have reduced active vendor pools by 40 percent.
Global Biomedical Textiles Market Segmentation
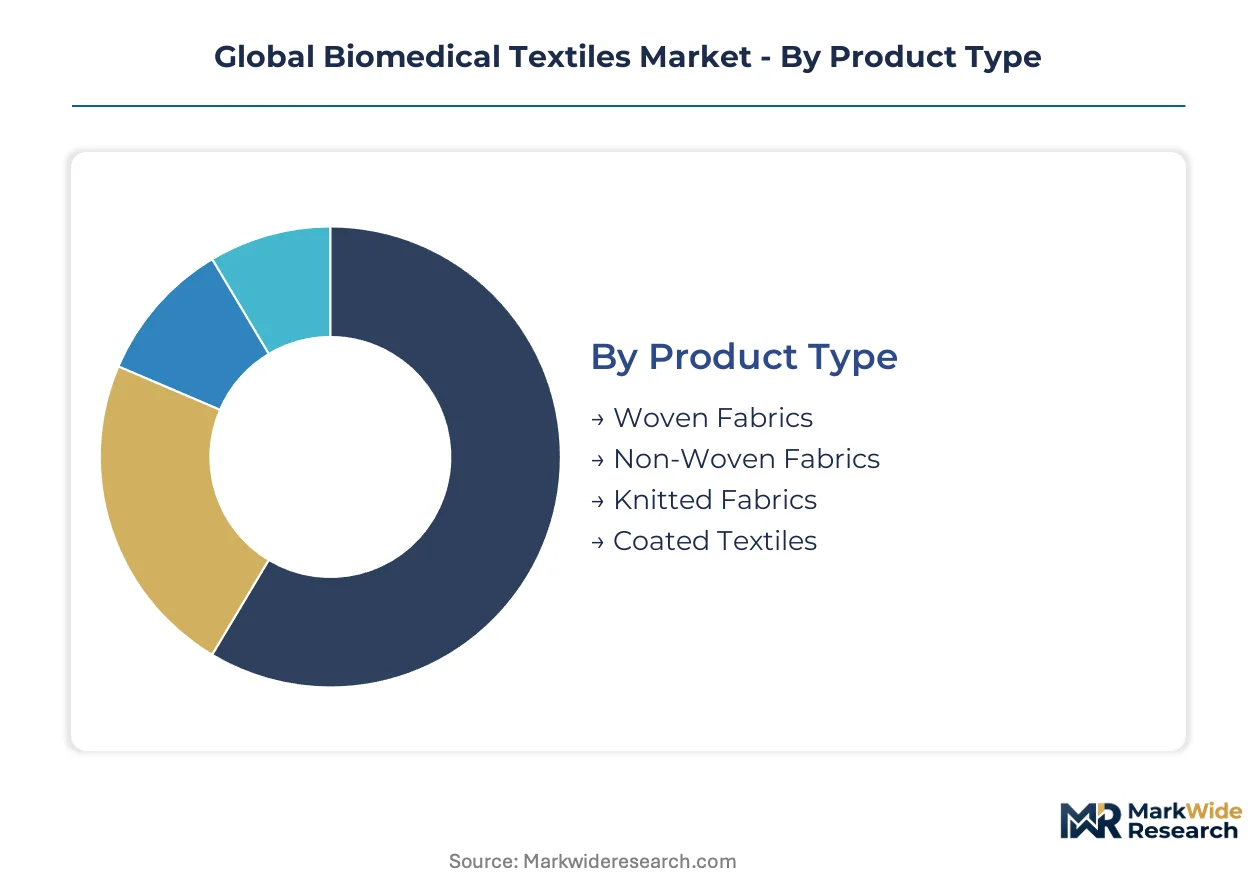
Biomedical textile segmentation reflects divergent manufacturing economics between high-volume disposable products and precision-engineered implantable constructions. Each category demands distinct polymer science capabilities, regulatory pathways, and capital intensity profiles that shape competitive positioning across the value chain.
Product Type:
Customization intensity varies sharply across this category, from commodity non-wovens produced at scale to patient-specific coated textiles requiring batch-level specification control.
- Woven Fabrics:These multi-layer constructions deliver tensile strength exceeding 50 MPa through interlaced yarn architectures, serving orthopedic implant reinforcement where mechanical durability under cyclic loading is non-negotiable. Demand concentrates in Switzerland's orthopedic textile cluster near Basel, where dsm-firmenich polymer expertise supports sports medicine applications requiring suture and mesh differentiation.
- Non-Woven Fabrics:Melt-blown and spunbond processes generate pore sizes between 10 and 500 microns for controlled barrier properties, dominating disposable surgical drapes and wound dressings where single-use protocols drive procurement. US hospital systems are consolidating vendor pools through group purchasing organizations, disintermediating smaller converters lacking compliance scale.
- Knitted Fabrics:Loop-structured architectures provide elasticity and conformability for soft tissue support applications.
- Coated Textiles:Surface-modified substrates incorporate silicone or bioactive layers for blood-contacting device performance.
Most installed capacity flows through Non-Woven Fabrics. Expansion is steepest in Coated Textiles.
Application:
Margin architecture separates this category, with implantable constructions commanding premium pricing against commoditized sterile barrier products.
- Vascular Grafts:Polyester and polytetrafluoroethylene constructions displace biological conduits in aortic and peripheral bypass procedures, with pore architecture calibrated to prevent hemorrhage while enabling tissue ingrowth. Germany's Freudenberg polymer research infrastructure anchors substrate development, drawing specialized talent and capital equipment to Baden-Württemberg.
- Wound Care:Absorbent non-woven dressings and antimicrobial textiles manage exudate and infection risk across acute and chronic wound protocols. Procurement concentrates in European hospital networks where EU MDR biocompatibility testing requirements are accelerating material reformulation cycles.
- Orthopedic Implants:Load-bearing textile reinforcements integrate with metallic fixation systems for ligament and tendon repair.
- Surgical Drapes:Sterile barrier fabrics protect operative fields from microbial contamination during invasive procedures.
Volume leadership sits with Wound Care. Value expansion is climbing fastest in Vascular Grafts.
End User:
Procurement sophistication tiers this category, from centralized hospital supply chains to fragmented research procurement with divergent specification requirements.
- Hospitals:Integrated health systems drive consolidated contracting for implantable textiles and disposable surgical supplies, with FDA Class III premarket approval requirements filtering supplier bases to established manufacturers with clinical validation resources. US southeastern networks have reduced active vendor pools substantially through merger-driven procurement centralization.
- Clinics:Outpatient surgical centers source standardized wound care and minor procedure textiles through distributor channels with limited technical specification involvement.
- Diagnostic Laboratories:Controlled environment applications demand sterile textile barriers with validated particulate filtration performance.
- Research Institutes:Preclinical and prototype textile development requires flexible small-batch production with extensive material characterization support.
Procurement volume concentrates in Hospitals. Specification complexity is expanding most quickly in Research Institutes.
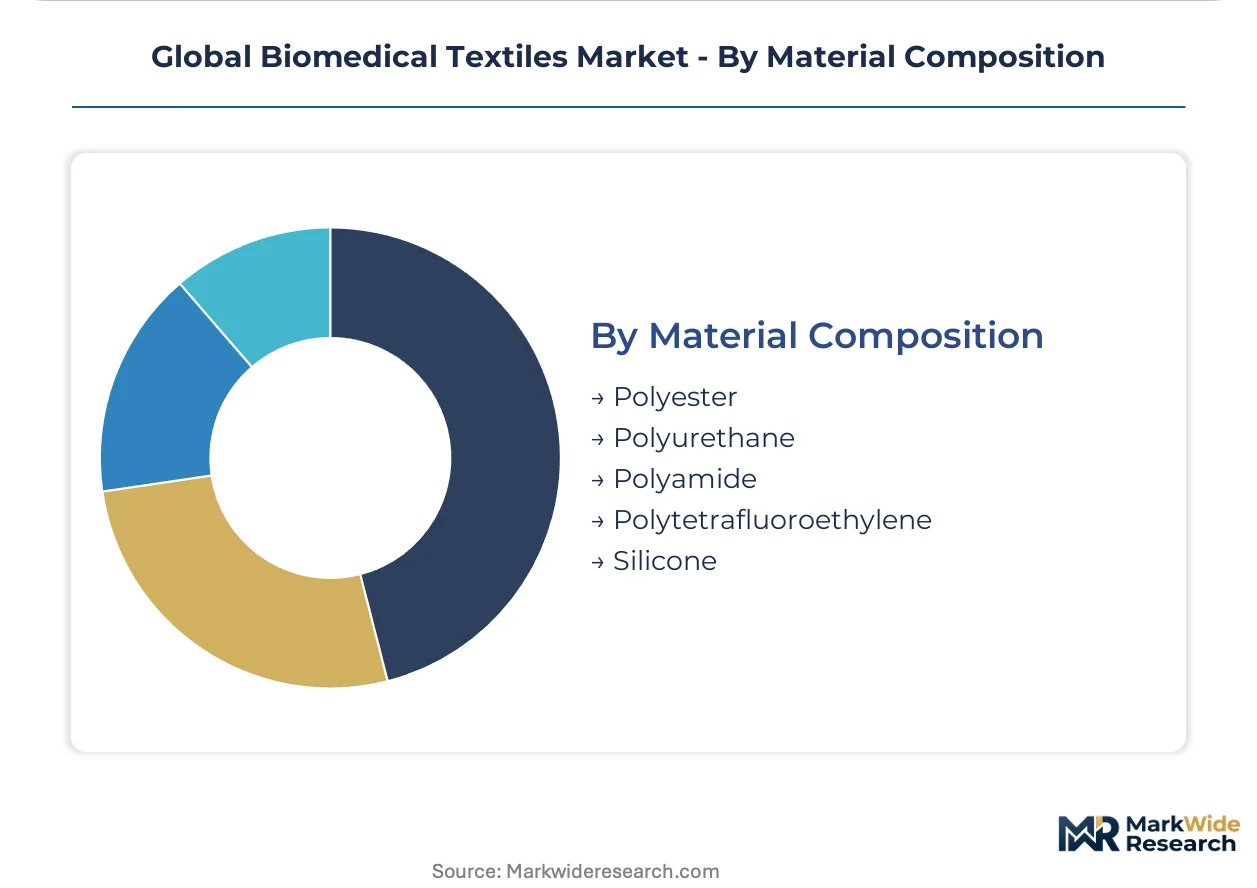
Material Composition:
Regulatory exposure to REACH chemical registrations and FDA biocompatibility pathways differentiates material selection economics across this category.
- Polyester:PET and PBT variants provide hydrolytic stability and mechanical strength for permanent implants and surgical meshes, with bio-based alternatives gaining qualification momentum ahead of ECHA authorization deadlines for legacy plasticizers. Woven orthopedic reinforcement manufacturers in Germany are accelerating substitution programs.
- Polytetrafluoroethylene:Expanded PTFE structures deliver microporous blood-contacting surfaces with exceptional chemical inertness, though anticipated EU restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer alternative development. Swiss and German cardiovascular device manufacturers are piloting silicone-coated substitutes.
- Polyurethane:Segmented elastomers balance compliance and durability in catheter and wound dressing applications.
- Polyamide:Nylon constructions offer abrasion resistance and knot security for suture applications.
- Silicone:Cross-linked polydimethylsiloxane provides biocompatible barriers and soft tissue approximations with minimal inflammatory response.
Production scale concentrates in Polyester. Reformulation urgency is accelerating fastest in Polytetrafluoroethylene.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing biomedical textile manufacturing toward jurisdictions with established polymer science infrastructure and streamlined device approval pathways. Manufacturers are relocating high-value vascular graft substrate production to clusters where EU MDR notified body density and FDA premarket approval expertise concentrate.
Germany
Cardiovascular implant demand from university hospital networks in Baden-Württemberg and Bavaria drives substrate development. The EU MDR's reinforced notified body oversight accelerates material innovation cycles as Freudenberg Performance Materials leverages regional polymer research infrastructure. Stuttgart anchors high-performance vascular graft manufacturing, drawing specialized extrusion equipment investment from Swiss and Austrian suppliers.
United States
Hospital procurement consolidation across southeastern health systems compresses vendor pools for disposable surgical drape fabrics. FDA Class III premarket approval requirements filter implantable textile suppliers to established manufacturers with clinical validation resources. Minneapolis and Cleveland host concentrated orthopedic textile development for sports medicine applications.
Switzerland
Precision implant manufacturing for orthopedic reinforcement commands premium positioning in Basel and Zurich medical device clusters. Swissmedic's streamlined quality system assessments attract EU MDR transition projects from manufacturers fleeing notified body bottlenecks elsewhere. The dsm-firmenich polymer science hub near Basel supports next-generation suture and mesh qualification.
China
Domestic vascular graft demand from tier-one hospital cardiovascular service lines outpaces local polyester substrate supply. NMPA's updated Class III implantable device guidance extends clinical trial requirements for permanent blood-contacting textiles. Shanghai and Suzhou concentrate foreign-invested manufacturing joint ventures targeting import substitution in woven orthopedic reinforcements.
India
Cost-sensitive wound care textile exports to Middle East and African hospital systems expand spunbond non-woven capacity. CDSCO's medical device rules harmonization with ISO 13485 quality standards attracts contract manufacturing inquiries from European brands. Ahmedabad and Mumbai host emerging surgical mesh converters serving domestic private hospital chains.
Global Biomedical Textiles Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers front-load biocompatibility testing infrastructure ahead of EU MDR enforcement deadlines. The vendor base stratifies between integrated polymer-to-device conglomerates, specialized textile converters, and regional distribution platforms. Three archetypes define positioning: captive research-to-manufacturing operators, compliance-scale procurement aggregators, and niche substrate technology licensors. M&A activity concentrates on analytical chemistry capabilities for ISO 10993-18 extractables testing, while strategic partnerships bridge fluoropolymer alternative development gaps.
Among European integrated materials groups, Freudenberg Performance Materials and dsm-firmenich occupy positions spanning polymer research through finished substrate supply. B. Braun SE exemplifies the captive manufacturing archetype, controlling surgical mesh and suture textile production for hospital network distribution. Cardinal Health represents the procurement-scale aggregator model, competing on consolidated contracting across US health systems for disposable surgical drape fabrics.
| Leading Market Players |
|---|
| Freudenberg Performance Materials |
| B. Braun SE |
| Cardinal Health |
| Medline Industries LP |
| ATEX Technologies Inc. |
| Bally Ribbon Mills |
| Cortland Biomedical |
| dsm-firmenich |
| Elkem ASA |
| Others |
Supply & Pricing Matrix
EU MDR biocompatibility testing mandates gate qualified supply access and premium-tier pricing for implantable textile manufacturers, forcing reformulation investments that stratify market positioning between certified substrate developers and commodity converters. REACH chemical substance registrations compound this filtering effect, concentrating margin capture among polymer science specialists with validated analytical chemistry capabilities.
Pricing Analysis
Distributor margin compression in US hospital procurement channels intensifies price competition for disposable surgical drape fabrics, while direct-to-OEM contracting preserves premium positioning for vascular graft substrates. Three-tier pricing structure across premium, standard, and economy levels separates FDA Class III validated implantable constructions from CE-marked mid-tier products and unbranded commodity wound dressings. Pricing pressure stems from polymer feedstock volatility tied to crude oil derivatives, squeezing fixed-contract non-woven manufacturers. Group purchasing organizations exhibit highest price sensitivity, while cardiovascular device OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Polyester and polytetrafluoroethylene resin supply rests on German, Chinese, and US specialty chemical producers with polymerization capabilities for medical-grade purity. Raw material dependencies span high-tenacity PET chips, expanded PTFE membranes, and silicone elastomer precursors. Single-source vulnerability concentrates in fluoropolymer feedstocks ahead of anticipated EU per- and polyfluoroalkyl substance restrictions. Distribution runs through regional medical device distributors for disposable products and direct mill-to-OEM partnerships for implantable substrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomedical textiles offer margin expansion through absorbable polymer premium-tier substitution and automated electrospinning cost-down capture. Reformulation urgency around REACH-compliant alternatives creates temporary pricing power for qualified suppliers.
For Market Incumbents: Deploy ISO 10993-18 analytical chemistry capabilities as a defensive moat against mid-scale converters facing outsourcing pressure from EU MDR extractables testing requirements. Acquire electrospinning automation assets to compress batch release timelines and defend vascular graft substrate positioning against emerging nanofiber technology licensors. Consolidate notified body relationships to navigate certification bottlenecks that disadvantage smaller competitors. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with European brands seeking CDSCO-compliant production for Indian private hospital chains, bypassing capital-intensive polymer research infrastructure. Target absorbable orthopedic reinforcement applications where FDA guidance evolution creates first-mover validation windows. Penetrate through bio-based polyester alternatives ahead of ECHA authorization deadlines for legacy plasticizers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale textile converters with ISO 13485 quality systems because EU MDR compliance costs are forcing vendor base consolidation among hospital procurement networks. Long-term viability favors analytical chemistry capability platforms over commodity non-woven capacity. Watch electrospinning patent litigation activity as inflection indicator for nanofiber scaffold commercialization timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Qualification | Accelerates market access for vascular graft substrate developers with established conformity assessment partnerships in Germany. |
| Electrospinning Capacity Installation | Compresses quality control timelines from weeks to days for cardiovascular device manufacturers in Swiss and German clusters. |
| REACH-Compliant Fluoropolymer Substitution | Opens silicone-coated barrier textile opportunities ahead of EU per- and polyfluoroalkyl substance restrictions. |
| Hospital GPO Contract Consolidation | Disintermediates smaller surgical drape converters lacking compliance scale across US southeastern health systems. |
| Bio-Based Polyester Qualification | Secures orthopedic reinforcement supply continuity ahead of ECHA authorization deadlines for phthalate-based plasticizers. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down polymer substrate production tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and vascular graft product directors combined with secondary validation from FDA 510(k) and PMA filings, EUDAMED device registrations, and hospital procurement database extracts. Triangulation across these sources ensures segmentation accuracy for woven, non-woven, knitted, and coated textile categories.
Historical trendline analysis of cardiovascular surgical procedure volumes and orthopedic implant unit shipments anchors the projection framework. Segmentation modeling spans product type, application, end user, and material composition dimensions across the analysis window. CAGRs derive from regression analysis against procedure growth rates, regulatory approval timelines, and polymer feedstock cost trajectories. Forecast inputs incorporate EU MDR transition progress, notified body capacity constraints, and electrospinning technology adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU per- and polyfluoroalkyl substance restriction timelines or FDA absorbable polymer guidance revisions. Assumptions reflect current regulatory enforcement patterns and hospital procurement consolidation trajectories. Material deviation in fluoropolymer substitution timelines or notified body capacity recovery warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market