
 Global Nonwoven Disposable Gloves Market | 2026-2036
Global Nonwoven Disposable Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nonwoven Disposable Gloves Market Foresight
Biodegradable polymer formulations is reconfiguring material selection across nonwoven disposable glove production, forcing manufacturers to reformulate synthetic blends without sacrificing barrier performance. Cleanis SASU leverages European sustainability mandates to anchor its position in compostable glove development. Hefei Telijie Sanitary Material Co., Ltd. sustains cost leadership through integrated polyethylene resin processing. BODY Products GmbH differentiates via specialized nitrile formulations for chemical-resistant industrial applications.
Nonwoven disposable gloves consist of bonded synthetic or natural fibers—typically polyethylene, latex, vinyl, or nitrile—manufactured through spunbond, meltblown, or needle-punch processes without traditional textile weaving, creating seamless barriers against contaminants, chemicals, and biological hazards for single-use protection across medical, food handling, and industrial settings. Examination gloves dominate volume throughput due to standardized hospital procurement protocols, while nitrile material commands premium positioning as latex allergy concerns reshape healthcare purchasing. Surgical gloves retain concentrated margin pools through sterilization certification requirements and specialized thickness tolerances that limit supplier qualification.
FDA medical device regulations govern barrier performance testing and biocompatibility standards for US-bound nonwoven disposable gloves, while REACH compliance in Europe restricts phthalate plasticizers in vinyl formulations. The EU Green Deal's packaging waste directives are accelerating fiber-to-fiber recyclability requirements. China's NMPA enforces sterility assurance levels for imported medical-grade products. Stakeholders must monitor evolving polymer substitution timelines as regulatory bodies tighten petrochemical-derived material restrictions across major import jurisdictions.
Market Dynamics
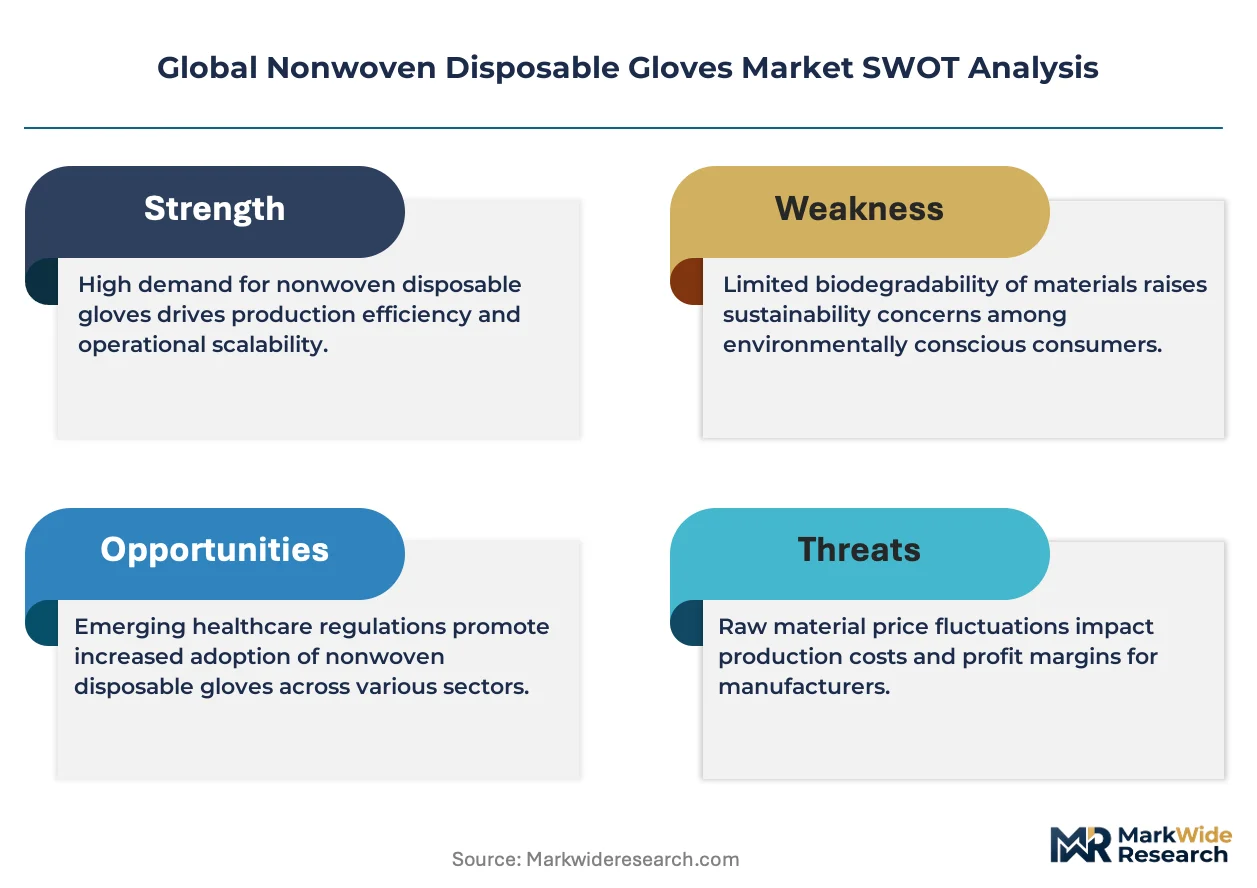
Biodegradable polymer substitution is compressing traditional polyethylene resin economics while forcing manufacturers to rebuild barrier performance specifications from molecular architecture upward.
Growth Catalysts
- EU Green Deal packaging directives:Compostability mandates across European healthcare procurement are redirecting R&D budgets toward fiber-to-fiber recyclable formulations. German hospital networks now require biodegradability certifications in tender specifications.
- Nitrile allergy migration:Latex sensitization rates in Southeast Asian manufacturing clusters are accelerating synthetic alternative qualification. Vietnam's foreign-owned electronics assembly plants specify nitrile-only protocols for cleanroom operations.
- FDA updated medical glove standards:Tighter barrier integrity testing for US-bound imports is consolidating supplier qualification pools. Malaysian and Thai manufacturers are investing in automated defect detection to maintain access.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress polyethylene glove margins. Integrated resin producers maintain cost advantages over compound-dependent competitors.
- Single-source sterilization infrastructure:Gamma irradiation capacity concentrates in industrial zones near Bangkok and Shanghai. Regional supply disruptions propagate immediately to finished glove availability.
- REACH phthalate restrictions:European vinyl formulation constraints limit plasticizer options for cost-sensitive food service segments. Alternative plasticizers raise unit costs without matching elasticity performance.
Strategic Opportunities
- India's PLI scheme for medical textiles:Domestic manufacturing incentives are attracting glove production investment away from established Southeast Asian bases. Maharashtra and Gujarat industrial corridors offer tariff advantages for export-oriented units.
- Home healthcare expansion:Post-acute care settings in Japan and South Korea are adopting examination-grade gloves for non-traditional applications. METI reimbursement codes now cover disposable protection for at-home nursing.
- Spunbond-meltblown composite integration:Hybrid nonwoven structures combining spunbond strength with meltblown filtration are opening industrial chemical protection segments previously reserved for woven alternatives.
Industry Challenges
- ISO 13485 medical device quality management certification:Small and mid-sized manufacturers face 12-18 month qualification timelines for surgical-grade production. Auditor capacity constraints in Southeast Asia extend approval cycles.
- Legacy vinyl compound reformulation:Substituting phthalate plasticizers requires recalibrating entire production lines for tensile strength and elongation specifications. Validation testing delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nonwoven Disposable Gloves Market |
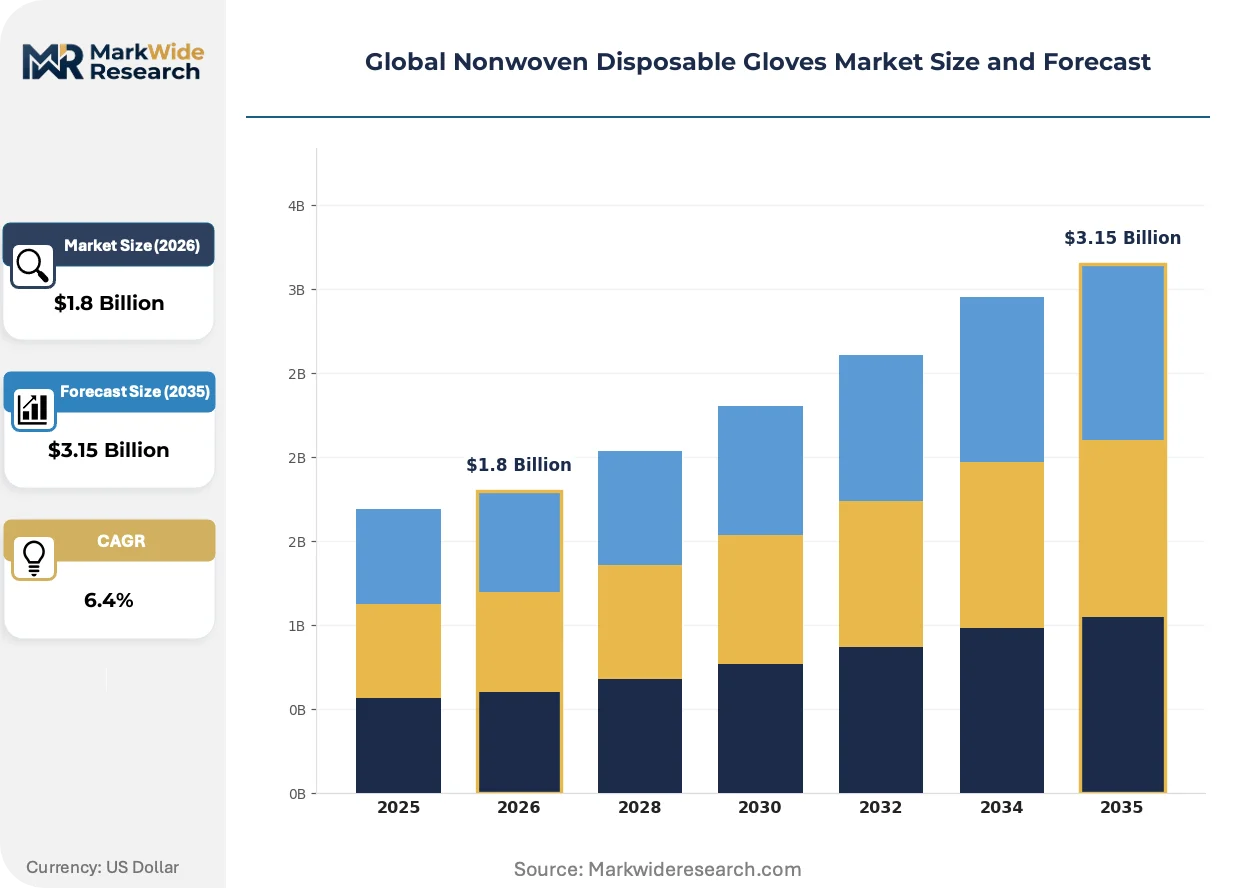
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gloves, Examination Gloves, Cleaning Gloves, Industrial Gloves Material: Polyethylene, Latex, Vinyl, Nitrile End User: Healthcare Facilities, Food Industry, Automotive Sector, Household Distribution Channel: Online Retail, Medical Supply Stores, Supermarkets, Wholesale Distributors |
| Companies Covered | A.M.G. Medical, Inc., Cleanis SASU, Mediberg S.r.l., Medical Depot, Inc., Hefei Telijie Sanitary Material Co., Ltd., BODY Products GmbH, Shanghai Dragon Medical Co., Ltd., Laian Yonghao Sanitary Material Co., Ltd., Riway Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nonwoven Disposable Gloves Market Shifts & Advancements
Material science convergence with automation is collapsing the traditional trade-off between barrier performance and environmental degradability that has governed procurement decisions for two decades.
Near-infrared spectroscopy inline inspection is digitizing quality assurance workflows across high-volume production lines. Malaysian manufacturers deploying these systems reduce defect escape rates to sub-hundredth-percent levels. Hospital procurement teams in Australia and the United Kingdom now require spectroscopic batch certification documentation.
REACH authorization procedures for persistent organic pollutants are tightening additive restrictions in vinyl glove formulations. European chemical safety assessments now classify certain stabilizers as substances of very high concern. Food service distributors across Germany and France are accelerating nitrile migration to preempt supply discontinuity.
Direct contracting between multinational hospital groups and certified manufacturers is compressing traditional medical distributor margins. Group purchasing organizations in the United States and hospital networks in Brazil are establishing quality-audited supplier panels. This channel restructuring concentrates volume with vertically integrated producers capable of sustained compliance documentation.
Global Nonwoven Disposable Gloves Market Segmentation
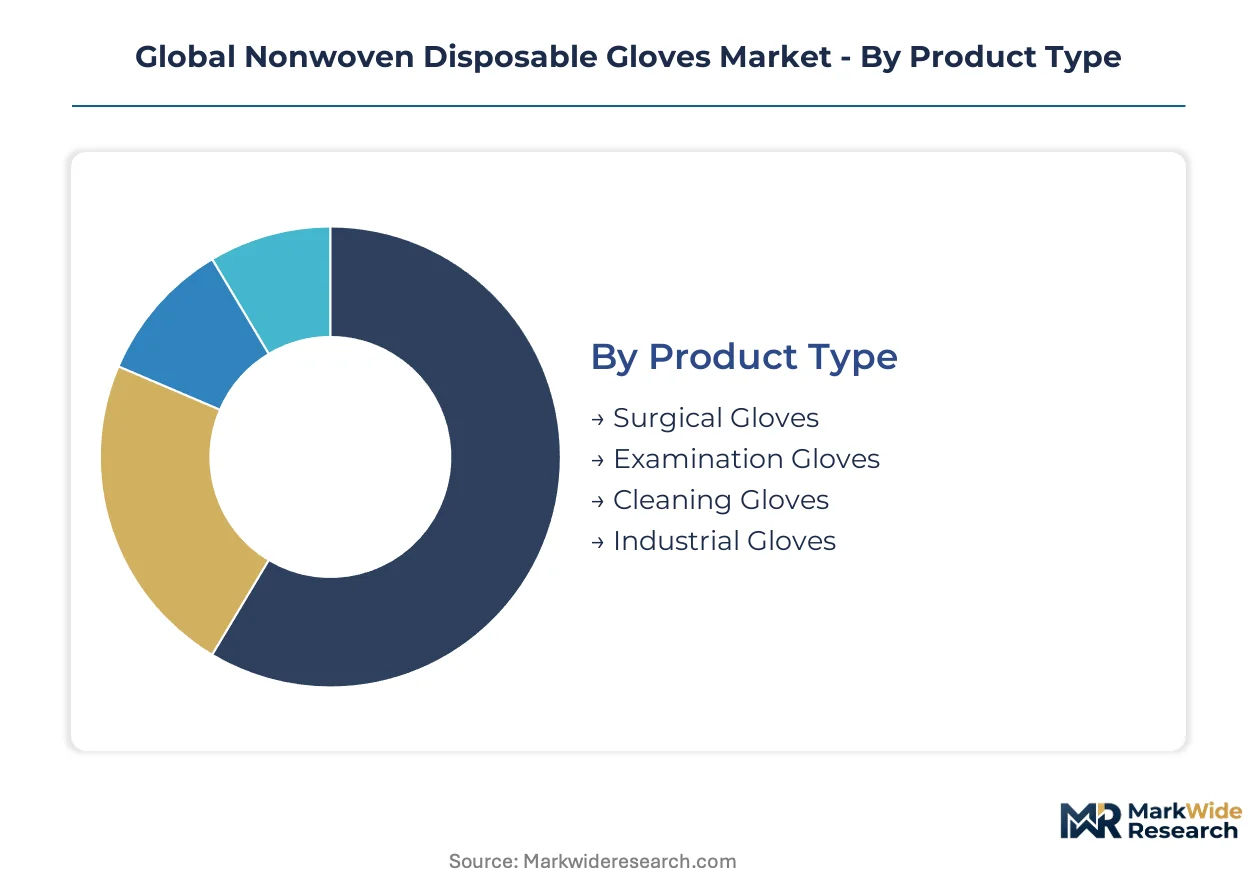
Segmentation in nonwoven disposable gloves reveals how procurement specifications diverge across sterilization requirements, chemical resistance needs, and channel access patterns. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier qualification.
Product Type:
Application intensity and certification depth separate these tiers, with sterile processing requirements creating steep entry barriers at the top.
- Examination Gloves:Non-sterile single-use barriers manufactured from nitrile, latex, or vinyl for diagnostic and general patient contact. Hospital procurement protocols in Vietnam and Thailand standardize bulk purchasing of examination-grade products, with FDA's updated barrier integrity testing consolidating supplier pools toward automated defect detection systems.
- Surgical Gloves:Sterilized hand coverings meeting ISO 13485 quality management and specialized thickness tolerances for invasive procedures. German hospital networks and Japanese surgical centers enforce gamma irradiation certification, limiting qualified suppliers to manufacturers with captive sterilization infrastructure near Bangkok or Shanghai industrial zones.
- Industrial Gloves:Chemical-resistant formulations for manufacturing and laboratory environments.
- Cleaning Gloves:Household and commercial sanitation applications with lower barrier specifications.
Examination gloves command the established base. The steepest expansion runs through surgical gloves as hospital networks tighten quality-audited supplier panels.
Material:
Polymer substitution timelines and feedstock economics determine competitive positioning across these formulations.
- Nitrile:Synthetic rubber compound delivering superior puncture resistance and eliminating latex protein allergens. Electronics assembly plants in Vietnam's foreign-owned manufacturing zones specify nitrile-only protocols for cleanroom operations, with latex sensitization rates accelerating synthetic alternative qualification across Southeast Asian industrial clusters.
- Polyethylene:Thermoplastic resin processed through spunbond or meltblown methods for cost-sensitive high-volume applications. Integrated resin producers in China maintain margin advantages over compound-dependent competitors, though EU Green Deal packaging directives are forcing reformulation toward biodegradable polymer architectures.
- Vinyl:PVC-based formulation facing REACH phthalate restrictions across European food service segments.
- Latex:Natural rubber compound declining in healthcare procurement due to allergen concerns.
Nitrile captures the premium positioning. Polyethylene maintains volume leadership despite sustainability pressures.
End User:
Regulatory jurisdiction and hygiene protocol stringency segment demand across these customer categories.
- Healthcare Facilities:Hospitals, clinics, and diagnostic centers requiring examination-grade or surgical-grade certification. Australia's hospital procurement teams now mandate near-infrared spectroscopic batch certification, while Japan's METI reimbursement codes expanded coverage to post-acute care settings including at-home nursing applications.
- Food Industry:Processing, preparation, and service operations requiring compliance with national food contact regulations. FSSAI standards in India and FDA food contact notifications in the United States drive formulation specifications, with European distributors accelerating nitrile migration to preempt REACH-authorized plasticizer discontinuity.
- Automotive Sector:Assembly and maintenance operations with chemical exposure protection needs.
- Household:Consumer retail purchases for domestic cleaning and personal protection.
Healthcare facilities anchor procurement volume. Food industry applications are climbing the fastest as safety auditing intensifies across processing chains.
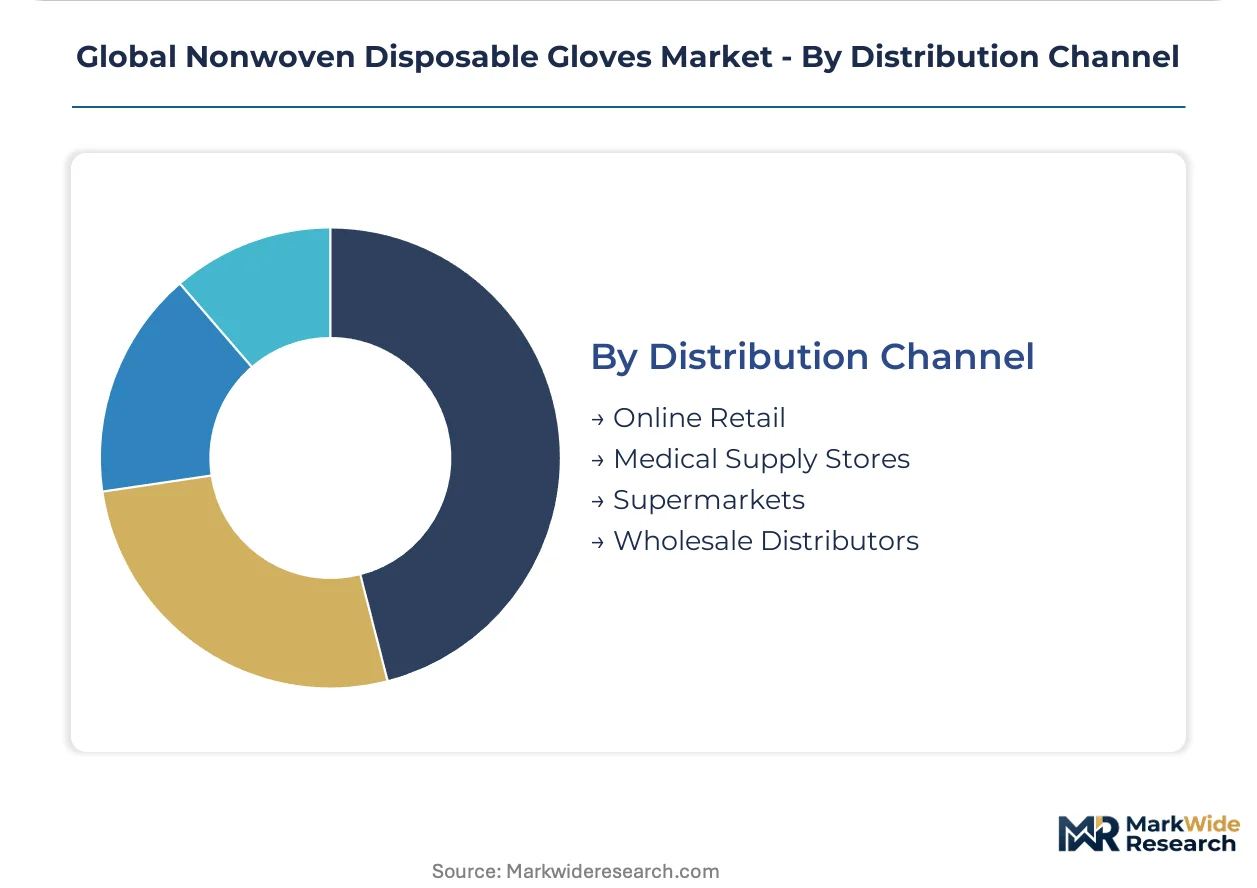
Distribution Channel:
Channel restructuring is compressing traditional intermediaries as volume concentrates with vertically integrated producers capable of sustained compliance documentation.
- Wholesale Distributors:Traditional medical supply intermediaries serving fragmented clinic and laboratory networks. Brazilian hospital networks and United States group purchasing organizations are establishing direct manufacturer contracts, eroding distributor margins while favoring suppliers with ISO 13485 certification and automated quality systems.
- Medical Supply Stores:Specialized retailers serving small-practice healthcare providers and dental clinics.
- Online Retail:E-commerce platforms capturing household and small-business procurement with transparent specification documentation.
- Supermarkets:Mass retail channels for consumer-grade cleaning and food preparation gloves.
Wholesale distributors retain the infrastructure base. Online retail is gaining share fastest as procurement digitization accelerates specification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Thai manufacturers dominate export flows to United States hospital networks, with gamma irradiation infrastructure clustering near Bangkok and Shanghai industrial zones serving as critical sterilization hubs for surgical-grade certification.
United States
FDA's updated medical glove quality standards are tightening barrier integrity testing for imported products, consolidating supplier qualification pools toward automated defect detection systems. Group purchasing organizations are establishing direct manufacturer contracts, compressing traditional medical distributor margins. Hospital procurement teams in the Southeast and Midwest now mandate near-infrared spectroscopic batch certification documentation.
Germany
EU Green Deal packaging waste directives are accelerating fiber-to-fiber recyclability requirements across hospital networks. German hospital procurement now requires biodegradability certifications in tender specifications, redirecting R&D budgets toward compostable formulations. Industrial zones in North Rhine-Westphalia host manufacturers reformulating synthetic blends without sacrificing barrier performance.
China
NMPA enforces sterility assurance levels for imported medical-grade products while domestic manufacturers leverage integrated polyethylene resin processing for cost leadership. Yangtze River Delta industrial corridors concentrate spunbond and meltblown production capacity. Shanghai-based facilities supply gamma irradiation services to regional finished glove producers.
Vietnam
Foreign-owned electronics assembly plants in manufacturing zones specify nitrile-only protocols for cleanroom operations, accelerating synthetic alternative qualification. Latex sensitization rates in industrial clusters are driving procurement shifts away from natural rubber formulations. Ho Chi Minh City and Hanoi industrial corridors anchor demand concentration under strict hygiene protocols.
India
PLI scheme for medical textiles is attracting glove production investment away from established Southeast Asian bases, with Maharashtra and Gujarat industrial corridors offering tariff advantages for export-oriented units. FSSAI standards drive food contact formulation specifications. Domestic manufacturing incentives are reshaping regional supply chain configurations.
Global Nonwoven Disposable Gloves Market Competitive Landscape
On the supply side, the industry is bifurcating between vertically integrated resin producers and compound-dependent specialists facing feedstock volatility pressures. Tiered competitive positioning separates scale-driven manufacturers with captive sterilization infrastructure from mid-sized players dependent on third-party gamma irradiation services. Strategic archetypes include integrated polymer processors, compostable formulation specialists, and chemical-resistant industrial application developers. Capacity expansion near Bangkok and Shanghai industrial zones and backward integration into polyethylene resin production represent dominant competitive moves.
Among European sustainability-focused developers, Cleanis SASU occupies a position exemplifying compostable glove development archetypes under EU Green Deal mandates. Hefei Telijie Sanitary Material Co., Ltd. and BODY Products GmbH represent contrasting strategic positions—Chinese integrated processing capability versus German specialized industrial formulation expertise. Shanghai Dragon Medical Co., Ltd. anchors the scale-driven tier with apparent geographic concentration in Yangtze River Delta manufacturing corridors. These three entities collectively illustrate the geographic and technological diversification patterns reshaping supplier qualification pools.
| Leading Market Players |
|---|
| A.M.G. Medical, Inc. |
| Cleanis SASU |
| Mediberg S.r.l. |
| Medical Depot, Inc. |
| Hefei Telijie Sanitary Material Co., Ltd. |
| BODY Products GmbH |
| Shanghai Dragon Medical Co., Ltd. |
| Laian Yonghao Sanitary Material Co., Ltd. |
| Riway Group |
| Others |
Supply & Pricing Matrix
Single-source sterilization infrastructure dependency determines both pricing tier spreads and supply chain shape across nonwoven disposable glove markets. Gamma irradiation capacity clustering near Bangkok and Shanghai industrial zones creates captive supply premiums for surgical-grade certification while forcing examination-grade producers toward spot-market resin economics.
Pricing Analysis
Current-generation nitrile formulations command substantial premiums over prior-generation latex alternatives and next-generation biodegradable polymer architectures still validating barrier performance. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified surgical gloves from examination-grade hospital procurement and food-service polyethylene volumes. Price differentiation rests on certification depth and vertical integration status, with integrated resin producers capturing margin advantages over compound-dependent competitors. Pricing pressure stems from ethylene and propylene feedstock volatility compressing polyethylene glove margins, while food service segments exhibit highest price sensitivity due to cost-plus distributor contracts.
Supply Chain Analysis
Extended payment terms from multinational hospital groups now reach 90-120 days, forcing supply-chain finance facilities upon mid-tier manufacturers lacking balance-sheet depth. Manufacturing concentrates in Malaysia, Thailand, and China, with Yangtze River Delta and Bangkok industrial corridors anchoring spunbond-meltblown composite capacity. Raw material dependencies center on acrylonitrile-butadiene rubber for nitrile synthesis, ethylene feedstock for polyethylene resin, and phthalate plasticizers for vinyl formulations facing REACH restrictions. Single-source vulnerability runs through gamma irradiation infrastructure concentration. Distribution runs through direct contracting between hospital networks and certified manufacturers, compressing traditional wholesale distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable polymer substitution constitutes a high-growth disruption reshaping supplier qualification pools, with EU Green Deal mandates forcing molecular-architecture reinvestment across incumbent manufacturing bases.
For Market Incumbents: Harden barrier performance specifications for compostable formulations without sacrificing tensile strength validation timelines. Secure captive sterilization infrastructure near Bangkok or Shanghai industrial zones to defend surgical-grade certification access against emerging Indian PLI scheme competitors. ISO 13485 auditor capacity constraints in Southeast Asia threaten qualification cycle extensions. For New Entrants and Emerging Players: Build out spunbond-meltblown composite capabilities targeting industrial chemical protection segments previously reserved for woven alternatives. India's Maharashtra and Gujarat industrial corridors offer tariff-advantaged export platforms with underdeveloped nitrile-only cleanroom supply to electronics assembly plants. Pursue direct contracting relationships with Japanese home healthcare networks expanding METI-reimbursed at-home nursing applications. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors backward-integrated resin producers with biodegradable formulation pipelines. Five-to-ten year viability hinges on polymer substitution timelines outpacing petrochemical restriction acceleration. Monitor EU REACH authorization procedures for persistent organic pollutant classifications as signal for vinyl formulation discontinuity velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Certification | EU Green Deal tender mandates now require compostability documentation for German hospital network procurement. |
| Gamma Irradiation Capacity Expansion | Captive sterilization infrastructure near Bangkok industrial zones secures surgical-grade ISO 13485 qualification access. |
| Near-Infrared Spectroscopy Deployment | Australian hospital procurement teams now mandate spectroscopic batch certification for defect detection validation. |
| India PLI Scheme Manufacturing Base | Maharashtra and Gujarat corridors offer tariff advantages redirecting investment from established Southeast Asian bases. |
| Nitrile-Only Cleanroom Protocol Adoption | Vietnam electronics assembly plants specify synthetic alternatives as latex sensitization rates accelerate across industrial clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA medical device registration databases, EU ECHA REACH authorization filings, and NMPA sterility assurance documentation. Interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and polymer R&D directors informed demand-side validation. Customs trade data, SEC 10-K disclosures from listed manufacturers, and hospital supply chain databases provided supply-side triangulation. Bottom-up volume modeling across product type, material, and end-user segments was cross-checked against top-down macroeconomic drivers.
Forecast inputs include examination-grade versus surgical-grade certification penetration, nitrile substitution velocity against latex and vinyl alternatives, and regional regulatory enforcement intensity across the analysis window. Segmentation dimensions span sterilization requirement, chemical resistance specification, and channel access pattern. CAGRs were derived from regression analysis against healthcare expenditure trajectories and industrial manufacturing output indices. Polymer feedstock price volatility and gamma irradiation capacity utilization served as industry-specific sensitivity variables.
Stress conditions across ethylene-propylene price spreads, REACH authorization timelines, and FDA barrier integrity testing enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and biodegradability certification adoption curves. Macroeconomic contraction, accelerated petrochemical restrictions, or breakthrough barrier-performance validation for next-generation polymers would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Non Woven Fabric Making Machine Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Nonwoven Blanket Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Decking Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Absorbable Nonwoven Textiles Market