
 Pant Type Adult Diaper Market | 2026-2036
Pant Type Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Pant Type Adult Diaper Market Analytics
East Asian absorbent hygiene producers is restructuring capacity to serve aging populations across Japan, South Korea, and coastal China. Kimberly-Clark Corporation leverages its North American manufacturing footprint to sustain institutional contract dominance. Unicharm Corporation anchors its competitive position through deep distribution in Japanese pharmacies and eldercare channels. Ontex BV differentiates via private-label scale across European retail and healthcare procurement networks.
Pant type adult diapers are pull-up garments engineered with elasticized waistbands, leg cuffs, and layered superabsorbent polymer cores designed for ambulatory users requiring discreet continence management; the construction prioritizes skin breathability measured by moisture vapor transmission rates and secure fit during moderate activity. Disposable variants dominate volume due to infection control protocols in hospitals and long-term care, while eco-friendly and biodegradable segments capture premium positioning as European retailers enforce packaging reduction mandates. Super absorbent products command the strongest margin pools in institutional procurement, whereas low-absorbency lines face commoditization in mass retail channels.
FDA device classification for adult incontinence products shapes US market entry requirements and clinical channel access, while EU REACH and MDR frameworks govern chemical safety and medical device traceability across European supply chains. Japan's PMDA and METI coordinate standards for skin-contact materials and eldercare product subsidies that directly influence domestic demand patterns. Stakeholders must monitor regulatory divergence between biodegradability certification regimes and absorbency performance labeling standards as procurement criteria harden across institutional buyers.
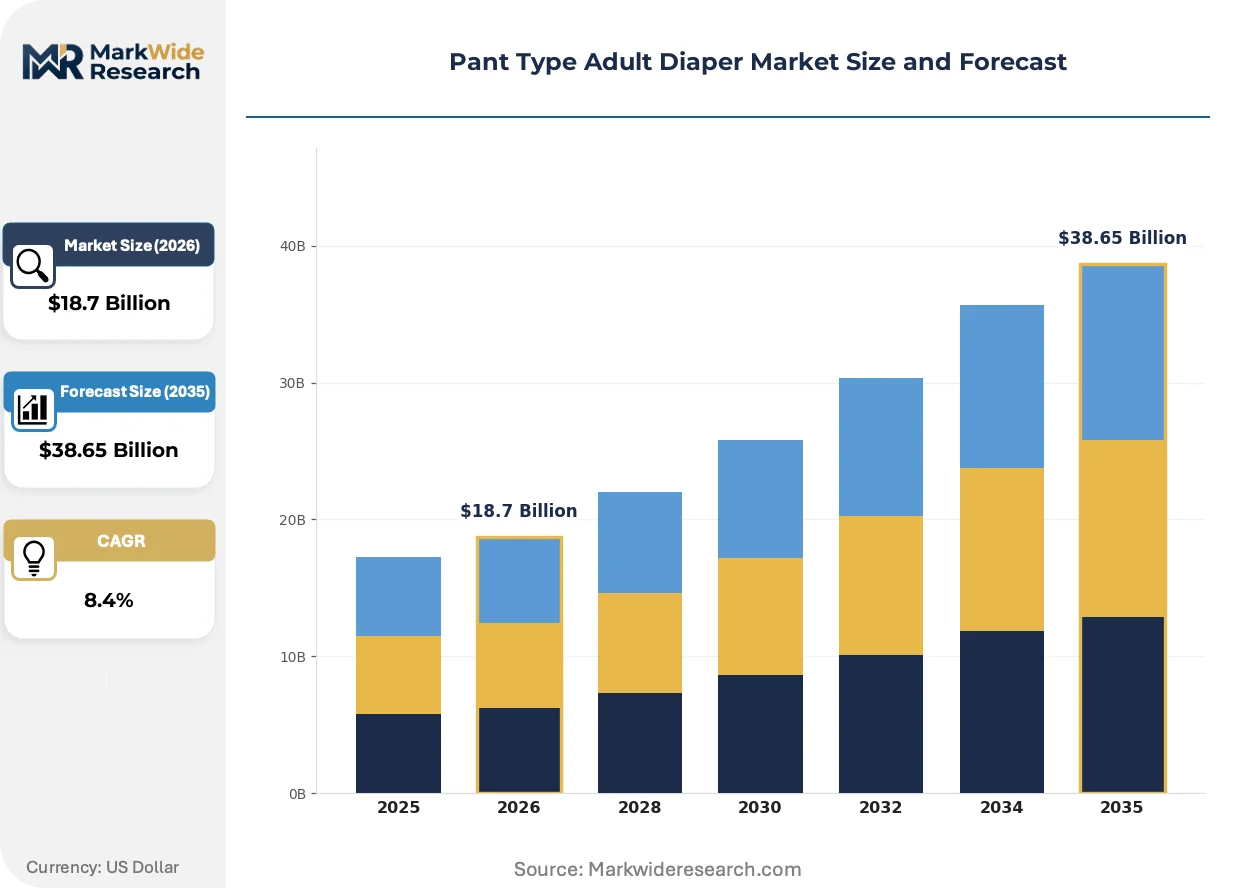
Market Dynamics
The pant type adult diaper market is being fundamentally restructured by EU biodegradability mandates under the EU Green Deal, which are forcing manufacturers to reformulate superabsorbent polymer cores while maintaining absorbency performance standards.
Growth Catalysts
- Japan's eldercare subsidy expansion:METI-coordinated reimbursement programs for skin-contact materials in long-term care facilities are accelerating institutional procurement volumes.
- Superabsorbent polymer reformulation:Next-generation biodegradable SAP technologies are opening premium positioning in European retail channels facing packaging reduction mandates.
- Coastal China hospital networks:Urban healthcare infrastructure expansion in provinces such as Zhejiang and Jiangsu is concentrating demand for disposable pull-up garments.
Market Restraints
- Petrochemical input volatility:Fluctuating propylene and acrylic acid prices compress margin pools for mid-tier manufacturers dependent on spot-market feedstock purchasing.
- East Asian supply concentration:Overreliance on Japanese and South Korean superabsorbent polymer producers creates vulnerability to regional logistics disruptions.
- REACH compliance friction:Extended chemical safety dossier requirements for skin-contact materials delay product registration timelines across EU member states.
Strategic Opportunities
- Indian institutional underpenetration:Nascent long-term care infrastructure in Maharashtra and Tamil Nadu offers first-mover positioning before domestic manufacturing scales.
- Home healthcare channel emergence:Direct-to-consumer subscription models for ambulatory seniors are bypassing traditional pharmacy distribution in North American markets.
- EU Green Deal procurement mandates:Public tender preferences for biodegradable-certified products are creating preferential access for compliant manufacturers in German and French eldercare systems.
Industry Challenges
- Polymer science talent scarcity:Shortages of formulation chemists specializing in biodegradability-absorbency trade-offs are extending R&D cycle timelines.
- Dual certification complexity:Simultaneous FDA device classification and EU MDR conformity assessment processes are straining regulatory affairs capacity.
- Legacy SAP integration:Retrofitting existing production lines for next-generation biodegradable cores requires substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pant Type Adult Diaper Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Eco-friendly, Biodegradable Age Group: Adults, Seniors, Middle-aged, Young Adults Distribution Channel: Retail Stores, Online Stores, Pharmacies, Hospitals Absorbency Level: Low, Medium, High, Super Absorbent |
| Companies Covered | Kimberly-Clark Corporation, Unicharm Corporation, Essity Aktiebolag, Kao Corporation, Procter & Gamble Company, First Quality Enterprises, Inc., Ontex BV, Daio Paper Corporation, Nippon Paper Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pant Type Adult Diaper Market Evolving Landscape
Material science breakthroughs and procurement model evolution are compressing traditional competitive advantages while elevating sustainability credentials as a primary ordering criterion across institutional buyers.
Plant-derived superabsorbent polymers derived from cellulose and starch matrices are converging with conventional petroleum-based SAPs in hybrid core formulations. Japanese and German manufacturers are piloting these blends in premium lines for pharmacy and eldercare channels. This convergence is compressing the performance gap between eco-friendly and conventional products, forcing price realignment across tiered positioning.
EU REACH annex amendments governing skin-contact chemical migration are tightening testing protocols for adult incontinence products. Manufacturers must now submit extended safety dossiers for polymer additives and fragrance components. The superabsorbent product segment faces the steepest compliance burden, driving consolidation among smaller private-label suppliers unable to absorb certification costs.
Hospital procurement consortia are consolidating vendor panels and demanding outcome-based performance guarantees for infection control and skin integrity metrics. Long-term care facilities in Japan and Germany are replacing transactional purchasing with multi-year framework agreements tied to resident satisfaction benchmarks. This behavioral shift is most visible in Kanagawa Prefecture and Bavaria, where integrated health systems are unbundling product supply from clinical service contracts.
Pant Type Adult Diaper Market Segmentation
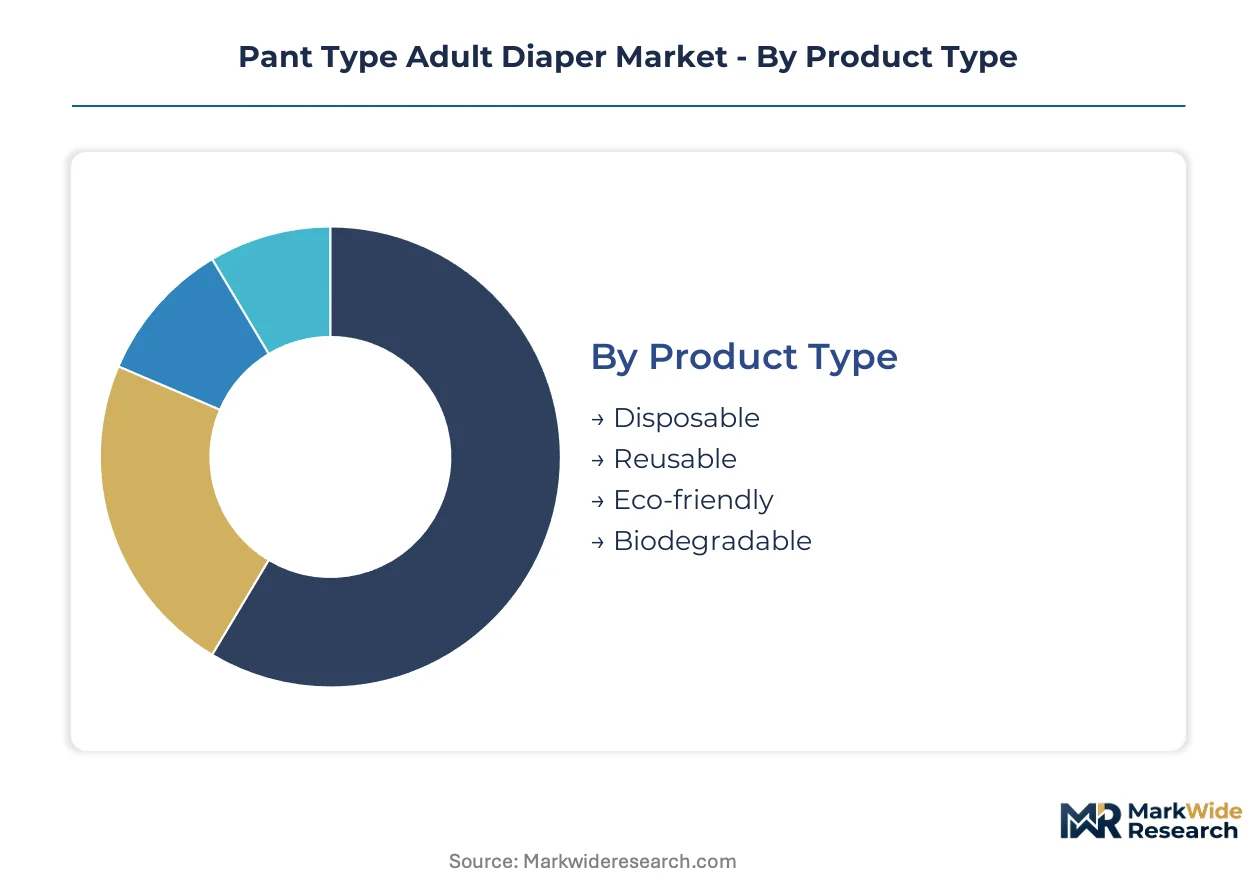
Pant type adult diaper segmentation reveals distinct performance requirements across ambulatory care settings. Product construction, user mobility profiles, and procurement channel economics create divergent margin structures that manufacturers must navigate.
Product Type:
Disposable formats dominate institutional procurement where infection control protocols mandate single-use protocols, while reusable and biodegradable variants occupy distinct cost-accounting frameworks.
- Disposable:Multi-layered cores with petroleum-based superabsorbent polymers engineered for moisture vapor transmission and secure fit during moderate activity. Demand concentrates in Japan's long-term care facilities where METI-coordinated subsidy programs accelerate procurement volumes as resident acuity rises.
- Reusable:Washable garments with moisture-wicking textile layers and elasticized retention systems designed for cost-per-use optimization. German and French home healthcare channels are expanding procurement as municipal eldercare budgets tighten and sustainability metrics enter purchasing criteria.
- Eco-friendly:Hybrid cellulose-starch core formulations targeting pharmacy premium positioning in EU markets facing packaging reduction mandates.
- Biodegradable:Plant-derived superabsorbent polymers certified under EU Green Deal procurement preferences for public tender access.
Disposable leads volumes today; biodegradable is gaining share fastest.
Age Group:
User physiology and mobility status determine absorbency requirements and garment construction priorities across demographic cohorts.
- Adults:Broad-spectrum pull-up designs accommodating active employment and social participation with discreet profiles. Coastal China hospital networks in Zhejiang and Jiangsu provinces are expanding procurement for post-surgical and neurological rehabilitation patients.
- Seniors:Maximum absorbency cores with skin integrity monitoring features for limited-mobility eldercare residents. Japanese long-term care facilities in Kanagawa Prefecture are standardizing procurement around resident satisfaction benchmarks tied to clinical outcomes.
- Middle-aged:Moderate-absorbency lines targeting workplace discretion and travel-oriented use cases.
- Young Adults:Slim-profile designs for athletic and active lifestyle positioning in direct-to-consumer channels.
Seniors command the largest procurement volumes; adults show the steepest expansion trajectory in institutional channels.
Distribution Channel:
Channel economics fragment pricing power between consolidated retail buyers and fragmented institutional procurement consortia.
- Retail Stores:Mass-market shelf placement driving volume through price-promotion cycles and private-label competition. European retail chains are enforcing packaging reduction mandates that favor eco-friendly product lines with certified sustainability credentials.
- Online Stores:Direct-to-consumer subscription models bypassing traditional pharmacy distribution in North American markets. Home healthcare channel emergence is compressing wholesale margin capture for incumbent distributors.
- Pharmacies:Clinical credibility positioning with pharmacist consultation attachment in Japanese and German markets.
- Hospitals:Outcome-based performance guarantees for infection control and skin integrity metrics under multi-year framework agreements.
Retail stores maintain volume leadership; online stores are climbing the fastest as subscription models penetrate ambulatory senior segments.
Absorbency Level:
Performance tiering aligns with clinical severity and reimbursement coding across institutional procurement systems.
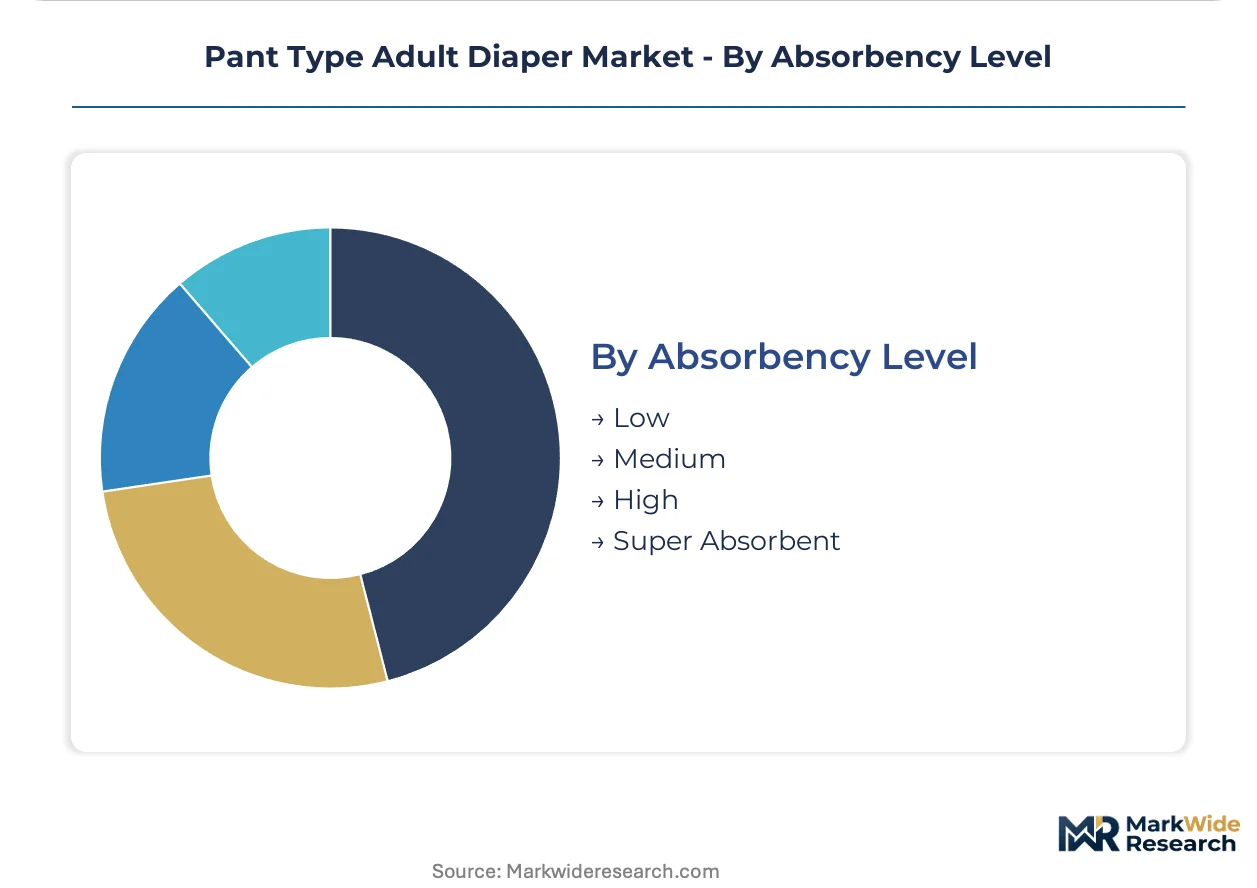
- Low:Light protection for stress incontinence and post-procedural recovery with minimal core thickness. Mass retail channels in commoditized positioning face margin compression from private-label substitution.
- Medium:Balanced capacity for daytime ambulatory use with breathability prioritization. Standard procurement tier for German and French eldercare systems under public tender specifications.
- High:Extended-wear cores for overnight and limited-toilet-access scenarios. Japanese long-term care facilities are consolidating vendor panels around high-absorbency lines with skin integrity outcome guarantees.
- Super Absorbent:Maximum retention polymers for severe incontinence and immobile resident care. EU REACH annex amendments impose the steepest compliance burden for additive and fragrance component dossiers.
Super absorbent commands premium margin pools; medium absorbency shows the fastest volume climb as procurement standardization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between EU biodegradability mandates and East Asian subsidy frameworks is fragmenting production location decisions. Manufacturers face a compliance-cost arbitrage where reformulation investments in Europe contrast with volume scaling opportunities in subsidized Asian eldercare markets.
Japan
Long-term care facilities in Kanagawa Prefecture are expanding pant type adult diaper procurement as resident acuity rises. METI-coordinated reimbursement programs for skin-contact materials accelerate institutional purchasing volumes. Tokyo anchors domestic manufacturing while Osaka channels distribute through pharmacy and eldercare networks.
Germany
Bavarian hospital procurement consortia are consolidating vendor panels around outcome-based performance guarantees. EU REACH annex amendments impose extended chemical safety dossier requirements for polymer additives. Frankfurt and Munich clusters concentrate private-label manufacturing for European retail distribution.
China
Coastal provinces of Zhejiang and Jiangsu are concentrating demand as urban hospital networks expand post-surgical rehabilitation services. SAMR and NMPA frameworks govern medical device traceability for institutional procurement. Shanghai anchors import distribution while local manufacturers scale capacity in the Yangtze River Delta.
United States
Direct-to-consumer subscription models are bypassing traditional pharmacy distribution in ambulatory senior segments. FDA device classification shapes clinical channel access and reimbursement coding. The Southeast manufacturing corridor sustains institutional contract fulfillment for long-term care chains.
India
Nascent long-term care infrastructure in Maharashtra and Tamil Nadu offers first-mover positioning before domestic manufacturing scales. CDSCO and BIS frameworks are evolving medical device standards for absorbent hygiene products. Mumbai and Chennai clusters concentrate import distribution and pilot eldercare procurement programs.
Pant Type Adult Diaper Market Competitive Landscape
East Asian producers anchor one tier; European specialists hold another through private-label scale and sustainability certification. The vendor base fragments across integrated multinationals, regional fabricators, and niche biodegradable innovators. Three archetypes dominate: subsidy-leveraged Japanese distributors, EU compliance-focused reformulators, and North American institutional contract holders. Competitive moves center on superabsorbent polymer reformulation partnerships and multi-year framework agreement negotiations with consolidated procurement consortia.
Among the named players, Kimberly-Clark Corporation exemplifies the North American institutional contract archetype through its manufacturing footprint and healthcare channel presence. Unicharm Corporation occupies a position within the Japanese subsidy-leveraged tier, anchored in pharmacy and eldercare distribution depth. Ontex BV represents the European private-label scale model, sitting within retail and healthcare procurement networks across EU member states.
| Leading Market Players |
|---|
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Essity Aktiebolag |
| Kao Corporation |
| Procter & Gamble Company |
| First Quality Enterprises, Inc. |
| Ontex BV |
| Daio Paper Corporation |
| Nippon Paper Industries Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Polymer formulation chemists concentrated in Japan's Kansai region and Germany's Rhine-Ruhr corridor command wage premiums that compress margin pools for mid-tier manufacturers, widening spreads between premium biodegradable lines and economy disposable tiers.
Pricing Analysis
Distributor margin layers in Japanese pharmacy channels absorb 18-25 points before eldercare facility delivery, while direct-to-consumer subscription models in North American markets bypass wholesale capture entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by absorbency certification and biodegradability credentials under EU Green Deal procurement preferences. Cost compression in economy lines intensifies as private-label substitution accelerates in European mass retail. Institutional buyers in German hospital consortia show lowest price sensitivity due to outcome-based contracting, whereas Indian municipal eldercare programs exhibit acute budget constraint.
Supply Chain Analysis
Ocean freight cost volatility from East Asian SAP producers to European conversion facilities has compressed landed margins for biodegradable core formulations. Superabsorbent polymer supply draws from Japanese, South Korean, and coastal Chinese petrochemical clusters, with cellulose-starch feedstocks sourcing from Nordic pulp and Southeast Asian cassava processors. Single-source vulnerability concentrates in acrylic acid derivatives from integrated Japanese refiners. Distribution runs through consolidated procurement consortia in Kanagawa Prefecture and Bavaria, with direct-to-consumer channels fragmenting last-mile economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on biodegradable SAP cost-down curves and premium-tier capture in EU public tender systems.
For Market Incumbents: Cement institutional contract dominance by securing multi-year framework agreements with Kanagawa and Bavarian eldercare consortia before biodegradable certification mandates harden. Deepen backward integration into plant-derived polymer feedstocks to defend margin position against petrochemical input volatility. Prioritize METI subsidy alignment in Japan and EU MDR conformity investment to maintain channel access. For New Entrants and Emerging Players: Begin with Maharashtra and Tamil Nadu institutional channels where long-term care infrastructure remains underpenetrated and domestic manufacturing has not scaled. Target medium-absorbency biodegradable lines for German municipal tender participation. Pursue direct-to-consumer subscription positioning in North American ambulatory senior segments to bypass entrenched pharmacy distribution. For Investors and Strategic Acquirers: European hygiene multinationals seeking EU Green Deal compliance are the most active acquirer in this space, driving valuations for biodegradable SAP innovators. Five-to-ten-year viability hinges on reformulation IP and certification dossier depth rather than volume scale. Watch for REACH annex amendment finalization as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable SAP Reformulation Partnership | Secures EU Green Deal tender access in German and French eldercare systems. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale margin capture in North American ambulatory senior segments. |
| Backward Integration into Plant-Derived Feedstocks | Reduces petrochemical cost exposure for premium eco-friendly product lines. |
| Multi-Year Framework Agreement Negotiation | Locks in volume with Kanagawa and Bavarian integrated health systems. |
| EU MDR Conformity Assessment Investment | Accelerates product registration timelines across REACH-regulated member states. |
Research Methodology
Direct dialogue with polymer formulation chemists, eldercare procurement managers, GPO contracts specialists, and retail category buyers grounded qualitative findings, cross-referenced with FDA 510(k) filings, EU MDR technical documentation, METI subsidy program records, and customs trade data for SAP feedstock flows. Bottom-up demand modeling triangulated with top-down macroeconomic validation.
Market size outputs and growth trajectories across the analysis window reflect segment-level modeling across product type, absorbency tier, distribution channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating METI reimbursement expansion rates, EU packaging mandate compliance timelines, and coastal China hospital procurement growth curves.
Several conditions sit outside the modeled scope, including abrupt petrochemical price shocks, trade restriction implementation, and polymer science talent migration patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Surgical Drapes Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market