
 Sanitary Napkin Market | 2026-2036
Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Napkin Market Intelligence
Consolidation among institutional buyers and pharmacy chains is recalibrating procurement leverage across the sanitary napkin value chain. Procter & Gamble leverages its manufacturing scale to secure favorable shelf placement in consolidated retail channels. Kimberly-Clark Corporation anchors North American supply reliability through regional production infrastructure. Essity competes in Europe by emphasizing sustainable material sourcing credentials.
A sanitary napkin is an absorbent personal hygiene product comprising a fluid-permeable top sheet, absorbent core of wood pulp and superabsorbent polymers, and leak-resistant back film, manufactured through continuous web-forming and heat-sealing processes to manage menstrual flow. Ultra-thin variants command premium positioning due to polymer innovation reducing bulk without compromising absorbency. Biodegradable materials represent the fastest-growing material segment as EU Green Deal requirements and consumer preference shift away from petrochemical backings. Supermarkets retain the largest distribution channel volume, though online channels capture disproportionate growth in subscription-based repeat purchases among adult users.
FDA regulates absorbent medical device classifications in the United States, while ECHA oversees chemical substance restrictions under REACH for European market access, and BIS enforces product safety standards for Indian domestic sales. These frameworks elevate compliance costs for new entrants but protect incumbent quality positions. Stakeholders must monitor evolving biodegradable certification requirements and pharmacy chain consolidation patterns to anticipate margin pressure points.
Market Dynamics
Pharmacy chain consolidation and biodegradable material mandates are compressing margins for mid-tier suppliers while rewarding scale players with compliance infrastructure. Retail shelf allocation now hinges on sustainability certification rather than brand recognition alone.
Growth Catalysts
- BIS Certification Expansion:India's tightening safety standards for feminine hygiene products are accelerating formalization of previously unregulated supply channels.
- Superabsorbent Polymer Innovation:Next-generation SAP formulations enable thinner cores without absorbency trade-offs, opening premium positioning in tropical climates.
- Rural Distribution Maturation:Last-mile networks in Indonesia and Nigeria now reach district-level pharmacies previously served only by informal vendors.
Market Restraints
- Wood Pulp Cost Volatility:Fluctuations in northern European pulp supply inflate raw material unpredictability for absorbent core manufacturers.
- REACH Compliance Burden:ECHA chemical substance restrictions elevate testing costs for petrochemical-based back film producers seeking European market access.
- Menstrual Cup Substitution:Reusable silicone alternatives capture cost-conscious users in urban European markets, pressuring disposable volume.
Strategic Opportunities
- EU Green Deal Tailwinds:Biodegradable certification requirements create first-mover advantages for suppliers with compostable back film capabilities.
- Subscription Channel Penetration:Direct-to-consumer platforms bypass pharmacy chain gatekeepers in underpenetrated Southeast Asian metros.
- PLI Scheme Leverage:India's production-linked incentive schemes for medical devices reduce capital barriers for domestic absorbent hygiene manufacturing.
Industry Challenges
- Compostability Certification Timelines:Third-party biodegradability testing under EN 13432 and ASTM D6400 extends product launch cycles by 8-14 months.
- Legacy Heat-Sealing Equipment Retrofit:Transitioning continuous web-forming lines to handle bio-based films demands capital outlays that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Napkin Market |
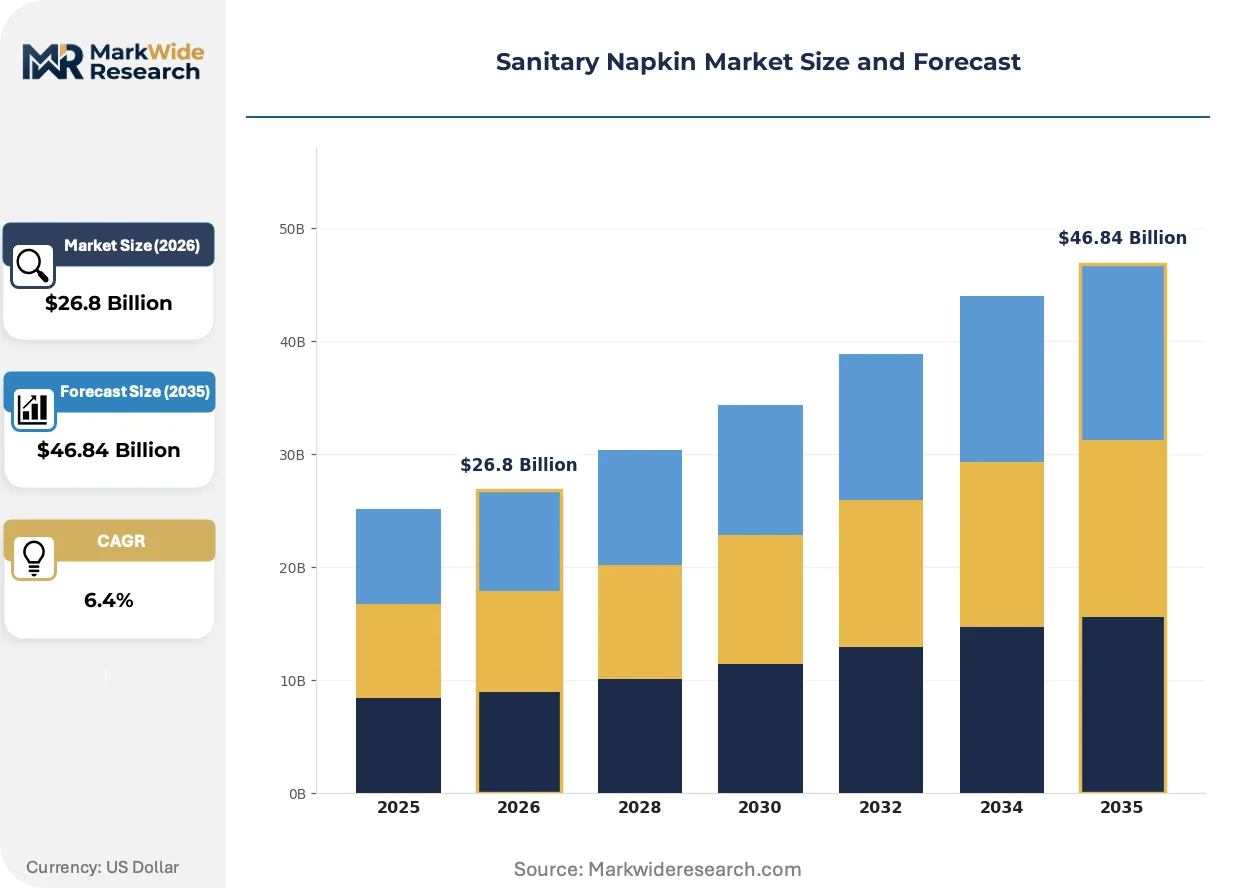
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $46.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Super, Overnight, Ultra Thin Material: Cotton, Rayon, Biodegradable, Plastic Distribution Channel: Online, Supermarkets, Pharmacies, Convenience Stores End User: Teenagers, Adults, Seniors, Women in Postpartum |
| Companies Covered | Kao Corporation, Johnson & Johnson Services Ltd., Procter & Gamble, Essity, Edgewell Personal Care Company, Kimberly-Clark Corporation, Hengan International Group, Lil-Lets UK Limited, Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Napkin Market Strategic Shifts & Innovations
Material science convergence and regulatory chemistry restrictions are redrawing competitive boundaries faster than brand equity can adapt. Suppliers now compete on certification depth rather than advertising spend.
Plant-derived superabsorbent polymers derived from agricultural waste streams are unifying sustainability credentials with performance parity. Premium pharmacy chains in Germany and the Netherlands have adopted these formulations as shelf-entry requirements. This unifying technology is compressing the window for petrochemical-dependent incumbents to reposition.
REACH Annex XVII restrictions on persistent organic pollutants are forcing reformulation of conventional leak-resistant films. Manufacturers serving European markets must validate alternative barrier chemistries or exit the region. Adult incontinence products face the steepest compliance curve due to higher polymer loading per unit.
Subscription-based replenishment models are displacing emergency pharmacy purchases among digitally native consumers. Direct-to-consumer platforms capture recurring revenue while traditional retail loses impulse-buy margins. This pattern concentrates in South Korean and Australian metropolitan markets where delivery infrastructure supports discreet logistics.
Sanitary Napkin Market Segmentation
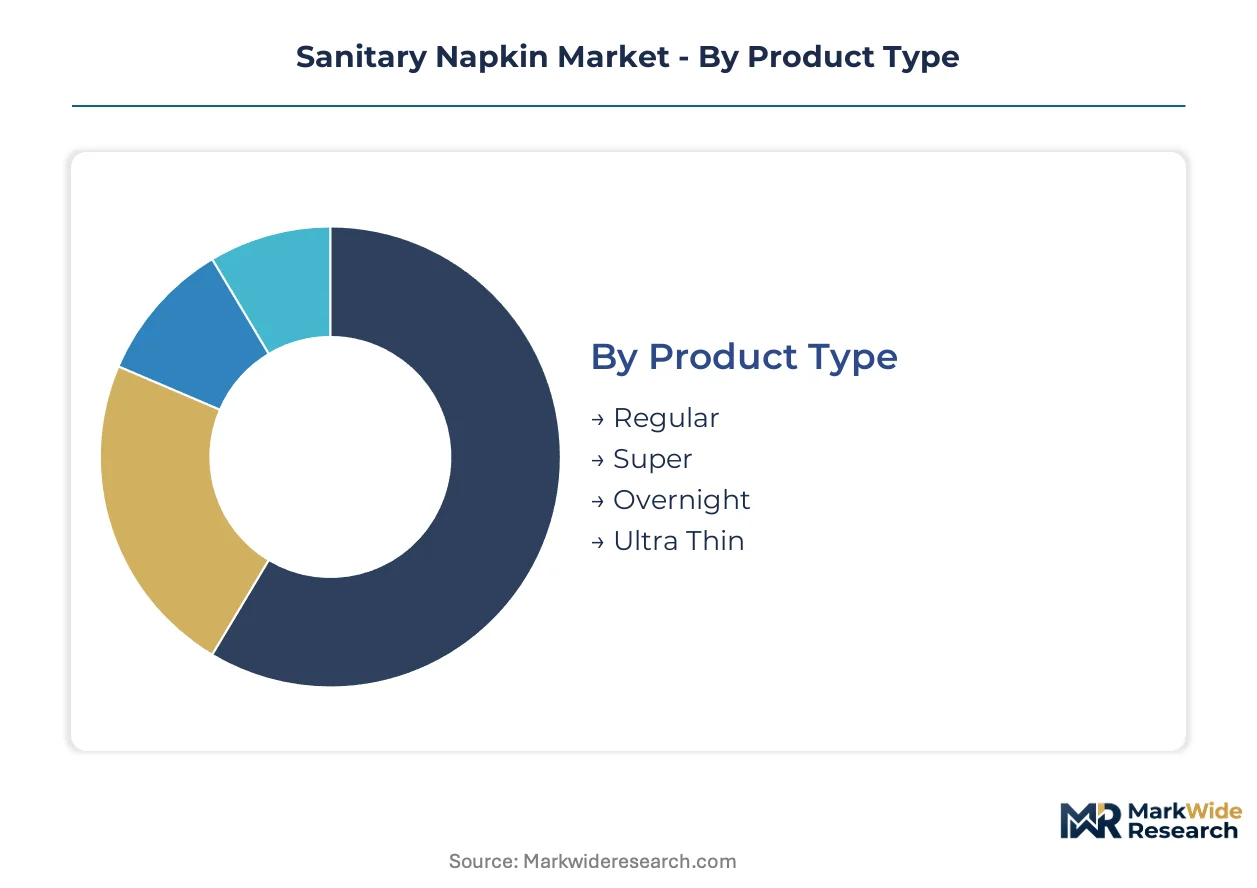
Sanitary napkin segmentation reflects divergent compliance burdens across product formats and material certifications. Manufacturers must align R&D investments with the specific regulatory pathways governing each segment's market access.
Product Type:
FDA medical device classifications and BIS safety mandates apply differentially across absorbency tiers, with overnight variants facing stricter polymer disclosure requirements.
- Ultra Thin:Compressed superabsorbent polymer cores achieve sub-3mm profiles through thermal bonding techniques. Demand concentrates in South Korean and Australian metropolitan markets where subscription services prioritize discreet portability.
- Overnight:Extended-length designs with reinforced leak barriers carry higher SAP loading per unit, triggering REACH Annex XVII scrutiny for persistent organic pollutants in European distribution. Reformulation timelines now determine shelf access in German pharmacy chains.
- Regular:Standard absorbency profiles dominate volume production in Indian contract manufacturing facilities serving domestic BIS-certified channels.
- Super:Mid-tier absorbency specifications balance material cost with performance claims in Indonesian district-level pharmacy networks.
Leading the category by volume: Regular. Expanding most quickly: Ultra Thin.
Material:
Raw material selection now predetermines geographic market eligibility through compostability certification and chemical restriction frameworks.
- Biodegradable:Compostable back films validated under EN 13432 and ASTM D6400 command shelf-entry requirements at premium pharmacy chains in Germany and the Netherlands. Agricultural waste-derived superabsorbent polymers from European suppliers unify sustainability credentials with performance parity.
- Plastic:Petrochemical-based leak-resistant films face ECHA-driven reformulation mandates across REACH jurisdictions. Manufacturers without alternative barrier chemistry validation risk regional exit.
- Cotton:Natural fiber top sheets appeal to dermatological sensitivity claims in Japanese and Australian markets with established organic certification infrastructure.
- Rayon:Semi-synthetic cellulosic cores offer cost-positioned alternatives to cotton in Southeast Asian manufacturing hubs.
Biodegradable materials gain share fastest. Plastic retains volume leadership but with contracting geographic scope.
Distribution Channel:
Channel selection determines margin structure and customer acquisition economics, with digital platforms bypassing traditional retail gatekeepers.
- Online:Subscription-based replenishment models capture recurring revenue in Seoul, Sydney, and Singapore metros where delivery infrastructure supports discreet logistics. Direct-to-consumer platforms circumvent pharmacy chain consolidation leverage.
- Supermarkets:Mass-market volume concentration persists in Indian and Indonesian urban retail, though shelf allocation increasingly hinges on sustainability certification rather than legacy brand recognition.
- Pharmacies:Consolidated chains in Europe and North America recalibrate procurement leverage, favoring suppliers with compliant manufacturing scale.
- Convenience Stores:Emergency purchase occasions dominate in Nigerian and Indonesian rural distribution networks with limited pharmacy penetration.
Supermarkets maintain volume dominance. Online channels show steepest expansion trajectory.
End User:
User demography shapes product specification requirements and pricing sensitivity, with postpartum and senior segments driving specialized absorbency engineering.
- Adults:Working-age users in South Korean and Australian markets drive subscription adoption and premium positioning for ultra-thin formats.
- Women in Postpartum:Hospital discharge protocols and maternity ward partnerships create institutional procurement channels with distinct volume and absorbency specifications.
- Teenagers:School-based distribution programs and digital-native purchasing patterns concentrate demand in urban Indian and Southeast Asian markets.
- Seniors:Adult incontinence overlap drives the steepest compliance burden under REACH due to higher polymer loading per unit.
Adults represent the largest addressable base. Women in Postpartum show concentrated growth in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wood pulp supply from northern European forests anchors manufacturing economics across multiple demand centers. Regional differentiation sharpens as certification requirements fragment market access.
United States
Subscription penetration in Seattle and Austin drives ultra-thin premiumization among working-age users. FDA medical device classifications enforce polymer disclosure standards for overnight variants. Manufacturing clusters in Georgia and Wisconsin concentrate absorbent core production serving consolidated pharmacy chain procurement.
Germany
REACH Annex XVII restrictions on persistent organic pollutants force reformulation of conventional leak-resistant films. ECHA compliance timelines now determine shelf access at premium pharmacy chains in Berlin and Hamburg. Compostable back film validation under EN 13432 creates first-mover advantages for domestic suppliers.
India
BIS certification mandates accelerate formalization of previously unregulated supply channels in rural districts. Production-linked incentive schemes for medical devices reduce capital barriers for domestic manufacturing in Gujarat and Maharashtra. District-level pharmacy networks in Uttar Pradesh and Bihar mature beyond informal vendor dependence.
Indonesia
Last-mile distribution networks now reach district-level pharmacies previously served only by informal vendors in Java and Sulawesi. National standards alignment with ASEAN harmonization frameworks elevates import compliance costs. Manufacturing concentration around Jakarta serves domestic volume and regional export positioning.
Nigeria
Rural distribution network maturation expands formal retail access beyond Lagos and Abuja into secondary cities. Import dependency for superabsorbent polymers creates foreign exchange exposure for local assemblers. Convenience store channels dominate emergency purchase occasions in northern regions with limited pharmacy penetration.
Sanitary Napkin Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification differentiation. Market structure tilts toward scale-driven consolidation as pharmacy chain procurement centralizes. Three archetypes dominate: multinational hygiene conglomerates with manufacturing scale, regional specialists with compliance infrastructure, and private-label assemblers serving price-sensitive channels. Competitive moves concentrate on sustainability certification acquisition and regional production footprint expansion.
Among multinational hygiene conglomerates, Procter & Gamble and Kimberly-Clark Corporation exemplify scale-driven positioning, while Essity occupies a position emphasizing sustainable material sourcing credentials. These anchors represent divergent responses to regulatory fragmentation: manufacturing scale leverage versus certification depth. Regional specialists such as Kao Corporation and Unicharm Corporation sit within Asia-Pacific focused tiers. The competitive terrain rewards compliance infrastructure over brand equity alone.
| Leading Market Players |
|---|
| Kao Corporation |
| Johnson & Johnson Services Ltd. |
| Procter & Gamble |
| Essity |
| Edgewell Personal Care Company |
| Kimberly-Clark Corporation |
| Hengan International Group |
| Lil-Lets UK Limited |
| Unicharm Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap producers across Gujarat and Maharashtra anchor India's contract manufacturing tier, channeling working capital discipline into volume pricing that undercuts multinational cost structures while absorbing BIS compliance overhead through operational efficiency rather than margin expansion.
Pricing Analysis
Volume production in Indian and Indonesian contract facilities captures economy-tier positioning, while biodegradable-certified variants in German pharmacy chains extract premium-mid-economy pricing differentiation based on EN 13432 validation timelines. Price differentiation hinges on certification grade and superabsorbent polymer source, with agricultural waste-derived SAP formulations commanding shelf-entry premiums. Cost compression in standard absorbency tiers intensifies as wood pulp volatility feeds through northern European supply contracts. Price-sensitive buyers concentrate in Nigerian rural convenience channels, while subscription users in Seoul and Sydney exhibit lowest sensitivity to per-unit premiums.
Supply Chain Analysis
Regional distribution centers in Jakarta, Lagos, and Mumbai operate hub-and-spoke patterns feeding district-level pharmacy networks previously served by informal vendors. Manufacturing concentrates in India, Indonesia, and China, with absorbent core production drawing from Swedish and Finnish pulp supply contracts. Raw material dependencies center on northern European wood pulp, Saudi and Korean superabsorbent polymer feedstock, and Malaysian palm-derived barrier films. Single-source vulnerability runs through SAP import channels for Nigerian assemblers exposed to foreign exchange fluctuation. Distribution runs through consolidated pharmacy chains in Europe and North America, fragmented traditional retail in South and Southeast Asia, and direct-to-consumer platforms in Australian and South Korean metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacy chain procurement centralization and biodegradable certification mandates are compressing mid-tier margins, forcing capital-constrained players toward exit or acquisition while rewarding scaled compliance infrastructure.
For Market Incumbents: Hedge against REACH Annex XVII reformulation timelines by securing alternative barrier chemistry validation before German shelf-access deadlines. Backward integration into agricultural waste-derived SAP sourcing locks in sustainability credential supply. Channel control through exclusive maternity ward partnerships in Indian hospital systems defends volume against subscription displacement. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms in underpenetrated Southeast Asian metros, bypassing consolidated pharmacy gatekeepers. White-space concentration sits in Indonesian district-level networks maturing beyond informal vendor dependence. Go-to-market angle: compostable back film certification as shelf-entry requirement at premium German chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Indian manufacturers with BIS certification infrastructure and PLI scheme eligibility in Gujarat and Maharashtra. Long-term viability across the projection horizon rests on compliance depth rather than brand equity. Signal to watch: third-party biodegradability testing backlog duration as indicator of certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Investment | EN 13432 validation secures shelf access at German pharmacy chains. |
| Backward Integration into SAP Sourcing | Agricultural waste polymer supply locks in EU Green Deal compliance positioning. |
| Direct-to-Consumer Platform Launch | Subscription models bypass consolidated retail procurement leverage in Seoul. |
| Regional Distribution Center Expansion | Hub-and-spoke networks reach Indonesian districts beyond informal vendor coverage. |
| Hospital System Partnership Development | Maternity ward procurement channels capture postpartum institutional volume in India. |
Research Approach
Trade databases, customs records, and BIS regulatory filings formed the secondary backbone, cross-referenced with primary interviews involving absorbent hygiene procurement managers at German pharmacy chains, Indian contract manufacturing executives, Indonesian distribution network operators, and ECHA compliance consultants. Bottom-up and top-down triangulation validated volume estimates against capacity disclosures and import-export flows.
Bottom-up modeling of installed production capacity across Indian and Indonesian manufacturing clusters anchored volume projections, while top-down expenditure analysis calibrated value estimates. Segmentation dimensions spanned product format, material certification tier, distribution channel type, and end-user demographic cluster. CAGRs derived from capacity expansion timelines, regulatory phase-in schedules, and subscription penetration curves in South Korean and Australian metros.
Wood pulp supply disruption, REACH Annex XVII enforcement acceleration, and menstrual cup substitution velocity in urban European markets are the dominant revision risks. Forecasts reflect documented assumptions regarding certification timeline completion rates and pharmacy chain consolidation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market