
 Europe Adult Diaper Market | 2026-2036
Europe Adult Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Adult Diaper Market Intelligence
Private-label manufacturing margins is narrowing as branded players internalize production capacity. Essity AB leverages its integrated pulp-to-pants supply chain across Nordic and Central European plants. Kimberly-Clark Corp sustains premium positioning through clinical channel partnerships with hospital procurement consortia. Ontex BV anchors volume competitiveness via dedicated adult incontinence manufacturing lines in Belgium and Italy.
Europe adult diapers are absorbent hygiene garments engineered with superabsorbent polymer cores, breathable non-woven topsheets, and elasticized leg gathers to contain moderate-to-heavy urinary and fecal incontinence in non-infant populations. SAP loading typically ranges from 8 to 20 grams depending on absorbency tier, with acquisition layer design dictating skin dryness performance for bedridden or mobile users. Disposable product formats dominate pharmacy and supermarket shelf space, while pull-up designs are capturing faster growth among ambulatory seniors seeking underwear-like discretion. Eco-friendly segments using bamboo fiber and bio-based backsheet films are emerging as margin-rich niches, though polymer-based constructions still occupy the bulk of institutional procurement contracts due to unit cost thresholds.
EMA medical device borderline classifications and EU Green Deal sustainability reporting obligations are reshaping material disclosure requirements and post-consumer waste accountability for absorbent hygiene manufacturers. CE marking under the MDR framework governs product safety claims for incontinence aids distributed through medical supply channels. Stakeholders must monitor how ECHA's microplastic restriction proposals and national extended producer responsibility schemes will alter raw material sourcing economics and end-of-life collection infrastructure investments.
Market Dynamics
Long-term care insurance reimbursement structures in Germany and the Netherlands are compressing unit pricing while elevating volume throughput, forcing manufacturers to recalibrate margin architecture around absorbency-tier differentiation and raw material sourcing efficiency.
Growth Catalysts
- Germany's Pflegeversicherung expansion:Reimbursement parity for higher-absorbency products is pulling institutional procurement toward premium-tier SKUs, expanding addressable revenue per patient.
- Superabsorbent polymer formulation advances:Next-generation partially neutralized sodium polyacrylate cores are reducing total polymer loading by 15-20% while maintaining retention capacity, lowering per-unit input costs.
- Aging-in-place policy frameworks:Municipal home care subsidy programs across Nordic municipalities are diverting demand from nursing facilities toward retail pharmacy and e-commerce channels.
Market Restraints
- Petrochemical feedstock volatility:Propylene and acrylic acid price swings—key inputs for SAP synthesis—are compressing gross margins on standard-tier products with limited pricing elasticity.
- ECHA microplastic restriction trajectory:Proposed broadened definitions of synthetic polymer microplastics threaten to reclassify conventional non-woven topsheets, requiring costly material substitutions or end-of-life collection infrastructure investments.
- Reusable textile pad substitution:Washable incontinence garments are capturing environmentally motivated ambulatory users in affluent urban clusters, particularly where municipal laundry services are subsidized.
Strategic Opportunities
- Poland and Romania home care underpenetration:Institutional bed capacity still dominates incontinence management in these markets, creating whitespace for retail-format pull-up products as family caregiver networks formalize.
- EU Green Deal sustainable product claims:Bio-based backsheet films and FSC-certified fluff pulp are qualifying products for public procurement preference margins in France and Belgium.
- Telehealth-integrated subscription models:Digital pharmacy platforms in the UK and Netherlands are virtualizing replenishment cycles, capturing patient adherence data that manufacturers can monetize through insurer partnerships.
Industry Challenges
- MDR technical documentation backlog:CE marking renewals under the 2017/745 framework are extending time-to-market for reformulated products, particularly for manufacturers without prior Class I medical device experience.
- Multi-site SAP qualification complexity:Dual-sourcing superabsorbent polymers across Asian and European suppliers requires harmonized quality protocols that strain analytical chemistry capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Adult Diaper Market |
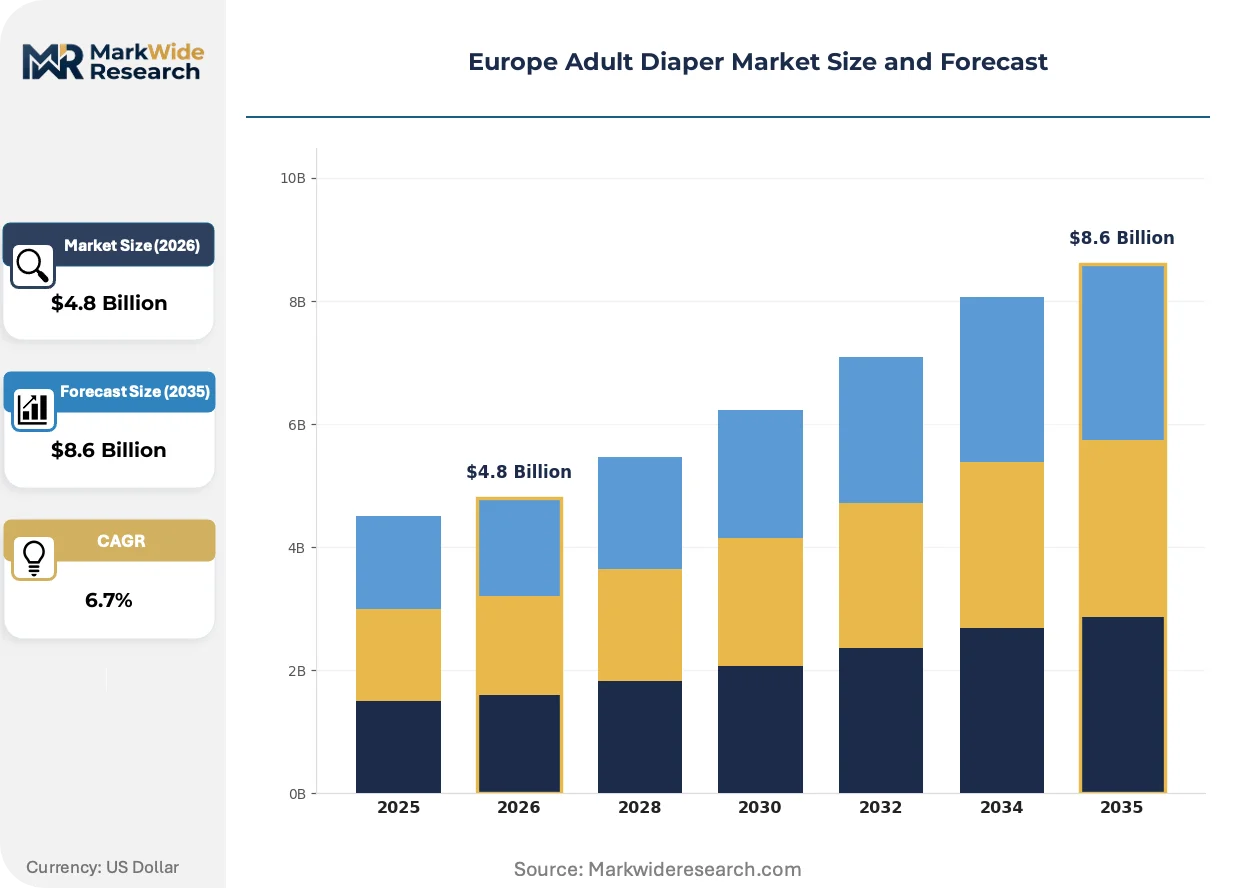
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Eco-Friendly, Pull-Up End User: Hospitals, Nursing Homes, Home Care, Individuals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Medical Supply Stores Material: Polymer, Cotton, Non-Woven Fabric, Bamboo Fiber |
| Companies Covered | Essity AB, Kimberly-Clark Corp, Ontex BV, Drylock Technologies NV, Paul Hartmann AG, Abena AS, Nippon Paper Industries Co Ltd, Procter & Gamble Company, Unicharm Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Adult Diaper Market Strategic Shifts & Innovations
Digital integration and material science convergence are restructuring how adult incontinence products are specified, procured, and consumed across European care ecosystems.
Sensor-embedded absorbent garments with moisture-alert functionality are virtualizing the role of scheduled check protocols in nursing facilities. German and Dutch long-term care operators are piloting these systems to optimize staffing allocation across night shifts. The technology is compressing liability exposure around moisture-associated skin damage while generating operational data that insurers are beginning to reference in risk-pricing models.
ECHA's REACH restriction roadmap for intentionally added microplastics is forcing disclosure of synthetic polymer content above 0.01% by mass across all absorbent hygiene articles. Manufacturers serving pharmacy and medical supply channels are accelerating qualification of thermoplastic starch alternatives to conventional polyethylene backsheet films. The regulatory friction falls heaviest on private-label suppliers lacking dedicated polymer science R&D capacity.
Ambulatory seniors in Scandinavia and the Benelux are migrating replenishment toward automated pharmacy subscriptions with discrete home delivery. Traditional supermarket bulk purchasing is yielding share to these services, which bundle product with skin health consultations and personalized absorbency recommendations. The behavioral pivot is most pronounced among digitally fluent cohorts managing mild-to-moderate incontinence without formal caregiver support.
Europe Adult Diaper Market Segmentation
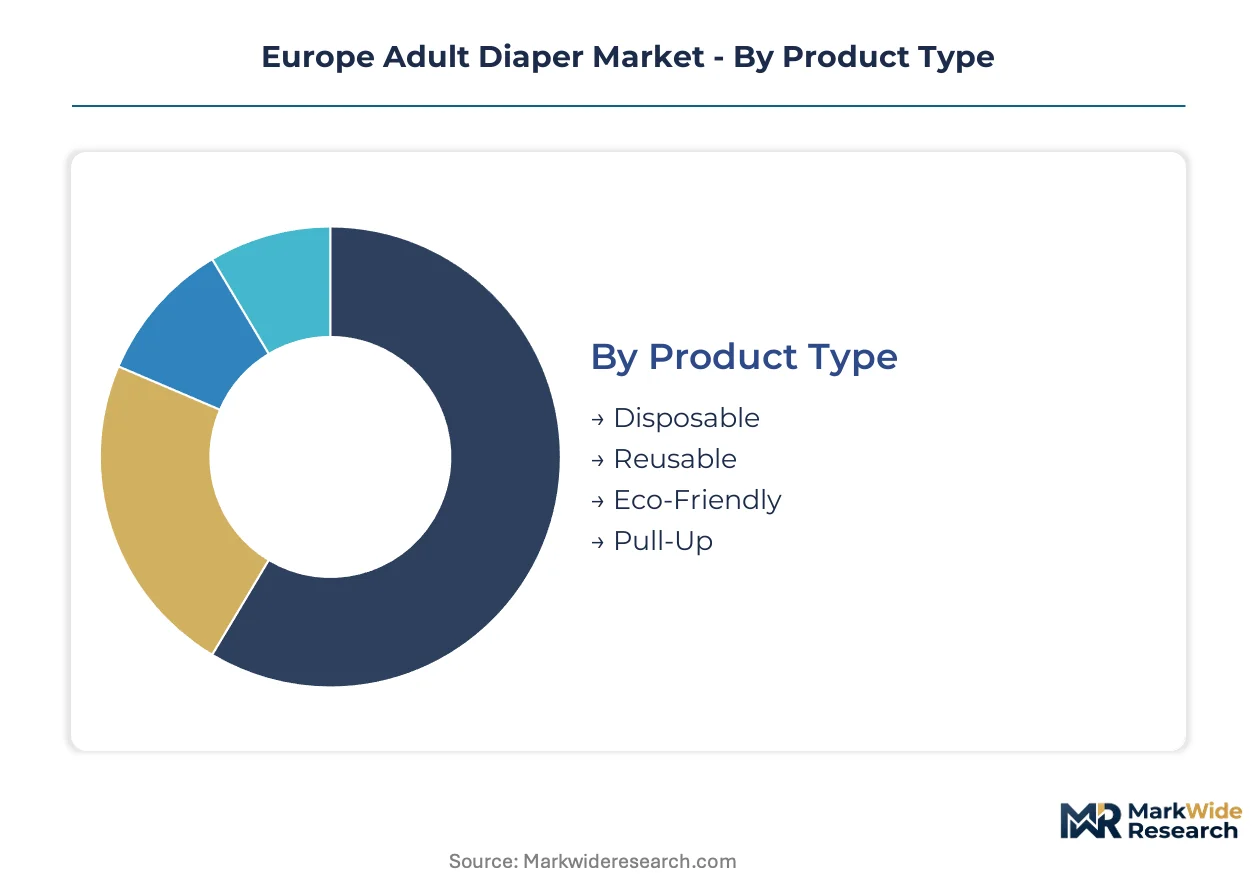
Adult diaper purchasing patterns across Europe fragment sharply across care settings, material preferences, and channel access. Manufacturers must calibrate formulation, packaging, and pricing architecture separately for institutional procurement contracts versus retail self-pay segments.
Product Type:
Disposable formats anchor institutional volume, while pull-up designs and sustainable alternatives reshape ambulatory and environmentally motivated demand pools.
- Disposable:Superabsorbent polymer cores with polyethylene backsheets dominate hospital and nursing home procurement. Germany's Pflegeversicherung reimbursement structures compress unit pricing while mandating minimum absorbency thresholds, forcing manufacturers to optimize polymer loading efficiency.
- Pull-Up:Elasticized waistbands and discreet profiles target mobile seniors aging in place. Nordic municipalities subsidizing home care services are accelerating pharmacy and e-commerce uptake of these underwear-like formats among digitally fluent cohorts.
- Reusable:Washable textile pads with waterproof PUL layers serve environmentally motivated users in affluent urban clusters where municipal laundry services operate.
- Eco-Friendly:Bamboo fiber topsheets and bio-based backsheet films qualify for public procurement preference margins in France and Belgium under EU Green Deal frameworks.
The dominant share belongs to Disposable, while Pull-Up is closing the gap fastest.
End User:
Reimbursement economics and care delivery models create four distinct demand profiles with divergent price elasticity and specification requirements.
- Home Care:Family caregivers purchasing through retail channels seek mid-tier absorbency with discreet packaging. Aging-in-place policy frameworks across Netherlands and Sweden are diverting volume from institutional beds toward domestic settings.
- Hospitals:Acute care procurement prioritizes high-capacity briefs with wetness indicators and breathable side panels. Clinical channel partnerships with hospital procurement consortia sustain premium positioning for compliant suppliers.
- Nursing Homes:Long-term care operators balance skin health protocols against per-patient daily product budgets. German and Dutch facilities are piloting sensor-embedded garments to optimize night shift staffing allocation.
- Individuals:Self-pay consumers managing mild incontinence drive subscription pharmacy growth in UK and Benelux markets, bundling replenishment with telehealth consultations.
Home Care commands the largest volume base, with Individuals expanding most quickly through digital channels.
Distribution Channel:
Channel strategy must reconcile reimbursement access, purchase discretion, and replenishment convenience across divergent European regulatory landscapes.
- Pharmacies:Reimbursement-eligible products move through this channel in Germany, Netherlands, and France with prescription-linked purchasing. Pharmacy staff influence absorbency tier selection for new caregivers navigating product complexity.
- Online Retail:Subscription models with discrete home delivery capture digitally fluent seniors in Scandinavia and UK. Automated replenishment cycles generate patient adherence data that manufacturers monetize through insurer partnerships.
- Supermarkets:Bulk purchasing of economy-tier products persists among price-sensitive family caregivers in Southern and Eastern Europe, though shelf space is yielding to pharmacy and digital channels.
- Medical Supply Stores:Specialized distributors serve nursing homes and home care agencies with institutional pack sizes and MDR-compliant documentation.
Pharmacies retain the dominant position, while Online Retail climbs the fastest among ambulatory user segments.
Material:
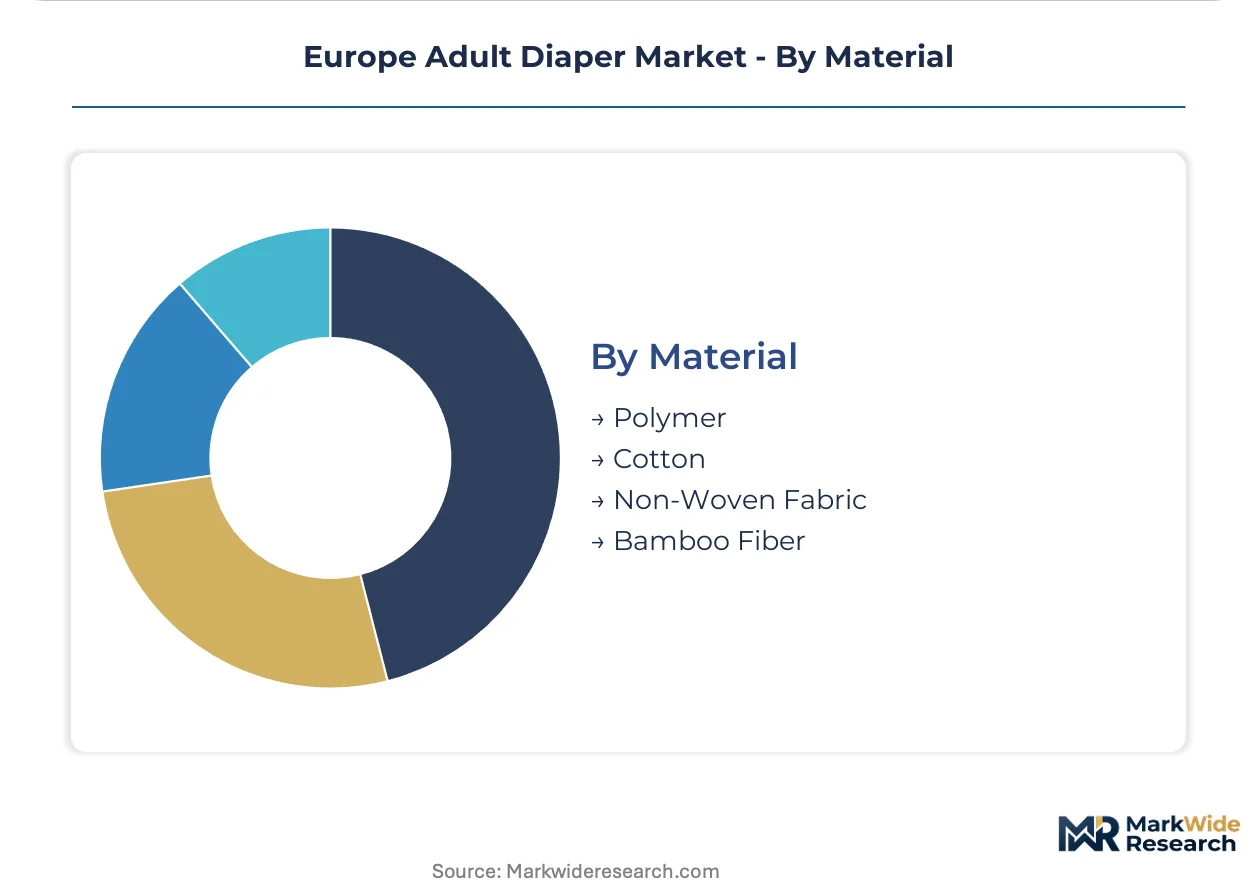
Raw material selection governs absorbency performance, regulatory compliance trajectory, and end-of-life accountability under tightening EU sustainability frameworks.
- Polymer:Sodium polyacrylate superabsorbent cores deliver retention capacity for moderate-to-heavy incontinence. ECHA microplastic restriction proposals threaten reclassification of conventional non-woven topsheets, requiring costly qualification of thermoplastic starch alternatives.
- Non-Woven Fabric:Polypropylene spunbond layers provide fluid acquisition speed and skin dryness. Petrochemical feedstock volatility in propylene and acrylic acid inputs compresses margins on standard-tier constructions.
- Cotton:Natural fiber blends serve reusable and premium disposable segments with breathable properties preferred by dermatologically sensitive users.
- Bamboo Fiber:Rapidly renewable cellulose sources qualify products for FSC-certified claims and public procurement sustainability preferences in Belgian and French tenders.
Polymer holds the dominant share, with Bamboo Fiber gaining share fastest among sustainability-positioned product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across European markets. German and Dutch buyers leverage insurance reimbursement for premium-tier products, while Southern and Eastern European consumers prioritize unit cost minimization in retail channels.
Germany
Pflegeversicherung reimbursement parity for higher-absorbency SKUs pulls institutional procurement toward premium tiers. CE marking under MDR 2017/745 governs medical supply channel distribution. The Rhine-Ruhr corridor hosts concentrated manufacturing capacity serving both domestic and export demand.
Netherlands
Municipal home care subsidy programs accelerate aging-in-place transitions away from nursing facilities. Long-term care insurance structures compress unit pricing while elevating volume throughput. Rotterdam-Antwerp logistics clusters support just-in-time replenishment for pharmacy distribution networks.
France
EU Green Deal sustainable product claims qualify bio-based and FSC-certified products for public procurement preference margins. ANSM borderline classifications shape medical device channel access. The Grand Est region anchors fluff pulp processing integrated into absorbent hygiene supply chains.
United Kingdom
Telehealth-integrated pharmacy subscriptions capture digitally fluent seniors managing mild incontinence independently. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for EU and UK markets. Greater Manchester and Birmingham logistics hubs facilitate discrete home delivery services.
Poland
Institutional bed capacity still dominates incontinence management, creating whitespace for retail-format pull-up products. Family caregiver networks are formalizing as home care infrastructure develops. Warsaw and Krakow pharmacy chains are expanding absorbent hygiene shelf space for ambulatory seniors.
Europe Adult Diaper Market Key Industry Players
Vertically integrated pulp-to-pants specialists and brand-led clinical channel operators split the market between cost-engineered volume and premium-positioned innovation. The competitive terrain stratifies across three archetypes: Nordic integrated suppliers with captive raw material streams, North American brand houses leveraging hospital procurement consortia, and Benelux contract manufacturers optimizing dedicated production lines. Consolidation pressure is intensifying as reimbursement compression forces scale efficiencies, while ECHA compliance costs disproportionately burden mid-tier private-label suppliers lacking dedicated polymer science capacity.
Among Nordic integrated suppliers, Essity AB exemplifies the backward-integrated archetype with captive pulp processing and multi-plant European manufacturing networks. Ontex BV occupies the contract manufacturing tier with specialized adult incontinence production lines in Belgium and Italy. Kimberly-Clark Corp represents the brand-led clinical channel approach, sustaining premium positioning through hospital procurement relationships. These three anchors illustrate how divergent strategic postures coexist within a market defined by reimbursement heterogeneity and regulatory fragmentation.
| Leading Market Players |
|---|
| Essity AB |
| Kimberly-Clark Corp |
| Ontex BV |
| Drylock Technologies NV |
| Paul Hartmann AG |
| Abena AS |
| Nippon Paper Industries Co Ltd |
| Procter & Gamble Company |
| Unicharm Corporation |
| Others |
Cost & Logistics Intelligence
Rhine-Ruhr freight corridors carry fluff pulp from Nordic ports to Central European converting plants, with logistics costs compressing margins on standard-tier disposables while enabling premium-tier price premiums through just-in-time pharmacy replenishment.
Pricing Analysis
After-sales skin health consultations and subscription bundling drive lifetime value for digitally fluent seniors. Three-tier pricing structure across premium, standard, and economy levels separates MDR-compliant medical supply products from pharmacy retail tiers and supermarket economy lines. Price differentiation hinges on absorbency certification and SAP loading efficiency. Cost compression in standard-tier products is intensifying because petrochemical feedstock volatility erodes polymer-based construction margins. Family caregivers in Southern and Eastern Europe exhibit highest price sensitivity, while German institutional buyers leverage Pflegeversicherung reimbursement for premium-tier uptake.
Supply Chain Analysis
Extended payment terms from Belgian and Italian converting plants to Nordic pulp suppliers stabilize working capital for mid-tier manufacturers. Supply concentrates in Germany, Belgium, and Italy for finished goods, with fluff pulp sourcing anchored in Sweden and Finland. Raw material dependencies center on sodium polyacrylate superabsorbent polymers, polypropylene spunbond non-wovens, and FSC-certified fluff pulp. Single-source vulnerability in Asian SAP qualification strains analytical chemistry capacity. Distribution runs through pharmacy networks in reimbursed markets and medical supply stores for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer science R&D capacity sits in short supply relative to ECHA compliance burdens, with only integrated suppliers possessing in-house formulation expertise to navigate REACH restriction roadmaps without external dependency.
For Market Incumbents: Insulate margin architecture by deepening backward integration into fluff pulp processing and accelerating thermoplastic starch alternative qualification ahead of microplastic restriction enforcement. Sensor-embedded garment development represents the priority R&D lever for capturing night-shift staffing optimization budgets from German and Dutch long-term care operators. For New Entrants and Emerging Players: Poland's retail pharmacy whitespace offers pull-up product entry before family caregiver networks fully formalize. Municipal home care subsidy expansion in Romanian urban clusters creates secondary beachhead opportunity. Direct-to-consumer subscription models with telehealth bundling provide the most penetrable go-to-market angle for bypassing entrenched institutional procurement relationships. For Investors and Strategic Acquirers: Private-label suppliers with dedicated adult incontinence lines but lacking captive SAP R&D capacity represent consolidation targets as compliance costs mount. Long-term viability frames around reimbursement policy durability and material substitution agility rather than volume scale alone. Watch ECHA's finalized microplastic restriction scope as the inflection signal for raw material sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluff Pulp | Captive supply from Nordic forests secures FSC certification for EU Green Deal procurement preference. |
| Sensor-Embedded Product Launch | Moisture-alert functionality captures night-shift staffing optimization budgets from Dutch care operators. |
| Thermoplastic Starch Qualification | Polyethylene backsheet substitution satisfies ECHA REACH disclosure thresholds for pharmacy channel access. |
| Pharmacy Subscription Partnership | Telehealth-integrated replenishment monetizes adherence data through German insurer risk-pricing models. |
| CE Marking Renewal Investment | MDR 2017/745 technical documentation clears regulatory pathway for reformulated premium-tier SKUs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across this study, combining primary interviews with procurement managers at German and Dutch long-term care facilities, pharmacy category buyers in France and Belgium, and polymer scientists at absorbent hygiene manufacturers with secondary validation from ECHA REACH registration databases, EU MDR technical documentation filings, and national health insurance reimbursement schedules. Bottom-up volume triangulation from institutional procurement contracts and retail scanner data was cross-checked against top-down macroeconomic elasticity assumptions.
Calibration against historical reimbursement policy shifts and SAP formulation cost curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, care setting, distribution channel, and material composition, with absorbency tier and regulatory certification status as industry-specific stratifiers. CAGRs were derived from elasticity-adjusted volume projections and input-cost pass-through assumptions, incorporating petrochemical feedstock volatility bands and ECHA restriction implementation scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian SAP suppliers or accelerated municipal subsidy programs in Eastern Europe would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Surgical Drapes Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Examination Gloves Market