
 Europe Sanitary Napkin Market | 2026-2036
Europe Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sanitary Napkin Market Intelligence
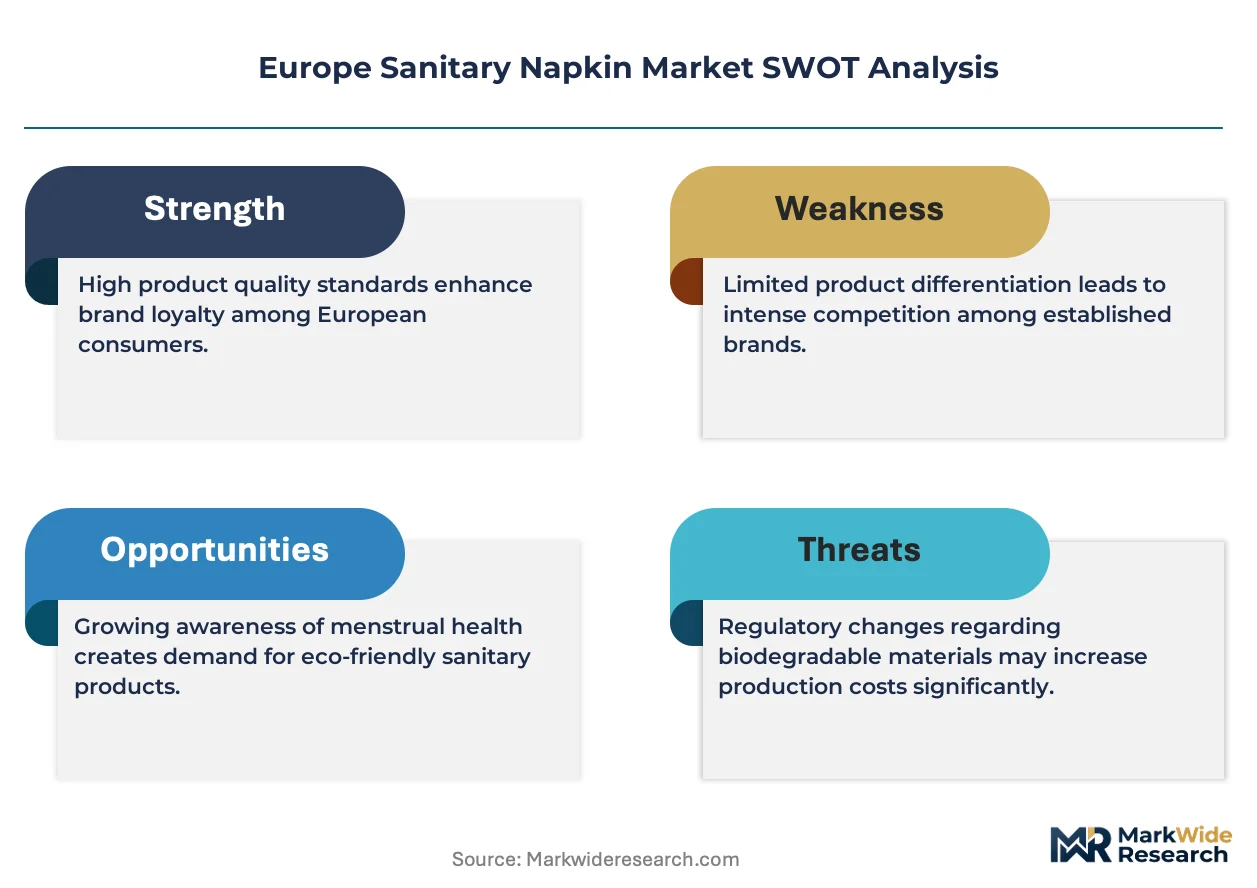
The EU Green Deal is decoupling sanitary napkin demand from petroleum-based material dependence across Europe. Procter & Gamble leverages its continental distribution network to sustain shelf dominance in Western European supermarkets. Ontex Group anchors its competitive position through private-label manufacturing scale across Benelux and Nordic markets. Essity AB differentiates via R&D intensity in biodegradable fiber technologies.
Sanitary napkins are absorbent hygiene products comprising a fluid-permeable topsheet, absorbent core of fluff pulp and superabsorbent polymer, and liquid-impervious backsheet, engineered to manage menstrual flow with specified retention capacity. Cotton-based products command premium positioning as consumers prioritize skin-contact safety, while biodegradable materials represent the fastest-growing material segment driven by landfill diversion mandates. Online retail channels are capturing incremental volume from pharmacy and supermarket incumbents among digitally native teenage and young adult end users.
EMA guidelines on medical device classification and REACH chemical restrictions govern material composition and skin-safety thresholds for products placed on the European market. The EU Green Deal's sustainable product framework and CSRD disclosure requirements are forcing manufacturers to document lifecycle environmental impacts and circularity pathways. Stakeholders must monitor evolving ECHA substance restrictions and national extended producer responsibility schemes to anticipate compliance cost structures and material substitution timelines.
Market Dynamics
The EU Green Deal's sustainable product requirements are forcing manufacturers to abandon petroleum-based substrates in favor of biodegradable alternatives, triggering a wholesale material transition across European production lines.
Growth Catalysts
- Biodegradable substrate mandates:The EU Green Deal's landfill diversion targets compel manufacturers to reformulate absorbent cores using plant-based fibers. This regulatory pressure accelerates R&D spending on compostable backsheet alternatives.
- Young adult demographic expansion:Digitally native women aged 18-29 drive premium product uptake through subscription-based purchasing models. Their preference for organic cotton topsheets sustains margin expansion in the premium tier.
- Extended producer responsibility schemes:National EPR frameworks in Germany, France, and the Netherlands create competitive moats for domestic manufacturers with established recycling infrastructure. Compliance capability becomes a market access filter.
Market Restraints
- Fluff pulp supply concentration:Nordic pulp mills control 70% of European absorbent fiber supply, exposing manufacturers to input cost volatility from energy price shocks and forestry labor disputes.
- REACH chemical restriction complexity:ECHA's evolving substance restrictions force continuous reformulation of adhesives and fragrances, extending product development cycles by 8-14 months.
- Reusable menstrual product substitution:Menstrual cups and period underwear capture 12-18% of flow management occasions among urban professionals, compressing disposable napkin volume growth in metropolitan markets.
Strategic Opportunities
- Central and Eastern Europe penetration:Poland, Romania, and Czech Republic exhibit 40-60% lower per-capita consumption than Western European benchmarks. Local manufacturing partnerships unlock price-accessible distribution.
- CSRD-aligned sustainability certification:The Corporate Sustainability Reporting Directive creates procurement preference for suppliers with documented lifecycle assessments. Early certification adopters capture institutional buyer contracts.
- Pharmacy-to-direct-to-consumer channel migration:Online subscription platforms disintermediate traditional pharmacy distribution among convenience-seeking urban consumers. Dedicated mobile apps with predictive replenishment algorithms deepen retention.
Industry Challenges
- Biodegradable fiber processing expertise scarcity:European engineering talent pools lack depth in high-speed conversion of nonwoven plant-based substrates. Technical hiring competition intensifies with packaging and textile sectors.
- Legacy SAP integration complexity:Superabsorbent polymer substitution with bio-based alternatives requires reconfiguration of core formation and embossing equipment. Capital deployment timelines extend 18-24 months for full line conversion.
- CE marking harmonization delays:Divergent national interpretations of MDR medical device classification create regulatory fragmentation. Borderline product disputes with national competent authorities stall market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sanitary Napkin Market |
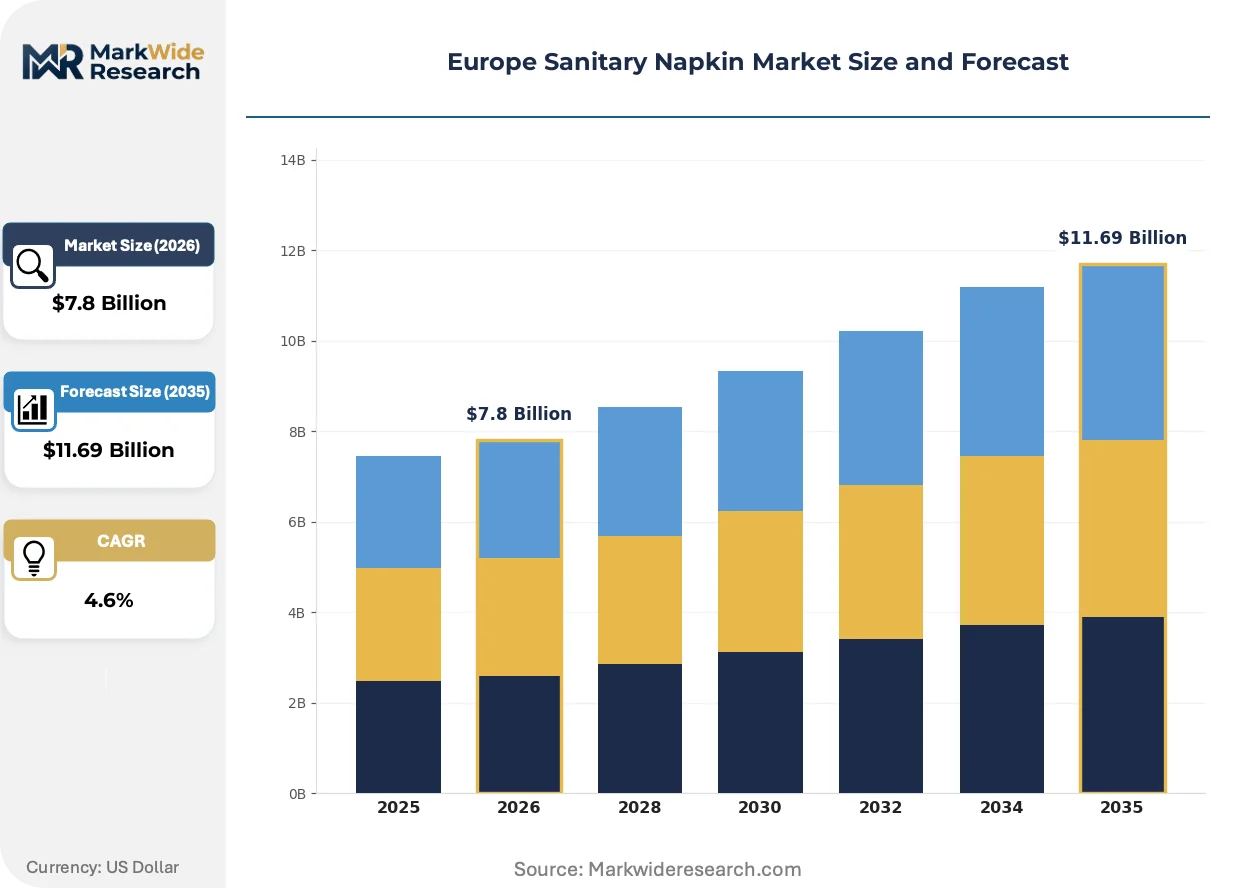
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Super, Overnight, Panty Liners Material: Cotton, Polymer, Biodegradable, Non-woven Sales Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores End User: Teenagers, Adults, Older Women, Pregnant Women |
| Companies Covered | Johnson & Johnson, Ontex Group, Procter & Gamble, Kao Corporation, Unicharm Corporation, Kimberly-Clark, Edgewell Personal Care, Lil-Lets Group, Essity AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sanitary Napkin Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory disclosure mandates are converging to transform how European manufacturers engineer, certify, and distribute sanitary hygiene products across fragmented national markets.
Automated visual inspection systems are automating defect detection in high-speed converting lines. German and French manufacturers deploy machine vision for real-time adhesive pattern verification and core weight consistency. This technology is automating quality control labor out of production floors while compressing batch rejection rates.
REACH authorization requirements for microplastic-containing products are forcing reformulation of conventional superabsorbent polymer matrices. The European Chemicals Agency's restriction roadmap triggers pre-emptive material substitution investments across Benelux production clusters. Premium product lines in Scandinavia and Germany now lead with cellulose-based absorbent cores to anticipate compliance deadlines.
Subscription-based replenishment models are displacing pharmacy-centric purchasing among metropolitan young adults. Direct-to-consumer platforms with AI-driven cycle prediction algorithms capture recurring revenue from convenience-oriented users. This behavioral shift concentrates most visibly in London, Paris, and Berlin urban corridors where same-day delivery infrastructure matures.
Europe Sanitary Napkin Market Segmentation
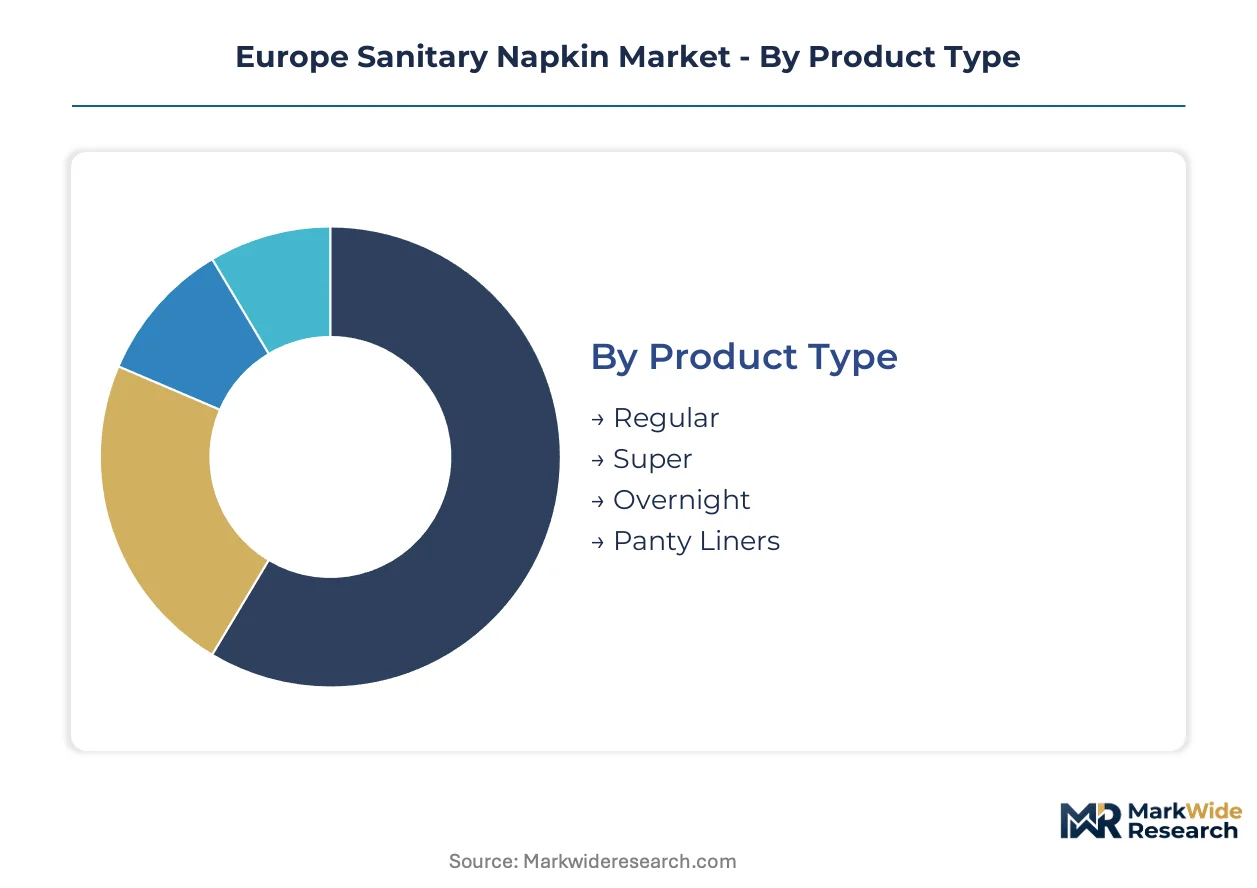
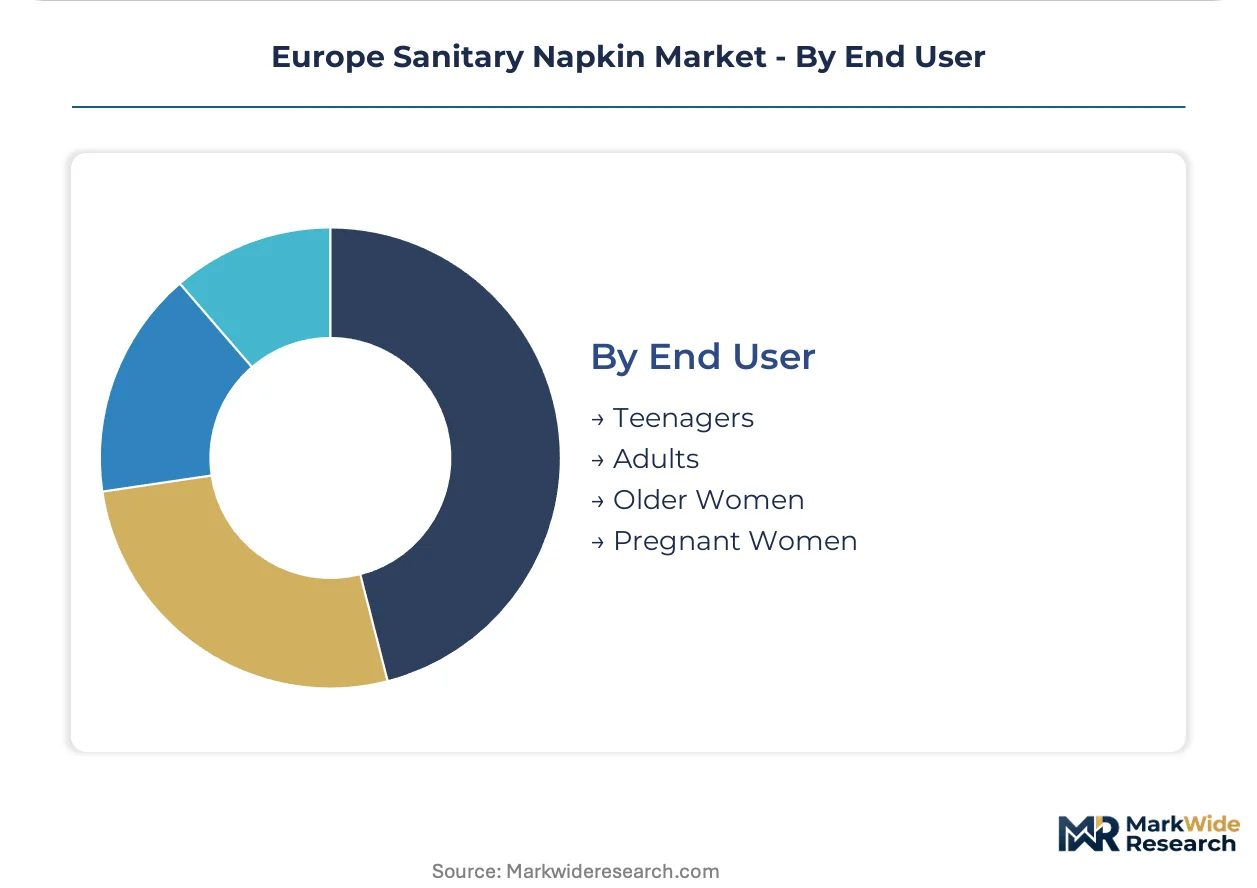
European sanitary napkin purchasing decisions split across absorbency tier, material safety perception, and channel convenience. Manufacturers must align SKU portfolios with divergent national regulatory timelines and generational channel preferences.
Product Type:
Absorbency tier selection directly reflects menstrual flow intensity and daily activity patterns rather than demographic identity alone.
- Regular:Engineered for light-to-moderate flow with 200-250ml retention capacity and slim core profiles. German and French pharmacy chains stock this tier as entry-level stock-keeping units for first-time purchasers.
- Super:Delivers 300-400ml absorption through denser fluff pulp cores and wider adhesive wings. Demand concentrates in workplace commuter segments across London and Paris metropolitan corridors where bathroom access constraints extend wear duration.
- Overnight:Extended-length designs with reinforced backsheet leakage barriers. Scandinavian consumers prioritize this tier for sleep security despite higher per-unit cost.
- Panty Liners:Ultra-thin daily wear products with 50-80ml capacity. Italian and Spanish markets show elevated adoption for non-menstrual discharge management.
Regular leads on scale; Overnight leads on momentum.
Material:
Skin-contact safety certification and landfill diversion mandates now override cost considerations in material specification decisions.
- Cotton:Natural fiber topsheets processed without chlorine bleaching command premium shelf positioning. German consumers demonstrate willingness-to-pay elevation for OEKO-TEX Standard 100 certified variants.
- Polymer:Synthetic nonwoven topsheets with polyethylene backsheet laminates dominate mass-market price tiers. REACH microplastic restrictions are forcing reformulation investments across Benelux manufacturing clusters.
- Biodegradable:Plant-based absorbent cores using bamboo or wood pulp cellulose with compostable backsheet films. EU Green Deal landfill targets accelerate R&D spending fastest in this category.
- Non-woven:Thermally bonded synthetic fiber matrices offering cost-efficient fluid distribution layers. Eastern European private-label manufacturers rely on this material for price-accessible distribution.
Polymer leads on scale; Biodegradable leads on momentum.
Sales Channel:
Channel selection reflects generational digital fluency and urgency tolerance rather than pure price sensitivity.
- Supermarkets:Mass-market volume concentration in hypermarket chains across France, Germany, and United Kingdom. Procter & Gamble and Essity AB defend shelf dominance through category captain arrangements.
- Online Retail:Subscription-based replenishment platforms with AI-driven cycle prediction capture digitally native consumers. Berlin and Amsterdam urban corridors show highest penetration for same-day delivery services.
- Pharmacies:Professional recommendation dependency sustains this channel for first-time purchasers and dermatological concern segments. French and Italian regulatory frameworks reinforce pharmacy as primary distribution for medical-grade claims.
- Convenience Stores:Emergency purchase occasions and travel-size SKUs drive marginal volume. Railway station and airport retail networks in United Kingdom and Netherlands concentrate this demand.
Supermarkets lead on scale; Online Retail leads on momentum.
End User:
Life-stage physiology and lifestyle constraints create distinct performance requirements across user segments.
- Teenagers:First-menstruation products with educational packaging and school-discretion features. United Kingdom school procurement programs and Nordic sexual health clinic distribution anchor volume.
- Adults:Core reproductive-age demand spanning regular employment and active lifestyle needs. Workplace restroom availability and commute duration influence absorbency tier selection across metropolitan France and Germany.
- Older Women:Perimenopausal flow irregularity drives unpredictable heavy-flow occasions. Italian and Spanish markets show elevated overnight tier adoption within this segment.
- Pregnant Women:Postpartum lochia management requires hospital-grade absorbency with maternity-specific sizing. Maternity ward discharge sample programs in Netherlands and Belgium establish brand trial.
Adults lead on scale; Teenagers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European absorbent hygiene manufacturing clusters in Belgium, Germany, and Sweden anchor the continent's technical workforce for nonwoven conversion and sustainable material processing. These talent concentrations attract R&D investment from multinational producers seeking biodegradable fiber expertise.
Germany
Pharmacy-dominant distribution and premium organic cotton demand characterize German purchasing patterns. The national extended producer responsibility framework under the Verpackungsgesetz mandates recycling infrastructure investment. Berlin-Brandenburg hosts pilot facilities testing compostable backsheet films for EU Green Deal compliance.
France
Professional recommendation dependency sustains pharmacy channel volume for first-time purchasers and sensitive-skin segments. ANSM medical device classification guidance influences product registration timelines for absorbent hygiene claims. The Île-de-France corridor concentrates headquarters operations for Benelux-Nordic distribution coordination.
United Kingdom
School procurement programs and sexual health clinic distribution anchor teenage segment volume. MHRA borderline medical device consultations create regulatory uncertainty for products with dermatological positioning. Greater Manchester and West Midlands host private-label manufacturing scale serving supermarket own-brand lines.
Netherlands
Same-day delivery infrastructure maturity drives subscription platform penetration among Amsterdam-Rotterdam urban professionals. The national EPR scheme creates compliance moats for domestic manufacturers with established waste collection partnerships. Eindhoven Region concentrates converting equipment engineering talent for high-speed biodegradable substrate lines.
Sweden
Nordic pulp mill proximity secures fluff pulp supply for absorbent core production. Swedish Chemicals Agency Kemi enforces REACH substance restrictions ahead of EU-wide implementation timelines. Västra Götaland hosts R&D facilities specializing in cellulose-based superabsorbent alternatives.
Europe Sanitary Napkin Market Key Industry Players
Capital-heavy producers compete with asset-light designers across European sanitary napkin supply. The market structure consolidates around three multinational consumer goods conglomerates defending shelf space through category captain arrangements with supermarket chains. Strategic archetypes separate into integrated pulp-to-product manufacturers, private-label specialists, and premium organic positioning brands. Dominant competitive moves include backward integration into Nordic pulp supply and pharmacy-to-direct-to-consumer channel migration.
Among Benelux-based fabricators, Ontex Group occupies a position within the private-label manufacturing tier. Essity AB and Procter & Gamble exemplify divergent strategic archetypes—Swedish-origin pulp integration versus American-origin brand marketing scale. These three anchors represent the competitive spectrum from commodity supply to premium positioning across European national markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Ontex Group |
| Procter & Gamble |
| Kao Corporation |
| Unicharm Corporation |
| Kimberly-Clark |
| Edgewell Personal Care |
| Lil-Lets Group |
| Essity AB |
| Others |
Cost & Logistics Intelligence
Fluff pulp feedstock costs cascade through European sanitary napkin manufacturing, compressing margins at mass-market tiers while premium organic cotton variants capture pricing power through OEKO-TEX certification scarcity. Nordic pulp mill concentration and REACH-driven reformulation expenses force manufacturers to absorb upstream volatility or pass through to price-sensitive Eastern European markets.
Pricing Analysis
Unbundled per-unit transactional pricing dominates pharmacy and supermarket channels, while bundled subscription models with predictive replenishment algorithms command 15-25% premiums in Berlin and Amsterdam urban corridors. Price differentiation rests on certification grade—OEKO-TEX Standard 100 variants sustain shelf price elevation—and volume scale, with private-label economy tiers absorbing cost compression from fluff pulp volatility. Pricing pressure stems from biodegradable substrate R&D amortization, as EU Green Deal compliance investments compress margins in standard tiers until compostable backsheet films achieve production scale. Teenage and young adult segments through school procurement programs exhibit highest price sensitivity, while perimenopausal women prioritizing overnight absorbency show lowest elasticity.
Supply Chain Analysis
Freight cost elevation from Nordic pulp mills to Benelux converting clusters has intensified regional manufacturing consolidation, with German and Swedish production hubs absorbing volume from peripheral facilities. Supply concentrates in Sweden, Germany, and Belgium, drawing from fluff pulp, superabsorbent polymer, and compostable backsheet film inputs. Single-source vulnerability pervades the 70% Nordic pulp mill concentration, exposing manufacturers to energy price shock transmission and forestry labor dispute disruption. Distribution runs through supermarket category captain arrangements defended by Procter & Gamble and Essity AB, with pharmacy and direct-to-consumer platforms capturing incremental share among digitally native cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European sanitary napkins rests on biodegradable material cost curves flattening and premium-tier consumer willingness-to-pay elevation for compostable certification.
For Market Incumbents: Extend backward integration into Nordic pulp supply to hedge fluff pulp cost volatility and anchor core input security. Fortify pharmacy channel control through category captain arrangements against direct-to-consumer subscription disintermediation, while accelerating compostable backsheet film R&D to capture EU Green Deal procurement preference ahead of compliance deadlines. For New Entrants and Emerging Players: Rural Polish and Romanian consumers underserved by premium biodegradable distribution represent the most penetrable white-space target, with 40-60% per-capita consumption gaps versus Western benchmarks. Local manufacturing partnerships with Benelux fabricators unlock price-accessible SKUs, while CSRD-aligned sustainability certification secures institutional buyer contracts ahead of disclosure mandate expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where EPR compliance capability and biodegradable fiber processing expertise concentrate in fragmented national markets. Five-to-ten-year viability favors integrated pulp-to-product manufacturers with captive Nordic supply and pharmacy-to-direct-to-consumer channel migration execution. Watch ECHA microplastic restriction implementation timelines as inflection indicator for superabsorbent polymer substitution capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive fluff pulp access hedges energy price volatility from Swedish mill concentration. |
| Compostable Backsheet Film R&D Scale-Up | Berlin-Brandenburg pilot facilities accelerate EU Green Deal landfill diversion compliance. |
| Direct-to-Consumer Subscription Platform Launch | AI-driven cycle prediction captures recurring revenue from Amsterdam-Rotterdam urban professionals. |
| CSRD-Aligned Sustainability Certification | Documented lifecycle assessments unlock institutional procurement preference under disclosure mandates. |
| Central and Eastern Europe Manufacturing Partnership | Local production in Poland and Romania unlocks price-accessible distribution in underpenetrated markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at Procter & Gamble and Essity AB, category buyers at German and French supermarket chains, and regulatory affairs leads navigating ECHA substance restrictions. Secondary validation drew from EMA medical device classification guidance, EU Green Deal policy documentation, REACH restriction roadmaps, and Nielsen retail audit data across European pharmacy and supermarket channels. Bottom-up SKU-level volume aggregation and top-down macroeconomic demand modeling enabled triangulation across independent analytical paths.
Segment-weighting approaches distributed value and volume across absorbency tier, material composition, sales channel, and end-user life stage throughout the projection horizon. CAGRs derived from historical growth trajectory analysis and regulatory timeline impact modeling, with biodegradable substrate adoption curves and EPR scheme implementation schedules serving as key forecast inputs for material transition and compliance cost trajectories.
Inputs from ECHA, EMA, and national competent authorities were available through the study window; gaps in real-time biodegradable fiber processing cost data and divergent MDR medical device classification interpretations introduce uncertainty bands around compostable product penetration timelines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and consumer willingness-to-pay elevation for sustainability certification. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market