
 United States Sanitary Napkin Market | 2026-2036
United States Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sanitary Napkin Market Intelligence
Aftermarket subscription revenue is narrowing as direct-to-consumer platforms capture recurring purchase relationships previously held by mass retailers. Procter & Gamble leverages its distribution scale to sustain shelf dominance across conventional retail channels. Kimberly-Clark differentiates through clinical positioning of its feminine hygiene portfolio. Edgewell Personal Care specializes in value-tier offerings that compete on price accessibility in dollar stores and discount chains.
Sanitary napkins are absorbent disposable products engineered with layered nonwoven topsheets, acquisition distribution layers, and superabsorbent polymer cores to manage menstrual flow, typically measuring 180-300mm in length for daytime variants. Ultra-thin products lead volume sales due to consumer preference for discreet wearability, while organic material formulations represent the fastest-growing segment as chemical-free claims reshape purchasing decisions among health-conscious buyers. The adult end-user category anchors overall demand, though teenager-oriented packaging and educational marketing occupy a distinct growth niche.
The FDA regulates sanitary napkins as Class II medical devices under 21 CFR 884.5425, requiring substantial equivalence demonstrations for market entry, while state-level legislation in California and New York mandates ingredient disclosure and tampon tax elimination that reshapes pricing transparency. The Federal Trade Commission monitors environmental marketing claims under its Green Guides, constraining how biodegradable and organic labels reach consumers. Stakeholders must monitor evolving state procurement policies for menstrual equity programs in schools and correctional facilities as these create institutional volume channels distinct from traditional retail.
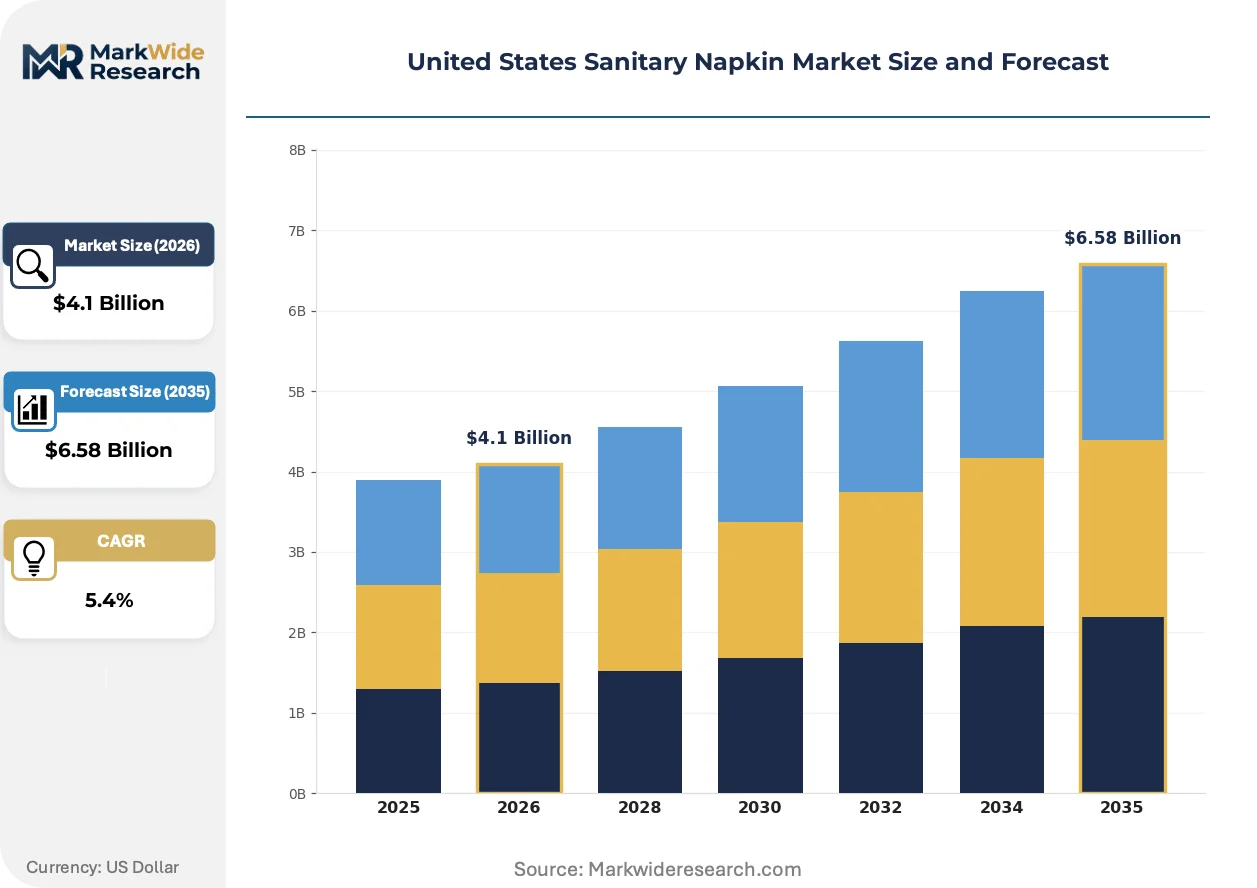
Market Dynamics
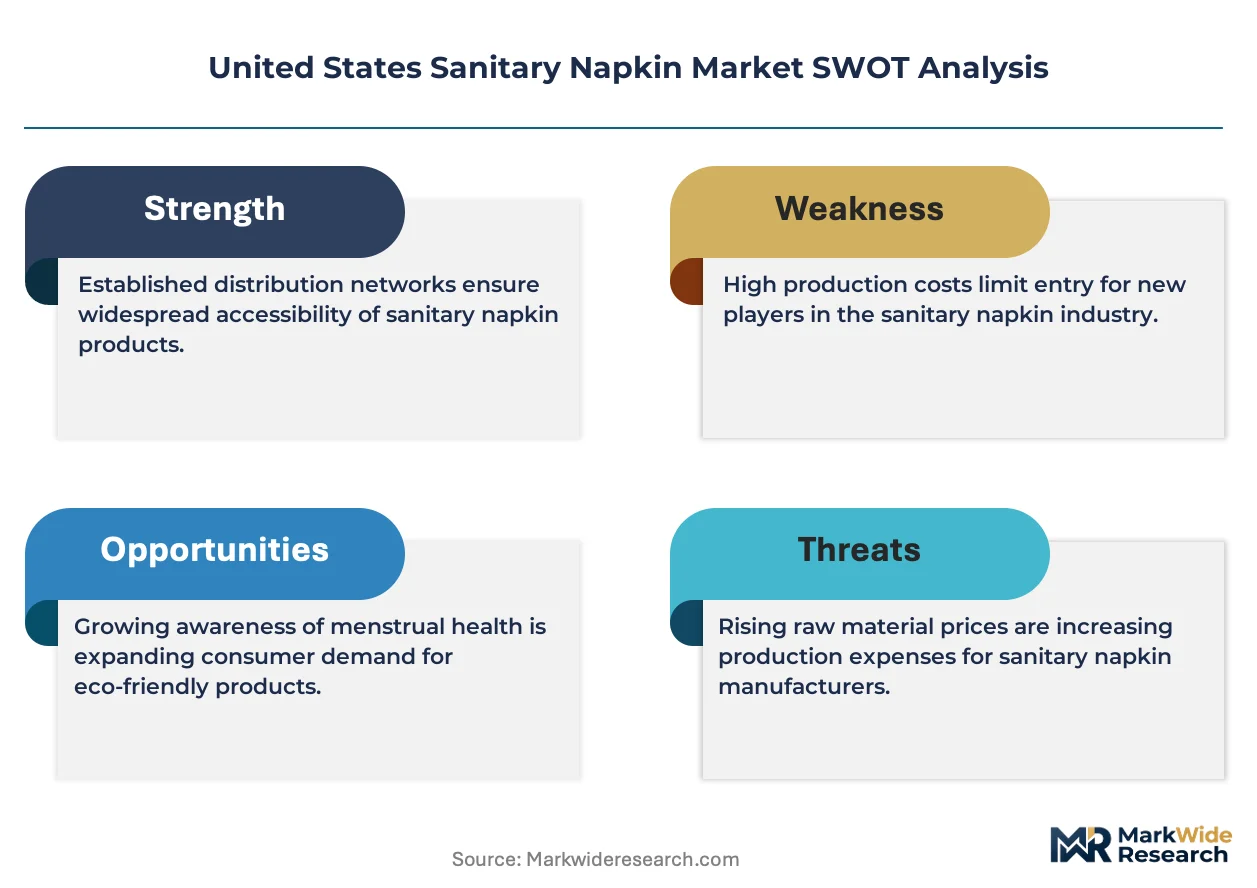
The FDA's Class II medical device classification for sanitary napkins is compressing innovation timelines while simultaneously raising compliance barriers for new entrants, forcing manufacturers to front-load clinical equivalence documentation before commercialization.
Growth Catalysts
- Menstrual equity procurement mandates:California and New York state legislation requiring free menstrual product access in schools and correctional facilities is institutionalizing bulk purchasing channels outside traditional retail.
- Superabsorbent polymer core advancements:Next-generation hydrogel formulations are extending wear time and reducing bulk without compromising leakage protection, particularly resonating with working professional segments.
- Urban coastal demand concentration:Premium and organic product preferences in California, New York, and Washington are pulling national assortment strategies toward higher-margin formulations.
Market Restraints
- Fluff pulp input cost volatility:Dependency on North American softwood pulp suppliers exposes margins to lumber market cyclicality and freight rate fluctuations.
- Polypropylene supply concentration:Nonwoven topsheet production relies heavily on Gulf Coast petrochemical complexes, creating geographic vulnerability to hurricane disruptions.
- Biodegradability technical limitations:Current superabsorbent polymers resist anaerobic decomposition, constraining compostability claims under FTC Green Guide scrutiny.
Strategic Opportunities
- Subscription direct-to-consumer channels:Recurring revenue models bypass retail slotting fees and capture lifetime value through personalized cycle tracking apps.
- Organic cotton certification expansion:USDA Organic and OEKO-TEX Standard 100 credentials command 40-60% price premiums in health-conscious segments.
- Teenager educational marketing white space:School-based health curriculum partnerships create brand loyalty formation before purchasing autonomy solidifies.
Industry Challenges
- 510(k) substantial equivalence documentation:FDA clearance timelines for novel materials average 12-18 months, delaying product refresh cycles.
- Legacy retail integration complexity:Mass merchant EDI and inventory management systems require expensive middleware to synchronize with DTC fulfillment operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sanitary Napkin Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Ultra-Thin, Overnight, Panty Liners Material: Cotton, Biodegradable, Synthetic, Organic Packaging Type: Pack of 10, Pack of 20, Bulk Packs, Individual Wraps End User: Teenagers, Adults, Elderly, Pregnant Women |
| Companies Covered | Unicharm Corporation, Essity AB, Procter & Gamble, First Quality Enterprises, Kao Corporation, Kimberly-Clark, Hengan International Group, Ontex Group, Edgewell Personal Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sanitary Napkin Market Strategic Shifts & Innovations
Digital cycle tracking and personalized subscription algorithms are compressing the traditional brand loyalty cycle while ingredient transparency mandates force reformulation investments across the supply base.
Plant-based absorbent cores derived from agricultural waste streams are virtualizing petroleum-dependent polymer architectures. Sustainability-focused millennials and Gen Z buyers are accelerating adoption through social media-influenced purchasing. This material transition is virtualizing conventional supply relationships between petrochemical suppliers and finished goods manufacturers, compressing incumbent raw material contracts.
New York's ingredient disclosure law and California's tampon tax elimination are reshaping pricing transparency and marketing claims verification. The FTC's Green Guides enforcement against biodegradable labeling is forcing substantiation investments. Premium organic segments in these states are responding with blockchain-traceable supply chain documentation to preempt regulatory challenge.
Subscription auto-replenishment is displacing emergency convenience store purchases among established users. Mass retailers are losing traffic to specialized DTC platforms offering customizable absorbency mixes. This channel rotation is most visible in metropolitan coastal markets where same-day delivery infrastructure supports just-in-cycle fulfillment models.
United States Sanitary Napkin Market Segmentation
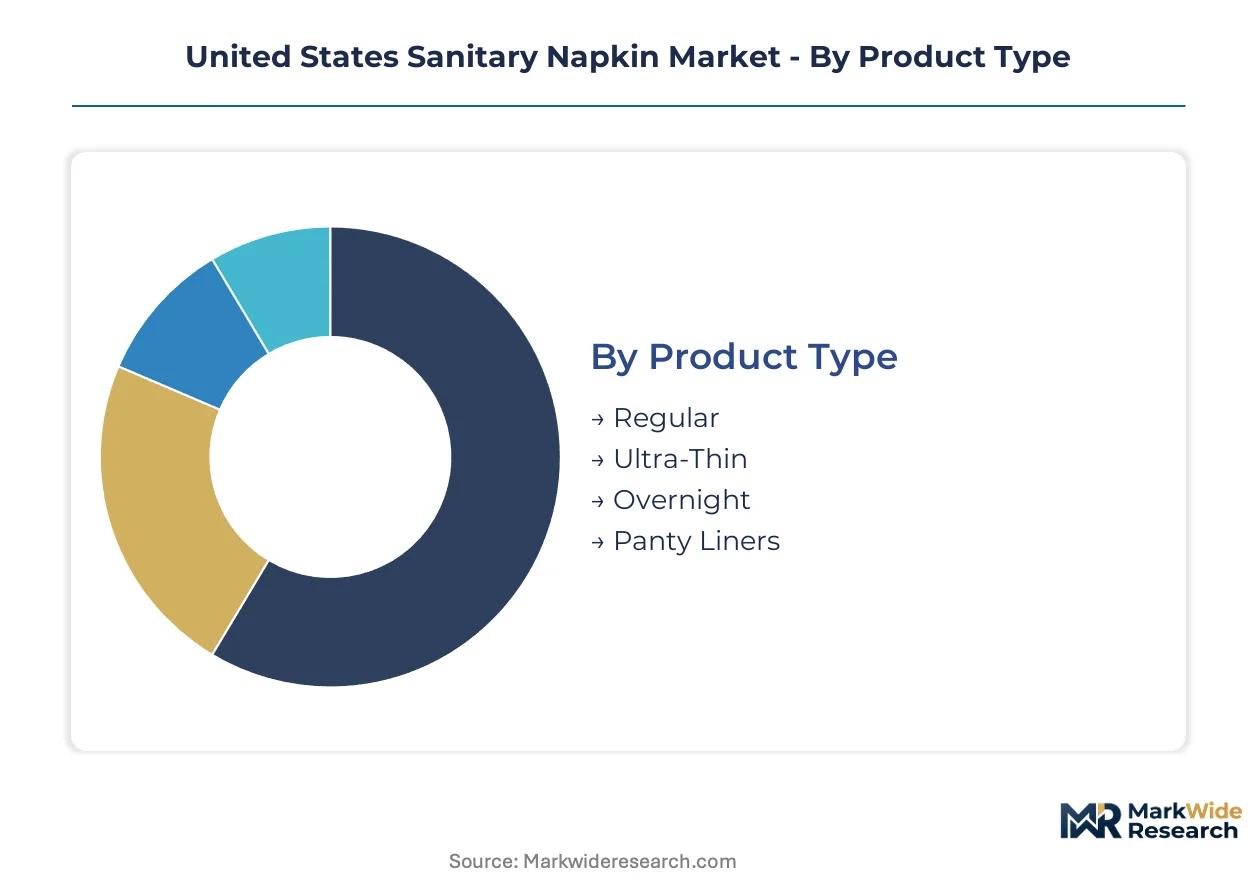
Product differentiation in the United States sanitary napkin market follows distinct usage occasions, material preferences, and distribution economics. Each segmentation dimension reveals divergent margin structures and channel strategies that manufacturers must navigate.
Product Type:
Absorbency requirements and wear duration create four distinct product architectures serving different moments in the menstrual cycle.
- Regular:Standard absorbency cores with 180-240mm lengths address moderate flow days for the broadest user base. Demand concentrates in suburban mass retail channels where multi-pack promotions drive volume.
- Ultra-Thin:Compressed superabsorbent polymer layers achieve sub-3mm profiles without leakage compromise. California and New York working professionals prioritize discretion, pulling national assortment toward this format.
- Overnight:Extended 280-320mm lengths with reinforced rear wings manage heavy flow and sleeping positions.
- Panty Liners:Light-absorbency daily wear products for non-menstrual discharge or backup protection.
The dominant share belongs to Regular products, while Ultra-Thin is closing the gap fastest.
Material:
Raw material sourcing strategies bifurcate between petroleum-dependent synthetics and agricultural-based alternatives with divergent certification economics.
- Cotton:Conventional cotton fluff pulp cores dominate cost-optimized production lines serving dollar store and discount channels. Texas and Georgia textile suppliers anchor domestic sourcing.
- Biodegradable:Plant-based absorbent cores from agricultural waste streams face FTC Green Guide scrutiny on decomposition claims. California buyers respond to verified compostability despite 25-35% price premiums.
- Synthetic:Polypropylene topsheets and petroleum-derived superabsorbent polymers enable ultra-thin engineering.
- Organic:USDA-certified cotton and OEKO-TEX Standard 100 compliance command the steepest price premiums.
Cotton maintains volume leadership, though Organic certification is expanding most quickly among coastal health-conscious segments.
Packaging Type:
Unit economics and purchase occasion segmentation drive four distinct packaging configurations across retail and institutional channels.
- Pack of 10:Entry-level trial sizes and convenience store emergency purchases. Urban bodegas and pharmacy checkout lanes concentrate this format.
- Pack of 20:Standard household replenishment quantity balancing per-unit cost with storage practicality. Mass merchant shelf space allocation favors this SKU density.
- Bulk Packs:40-100 count configurations serve California and New York menstrual equity programs in schools and correctional facilities.
- Individual Wraps:Single-unit discreet packaging for workplace restrooms, travel, and first-aid kits.
Pack of 20 dominates household purchasing, while Bulk Packs are gaining share fastest through institutional procurement mandates.
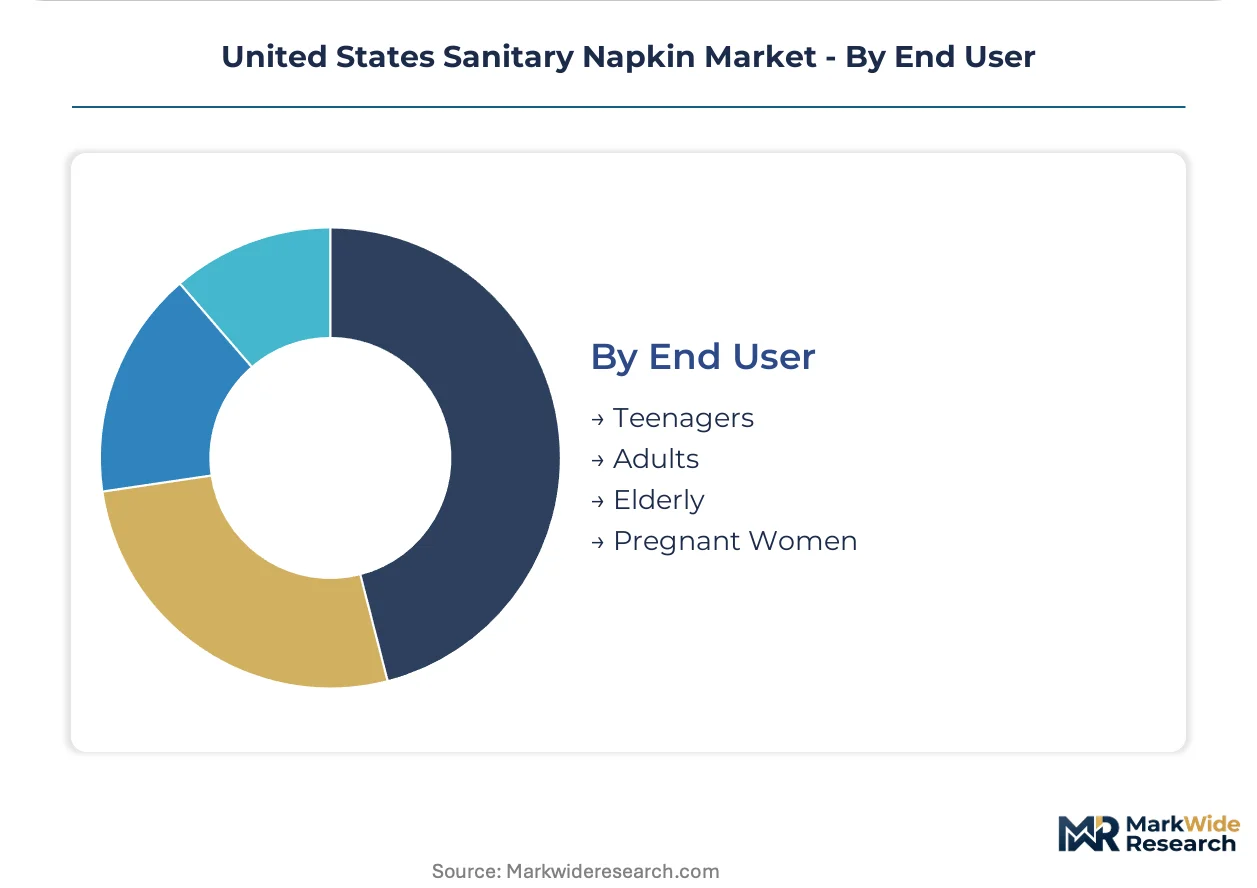
End User:
Age and physiological condition create distinct absorbency needs, brand relationship formation windows, and channel access patterns.
- Teenagers:First-period educational marketing and school nurse distribution programs establish brand loyalty before purchasing autonomy. California mandates free access in public schools.
- Adults:Working-age women aged 18-45 constitute the core revenue base with established cycle predictability and subscription adoption. New York professional segments drive premium organic demand.
- Elderly:Light incontinence and post-menopausal discharge management overlaps with panty liner usage.
- Pregnant Women:Elevated discharge and postpartum lochia create temporary elevated absorbency requirements distinct from standard menstrual products.
Adults anchor absolute demand volume, while Teenager-focused programming is expanding fastest through state-mandated school access policies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal metropolitan areas exhibit fundamentally different consumption patterns than interior states, with premium organic formulations commanding shelf space in California and New York while value-tier products dominate Texas and Florida mass retail channels.
California
Los Angeles and San Francisco Bay Area working professionals drive ultra-thin and organic certification demand, with USDA Organic and OEKO-TEX Standard 100 products capturing significant price premiums. The state's menstrual equity legislation mandates free product access in public schools and correctional facilities, creating institutional bulk procurement channels alongside traditional retail. San Diego and Sacramento distribution hubs serve as West Coast consolidation points for both domestic manufacturing and Asian imports.
New York
Manhattan and Brooklyn consumers prioritize discreet, subscription-based delivery models over emergency convenience store purchases, compressing traditional brand loyalty cycles. State-level tampon tax elimination and ingredient disclosure laws reshape pricing transparency and marketing claims verification. Buffalo and Rochester manufacturing facilities anchor Northeast production capacity for both conventional and plant-based absorbent core formulations.
Texas
Houston and Dallas-Fort Worth mass retail channels concentrate demand for cotton-based, cost-optimized products serving suburban and exurban household budgets. The state's petrochemical corridor supplies polypropylene feedstock for nonwoven topsheet production, though Gulf Coast hurricane exposure creates periodic supply vulnerability. Austin's tech workforce exhibits emerging subscription adoption patterns diverging from statewide averages.
Illinois
Chicago's diverse demographic composition supports multi-tier retail assortments spanning premium organic through dollar-store value positioning. The state's central logistics infrastructure positions it as a distribution nexus connecting East Coast manufacturing to Midwest consumption. Peoria and Rockford secondary markets demonstrate stronger teenager-oriented educational marketing responsiveness tied to school health curriculum partnerships.
Florida
Miami and Tampa tourism-dependent retail channels emphasize individual-wrap and travel-sized formats for hospitality industry procurement. The state's retiree concentration elevates panty liner demand for light incontinence management distinct from standard menstrual products. Orlando's central location supports distribution network efficiency for Southeast regional fulfillment.
United States Sanitary Napkin Market Key Industry Players
Capability concentration sits with specialized material innovators; scale advantage sits with diversified consumer goods conglomerates. The market exhibits tiered structure with three to four national-scale manufacturers commanding retail shelf dominance while regional specialists capture subscription and organic certification niches. Strategic archetypes separate into petrochemical-integrated mass producers, agricultural supply chain controllers, and direct-to-consumer platform operators. Dominant competitive moves include backward integration into fluff pulp supply and technology licensing for superabsorbent polymer formulations.
Among diversified consumer goods conglomerates, Procter & Gamble and Kimberly-Clark exemplify scale-driven retail channel control, while Edgewell Personal Care occupies a position within value-tier competitive positioning. Japanese and European multinationals including Unicharm Corporation and Essity AB represent international portfolio diversification archetypes with US market presence. These named entities serve as anchors for understanding how geographic origin and corporate structure shape strategic options without prescribing specific tactical decisions.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Essity AB |
| Procter & Gamble |
| First Quality Enterprises |
| Kao Corporation |
| Kimberly-Clark |
| Hengan International Group |
| Ontex Group |
| Edgewell Personal Care |
| Others |
Cost & Logistics Intelligence
Interstate 35 freight corridors linking Texas petrochemical complexes to Midwest manufacturing hubs transmit cost volatility directly into finished goods pricing, compressing margins on cotton-based value tiers while enabling premium capture for organic-certified products in coastal markets. This logistics architecture concentrates pricing power among distributors with captive rail and warehousing capacity.
Pricing Analysis
Long-term offtake contracts between fluff pulp suppliers and major manufacturers anchor input cost predictability, though spot market exposure for superabsorbent polymers introduces quarterly margin variability. Price differentiation rests on USDA Organic certification and OEKO-TEX Standard 100 compliance, with subscription models capturing lifetime value through cycle-tracking app integration. Cost compression in synthetic material tiers is intensifying because polypropylene feedstock draws from Gulf Coast petrochemical exposure. Dollar store channels exhibit highest price sensitivity; direct-to-consumer organic subscribers show lowest.
Supply Chain Analysis
Export-control scrutiny on advanced hydrogel formulations limits technology transfer to domestic superabsorbent polymer production, constraining innovation sourcing. Geographic concentration centers on United States fluff pulp from Georgia and Alabama, Canadian softwood pulp, and Chinese superabsorbent polymer imports. Raw material dependencies span cotton lint, polypropylene resin, and petroleum-derived hydrogel precursors. Single-source vulnerability runs through Gulf Coast petrochemical complexes exposed to hurricane disruption. Distribution runs through mass merchant DC networks, with direct-to-consumer fulfillment bypassing traditional retail slotting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Menstrual equity legislation in California and New York is institutionalizing bulk procurement channels at double-digit growth rates, compressing traditional retail dominance and rewarding manufacturers with state contract certification.
For Market Incumbents: Pre-empt subscription platform erosion by acquiring cycle-tracking app capabilities or licensing biometric integration patents. Consolidate fluff pulp supply through backward integration into Georgia and Alabama timberland assets. Channel control through exclusive school distribution partnerships defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Establish a beachhead in teenager-oriented educational marketing through curriculum-integrated health programs in California public schools. White-space targets include blockchain-traceable organic certification for coastal professional segments and compostable core formulations verified under FTC Green Guide standards. Go-to-market angle: school nurse direct distribution bypasses retail slotting barriers. For Investors and Strategic Acquirers: Direct-to-consumer platform operators with proprietary cycle data algorithms represent the highest-multiple acquisition archetype in this category. Long-term viability hinges on regulatory compliance infrastructure and subscription retention engineering. Signal to watch: FDA 510(k) clearance acceleration timelines for novel plant-based absorbent materials.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Expansion | USDA Organic and OEKO-TEX credentials command 40-60% price premiums in California and New York. |
| Direct-to-Consumer Platform Launch | Subscription auto-replenishment captures recurring revenue previously held by mass retailers. |
| State Procurement Certification | Menstrual equity mandates in California and New York create institutional volume channels outside retail. |
| Plant-Based Core Development | Agricultural waste stream absorbents virtualize petroleum-dependent polymer architectures for sustainability positioning. |
| Cycle-Tracking App Integration | Biometric data platforms compress brand loyalty cycles and enable personalized absorbency matching. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with brand managers, retail category buyers, supply chain planners, and regulatory affairs specialists at FDA-cleared manufacturers; and secondary validation through FDA 510(k) filings, state procurement databases, Nielsen retail audit data, and customs import records. Bottom-up triangulation across product-level volume estimates and top-down reconciliation against aggregate market sizing anchored forecast integrity.
Forecast inputs considered absorbency tier, material certification grade, packaging format, distribution channel, and end-user age segment across the projection horizon. CAGRs were derived from segment-level growth rate modeling applied to baseline volume estimates. Industry-specific inputs included FDA clearance timeline distributions and state menstrual equity procurement rollout schedules.
Stress conditions across fluff pulp cost volatility, Gulf Coast hurricane frequency, and subscription churn rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and consumer willingness-to-pay for organic certification. Material shifts in FDA Class II device reclassification or federal menstrual equity mandate passage would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Medical Fabrics Market