
 Latin America Sanitary Napkin Market | 2026-2036
Latin America Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Sanitary Napkin Market Intelligence
Teen and maternity end-user demand is shifting toward specialized absorbency tiers across Latin America. Procter & Gamble Co. leverages its brand architecture to dominate supermarket and pharmacy shelf space throughout Brazil and Mexico. Kimberly-Clark Corporation anchors regional production through localized manufacturing assets that reduce import dependency. Essity Aktiebolag differentiates via sustainability messaging tied to biodegradable material transitions.
A sanitary napkin is an absorbent hygiene product designed for menstrual management, typically constructed with a topsheet, absorbent core of fluff pulp and superabsorbent polymers, and breathable backsheet to prevent leakage. Overnight pads lead product type revenue pools due to premium pricing and higher absorbency engineering, while organic pads represent the fastest-growing material-positioned segment as ANVISA and Mexico's COFEPRIS tighten chemical disclosure rules. Supermarkets control the dominant distribution channel share, though online retail accelerates fastest among teens and urban professionals seeking subscription models.
ANVISA governs sanitary product registration and microbiological safety standards in Brazil, while COFEPRIS regulates absorbent hygiene labeling and ingredient transparency in Mexico; both agencies are expanding biodegradable and chlorine-free certification requirements that reshape supplier qualification. Stakeholders must monitor how evolving material standards across Brazil, Mexico, and Colombia will force reformulation investments and filter which manufacturers retain market access.
Market Dynamics
Biodegradable material mandates from ANVISA and COFEPRIS are forcing wholesale absorbent core reformulation across Brazilian and Mexican manufacturing bases, compressing legacy fluff pulp supply chains while opening qualification pathways for certified organic cotton and plant-based polymer alternatives.
Growth Catalysts
- ANVISA Hygiene Standards:Brazil's tightening microbiological safety protocols are accelerating facility upgrades among domestic converters, filtering out subscale suppliers and consolidating shelf access for compliant manufacturers.
- Teen Segment Expansion:First-menstruation product access programs in Mexican public schools are creating institutional procurement channels that bypass traditional retail markups and build brand loyalty early.
- Supermarket Channel Penetration:Pharmacy and hypermarket shelf-space expansion in São Paulo and Rio de Janeiro is unifying product visibility across income tiers, pulling volume from informal street vendors.
Market Restraints
- Superabsorbent Polymer Cost Volatility:Petrochemical feedstock fluctuations for acrylic acid derivatives compress margin buffers for mid-tier producers locked into annual retail pricing contracts.
- Import Dependency for Specialty Fibers:Latin American manufacturers lack domestic production of certified organic cotton and bamboo pulp, concentrating supply risk on Southeast Asian fiber traders.
- COFEPRIS Ingredient Disclosure Friction:Mexico's expanding chemical transparency requirements extend product registration timelines by 8-14 months for reformulated SKUs, delaying revenue recognition.
Strategic Opportunities
- Colombian Andean Corridor:Underpenetrated pharmacy distribution in Bogotá and Medellín offers first-mover advantage for brands willing to build cold-chain logistics for natural material preservation.
- Subscription Direct-to-Consumer Models:Urban professionals in Mexico City and São Paulo are bypassing supermarket aisles for auto-replenishment apps, capturing lifetime value through data-driven personalization.
- Biodegradable Certification Tailwinds:ANVISA's pending chlorine-free absorbency standard creates qualification moats for early certifiers, locking out reformulation-laggards from pharmacy formulary access.
Industry Challenges
- Biopolymer Process Engineering Talent Scarcity:Local universities lack specialized programs in sustainable absorbent material science, forcing manufacturers to import Brazilian and Argentine technical staff at premium compensation.
- Legacy Equipment Retrofit Capex Burden:Converting lines engineered for synthetic cores require seven-figure investments to handle natural fiber variability without throughput degradation.
- Multi-Jurisdiction Labeling Complexity:Divergent ANVISA and COFEPRIS packaging standards force SKUs to carry dual compliance markings, complicating cross-border inventory pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Sanitary Napkin Market |
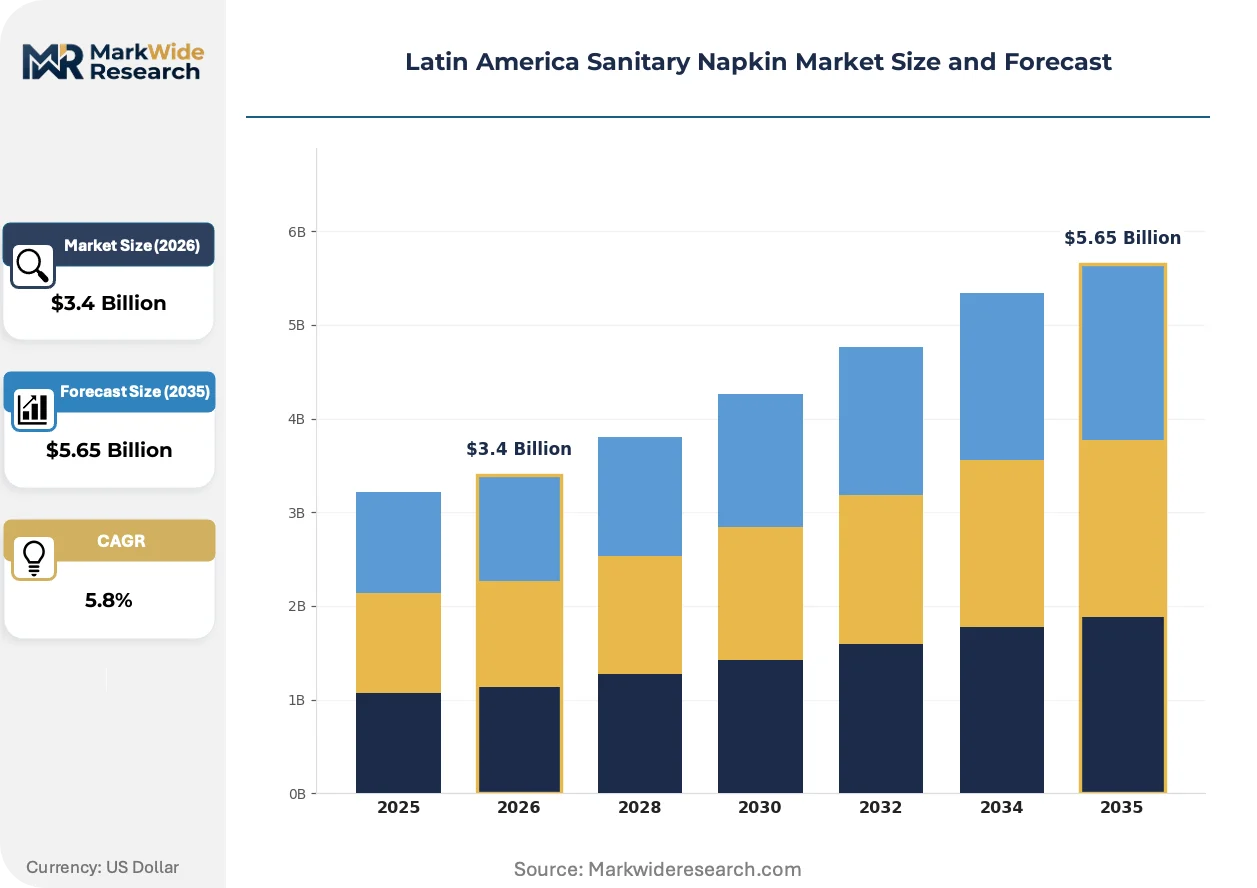
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Pads, Overnight Pads, Pantyliners, Organic Pads End User: Women, Teens, Maternity, Seniors Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Material: Cotton, Biodegradable, Synthetic, Chlorine-Free |
| Companies Covered | Essity Aktiebolag, Kao Corporation, Procter & Gamble Co., Edgewell Personal Care Company, Hengan International Group Company Limited, Kimberly-Clark Corporation, Unicharm Corporation, First Quality Enterprises, Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Sanitary Napkin Market Strategic Shifts & Innovations
Material science convergence with digital distribution infrastructure is compressing traditional go-to-market cycles, enabling faster formulation iteration while fragmenting buyer touchpoints across physical and virtual channels.
Plant-based superabsorbent polymers derived from cassava starch and sugarcane bagasse are unifying absorbency performance with biodegradability certification requirements. Teen and maternity segments in Brazil are adopting these materials fastest, driven by social media transparency campaigns. This chemistry shift is unifying previously separate premium and sustainability price tiers into single-positioned SKUs.
COFEPRIS is expanding mandatory ingredient disclosure to include fragrance allergens and dye compounds, forcing reformulation of legacy scented product lines. Manufacturers serving the Mexican market are stripping synthetic additives to avoid registration delays. The overnight pad segment faces the steepest compliance burden due to higher chemical load in odor-control formulations.
Urban professionals across São Paulo and Mexico City are consolidating purchases through subscription platforms that bundle menstrual products with wellness diagnostics. Pharmacy chains are responding with private-label auto-replenishment portals, disintermediating traditional CPG distributors. This channel rotation is most visible among dual-income households aged 25-34 seeking convenience without stockout risk.
Latin America Sanitary Napkin Market Segmentation
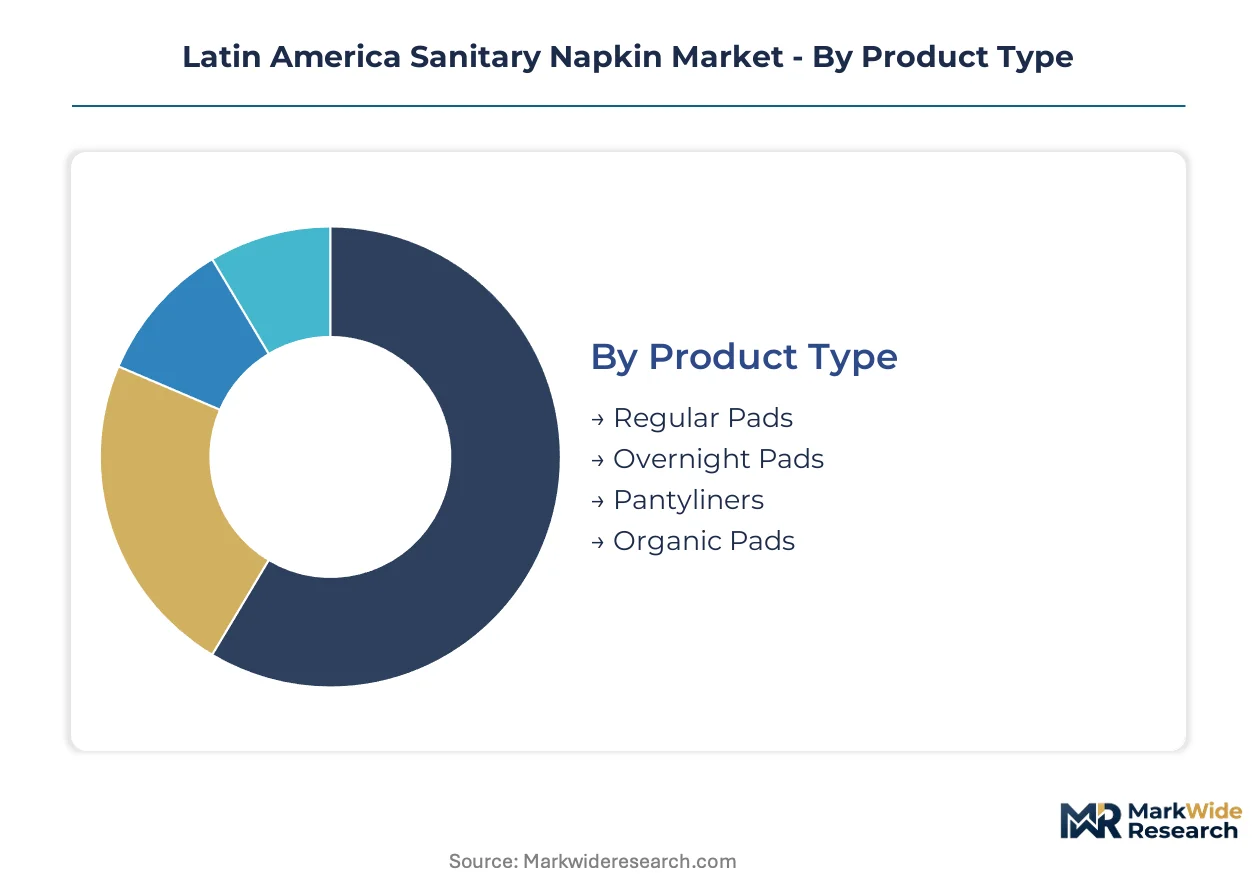
Segmentation in Latin America's sanitary napkin market reveals how product positioning must navigate divergent regulatory environments across Brazil, Mexico, and Colombia. Manufacturers face distinct formulation and channel requirements depending on whether they target teen access programs, maternity wards, or urban subscription buyers.
Product Type:
Standalone disposable products dominate pharmacy shelves, while embedded subscription bundles reshape how consumers encounter specialized formats.
- Overnight Pads:Engineered with expanded absorbent cores and wider rear guards to manage elevated flow volumes during sleep cycles. São Paulo and Rio de Janeiro households pull disproportionate volume as pharmacy chains prioritize premium shelf placement. ANVISA's absorbency labeling standards force disclosure of core polymer density, compressing formulation variance among compliant suppliers.
- Organic Pads:Constructed with certified organic cotton topsheets and plant-based backsheet films to meet biodegradable certification pathways. Brazilian teen segments adopt these fastest following social media transparency campaigns targeting COFEPRIS chemical disclosure rules. Reformulation investments here lock out mid-tier competitors lacking certified fiber supply relationships.
- Regular Pads:Standard absorbency products serving baseline menstrual management across income tiers.
- Pantyliners:Thin daily-use formats with minimal core density for light discharge and end-cycle spotting.
Overnight pads lead volumes today; organic pads are gaining share fastest.
End User:
Customer lifecycle positioning separates institutional procurement channels from retail-driven brand building.
- Teens:First-menstruation product access programs in Mexican public schools create bulk procurement channels that bypass traditional retail markups. COFEPRIS-mandated ingredient transparency resonates strongly with parent purchasing committees evaluating school vendor selections.
- Maternity:Postpartum absorbency requirements drive elevated pad thickness and extended wear-time engineering. Brazilian hospital formulary access depends on ANVISA microbiological safety certification, filtering supplier pools to compliant domestic converters.
- Women:Core reproductive-age segment with established brand loyalty and channel preferences.
- Seniors:Light incontinence overlap creates dual-use positioning challenges for pure-play menstrual brands.
Women constitute the volume base; teens show the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin structure and customer data access for subscription economics.
- Supermarkets:São Paulo and Rio de Janeiro hypermarket chains unify product visibility across income tiers, pulling volume from informal street vendors. Shelf-space negotiations with Grupo Pão de Açúcar and Chedraui concentrate access for manufacturers with national logistics scale.
- Online Retail:Mexico City and São Paulo urban professionals bypass supermarket aisles for auto-replenishment apps capturing lifetime value through data-driven personalization. Pharmacy chains respond with private-label portals, disintermediating traditional CPG distributors.
- Pharmacies:Regulated channel with ANVISA and COFEPRIS compliance requirements that filter supplier access.
- Convenience Stores:Emergency purchase occasions with limited SKU depth and premium pricing tolerance.
Supermarkets anchor volume today; online retail is climbing the fastest.
Material:
Raw material certification status increasingly determines pharmacy formulary eligibility across Brazilian and Mexican regulatory jurisdictions.
- Biodegradable:Cassava starch and sugarcane bagasse-derived superabsorbent polymers unify absorbency performance with ANVISA pending certification requirements. Local universities lack specialized programs in sustainable absorbent material science, forcing manufacturers to import technical staff at premium compensation.
- Chlorine-Free:Bleaching process certification addresses growing consumer preference for reduced chemical exposure in intimate products. COFEPRIS expansion of mandatory disclosure to fragrance allergens and dye compounds accelerates stripping of synthetic additives from legacy formulations.
- Cotton:Natural fiber baseline with conventional agricultural sourcing and established supply chains.
- Synthetic:Petrochemical-derived materials facing reformulation pressure from tightening transparency mandates.
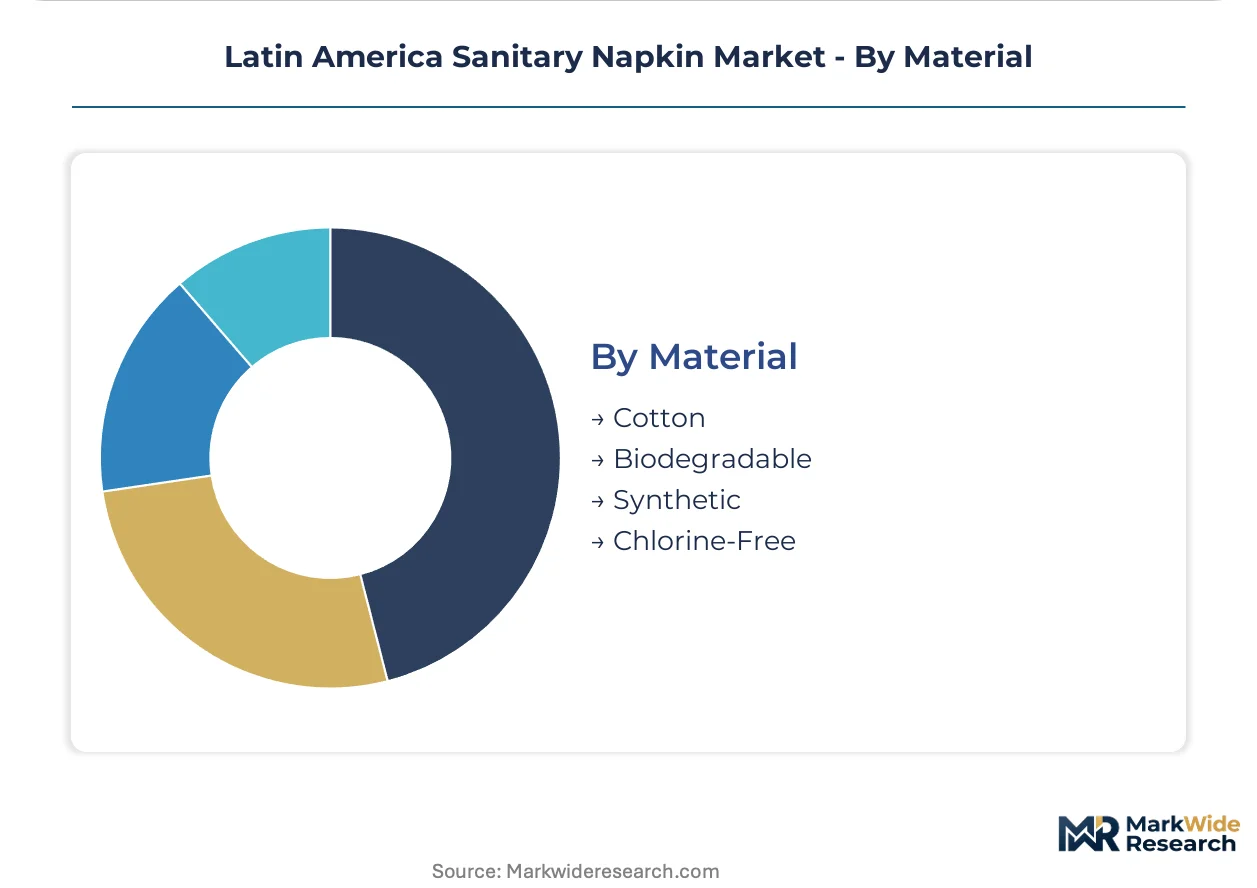
Cotton dominates volume today; biodegradable materials show the sharpest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin America's sanitary napkin demand through concentrated pharmacy chains and supermarket penetration that pulls volume from informal channels across Brazil's urban centers.
Brazil
ANVISA hygiene standards filter domestic converters through microbiological safety certification requirements that consolidate shelf access for compliant manufacturers. São Paulo and Rio de Janeiro hypermarket chains unify product visibility across income tiers, disintermediating street vendors through formal retail expansion. Facility upgrades accelerate among domestic converters seeking pharmacy formulary eligibility under tightening protocols.
Mexico
COFEPRIS ingredient disclosure mandates extend product registration timelines for reformulated SKUs, delaying revenue recognition for manufacturers adapting to chemical transparency rules. First-menstruation product access programs in Mexican public schools create institutional procurement channels that bypass traditional retail markups. Mexico City urban professionals drive subscription platform adoption for auto-replenishment models capturing lifetime value.
Colombia
Underpenetrated pharmacy distribution in Bogotá and Medellín offers first-mover positioning for brands building cold-chain logistics for natural material preservation. The country's national pharmaceutical regulator tightens labeling standards that reshape supplier qualification pathways. Andean corridor urban clusters concentrate demand among dual-income households seeking convenience-oriented purchase formats.
Argentina
Import dependency for specialty fibers concentrates supply risk on Southeast Asian traders serving Buenos Aires manufacturing bases. Economic volatility compresses margin buffers for mid-tier producers locked into annual retail pricing contracts. Local universities lack specialized programs in sustainable absorbent material science, forcing manufacturers to import technical staff at premium compensation.
Chile
Santiago metropolitan demand concentrates among pharmacy and supermarket channels with expanding shelf-space for biodegradable-certified products. Consumer preference for reduced chemical exposure in intimate products accelerates stripping of synthetic additives from legacy formulations. Cold-chain infrastructure investments support natural material preservation requirements for plant-based polymer alternatives.
Latin America Sanitary Napkin Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers retrofit converting lines for biodegradable core materials. The market structures around three tiers: multinational CPG conglomerates with national logistics scale, regional specialists with ANVISA-certified domestic production, and emerging subscription-native brands bypassing traditional retail. Strategic archetypes include supermarket shelf-space negotiators, pharmacy formulary access specialists, and direct-to-consumer platform operators. M&A activity and backward integration into certified fiber supply chains represent the dominant competitive moves reshaping supplier relationships.
Among multinational CPG anchors, Procter & Gamble Co., Kimberly-Clark Corporation, and Essity Aktiebolag exemplify distinct strategic positioning archetypes. Procter & Gamble Co. occupies a position representing brand architecture leverage across pharmacy and supermarket shelf space. Kimberly-Clark Corporation anchors regional production capabilities through localized manufacturing assets that reduce import dependency. Essity Aktiebolag sits within the sustainability-messaging tier, differentiating via biodegradable material transitions tied to tightening ANVISA and COFEPRIS certification requirements.
| Leading Market Players |
|---|
| Essity Aktiebolag |
| Kao Corporation |
| Procter & Gamble Co. |
| Edgewell Personal Care Company |
| Hengan International Group Company Limited |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| First Quality Enterprises, Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Cost & Logistics Intelligence
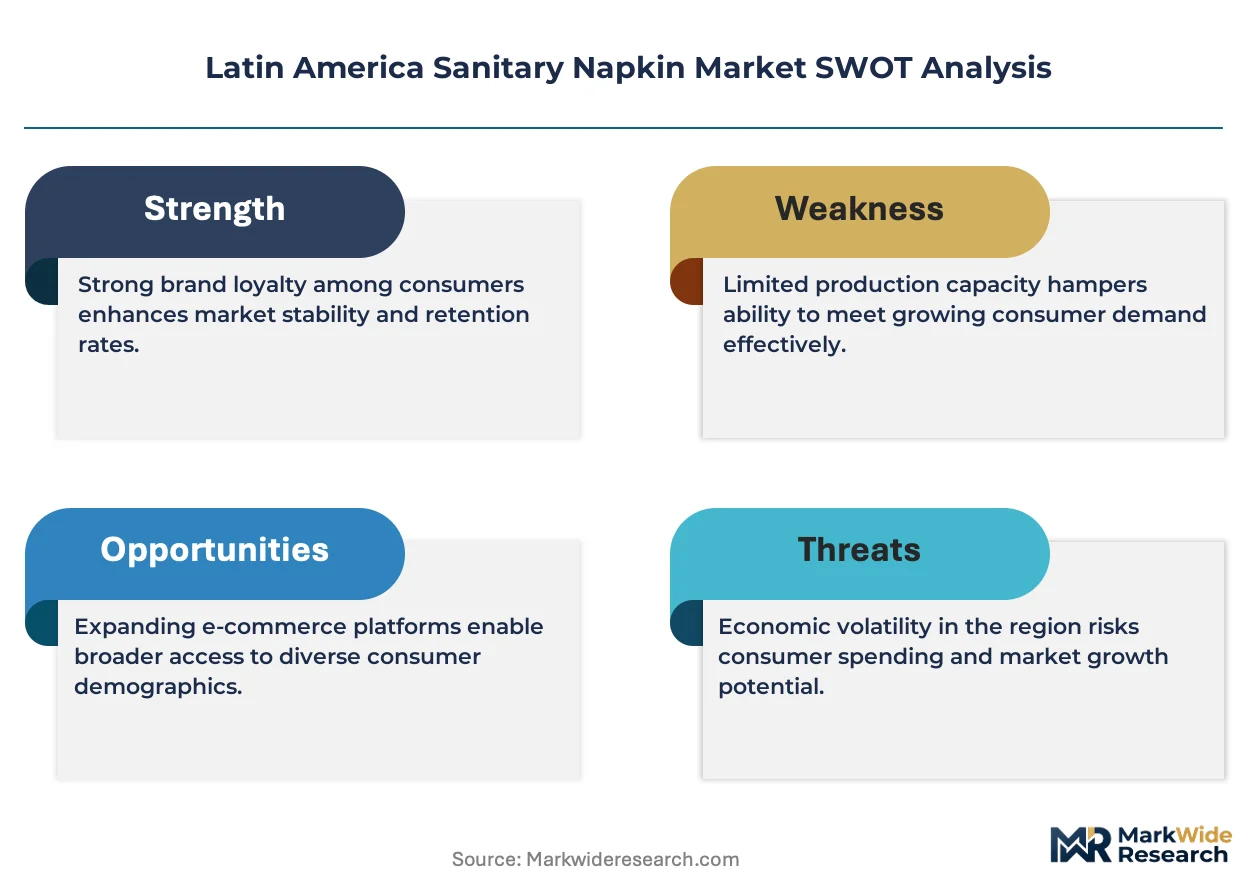
ANVISA's pending chlorine-free absorbency certification gates both qualified supply and premium-tier pricing access, compressing margins for converters lacking reformulation readiness while rewarding early certifiers with pharmacy formulary placement and pricing power over laggards.
Pricing Analysis
Pharmacy chain markup layers absorb compliance certification costs into shelf pricing, while direct-to-consumer subscription models bypass retail margin stacking entirely. Three-tier pricing structure across premium biodegradable, standard synthetic-core, and economy unbranded levels separates buyers by certification sensitivity rather than absorbency performance alone. Cost compression in mid-tier synthetic products is intensifying because COFEPRIS registration delays strand inventory carrying costs. Teen segment buyers through Mexican school procurement channels exhibit lowest price sensitivity; informal street vendor customers in Brazilian urban peripheries show highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale supermarket and pharmacy chain demand through national distribution networks anchored in São Paulo and Mexico City. Raw material dependencies draw from Southeast Asian certified organic cotton traders, Brazilian fluff pulp processors, and German specialty chemical suppliers for plant-based polymer alternatives. Single-source vulnerability concentrates in certified fiber supply, where Latin American manufacturers lack domestic production capacity. Distribution runs through Grupo Pão de Açúcar and Chedraui hypermarket networks, with pharmacy chains operating parallel cold-chain logistics for natural material preservation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's sanitary napkin market offers geographic-arbitrage returns for manufacturers relocating production from import-dependent Argentina to ANVISA-certified Brazilian facilities, capturing regulatory compliance cost differentials and logistics proximity to Andean corridor demand.
For Market Incumbents: Hedge against biodegradable certification disruption by accelerating backward integration into certified organic cotton supply relationships before ANVISA finalizes chlorine-free standards. Lock pharmacy formulary access through facility upgrades that filter subscale competitors. Defensive capacity addition in São Paulo manufacturing corridors captures shelf-space consolidation as compliance costs rise.
For New Entrants and Emerging Players: Enter via subscription-native positioning targeting Mexico City and São Paulo dual-income households aged 25-34, where auto-replenishment apps bypass entrenched supermarket distribution. Colombian pharmacy distribution in Bogotá and Medellín presents the most penetrable white-space geography. Go-to-market execution should anchor on cold-chain logistics partnerships for natural material preservation.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Brazilian converters with ANVISA certification gaps but intact retail relationships. Long-term viability hinges on reformulation capex execution over the next decade. Acquisition targets should display certified fiber supply contracts or proprietary plant-based polymer processing capabilities. Watch ANVISA chlorine-free standard promulgation timing as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Investment | ANVISA chlorine-free standard compliance locks pharmacy formulary access against reformulation laggards. |
| Backward Integration into Certified Fiber Supply | Captive organic cotton sourcing reduces Southeast Asian import dependency and registration timeline risk. |
| Subscription Platform Launch | Mexico City and São Paulo urban professionals bypass supermarket markups through auto-replenishment apps. |
| Cold-Chain Logistics Buildout | Natural material preservation requirements enable Colombian Andean corridor pharmacy distribution expansion. |
| Facility Upgrade for Microbiological Safety | ANVISA hygiene protocol compliance filters domestic converter competition and consolidates shelf access. |
Research Approach
Coverage spans Brazil, Mexico, Colombia, Argentina, and Chile, with primary inputs from each market's manufacturing base and distribution channels. The analysis combines structured interviews with plant managers at domestic converting facilities, procurement leads at Grupo Pão de Açúcar and Chedraui, ANVISA regulatory affairs specialists, and pharmacy chain category buyers. Secondary validation draws from customs records tracking fluff pulp and superabsorbent polymer imports, ANVISA product registration databases, COFEPRIS chemical disclosure filings, and Nielsen retail audit data. Bottom-up channel volume estimates triangulate against top-down category spending benchmarks.
Granularity-level modeling operates at product type, end-user segment, distribution channel, and material certification status dimensions. Absorbency tier engineering specifications and biodegradable certification pathways were modeled as industry-specific forecast inputs. CAGRs derive from regression analysis of historical volume trends against regulatory implementation schedules and channel penetration curves across the projection horizon.
Inputs from ANVISA registration databases and COFEPRIS disclosure filings were available through the study window; gaps in real-time subscription platform transaction data introduce uncertainty bands around direct-to-consumer growth trajectories. Forecasts reflect assumptions regarding regulatory timeline adherence and fiber supply contract renewals. Periodic stress-testing of base assumptions is recommended given petrochemical feedstock volatility and pending certification standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Surgical Drapes Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Examination Gowns Market