
 Antimicrobial Textiles Market | 2026-2036
Antimicrobial Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Textiles Market Analysis
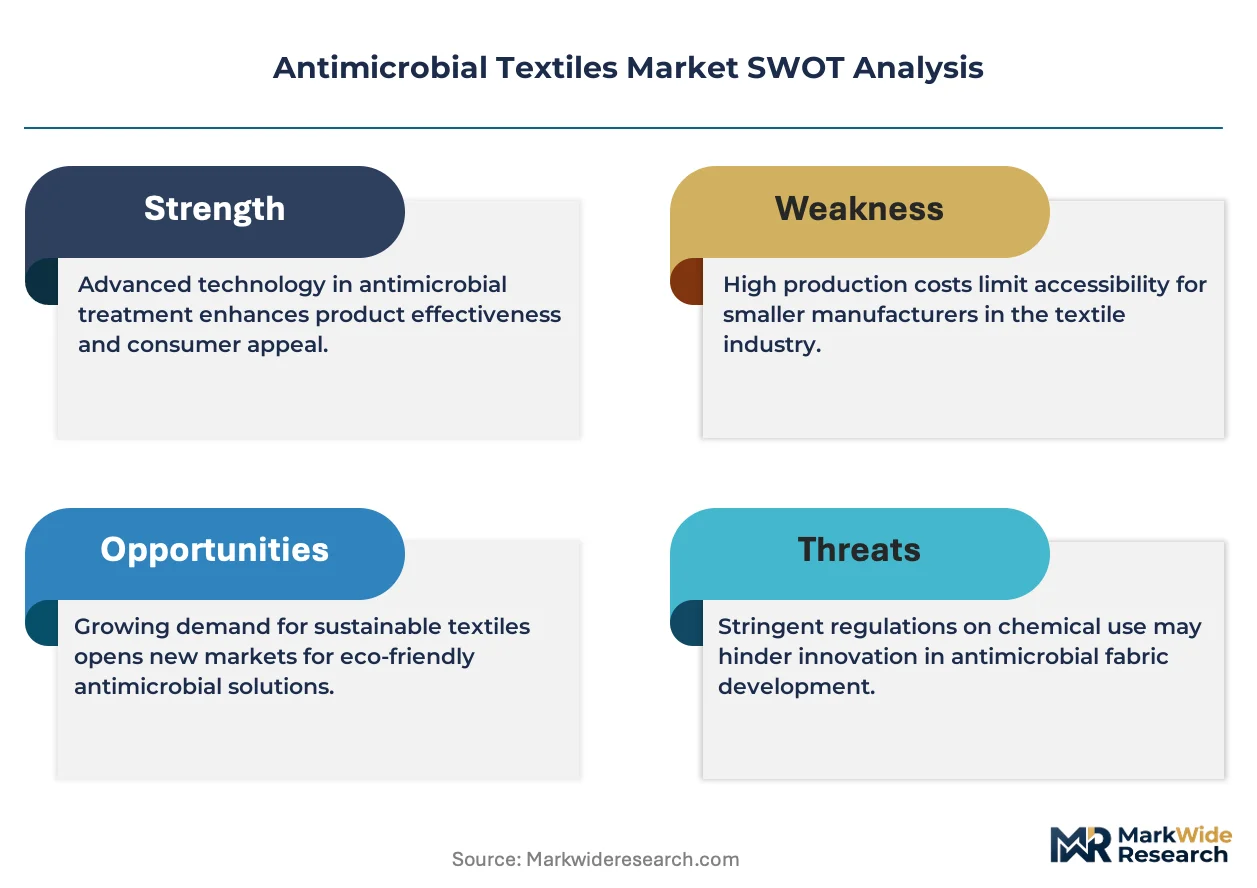
Healthcare procurement is decoupling from commodity textile sourcing as hospitals demand certified antimicrobial performance in scrubs, linens, and privacy curtains. HeiQ Materials AG leverages its Swiss R&D base to sustain technology leadership in bio-based finishing chemistry. Milliken & Company anchors North American supply through its South Carolina manufacturing complex, while BASF SE competes by extending its polymer science expertise into silver-ion masterbatch formulations.
Antimicrobial textiles are engineered fabrics treated with biocidal agents—silver ions, quaternary ammonium compounds, or chitosan derivatives—that inhibit microbial colonization on fiber surfaces, with efficacy typically measured by ISO 20743 reduction rates against Staphylococcus aureus and Klebsiella pneumoniae. The primary commercial purpose spans infection prevention in clinical settings, odor control in athletic wear, and hygiene maintenance in hospitality environments. Cotton dominates material value pools due to its absorbency and compatibility with diverse finishing chemistries, while nano-coating technology represents the fastest-expanding segment as manufacturers seek durable functionality without altering hand feel. Healthcare textiles remain the most margin-rich end-user category, given stringent validation requirements and long-term hospital supply contracts.
The EPA regulates antimicrobial claims under FIFRA in the United States, requiring treated articles to meet specific efficacy thresholds before marketing, while the EU Medical Device Regulation classifies certain antimicrobial textiles as Class I medical devices, imposing CE marking and clinical evaluation obligations. REACH restrictions on silver nanoparticles and triclosan are forcing reformulation toward bio-based and organic treatment pathways. Stakeholders must monitor evolving biocompatibility standards and decide whether to pursue vertical control over finishing operations or partner with specialized chemical suppliers.
Market Dynamics
Hospital infection control mandates are compressing validation timelines for antimicrobial textile suppliers, forcing simultaneous compliance with EPA FIFRA claims in the United States and EU MDR biocompatibility protocols in Europe.
Growth Catalysts
- EU Medical Device Regulation:Class I device designation for antimicrobial hospital textiles creates mandatory CE marking demand, locking suppliers into long-term clinical evaluation contracts with European healthcare systems.
- Silver-ion masterbatch chemistry:Polymer science advances enable durable biocidal functionality in synthetic fibers without compromising tensile strength, expanding application into high-wear surgical garments.
- German technical textile clusters:Stuttgart and Chemnitz manufacturing networks are embedding antimicrobial finishing into automotive and industrial supply chains, diversifying revenue beyond healthcare.
Market Restraints
- REACH silver nanoparticle restrictions:ECHA substance evaluations are forcing costly reformulation away from established biocidal chemistries toward unproven bio-based alternatives.
- Cotton price volatility:Natural fiber input costs fluctuate with agricultural yields and climate disruption, squeezing margin on the dominant material value pool.
- Triclosan phase-out:EPA and EU parallel bans on organohalogen biocides eliminated a low-cost treatment pathway, compressing mid-market pricing flexibility.
Strategic Opportunities
- India hospital infrastructure expansion:CDSCO medical device registration pathways for antimicrobial textiles remain underdeveloped, creating first-mover advantage for compliant foreign suppliers.
- Nano-coating durability convergence:Plasma treatment and layer-by-layer assembly techniques enable wash-stable functionality in hospitality linens, opening hotel chain procurement channels.
- US IRA clean manufacturing incentives:Bio-based finishing chemistry qualifies for domestic production credits, offsetting capital costs for greenfield antimicrobial textile facilities.
Industry Challenges
- ISO 20743 testing capacity:Third-party microbiological validation against Staphylococcus aureus and Klebsiella pneumoniae faces 12-18 month queue times, delaying product launches.
- Biocidal product registration:EPA FIFRA and EU BPR parallel submission requirements demand specialized regulatory affairs talent scarce in traditional textile firms.
- Legacy dyehouse integration:Antimicrobial finishing lines require stainless steel equipment incompatible with existing cotton processing infrastructure, forcing greenfield capex decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Textiles Market |
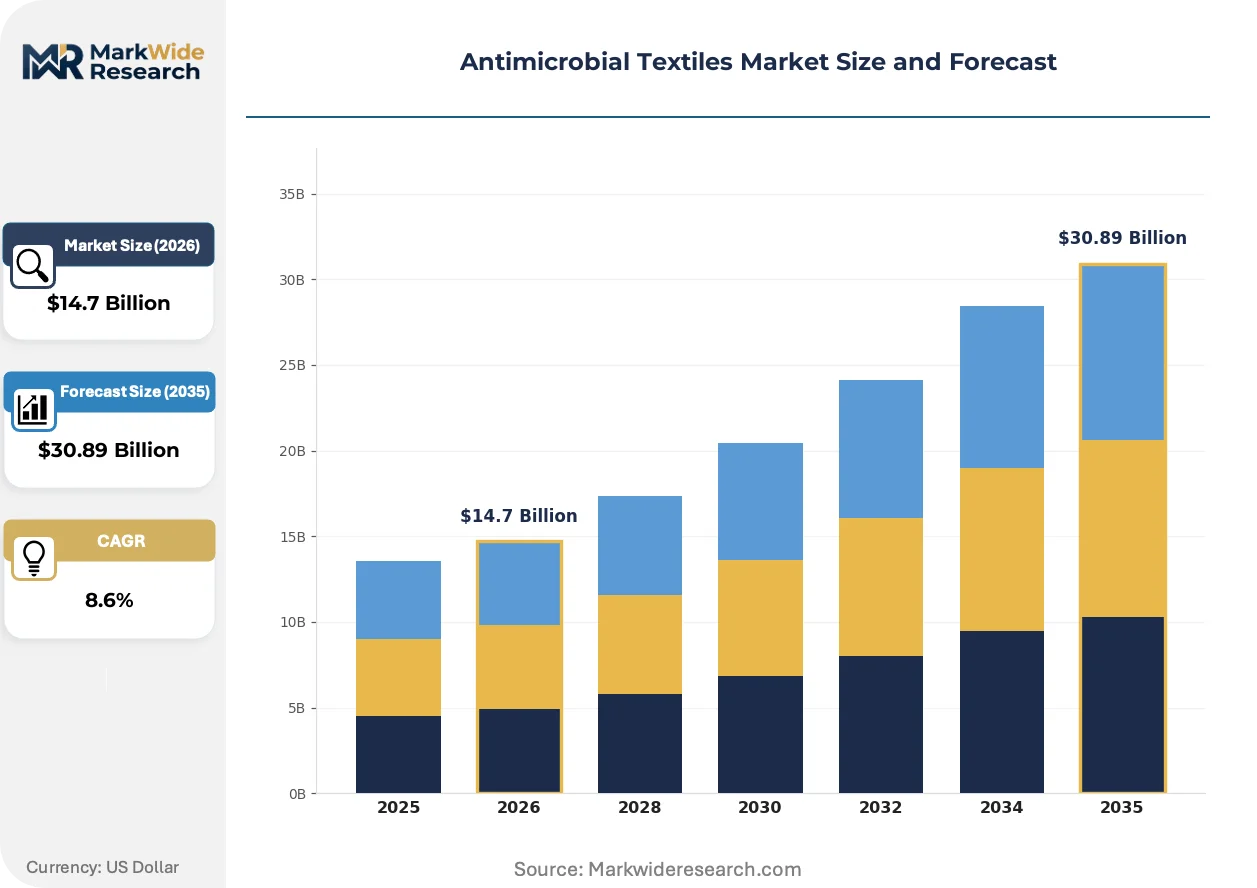
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Home Textiles, Healthcare Textiles, Technical Textiles Material: Cotton, Polyester, Nylon, Silver-infused Fabrics End User: Fashion Industry, Medical Sector, Sports, Hospitality Technology: Bio-based, Chemical, Nano-coating, Organic Treatments |
| Companies Covered | HeiQ Materials AG, DuPont de Nemours Inc., Milliken & Company, Trevira GmbH, PurThread Technologies, Microban International, BASF SE, Polygiene Group AB, Sanitized AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Textiles Market Emerging Trajectories
Biocidal chemistry is migrating from surface coatings to fiber-core integration, eliminating durability trade-offs between antimicrobial efficacy and fabric hand feel. This shift reconfigures supplier relationships and capital allocation across finishing operations.
Chitosan derivatives derived from crustacean processing waste are integrating into cellulosic fiber spinning processes, creating inherent antimicrobial properties without secondary treatment stages. Athletic wear manufacturers in Japan and South Korea are adopting these fibers for odor-control base layers, compressing lead times by removing post-weave finishing steps. The technology is integrating upstream into raw material supply, displacing conventional chemical supplier relationships.
REACH restrictions on silver nanoparticles are compelling reformulation toward quaternary ammonium compound and bio-based peptide alternatives, with ECHA substance evaluation timelines creating 24-36 month regulatory uncertainty windows. European medical textile suppliers are stockpiling grandfathered silver-ion formulations while accelerating alternative chemistry R&D. German and Swiss finishing houses face the steepest compliance cost curves given their concentration of EU MDR Class I device production.
Hospital procurement departments are consolidating vendor panels around certified antimicrobial performance, replacing commodity textile sourcing with outcome-based linen service contracts. Third-party rental and processing companies are capturing decision-making authority from hospital materials management, concentrating purchasing power in North American and Western European healthcare networks. This channel shift favors suppliers with vertically integrated finishing and logistics capabilities over pure manufacturing plays.
Antimicrobial Textiles Market Segmentation
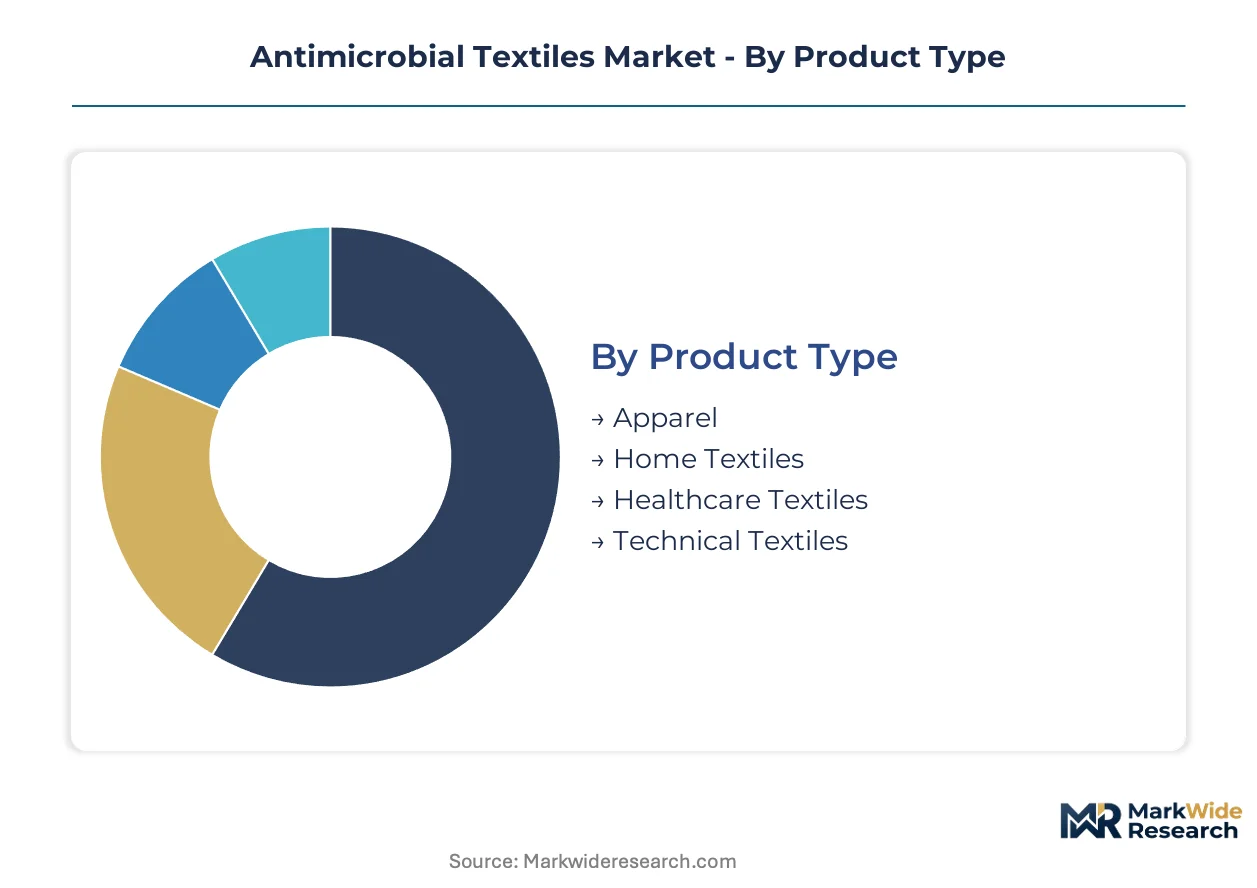
Antimicrobial textile procurement diverges sharply across end-use contexts, with hospital infection control protocols demanding certified biocompatibility while athletic wear prioritizes odor-neutralizing durability. Segmentation reveals how biocidal chemistry, fiber substrate, and finishing technology interact to determine commercial viability in distinct application environments.
Product Type:
Replacement cycles vary dramatically across textile categories, with hospital linens requiring quarterly refresh schedules versus multi-year durability expectations in technical industrial applications.
- Healthcare Textiles:Surgical scrubs, privacy curtains, and patient linens treated with silver-ion or quaternary ammonium formulations must achieve ISO 20743 reduction thresholds against Staphylococcus aureus. German hospital networks are consolidating vendor panels around certified suppliers capable of EU MDR Class I device documentation.
- Technical Textiles:Automotive seating, industrial filtration media, and agricultural covers integrate antimicrobial functionality during fiber extrusion rather than post-weave finishing. Stuttgart manufacturing clusters embed these capabilities into supply chains serving BMW and Mercedes-Benz interior programs.
- Apparel:Base layers and outerwear rely on surface treatments for odor control in athletic and everyday applications.
- Home Textiles:Bedding and bath products target hygiene-conscious consumers through retail channels with shorter performance validation requirements.
Volume placements concentrate in Healthcare Textiles; the faster expansion belongs to Technical Textiles.
Material:
Substrate selection determines finishing chemistry compatibility and end-use performance envelopes across antimicrobial textile portfolios.
- Cotton:Natural fiber absorbency enables diverse biocidal treatments from metal-ion impregnation to chitosan derivatization, though agricultural price volatility squeezes margin. Indian spinning mills dominate raw material supply for hospital linen programs.
- Silver-infused Fabrics:Synthetic fiber core integration of silver ions delivers durable antimicrobial efficacy through 100+ wash cycles without surface coating degradation. REACH restrictions on nanoparticle formulations are forcing reformulation toward ionic silver alternatives in EU-facing production.
- Polyester:Hydrophobic properties limit bacterial adhesion in moisture-wicking athletic applications.
- Nylon:High tenacity supports surgical mesh and implantable textile structures requiring biocompatibility certification.
Production scale favors Cotton; the steepest technology investment is flowing into Silver-infused Fabrics.
End User:
Procurement authority structures fragment antimicrobial textile demand across divergent buying centers with distinct performance validation requirements.
- Medical Sector:Hospital materials management and third-party linen services demand documented efficacy against Klebsiella pneumoniae alongside EPA FIFRA or EU BPR biocidal product registration. US health systems are shifting toward outcome-based rental contracts that transfer laundering liability to specialized service providers.
- Hospitality:Hotel chains specify wash-stable nano-coating treatments for bedding and towel programs, with procurement concentrated in North American and Western European flag properties. Plasma treatment durability is opening procurement channels previously closed to antimicrobial claims due to performance degradation concerns.
- Fashion Industry:Premium positioning drives limited antimicrobial feature integration in luxury and performance lifestyle segments.
- Sports:Athletic brands specify odor-control functionality for high-sweat base layer applications with shorter product lifecycles.
Contract value concentrates in the Medical Sector; Hospitality is gaining share fastest as hotel chains standardize hygiene protocols.
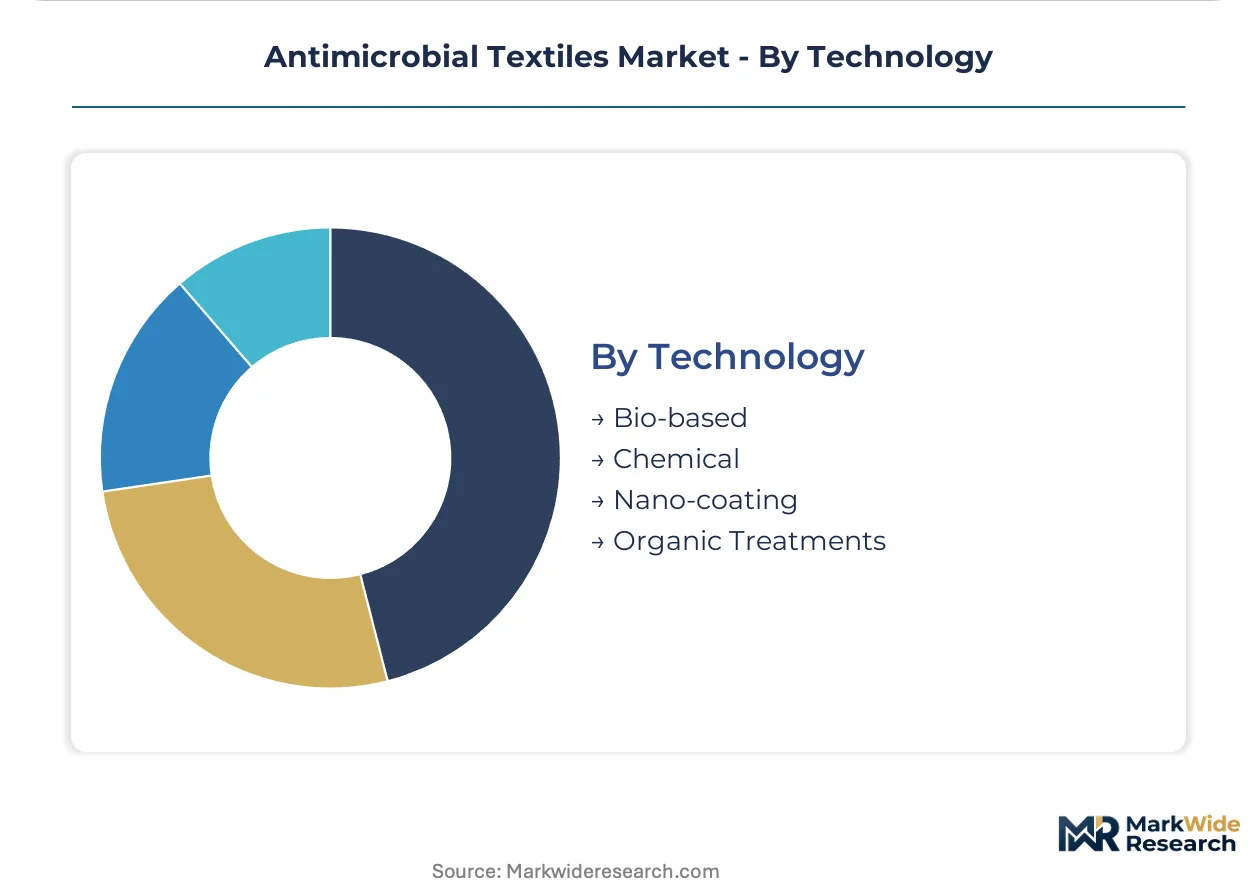
Technology:
Finishing chemistry selection determines regulatory compliance pathways and durability performance in target applications.
- Nano-coating:Layer-by-layer assembly and plasma treatment techniques enable sub-micron biocidal deposition without altering fabric hand feel or breathability. Japanese textile machinery suppliers are commercializing roll-to-roll plasma systems for hospitality linen processors seeking differentiated service offerings.
- Bio-based:Chitosan derivatives from crustacean processing waste integrate into cellulosic fiber spinning, creating inherent antimicrobial properties without secondary treatment. South Korean fiber producers are scaling these capabilities for athletic wear odor control applications.
- Chemical:Conventional silver-ion and quaternary ammonium surface treatments face reformulation pressure from REACH and EPA regulatory action.
- Organic Treatments:Plant-derived biocidal compounds target eco-conscious consumer segments with limited durability validation.
Installed capacity concentrates in Chemical treatments; Bio-based approaches are climbing the fastest as regulatory pressure accelerates alternative chemistry R&D.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while consumption growth accelerates across India and South Korea. European regulatory pressure is reshaping supplier geography.
United States
Hospital infection control mandates drive procurement of certified antimicrobial linens and surgical textiles. EPA FIFRA registration requirements filter supplier access to institutional buyers. South Carolina hosts Milliken & Company's manufacturing complex, anchoring North American finishing capacity.
Germany
EU MDR Class I device classification for hospital textiles locks suppliers into CE marking obligations. ECHA REACH evaluations on silver nanoparticles force reformulation toward bio-based alternatives. Stuttgart and Chemnitz technical textile clusters embed antimicrobial finishing into automotive supply chains serving BMW and Mercedes-Benz.
India
Hospital infrastructure expansion creates demand for imported antimicrobial textiles as domestic CDSCO registration pathways mature. Cotton spinning mills in Gujarat and Maharashtra supply raw material for hospital linen programs. Tamil Nadu's textile belt is attracting finishing technology partnerships from European suppliers seeking tariff-advantaged production.
South Korea
Athletic wear manufacturers specify odor-control fibers for export markets. MFDS medical device regulations create compliance benchmarks for healthcare textile imports. Seoul-based fiber producers are scaling chitosan-derivative spinning for base layer applications.
Switzerland
Swissmedic biocompatibility standards influence premium medical textile specifications across adjacent EU markets. HeiQ Materials AG leverages Basel-region R&D infrastructure for bio-based finishing chemistry development. The country's precision chemical sector supplies quaternary ammonium compound formulations to German finishing houses.
Antimicrobial Textiles Market Vendor Landscape
Top-tier vendors anchor European and North American finishing chemistry, while mid-scale fabricators compete on regional hospital supply contracts. The market exhibits tiered concentration around specialized biocidal formulation and integrated textile manufacturing. Three archetypes dominate: polymer science conglomerates extending into masterbatch chemistry, dedicated finishing technology licensors, and vertically integrated textile producers with captive treatment lines. Competitive moves center on regulatory compliance capacity building and geographic expansion into underpenetrated hospital procurement markets.
Within the Swiss-German precision chemistry tier, HeiQ Materials AG and Sanitized AG exemplify technology-led positioning built on regulatory navigation expertise. BASF SE represents polymer science conglomerates leveraging materials science breadth into antimicrobial masterbatch formulations. Among North American integrated manufacturers, Milliken & Company occupies a scale-driven position spanning finishing chemistry through end-product supply. DuPont de Nemours Inc. anchors the industrial materials archetype with fiber substrate integration capabilities. These five entities collectively represent the competitive spectrum from specialized biocidal R&D through commodity textile manufacturing.
| Leading Market Players |
|---|
| HeiQ Materials AG |
| DuPont de Nemours Inc. |
| Milliken & Company |
| Trevira GmbH |
| PurThread Technologies |
| Microban International |
| BASF SE |
| Polygiene Group AB |
| Sanitized AG |
| Others |
Supply Flow & Price Mechanics
Cotton futures volatility on the Intercontinental Exchange cascades through antimicrobial textile supply chains, compressing margins at spinning mills while concentrating pricing power among German and Swiss finishing houses with captive silver-ion chemistry.
Pricing Analysis
Cost-down pressure on hospital linen tiers accelerates because REACH-mandated silver nanoparticle reformulation forces R&D recapture. Pricing stratifies across premium, standard, and economy tiers based on ISO 20743 certification grade and EU MDR Class I device documentation. Mid-market suppliers face the steepest margin compression. Academic medical centers exhibit lowest price sensitivity due to outcome-based contracting requirements.
Supply Chain Analysis
Silver nitrate supply rests on Mexican and Peruvian mining output coupled with German refining capacity. Chitosan feedstock draws from Vietnamese and Indonesian crustacean processing waste streams. Single-source vulnerability concentrates in Japanese plasma treatment equipment. Distribution runs through third-party linen service operators consolidating hospital procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 20743 testing capacity constraints prop pricing power for validated suppliers, creating supply-constrained conditions favoring incumbents with certified throughput.
For Market Incumbents: Anchor market position by securing stainless steel finishing line capacity in South Carolina and Chemnitz clusters. Accelerate bio-based peptide R&D to preempt REACH silver-ion restrictions. Defend against chitosan-fiber entrants by locking multi-year hospital rental contracts. For New Entrants and Emerging Players: Enter via CDSCO registration arbitrage in Indian hospital infrastructure expansion. Target hospitality nano-coating segments where plasma treatment durability opens procurement channels previously closed to antimicrobial claims. Lead with wash-stability performance guarantees. For Investors and Strategic Acquirers: The window for entry favors specialized biocidal formulation licensors with EU BPR dossier expertise. Long-term viability hinges on regulatory navigation capability rather than manufacturing scale. Watch ECHA substance evaluation timelines as inflection triggers for silver-ion replacement chemistry adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class I Device Certification | CE marking unlocks long-term clinical evaluation contracts with German hospital networks. |
| Backward Integration into Silver-ion Masterbatch | Polymer science capabilities secure durable biocidal functionality for surgical garment applications. |
| Bio-based Peptide Formulation Partnership | Alternative chemistry R&D hedges REACH silver nanoparticle restriction exposure. |
| Plasma Treatment Equipment Deployment | Japanese roll-to-roll systems differentiate hospitality linen service offerings. |
| CDSCO Registration Pathway Development | First-mover compliance captures Indian hospital infrastructure expansion demand. |
Methodological Framework
Independent corroboration across textile finishing plant managers, hospital procurement committee members, and regulatory affairs specialists at biocidal suppliers underwrites the qualitative findings. Secondary validation draws from ECHA substance evaluation databases, EPA FIFRA registration filings, EU MDR notified body documentation, and hospital GPO contract repositories. Bottom-up fiber demand modeling and top-down healthcare expenditure allocation triangulate market sizing.
Rate-of-change decomposition isolates volume drivers across material substrate, finishing technology, and end-use segment dimensions throughout the forecast period. CAGRs derive from wash-cycle durability assumptions, hospital replacement schedules, and regulatory compliance cost curves. Silver-ion price trajectories and chitosan feedstock availability inform chemistry-specific penetration modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH restriction timelines or cotton supply disruption scenarios. A small set of named triggers warrants ongoing watch: ECHA evaluation conclusions, CDSCO registration pathway maturation, and plasma treatment equipment lead times.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market