
 Examination Gloves Market | 2026-2036
Examination Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Examination Gloves Market Foresight
Automated dipping lines with real-time thickness monitoring is rewriting manufacturing economics for examination gloves. Hartalega Holdings Berhad leverages this technology to sustain its cost leadership in nitrile production. Top Glove Corporation Bhd anchors the global supply base through unmatched production scale across Malaysia. Kossan Rubber Industries Bhd differentiates via specialized formulations for chemical resistance segments.
Examination gloves are disposable protective barriers manufactured from natural rubber latex or synthetic polymers such as nitrile, vinyl, or neoprene, typically ranging from 3 to 8 mils in thickness and designed to prevent cross-contamination between healthcare workers and patients during physical contact. Nitrile formulations now dominate hospital procurement due to latex allergy prevalence and superior puncture resistance, while vinyl retains share in low-risk food handling where cost sensitivity outweighs performance demands. Powder-free products command premium positioning across dental and diagnostic settings where particulate contamination risks are elevated.
The FDA enforces Quality System Regulation and biocompatibility standards under 21 CFR Part 820 for all medical examination gloves sold in the United States, while the EU Medical Device Regulation mandates CE marking and clinical evaluation documentation for European market access. Malaysia's Ministry of Health licensing requirements and the International Organization for Standardization's ISO 11193 specifications collectively shape export eligibility and batch-level quality accountability. Stakeholders must monitor regulatory divergence between synthetic material approvals and evolving single-use plastic restrictions that could force formulation pivots.
Market Dynamics
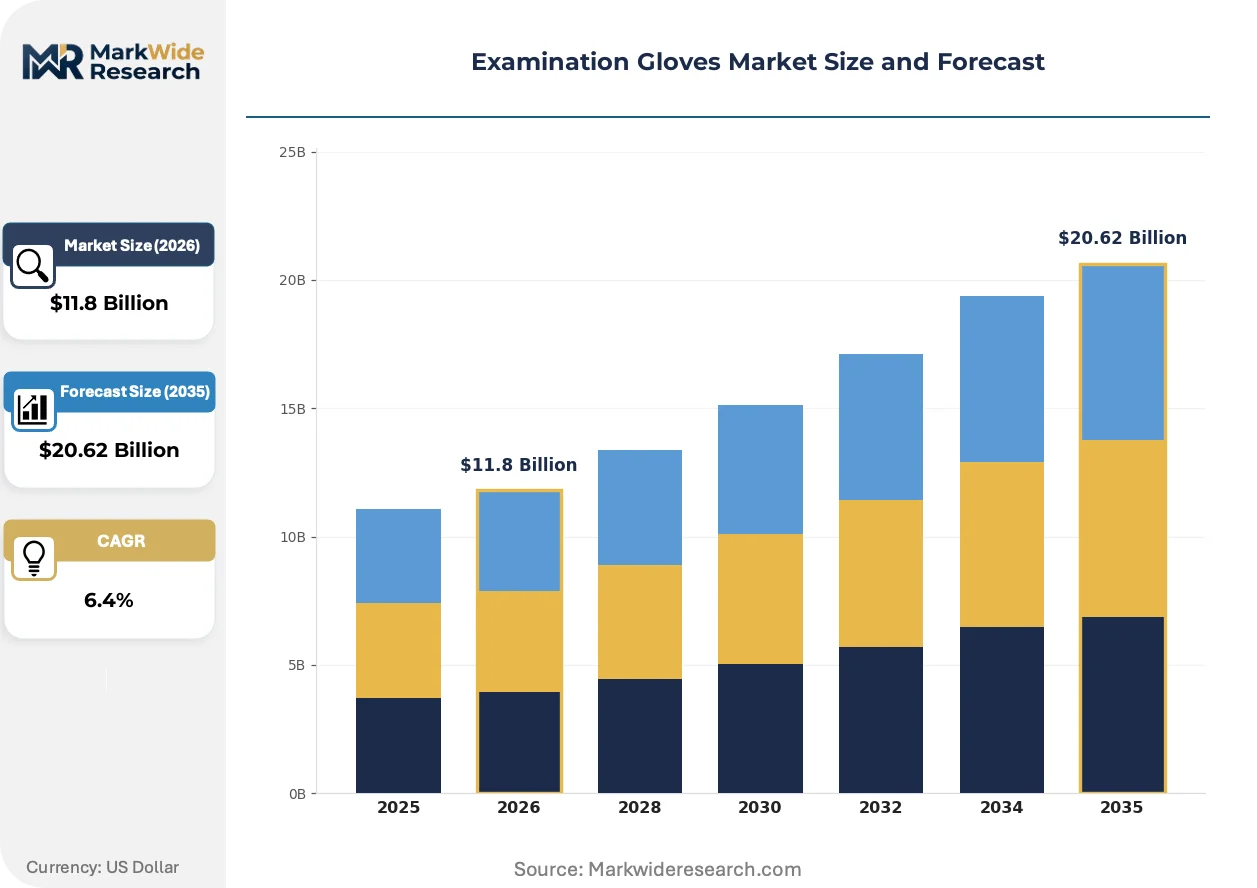
Automated dipping lines with real-time thickness monitoring are collapsing traditional cost structures in nitrile glove manufacturing, concentrating production advantage among Malaysian operators with capital deployment capability.
Growth Catalysts
- EU Medical Device Regulation compliance mandates:CE marking requirements and clinical evaluation documentation are accelerating hospital procurement of certified synthetic alternatives across European diagnostic networks.
- Diagnostic laboratory expansion:Stricter infection control protocols in pathology and clinical testing facilities are multiplying glove consumption per procedure.
- Malaysian production infrastructure:Established rubber industry ecosystems and nitrile formulation expertise continue attracting capacity investments.
Market Restraints
- Butadiene price volatility:Nitrile polymer feedstock costs fluctuate with crude oil derivatives, compressing margin stability for non-integrated manufacturers.
- Single-use plastic restrictions:France's AGEC law and similar national frameworks in Germany and Italy threaten vinyl glove viability in food service applications.
- Latex allergy liability exposure:Natural rubber protein sensitization risks limit hospital procurement flexibility despite cost advantages.
Strategic Opportunities
- Indian healthcare infrastructure buildout:CDSCO medical device registration pathways and government hospital procurement expansion create entry corridors for ISO 11193-certified suppliers.
- Chemical resistance specialization:Oncology compounding and industrial solvent handling applications reward differentiated neoprene and nitrile formulations.
- Direct-to-clinic distribution platforms:E-procurement portals are disintermediating traditional medical supply distributors in dental and veterinary segments.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 12-18 month validation cycles, delaying new formulation launches.
- Cleanroom retrofit requirements:FDA Quality System Regulation compliance demands capital-intensive facility upgrades for powder-free production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Examination Gloves Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Nitrile, Latex, Vinyl, Neoprene, Polyethylene Product Type: Powder-Free, Powdered, Textured, Smooth, Flavored End User: Dental Clinics, Diagnostic Labs, Pharmacies, Veterinary Clinics Application: Medical Examinations, Laboratory Testing, Food Handling, Janitorial Services, Automotive Maintenance |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Kossan Rubber Industries Bhd, Ansell Ltd, Supermax Corporation Berhad, Sri Trang Gloves PLC, Medline Industries, Cardinal Health, INTCO Medical Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Examination Gloves Market Shifts & Advancements
Material science advances and regulatory stringency are compressing product lifecycles while elevating performance thresholds across examination glove categories.
Chlorinated surface treatment technology is collapsing the tactile disadvantage that historically separated nitrile from natural rubber latex in surgical-adjacent applications. Cardiac catheterization labs and interventional radiology suites in US academic medical centers are adopting chlorinated nitrile as their default barrier standard. This shift is collapsing the premium pricing tier that latex once commanded in high-sensitivity procedural settings.
REACH Annex XVII restrictions on N-nitrosamines and powder additives are forcing reformulation investments across European export portfolios. Manufacturers serving German and French markets must now validate accelerator-free curing systems and demonstrate compliance with migration limits. The regulatory pressure is most acute in pediatric and neonatal care segments where dermal exposure sensitivity peaks.
Consolidated purchasing organizations are compressing supplier rosters and demanding lot-level traceability via blockchain-enabled verification. US group purchasing organizations and NHS Supply Chain in the United Kingdom now require digital certificates of analysis with each delivery. This behavioral shift is most visible in tertiary hospital networks where compliance documentation burdens have eliminated smaller, non-integrated vendors from consideration sets.
Examination Gloves Market Segmentation
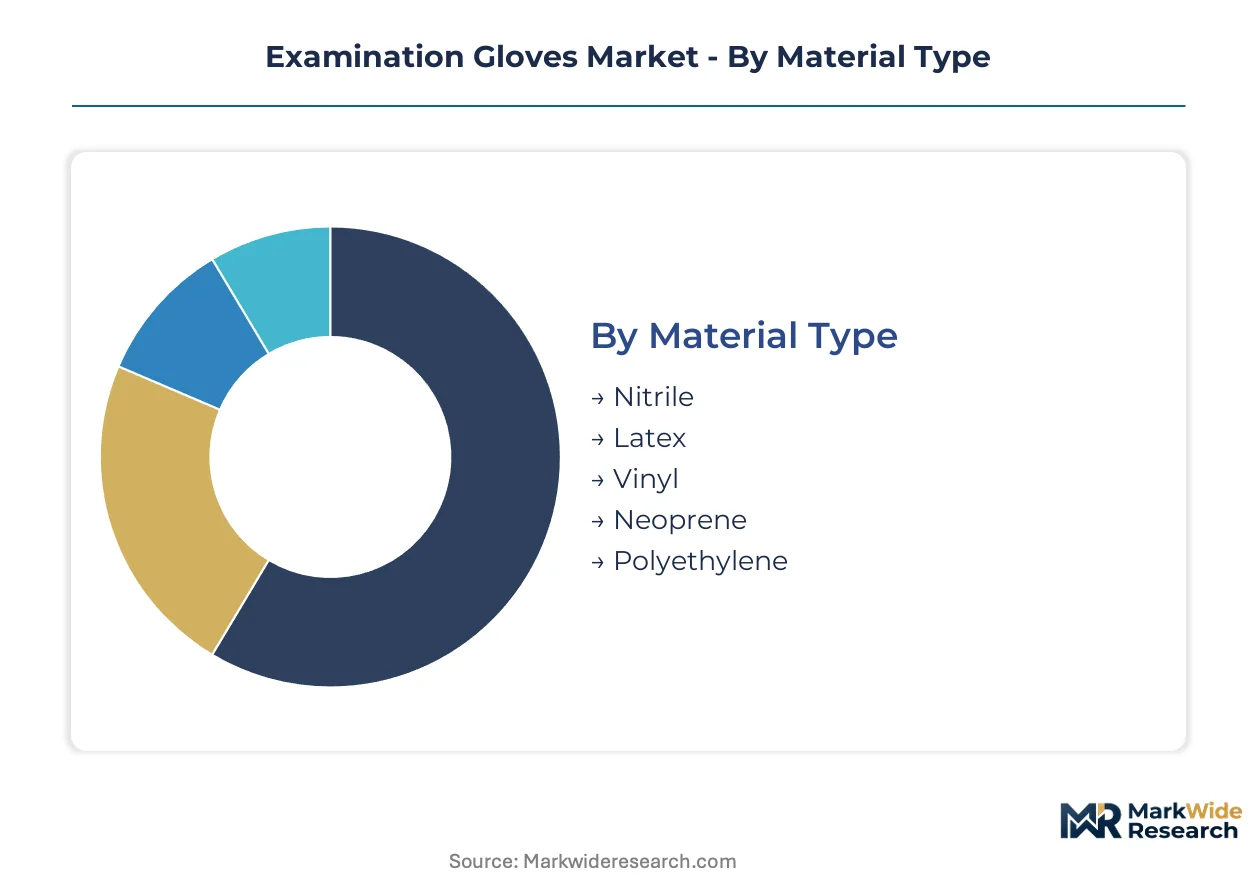
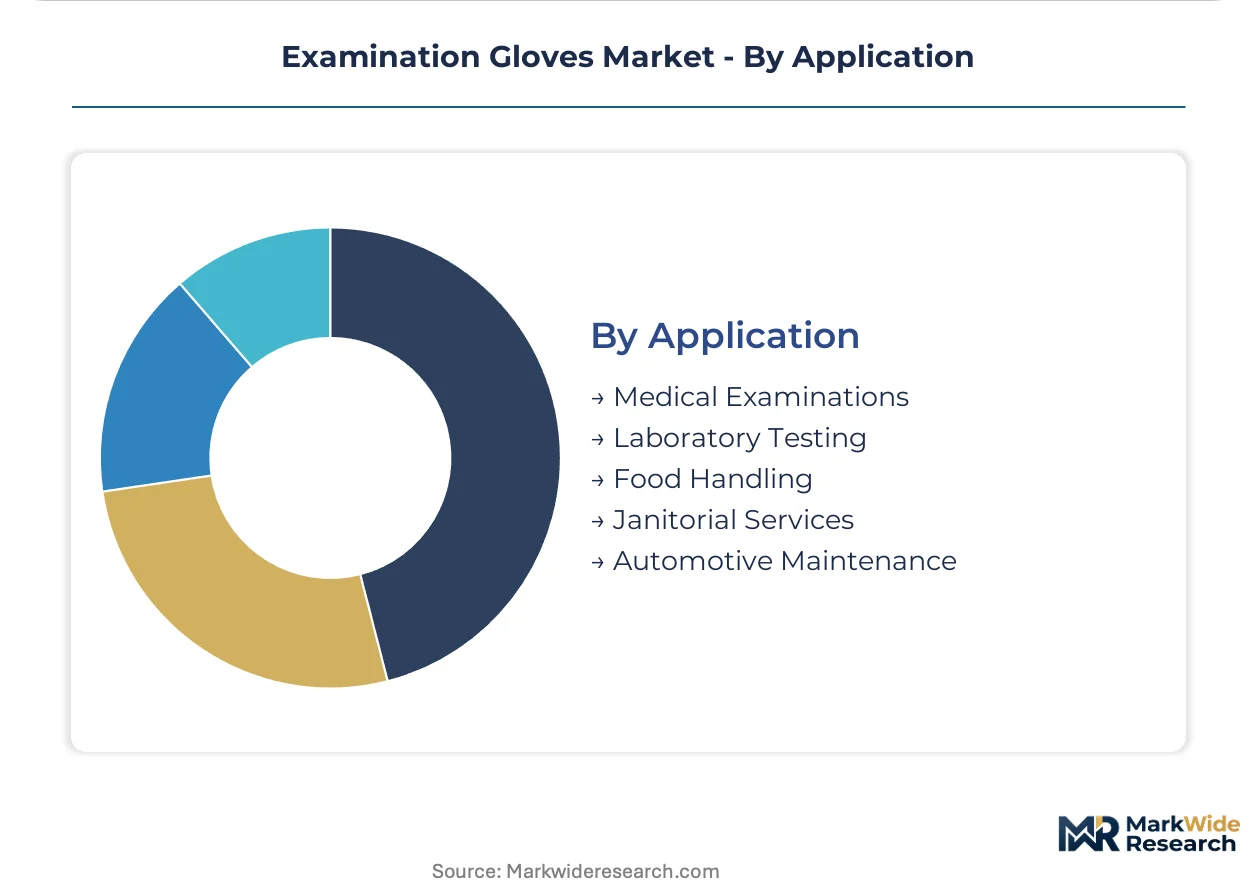
Examination glove procurement decisions split across material chemistry, surface treatment, and end-use risk profiles. Manufacturers align formulation investments with the specific barrier performance and regulatory compliance each segment demands.
Material Type:
Cost tier and allergy risk profile determine material selection across hospital and industrial procurement channels.
- Nitrile:Synthetic acrylonitrile-butadiene copolymer delivers puncture resistance three times that of latex. Demand concentrates in US emergency departments and oncology units where latex allergy protocols and chemotherapy drug permeation standards apply. Malaysian production clusters supply the bulk of hospital-grade nitrile through integrated nitrile butadiene rubber supply chains.
- Latex:Natural rubber harvested from Hevea brasiliensis plantations provides unmatched tactile sensitivity and elasticity. European hospital networks retain limited latex procurement for surgical-adjacent procedures where fine motor control outweighs allergy liability concerns. Protein content labeling requirements under EU MDR constrain supplier eligibility.
- Vinyl:Polyvinyl chloride formulations serve cost-sensitive food service and janitorial applications where puncture risk remains minimal. France's AGEC law and similar single-use plastic restrictions in Germany threaten long-term viability despite low unit economics.
- Neoprene:Polychloroprene construction resists degradation from oils, solvents, and oxidizing agents. Industrial maintenance and automotive chemical handling operations specify neoprene where nitrile permeation limits are exceeded.
- Polyethylene:Cast or blown film construction offers the lowest cost barrier for food preparation and patient transport scenarios with minimal contamination risk. Loose fit and limited durability restrict penetration beyond entry-level food handling.
Nitrile commands the established base. The steepest expansion runs through neoprene as industrial chemical resistance requirements tighten.
Product Type:
Surface treatment and donning technology differentiate performance tiers within each material category.
- Powder-Free:Chlorinated or polymer-coated interiors enable dry donning without cornstarch particulate contamination. US dental clinics and interventional radiology suites mandate powder-free specifications to prevent adhesive interference and post-operative complications. FDA biocompatibility testing under ISO 10993 validates cytotoxicity compliance.
- Powdered:Cornstarch or calcium carbonate lubrication accelerates glove donning in high-throughput emergency settings. Remaining demand concentrates in developing-market hospitals where cost constraints override particulate contamination protocols. Regulatory phase-outs in Europe and North America constrain growth trajectories.
- Textured:Raised surface patterns on fingertips and palms enhance instrument grip in wet conditions. Surgical and dental applications specify textured nitrile where blood and irrigation fluid exposure is routine.
- Smooth:Untextured surfaces minimize friction for delicate tissue handling and precision assembly work. Microelectronics and pharmaceutical compounding operations prioritize smooth finishes to prevent particulate shedding.
- Flavored:Mint, fruit, or bubblegum scenting reduces latex odor aversion in pediatric dental examinations. Child-focused dental practices in North America and Western Europe specify flavored vinyl or nitrile to improve patient compliance.
Powder-Free dominates procurement specifications across regulated healthcare environments. Textured variants gain share fastest as surgical-adjacent applications expand.
End User:
Customer type dictates volume scale, certification requirements, and distribution channel configuration.
- Dental Clinics:High-frequency glove changes during patient examinations drive per-procedure consumption rates. US dental group purchasing organizations consolidate procurement across multi-site practices, favoring suppliers with lot-level traceability systems.
- Diagnostic Labs:Pathology and clinical testing facilities multiply glove usage per sample handling step. Stricter infection control protocols in PCR and biosafety level-2 environments accelerate synthetic glove adoption.
- Pharmacies:Compounding and vaccine administration require intermittent barrier protection with extended wear comfort. Independent pharmacy chains prioritize cost-efficient vinyl or blended nitrile for low-risk medication handling.
- Veterinary Clinics:Animal bite resistance and zoonotic pathogen protection shape material selection. Large-animal practices specify thicker nitrile formulations compared to small-animal companion care settings.
Diagnostic Labs anchor volume demand through institutional procurement contracts. Dental Clinics represent the fastest-climbing segment as cosmetic and preventive service volumes expand.
Application:
Exposure risk severity and regulatory jurisdiction define performance thresholds across use cases.
- Medical Examinations:Patient contact protocols in hospitals and primary care settings mandate FDA-cleared or CE-marked barriers. Bloodborne pathogen standards under OSHA drive consistent nitrile specification.
- Laboratory Testing:Chemical splash protection and biological containment requirements vary by biosafety level. Research universities and commercial diagnostics operators maintain differentiated glove inventories by hazard class.
- Food Handling:FDA food contact substance regulations and HACCP compliance shape vinyl and polyethylene selection. Quick-service restaurant chains optimize cost per unit over durability metrics.
- Janitorial Services:Cleaning chemical compatibility and abrasion resistance determine nitrile or neoprene specification. Commercial building maintenance contractors prioritize bulk pricing over performance differentiation.
- Automotive Maintenance:Motor oil, brake fluid, and solvent exposure requires chemical resistance validation. Independent repair shops and dealership service centers specify industrial-grade nitrile or neoprene based on task-specific permeation data.
Medical Examinations retain the revenue base. Laboratory Testing expands most quickly as molecular diagnostics and biopharma research activity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export surpluses from Malaysian producers dominate international trade flows, while import dependency shapes procurement strategies in deficit markets. The United States absorbs substantial nitrile volumes through hospital group purchasing organizations. European regulatory tightening accelerates supplier qualification timelines across the continent.
United States
Emergency department throughput and oncology compounding protocols drive synthetic glove consumption. FDA Quality System Regulation enforcement under 21 CFR Part 820 mandates biocompatibility documentation for all medical-grade imports. The Texas Medical Center cluster in Houston anchors procurement volume for the south-central region through consolidated health system contracts.
Germany
REACH Annex XVII restrictions on N-nitrosamines and accelerator chemicals reshape formulation requirements for hospital networks. The EU Medical Device Regulation mandates clinical evaluation documentation and CE marking for all European market entry. The Rhine-Ruhr industrial corridor hosts specialized distributors serving Benelux and Scandinavian re-export channels.
Malaysia
Integrated nitrile butadiene rubber supply chains and established dipping infrastructure sustain cost-competitive export capacity. The Ministry of Health licensing framework governs export eligibility and batch-level quality accountability. The Klang Valley production cluster around Kuala Lumpur and Shah Alam concentrates automated manufacturing lines with real-time thickness monitoring systems.
India
Government hospital procurement expansion and CDSCO medical device registration pathways create entry corridors for ISO 11193-certified suppliers. The FSSAI and central drug regulator enforce parallel compliance tracks for food-contact and medical-grade categories. The Tamil Nadu industrial belt around Chennai attracts capacity investments targeting domestic diagnostic laboratory networks.
Japan
Aging demographics and infection control protocol standardization elevate per-capita consumption in primary care settings. PMDA and METI coordinate on polymer biocompatibility standards under harmonized ICH frameworks. The Osaka-Kobe manufacturing zone maintains specialized compounding operations for high-sensitivity chlorinated nitrile formulations.
Examination Gloves Market Competitive Landscape
On the supply side, the industry is consolidating around Malaysian operators with integrated polymer supply and automated production infrastructure. Three strategic archetypes dominate: scale-driven volume exporters with multi-billion unit capacity, specialized formulators serving chemical resistance segments, and regional distributors with direct-to-clinic e-procurement platforms. Competitive dynamics center on backward integration into nitrile butadiene rubber production and cleanroom facility retrofitting for powder-free compliance.
Among Malaysia-based producers, Top Glove Corporation Bhd, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd exemplify the integrated manufacturing archetype that has captured dominant export share. These entities anchor the global supply base through established production ecosystems in the Klang Valley. Ansell Ltd and Cardinal Health represent the diversified health conglomerate model with procurement leverage across multiple barrier protection categories.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Bhd |
| Ansell Ltd |
| Supermax Corporation Berhad |
| Sri Trang Gloves PLC |
| Medline Industries |
| Cardinal Health |
| INTCO Medical Technology Co., Ltd. |
| Others |
Supply & Pricing Matrix
The Port Klang-Pasir Gudang container corridor governs landed costs for Malaysian nitrile exports, concentrating pricing power among integrated producers while forcing non-integrated competitors into cost-pass-through vulnerability against hospital group purchasing organizations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates ISO 11193-certified hospital-grade nitrile from food-service vinyl and janitorial polyethylene tiers. Cost compression in the economy segment is intensifying because butadiene feedstock volatility squeezes non-integrated manufacturers. Quick-service restaurant chains exhibit the highest price sensitivity, while oncology compounding units prioritize chemical resistance certification over unit economics.
Supply Chain Analysis
Export licensing restrictions under Malaysia's Ministry of Health framework constrain batch-level traceability documentation for uncertified producers. Manufacturing gravity centers on Malaysia, Thailand, and Vietnam through established rubber industry ecosystems and nitrile butadiene rubber supply chains. Raw material flows draw from petrochemical butadiene, acrylonitrile monomer, and chlorination chemical inputs. Single-source vulnerability concentrates in Malaysian nitrile butadiene rubber production. Distribution runs through hospital group purchasing organizations, medical supply distributors, and emerging direct-to-clinic e-procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled lot verification is collapsing information asymmetries between manufacturers and procurement committees, transforming examination gloves into a platform-governed category where certification interoperability determines supplier survival.
For Market Incumbents: Insulate margin structures through backward integration into nitrile butadiene rubber production and captive chlorination chemical supply. Accelerate cleanroom retrofit investments to preempt FDA Quality System Regulation enforcement waves. Defend against non-integrated Vietnamese entrants by locking multi-year offtake contracts with US hospital systems. For New Entrants and Emerging Players: India's Tamil Nadu diagnostic laboratory corridor offers the most penetrable white-space for ISO 11193-certified suppliers. Target government hospital procurement expansion through CDSCO registration pathways. Enter via specialized neoprene formulations for industrial chemical resistance segments where Malaysian giants maintain thinner coverage. For Investors and Strategic Acquirers: EU Medical Device Regulation enforcement reshapes the acquisition landscape toward CE-marked, accelerator-free formulation capabilities. Long-term viability favors targets with demonstrated REACH Annex XVII compliance and pediatric segment positioning. Watch for FDA warning letter activity as an inflection indicator for incumbent vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Formulation Development | REACH Annex XVII compliance secures German and French hospital network access. |
| Backward Integration into NBR Production | Captive butadiene supply shields margins from petrochemical price swings. |
| Blockchain Traceability Implementation | NHS Supply Chain and US GPOs now mandate digital certificates of analysis. |
| Cleanroom Facility Retrofit | FDA 21 CFR Part 820 compliance enables powder-free production for dental and interventional radiology segments. |
| Direct-to-Clinic E-Procurement Platform | Disintermediation captures margin from traditional medical supply distributors in veterinary and dental channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineers, GPO contracts managers, and nitrile formulation chemists. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, Malaysian Ministry of Health export licensing records, and ISO 11193 certification databases. Bottom-up volume modeling triangulated against top-down trade flow analysis from customs declarations.
Calibration anchored segment-level growth trajectories to observed procurement pattern shifts across the analysis window. The modeling framework spanned material type, surface treatment, end-user risk profile, and regional regulatory cluster dimensions. CAGR derivation synthesized historical volume elasticities against projected infection control protocol tightening and diagnostic laboratory expansion rates. Feedstock cost scenarios and single-use plastic restriction timelines fed sensitivity testing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Vietnamese or Indonesian entrants would shift outcomes. Material shifts in EU accelerator chemical bans or FDA biocompatibility testing requirement changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Global Maternity Support Product Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Medical Fabrics Market