
 Global Feminine Hygiene Wash Market | 2026-2036
Global Feminine Hygiene Wash Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feminine Hygiene Wash Market Analysis
Subscription-based replenishment models is broadening the recurring revenue architecture of feminine hygiene wash offerings beyond traditional retail velocity. Procter & Gamble Co. leverages its direct-to-consumer infrastructure to anchor recurring purchase behavior through auto-delivery programs. Unicharm Corporation competes through pharmacy-centric distribution in East Asian markets, while Johnson & Johnson sustains clinical credibility via healthcare professional endorsement channels.
Feminine hygiene wash denotes a topical cleansing formulation engineered to maintain vulvovaginal pH between 3.8 and 4.5, typically incorporating lactic acid, prebiotic substrates, or mild surfactant systems distinct from standard body cleansers. Its commercial purpose centers on symptom management of irritation, odor control, and support of commensal lactobacilli populations without disrupting mucosal barriers. Gels currently occupy the dominant volume position due to dispensing precision and consumer familiarity, while foams represent the fastest-expanding product type as aerosol-free pump systems gain manufacturing scale. Among end users, postpartum and active lifestyle segments command premium pricing power because clinical and athletic contexts respectively validate specialized formulation claims.
FDA cosmetic labeling requirements and EMA borderline product classifications jointly determine whether feminine hygiene washes register as cosmetics or medical devices, directly influencing formulation disclosure obligations and market entry timelines. REACH compliance in Europe and state-level cosmetic safety statutes in California further constrain preservative selection and fragrance compound portfolios. Stakeholders must monitor evolving microbiome-specific health claims regulation, as regulators in multiple jurisdictions weigh whether bacterial culture references trigger pharmaceutical reclassification.
Market Dynamics
pH-balanced formulation science is fragmenting competitive advantage in feminine hygiene wash, as microbiome research capabilities separate clinically credible suppliers from commodity formulators.
Growth Catalysts
- Postpartum Clinical Protocols:Obstetric care guidelines in India and Brazil now incorporate specialized wash regimens, expanding prescription-adjacent distribution through hospital discharge programs.
- EMA Borderline Classification Clarity:Recent guidance documents reduce registration uncertainty for microbiome-supporting claims, accelerating product pipeline advancement for European manufacturers.
- Lactic Acid Fermentation Advances:Biotech-derived pH stabilizers achieve cost parity with synthetic alternatives, enabling mass-market tiering without efficacy compromise.
Market Restraints
- Surfactant Input Volatility:Coconut-derived mild surfactant supply chains concentrate in Southeast Asian processing clusters, exposing margin structures to weather-driven raw material swings.
- FDA Cosmetic-Drug Boundary Enforcement:Investigational scrutiny of vaginal health claims triggers warning letters and reformulation costs for products crossing into unapproved drug territory.
- Standard Body Wash Substitution:pH-unaware consumers in price-sensitive markets default to general cleansers, compressing category penetration velocity in rural pharmacy networks.
Strategic Opportunities
- Subscription Platform Expansion:Direct-to-consumer auto-delivery infrastructure in the United States enables recurring revenue capture and first-party data accumulation for personalized formulation development.
- Active Lifestyle Segment White Space:Athletic-specific variants addressing sweat-induced pH disruption remain underdeveloped relative to postpartum positioning, creating brand differentiation potential.
- India PLI Scheme Alignment:Domestic manufacturing incentives for personal care ingredients reduce import dependency and accelerate regional supply chain localization for multinational entrants.
Industry Challenges
- Microbiome Research Talent Scarcity:Formulation chemistry programs lack vulvovaginal ecology specialization, forcing manufacturers to compete for limited clinical research partnerships.
- Multi-Jurisdiction Claim Harmonization:Divergent FDA, EMA, and CDSCO standards for bacterial culture references complicate global product architecture and label versioning.
- Aerosol-Free Foam System Integration:Pump mechanism reliability at scale requires capital-intensive manufacturing line retrofits for gel-dominant incumbent facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feminine Hygiene Wash Market |
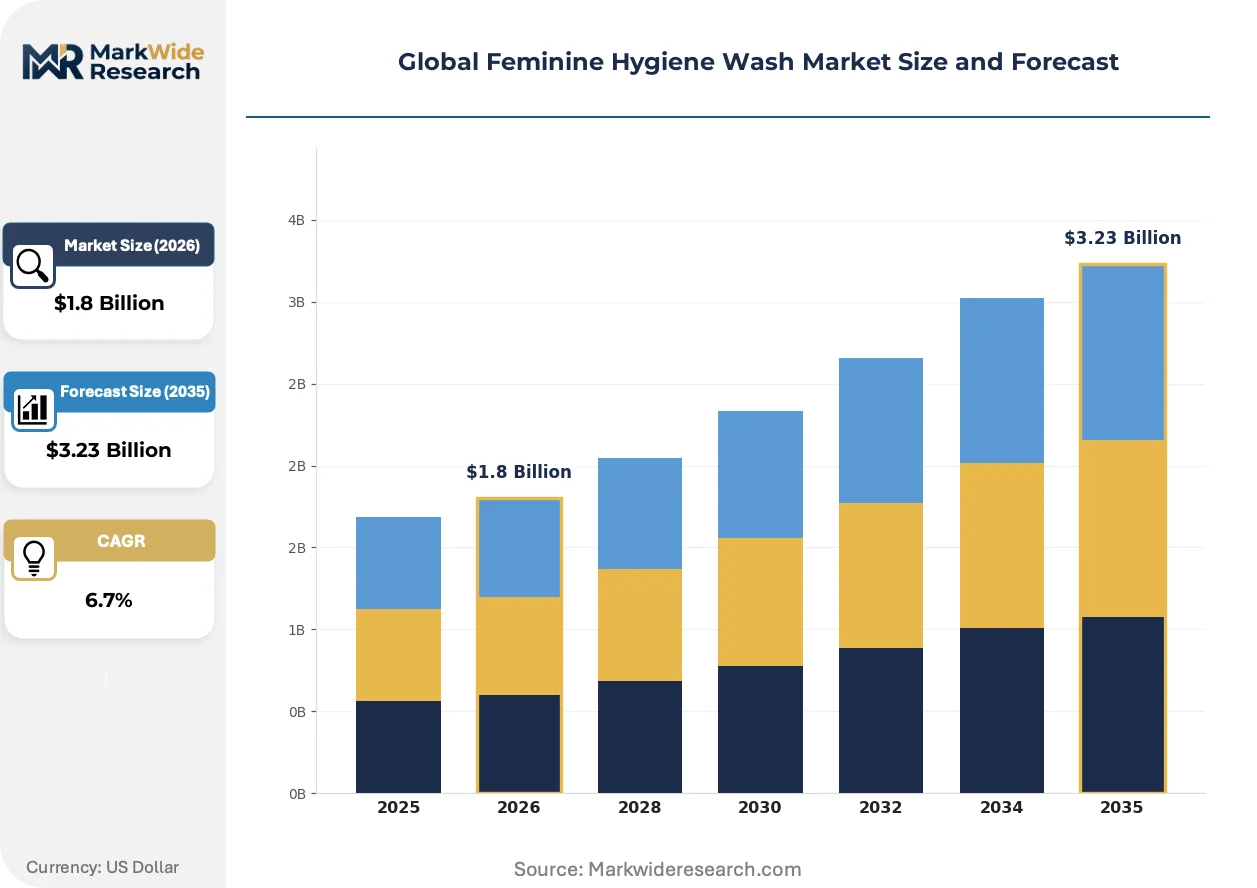
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foams, Gels, Sprays, Wipes End User: Women, Teens, Postpartum, Active Lifestyle Users Packaging Type: Tubes, Bottles, Sachets, Pumps Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores |
| Companies Covered | Procter & Gamble Co., Johnson & Johnson, Kimberly-Clark Corporation, Unilever, Unicharm Corporation, Essity AB, Lactacyd, Summer's Eve, LIFEON Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feminine Hygiene Wash Market Emerging Trajectories
Prebiotic substrate engineering and delivery system miniaturization are compressing development cycles, while regulatory frameworks race to catch up with microbiome-specific efficacy claims.
Biocompatible oligosaccharide complexes are modularizing formulation architecture, allowing pH buffers and commensal bacterial nutrients to be swapped independently based on regional water hardness and user sensitivity profiles. Postpartum and menopausal segments in Germany and Japan adopt these adaptive systems fastest, compressing SKU proliferation costs for multinational portfolios.
REACH Annex XVII updates on fragrance allergen disclosure are forcing reformulation of legacy preservative systems, particularly affecting products targeting sensitive-skin positioning in European pharmacy channels. Manufacturers are responding by accelerating biotech-derived antimicrobial alternatives through toxicological assessment pipelines previously reserved for pharmaceutical excipients.
Direct-to-consumer sampling programs are displacing traditional in-store trial as the primary acquisition mechanism, with digital-native brands in South Korea and the United States leveraging micro-influencer networks to reduce customer acquisition costs. Subscription bundling with menstrual products concentrates highest in urban Indian markets, where pharmacy e-commerce platforms integrate wash replenishment into existing hygiene purchasing cycles.
Global Feminine Hygiene Wash Market Segmentation
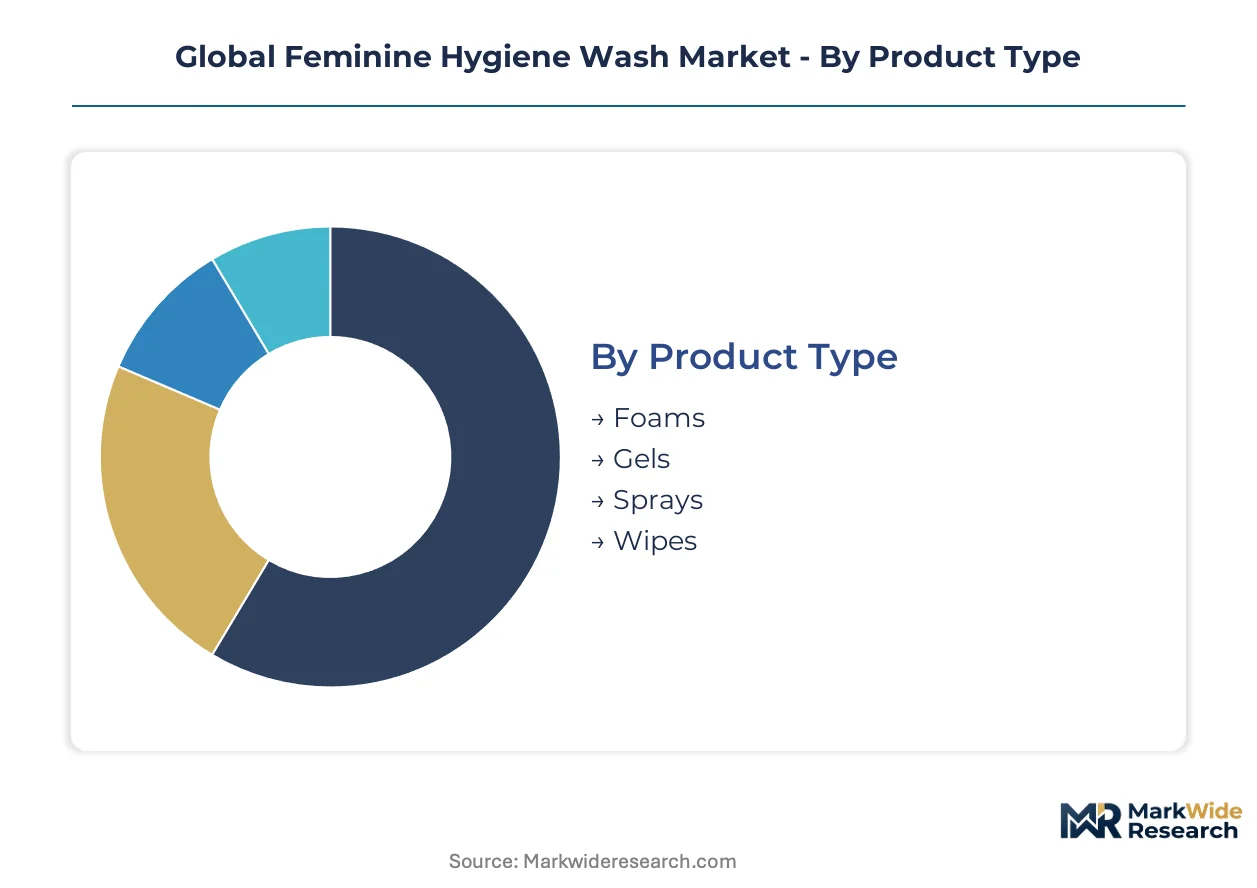
Segmentation in feminine hygiene wash separates clinically validated formulations from commodity alternatives. pH precision, microbiome compatibility, and dispensing format drive purchasing decisions across distinct user contexts and channel preferences.
Product Type:
Gels dominate current volume while foams capture the steepest premium expansion trajectory, reflecting divergent manufacturing scale and consumer experience priorities.
- Gels:Viscous aqueous formulations incorporating lactic acid buffers and mild surfactant systems enable precise dosing control. Demand concentrates in established pharmacy networks across Germany and Japan where clinical endorsement validates efficacy claims. Pump-dispensed variants command shelf preference over squeeze tubes in professional channels.
- Foams:Aerosol-free pump systems deliver pre-expanded lather with reduced surfactant concentration per application. Active lifestyle users in South Korea and the United States drive adoption for gym-bag portability and rapid-rinse convenience. Manufacturing line retrofits limit incumbent conversion speed.
- Sprays:Mist-delivery formats target touch-free application preferences in public restroom contexts.
- Wipes:Single-use substrates serve travel and postpartum hospital discharge scenarios where water access is constrained.
Today's leader: Gels. Tomorrow's challenger: Foams.
End User:
Postpartum protocols and athletic contexts generate formulation premiums that standard daily-use segments cannot match.
- Postpartum:Hospital discharge programs in India and Brazil now incorporate pH-balanced wash regimens into obstetric care guidelines. This segment commands the highest per-unit pricing due to clinical credibility requirements and insurance-adjacent reimbursement pathways. Formulations emphasize microbiome restoration following antibiotic exposure during delivery.
- Active Lifestyle Users:Sweat-induced pH disruption creates distinct cleansing needs for athletes and fitness participants. White space remains significant relative to postpartum positioning, with limited brand differentiation currently targeting marathon runners, cyclists, and CrossFit participants specifically.
- Women:General adult population represents the volume baseline with commodity-tier competition.
- Teens:First-user education and parental purchase influence shape channel strategy toward pharmacy and online sampling programs.
Postpartum segments anchor current premium capture. Active lifestyle positioning offers the most underdeveloped expansion corridor.
Packaging Type:
Dispensing precision and unit economics fragment competitive advantage across format choices.
- Pumps:Metered-dose mechanisms reduce overuse and support subscription replenishment models. Concentrated demand in direct-to-consumer channels and urban Indian pharmacy e-commerce platforms where auto-delivery bundling with menstrual products is standard. Foam-compatible pump engineering requires specialized valve tolerances.
- Tubes:Collapsible aluminum or laminate structures dominate travel-size and sample formats. Cost efficiency supports mass-market tiering in price-sensitive Southeast Asian markets.
- Bottles:Rigid PET or HDPE containers serve family-size and refill applications.
- Sachets:Single-dose foil pouches enable trial conversion and rural distribution where bottle return logistics are impractical.
Pump systems concentrate innovation investment. Sachets unlock geographic segments unreachable through conventional retail.
Distribution Channel:
Channel selection determines claim latitude, with pharmacy and online environments permitting clinical positioning unavailable in mass retail.
- Pharmacies:Professional endorsement channels sustain credibility for microbiome-supporting formulations. Unicharm Corporation and Johnson & Johnson compete through healthcare professional relationships in East Asian and North American markets respectively. EMA borderline classification clarity reduces registration uncertainty for products with bacterial culture references.
- Online Retail:Direct-to-consumer infrastructure enables subscription bundling and first-party data accumulation for personalized formulation development. Procter & Gamble Co. anchors recurring purchase behavior through auto-delivery programs in the United States.
- Supermarkets:Mass retail velocity depends on price competitiveness and shelf placement negotiations.
- Convenience Stores:Impulse and emergency purchase occasions favor sachet and travel-size formats.
Pharmacy channels defend clinical premium positioning. Online retail is expanding most quickly through subscription architecture and influencer-acquisition cost efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions with streamlined cosmetic-drug boundary classifications. Cost-of-compliance gaps between FDA, EMA, and CDSCO frameworks create location incentives for formulation facilities serving multiple export markets.
United States
Direct-to-consumer subscription infrastructure concentrates demand generation in coastal metropolitan corridors. FDA cosmetic labeling enforcement shapes formulation disclosure requirements for microbiome-supporting claims. Manufacturing scale clusters around Cincinnati and Boston metro areas where personal care R&D talent pools intersect with packaging engineering capabilities.
Germany
EMA borderline classification clarity accelerates product registration for pH-balanced formulations with bacterial culture references. REACH Annex XVII fragrance allergen rules drive preservative system reformulation across pharmacy-distributed portfolios. Industrial activity concentrates in North Rhine-Westphalia where contract manufacturing infrastructure serves pan-European distribution.
India
Postpartum hospital discharge programs in Maharashtra and Karnataka normalize specialized wash regimens through obstetric care guidelines. PLI scheme incentives for personal care ingredients reduce import dependency for coconut-derived surfactant inputs. Domestic formulation capacity expands around Mumbai and Ahmedabad to serve pharmacy e-commerce platform demand.
South Korea
Active lifestyle user segments drive foam-format adoption through gym-bag portability preferences. MFDS cosmetic safety standards influence preservative selection for sensitive-skin positioning. Seoul-based digital-native brands leverage micro-influencer networks to displace traditional in-store trial mechanisms.
Brazil
Postpartum clinical protocols in São Paulo and Rio de Janeiro states incorporate wash regimens into public health obstetric guidelines. ANVISA registration requirements determine whether formulations classify as cosmetics or medical devices. Regional manufacturing serves Latin American export demand while navigating surfactant input volatility from Southeast Asian supply chains.
Global Feminine Hygiene Wash Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy-channel credibility commanding premium positioning against mass-retail velocity players. Market structure tilts toward consolidated multinational portfolios at the premium tier and fragmented regional formulators serving price-sensitive segments. Three archetypes dominate: clinically endorsed healthcare brands, direct-to-consumer digital natives, and private-label contract manufacturers. Competitive moves concentrate on subscription platform architecture and aerosol-free foam manufacturing line retrofits.
Among established consumer goods conglomerates, Procter & Gamble Co. and Johnson & Johnson exemplify divergent channel strategies within the same regulatory environment. Procter & Gamble Co. anchors recurring revenue capture through auto-delivery infrastructure, while Johnson & Johnson occupies a position sustained by healthcare professional endorsement relationships. Unicharm Corporation represents the pharmacy-centric distribution archetype prevalent in East Asian markets, sitting within a tier where clinical credibility determines shelf access rather than price competitiveness.
| Leading Market Players |
|---|
| Procter & Gamble Co. |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Unilever |
| Unicharm Corporation |
| Essity AB |
| Lactacyd |
| Summer's Eve |
| LIFEON Labs |
| Others |
Supply Flow & Price Mechanics
Aerosol-free foam manufacturing line retrofits simultaneously compress unit production costs and concentrate supplier capability among capital-rich multinationals, fragmenting tier-two formulators who lack retrofit financing access. This technology transition feeds directly into subscription pricing architectures where pump-dispensed formats command recurring revenue premiums over legacy squeeze tubes.
Pricing Analysis
Distributor margins in pharmacy channels absorb the steepest compression as direct-to-consumer platforms disintermediate traditional wholesale networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical endorsement intensity and microbiome claim substantiation. Pricing pressure stems from coconut-derived surfactant input volatility exposing margin structures to weather-driven raw material swings. Postpartum segments exhibit lowest price sensitivity due to insurance-adjacent reimbursement pathways, while rural pharmacy networks in price-sensitive markets demonstrate highest elasticity toward standard body wash substitution.
Supply Chain Analysis
Regional distribution centers in Mumbai, North Rhine-Westphalia, and Cincinnati anchor hub-and-spoke patterns serving pharmacy e-commerce platforms and direct-to-consumer auto-delivery infrastructure. Manufacturing concentration clusters in India, Germany, and the United States where contract manufacturing infrastructure intersects with packaging engineering capabilities. Raw material dependencies center on Southeast Asian coconut-derived mild surfactant processing, biotech-derived lactic acid fermentation outputs, and REACH-compliant preservative alternatives. Single-source vulnerability concentrates in coconut surfactant supply chains exposed to climate-driven harvest variability. Distribution runs through pharmacy professional endorsement channels and online retail subscription bundling with menstrual products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA cosmetic-drug boundary enforcement and EMA borderline classification clarity creates geographic manufacturing incentives, with cost-of-compliance gaps redirecting formulation facility investment toward jurisdictions with streamlined microbiome claim pathways.
For Market Incumbents: Extend clinical credibility moats through healthcare professional endorsement deepening in pharmacy channels, while accelerating aerosol-free foam manufacturing line retrofits to capture active lifestyle segment premiums. Defensive priority rests on backward integration into biotech-derived lactic acid fermentation capacity to neutralize synthetic pH stabilizer cost parity threats from emerging formulators. Channel control through subscription platform architecture anchors recurring revenue capture against direct-to-consumer digital native disruption. For New Entrants and Emerging Players: Active lifestyle users represent the most penetrable white space, with athletic-specific variants for marathon runners and CrossFit participants remaining underdeveloped relative to saturated postpartum positioning. Geographic entry through South Korean micro-influencer acquisition networks reduces customer acquisition costs versus traditional in-store trial mechanisms. Go-to-market angle centers on gym-bag portability claims and rapid-rinse convenience messaging displacing gel-format incumbents in fitness contexts. For Investors and Strategic Acquirers: Roll-up economics work for regional pharmacy-centric formulators because EMA borderline classification clarity reduces registration uncertainty and enables pan-European product pipeline advancement through centralized regulatory filing. Long-term viability frames around microbiome research capability scarcity forcing consolidation among clinical research partnership holders. Acquisition target archetype: digital-native brands with first-party data accumulation infrastructure for personalized formulation development. Signal to watch: CDSCO microbiome-specific health claims regulation evolution triggering pharmaceutical reclassification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Aerosol-Free Foam Manufacturing Retrofit | Pump mechanism reliability at scale captures active lifestyle premiums in South Korea and United States gym channels. |
| Direct-to-Consumer Subscription Launch | Auto-delivery bundling with menstrual products concentrates recurring revenue in urban Indian pharmacy e-commerce platforms. |
| Clinical Endorsement Channel Expansion | Healthcare professional relationships in Germany and Japan validate microbiome-supporting formulation claims against commodity alternatives. |
| Biotech-Derived Input Backward Integration | In-house lactic acid fermentation capacity neutralizes synthetic pH stabilizer cost parity and secures mass-market tiering flexibility. |
| Regulatory Arbitrage Manufacturing Relocation | EMA borderline clarity and PLI scheme incentives redirect formulation facilities toward India and Germany for multi-jurisdiction export efficiency. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at pharmacy retailers, supply planners at contract manufacturers, and regulatory affairs leads at multinational consumer health divisions with secondary validation through FDA cosmetic labeling guidance documents, EMA borderline classification guidance, REACH Annex XVII fragrance allergen updates, Nielsen retail audit data, and customs records of coconut-derived surfactant imports. Bottom-up demand modeling across product type, end user, packaging format, and distribution channel segments triangulated against top-down market sizing from production capacity and channel velocity indicators.
Segment-weighting approaches distributed analytical emphasis across gels, foams, sprays, and wipes by volume contribution and premium expansion trajectory, with postpartum and active lifestyle end user segments receiving differentiated growth assumptions based on clinical protocol adoption rates and athletic participation demographics. CAGRs derived from regression analysis of historical channel velocity against macroeconomic indicators and regulatory event timelines. Industry-specific forecast inputs incorporated PLI scheme incentive uptake rates in India and aerosol-free pump manufacturing line conversion schedules among incumbent facilities.
Underlying measurement precision varies by segment; pharmacy-dispensed premium tiers with established clinical endorsement carry tighter precision than emerging direct-to-consumer digital native brands with limited historical velocity. Forecasts reflect documented assumptions regarding regulatory classification stability, surfactant input cost trajectories, and microbiome claim substantiation standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Surgical Drapes Market
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Europe Sanitary Napkin Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Feminine Wipes Market
Medical and Hygiene Textiles
Global Biomedical Textiles Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market