
 Tissue Towel Market | 2026-2036
Tissue Towel Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Towel Market Outlook
Foodservice buyer consolidation is decoupling from traditional retail-driven demand patterns as institutional procurement platforms aggregate volume across multi-site operators. Kimberly-Clark Corporation leverages its North American manufacturing footprint to serve this shifting channel mix. Georgia-Pacific sustains cost leadership through integrated pulp supply chains in the southeastern United States. Essity AB differentiates via premium hygiene positioning across European commercial facilities.
Tissue towel denotes absorbent paper-based wiping products manufactured from virgin wood pulp, recycled fiber, or alternative cellulosic substrates through creping processes that impart bulk and softness for moisture absorption. The primary commercial purpose spans personal hygiene, surface cleaning, and hand-drying applications across household and institutional settings. Two-ply products dominate volume due to perceived durability, yet bamboo-based single-ply alternatives are capturing margin pools in sustainability-focused retail channels. Online retail distribution is accelerating fastest among channels as subscription models penetrate household replenishment cycles.
The EPA's Comprehensive Procurement Guidelines shape recycled content requirements for federal facility supply contracts, while the EU Ecolabel and FSC chain-of-custody certification constrain raw material sourcing for products entering European public procurement. FDA oversight of indirect food-contact materials affects tissue towel composition for foodservice applications in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine cost allocation between virgin and recycled fiber supply chains.
Market Dynamics
Post-pandemic hygiene protocols have permanently elevated institutional procurement standards, decoupling foodservice and hospitality demand from traditional retail cycles while pressuring manufacturers to certify sustainable fiber sourcing under tightening EU and US federal guidelines.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates on disposable product sustainability are accelerating substrate innovation toward bamboo and recycled fiber alternatives, creating compliant supply channels for European institutional buyers.
- Foodservice procurement platforms:Multi-site operator consolidation through institutional purchasing networks is aggregating volume and standardizing specifications across hospitality chains.
- Federal facility contracts:EPA Comprehensive Procurement Guidelines are mandating recycled content thresholds, securing demand baselines for domestic recycled fiber producers.
Market Restraints
- Pulp cost volatility:Virgin softwood pulp prices fluctuate with energy and freight inputs, compressing margins for non-integrated converters lacking captive timber supply.
- Southeastern US supply concentration:Integrated pulp-to-towel manufacturing clusters in Georgia and Alabama create geographic vulnerability to hurricane disruption and regional labor tightness.
- Air-dryer substitution:High-velocity hand dryers in commercial restrooms are displacing paper towel dispensers in airport, stadium, and corporate facility retrofits.
Strategic Opportunities
- German manufacturing expansion:WEPA Hygieneprodukte GmbH and Essity AB anchor substantial European capacity, positioning the country as a compliance-forward export hub for Ecolabel-certified products.
- Subscription household replenishment:Direct-to-consumer auto-replenishment models via online retail are capturing recurring revenue streams and bypassing traditional grocery shelf competition.
- Bamboo fiber convergence:Agricultural residue processing technology is enabling cost-competitive bamboo pulp integration, opening premium positioning in sustainability-focused retail channels.
Industry Challenges
- FSC chain-of-custody certification timelines:Multi-month audit and documentation requirements delay product launches for new recycled fiber suppliers seeking European public procurement eligibility.
- Legacy dispenser infrastructure:Foodservice and hospitality operators face capital friction retrofitting automated, sensor-enabled dispensers that optimize consumption tracking and reduce waste.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Towel Market |
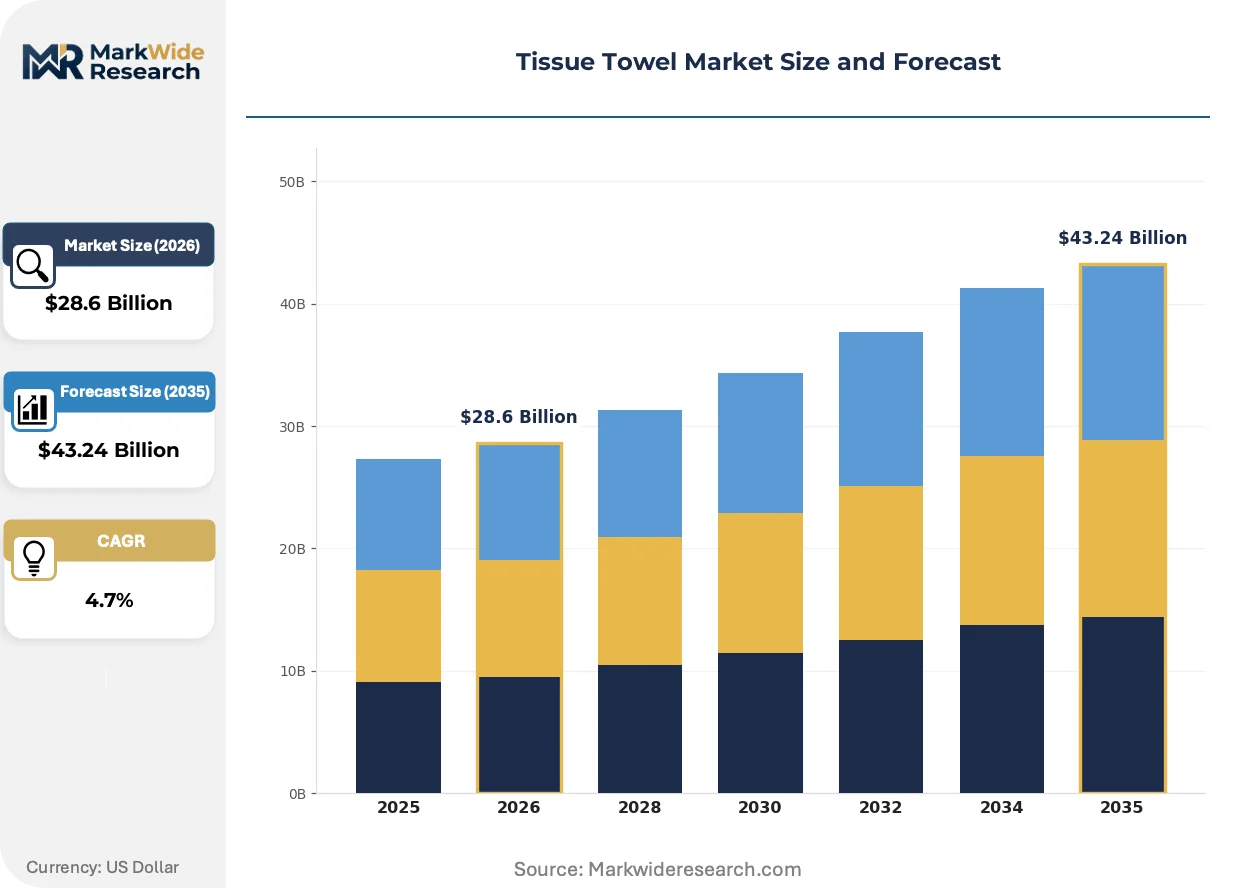
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-ply, Two-ply, Reusable, Disposable Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Commercial Facilities, Healthcare Institutions, Educational Institutes Material: Pulp, Recycled Fiber, Bamboo, Others |
| Companies Covered | Procter & Gamble, Kimberly-Clark Corporation, Georgia-Pacific, Essity AB, Sofidel Group, Cascades Inc, Kruger Inc., Metsa Tissue, WEPA Hygieneprodukte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Towel Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine substrate composition, while procurement digitization and sustainability certification are reshaping competitive differentiation and channel access.
Dry-creped tissue manufacturing is consolidating around through-air-dried (TAD) technology, which delivers superior bulk and absorbency per gram of fiber. Institutional buyers in healthcare and premium hospitality are specifying TAD-constructed towels for perceived quality and reduced consumption per hand-drying event. This technology is consolidating production scale advantages among capital-intensive manufacturers with multi-machine TAD assets.
REACH chemical restrictions and EU Ecolabel criteria are tightening permissible processing aids and bleaching chemistries in fiber preparation. Manufacturers must reformulate wet-strength resins and softening agents to maintain performance while meeting substance authorization thresholds. German and Nordic markets exhibit the strictest enforcement, with public procurement tenders rejecting non-compliant bids regardless of price positioning.
Foodservice operators are unbundling towel supply from broadline distribution contracts, establishing direct relationships with specialty hygiene suppliers for specification control and sustainability verification. Casino, cruise line, and quick-service restaurant chains are leading this disintermediation, driven by corporate ESG reporting requirements that demand granular supply chain transparency. The US Gulf Coast and Atlantic seaboard hospitality corridors show the highest concentration of this procurement model shift.
Tissue Towel Market Segmentation
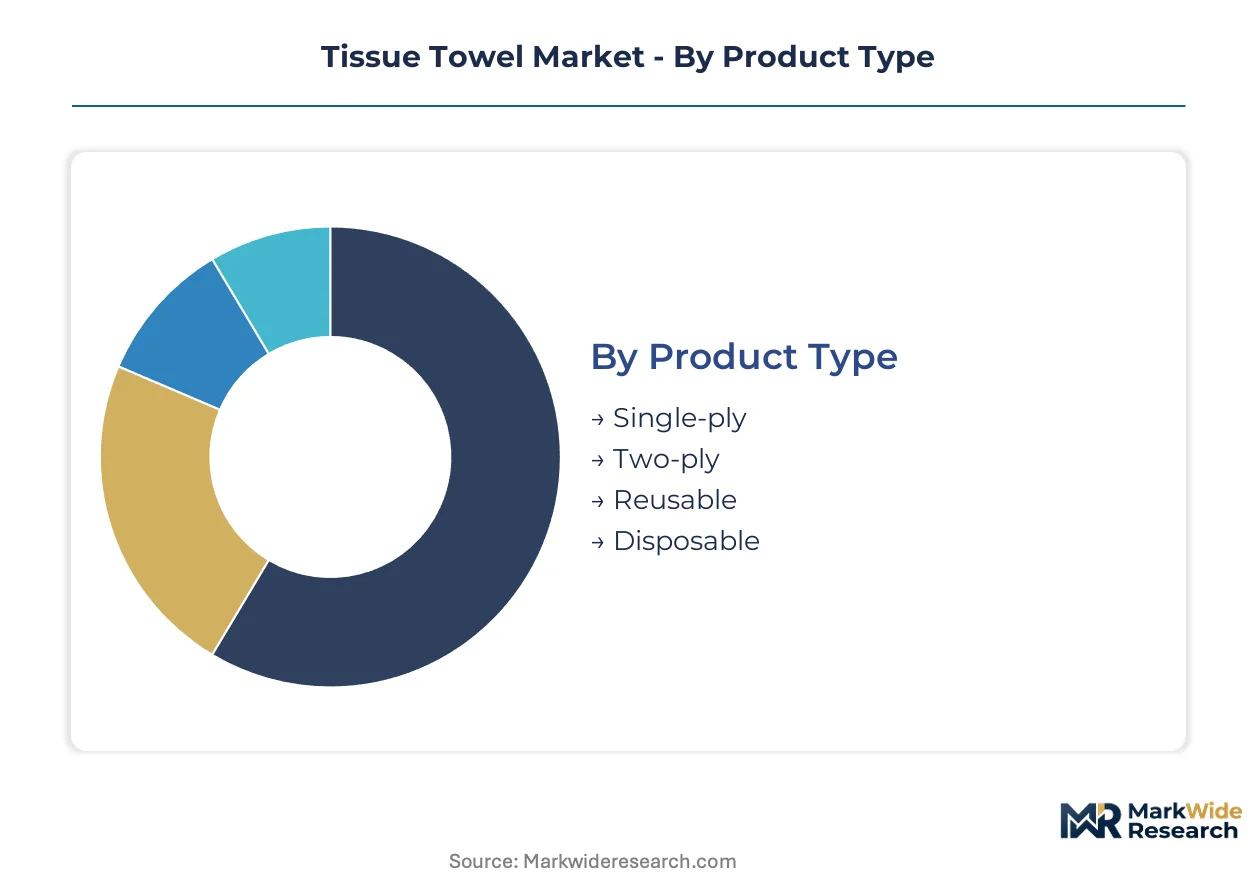
Tissue towel segmentation reveals divergent margin structures between mass-market disposable volumes and premium sustainable alternatives. Manufacturers calibrate fiber sourcing, ply construction, and distribution strategy against distinct procurement behaviors across household replenishment versus institutional specification buying.
Product Type:
Volume concentration tilts toward multi-ply construction for perceived durability, while single-ply formats capture sustainability premiums through substrate innovation.
- Two-ply:Creped construction layers deliver bulk and tensile strength for hand-drying efficiency. Hospitality chains in Germany and the United States specify two-ply as baseline quality for guest-facing restrooms, driving procurement standardization across multi-site portfolios.
- Single-ply:Reduced fiber content per unit enables cost positioning and lowers environmental footprint claims. Bamboo-based single-ply alternatives are gaining shelf space in European retail channels under EU Ecolabel positioning, though institutional buyers resist perceived quality trade-offs.
- Disposable:Virgin and recycled fiber substrates dominate foodservice and healthcare procurement where contamination protocols mandate single-use. EPA Comprehensive Procurement Guidelines shape federal facility demand toward recycled content thresholds.
- Reusable:Cloth-based alternatives serve industrial wiping and select hospitality applications with laundering infrastructure. Capital intensity for linen service integration limits penetration outside contracted facility management relationships.
Today's leader: Two-ply. Tomorrow's challenger: Single-ply bamboo alternatives.
Distribution Channel:
Channel selection determines margin capture and customer data access, with digital routes disrupting traditional grocery replenishment cycles.
- Online Retail:Subscription auto-replenishment models bypass shelf competition and build direct consumer relationships. Amazon and specialized hygiene platforms aggregate household demand with predictive inventory algorithms that reduce stockout risk.
- Supermarkets:Impulse and planned purchases concentrate in multi-pack formats with high shelf velocity. Retailer private label penetration pressures branded manufacturers to differentiate through TAD technology or FSC certification callouts.
- Wholesale:Institutional volume flows through broadline distributors and specialty hygiene suppliers to foodservice, healthcare, and educational facilities. Procurement platform consolidation is disintermediating traditional distributor relationships for specification control.
- Convenience Stores:Emergency and travel-size purchases drive single-roll and small-pack formats with premium per-unit pricing. Urban density and transit hub proximity determine store-level assortment decisions.
Online retail climbs fastest; supermarkets defend the volume base.
End User:
Demand bifurcates between price-sensitive household replenishment and specification-driven institutional procurement with compliance documentation requirements.
- Commercial Facilities:Offices, airports, and stadiums balance consumption cost against restroom traffic and sustainability reporting. High-velocity hand dryer substitution threatens paper towel specification in new construction and major retrofits.
- Healthcare Institutions:Infection control protocols mandate single-use disposable towels with specific absorbency and linting performance. FDA oversight of indirect food-contact materials extends to towel composition in clinical foodservice settings.
- Households:Replenishment cycles align with grocery trips or subscription deliveries, with brand loyalty eroding under private label quality convergence. Two-ply products dominate basket composition for perceived value.
- Educational Institutes:K-12 and university procurement aggregates volume through cooperative purchasing agreements with recycled content mandates. Budget constraints favor economy-tier specifications against premium hospitality benchmarks.
Commercial facilities lead institutional spend; healthcare tightens specification standards.
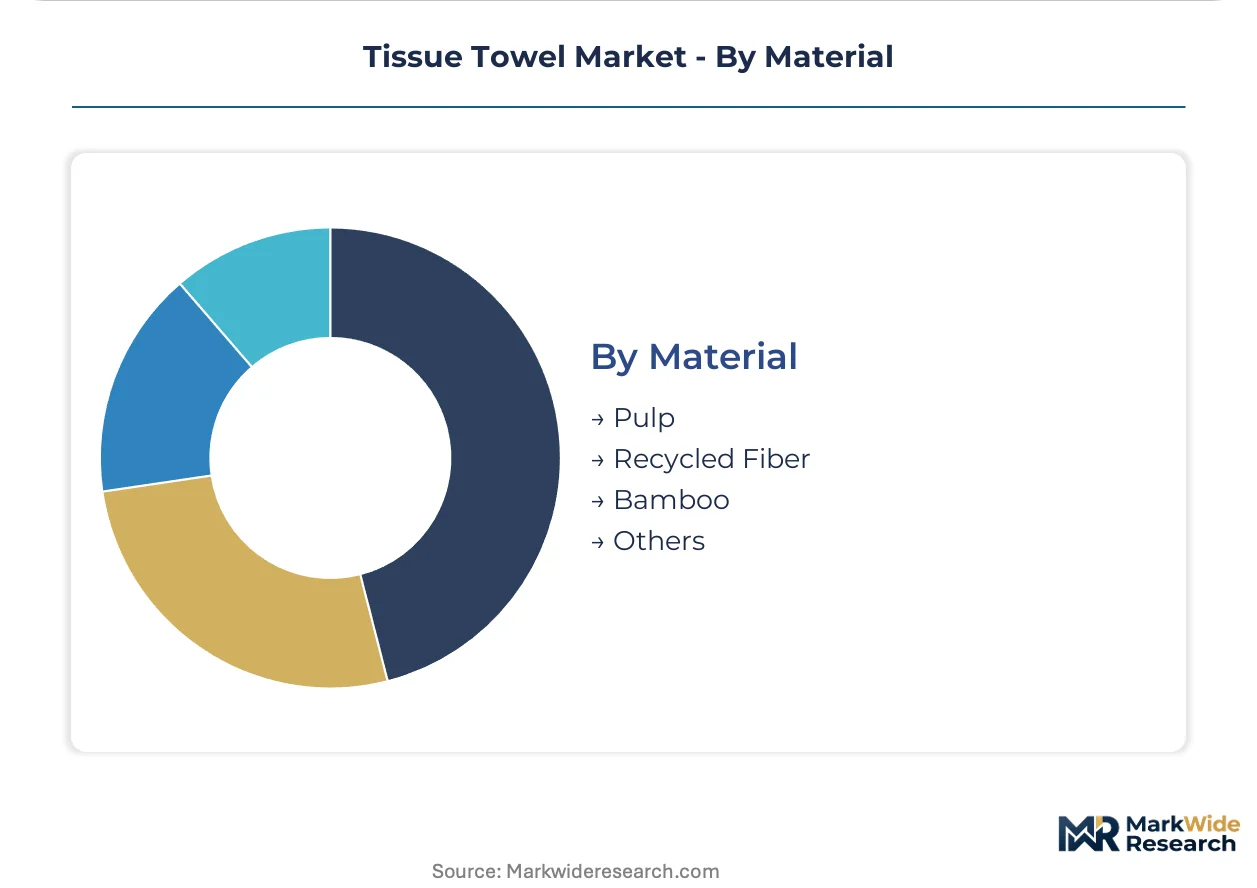
Material:
Fiber sourcing decisions cascade through cost structure, regulatory compliance eligibility, and premium positioning in sustainability-focused channels.
- Pulp:Virgin softwood kraft pulp delivers consistent fiber length and absorbency performance for TAD manufacturing. Southeastern United States timber supply clusters anchor integrated production for North American market supply.
- Recycled Fiber:Post-consumer content satisfies EPA Comprehensive Procurement Guidelines and European public procurement thresholds. Collection infrastructure quality and deinking technology determine finished product softness and visual acceptability.
- Bamboo:Rapid-renewable grass fiber enables agricultural residue processing with lower water and chemical inputs. REACH chemical restrictions and EU Ecolabel criteria constrain processing aid selection for European market access.
- Others:Wheat straw, bagasse, and emerging cellulosic alternatives occupy niche positioning with limited scale. Technical performance gaps in bulk and wet strength restrict mainstream adoption.
Virgin pulp holds volume dominance; bamboo gains fastest in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands European institutional procurement standards while the United States anchors North American manufacturing capacity with distinct regulatory frameworks shaping fiber sourcing compliance across both markets.
United States
Federal facility contracts and hospitality chain consolidation drive institutional demand. EPA Comprehensive Procurement Guidelines mandate recycled content thresholds for government supply agreements. Southeastern timber clusters in Georgia and Alabama host integrated pulp-to-towel manufacturing operations serving domestic foodservice networks.
Germany
EU Ecolabel certification requirements and REACH chemical restrictions elevate compliance barriers for market entry. The EU Single-Use Plastics Directive accelerates substrate innovation toward bamboo and recycled fiber alternatives. WEPA Hygieneprodukte GmbH and Essity AB anchor substantial European manufacturing capacity in North Rhine-Westphalia and Baden-Württemberg.
China
Rapid urbanization and expanding foodservice infrastructure sustain volume consumption growth. National standards under SAMR oversight govern food-contact material safety for hospitality applications. Yangtze River Delta manufacturing zones concentrate tissue converting capacity for domestic and export supply.
Japan
Premium hospitality specifications and healthcare infection control protocols sustain quality-tier demand. METI industrial standards and JIS certification requirements constrain processing chemistry selection. Kanto region facilities serve Tokyo metropolitan commercial and institutional procurement networks.
United Kingdom
Post-Brexit regulatory divergence from EU Ecolabel frameworks creates parallel compliance pathways for suppliers. Corporate ESG reporting mandates drive sustainability verification requirements across hospitality and foodservice procurement. Midlands-based converting operations supply retail and institutional channels with recycled fiber alternatives.
Tissue Towel Market Competitive Environment
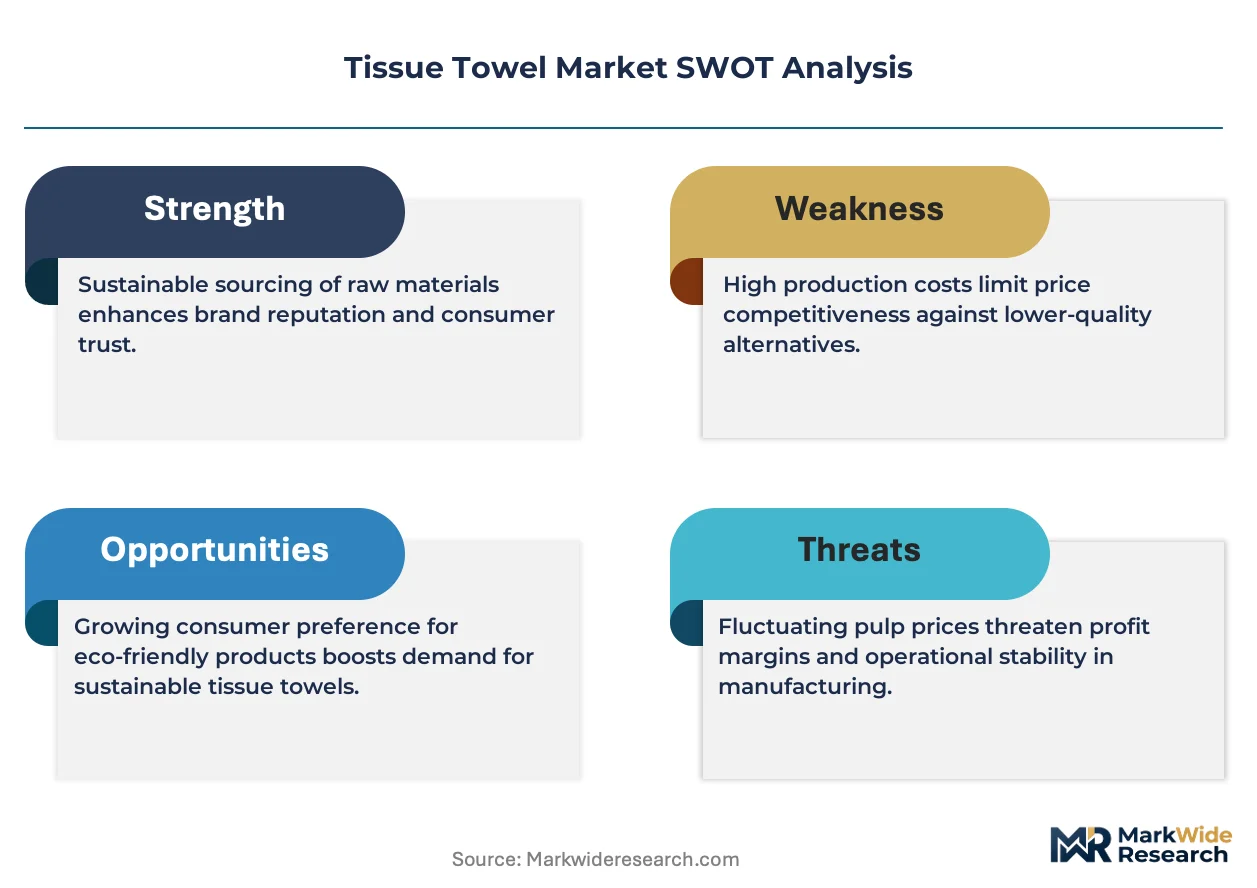
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. Consolidated manufacturing scale concentrates among North American and European integrated producers with captive pulp supply. Three strategic archetypes dominate: timber-integrated volume leaders, sustainability-certified premium specialists, and regional private-label converters. Capacity expansion and fiber sourcing certification represent the dominant competitive moves as procurement platforms demand supply chain transparency documentation.
Among North American integrated producers, Georgia-Pacific and Kimberly-Clark Corporation exemplify scale-driven manufacturing archetypes with extensive pulp supply chain control. Essity AB represents the European premium hygiene specialist positioning, anchoring compliance-forward production for Ecolabel-certified institutional contracts. WEPA Hygieneprodukte GmbH occupies the focused regional manufacturer tier, serving German and export markets with specialized tissue converting expertise.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark Corporation |
| Georgia-Pacific |
| Essity AB |
| Sofidel Group |
| Cascades Inc |
| Kruger Inc. |
| Metsa Tissue |
| WEPA Hygieneprodukte GmbH |
| Others |
Value Chain & Pricing Dynamics
Machine tender workforce concentration in the southeastern United States creates labor-cost differentials that widen pricing-tier spreads between virgin pulp-based economy towels and TAD-constructed premium alternatives. German and Nordic compliance-certified production commands substantial premiums over non-Ecolabel alternatives due to audit documentation and reformulation costs.
Pricing Analysis
Capacity additions in China and Indonesia are reshaping price floors for standard-grade recycled fiber towels, compressing margins for non-integrated converters. Three-tier pricing structure across premium TAD, standard two-ply, and economy single-ply levels stratifies by absorbency certification and FSC chain-of-custody status. Price differentiation stems from wet-strength resin chemistry compliance and dispenser system compatibility. Foodservice procurement platforms exhibit highest price sensitivity; healthcare infection-control specifications show least sensitivity due to protocol mandates.
Supply Chain Analysis
Domestic-content mandates under EPA Comprehensive Procurement Guidelines are reshaping sourcing toward North American recycled fiber collectors and deinking facilities. Virgin softwood pulp supply concentrates in the United States, Canada, and Brazil; bamboo fiber processing clusters in China and Southeast Asia. Raw material dependencies include timber supply contracts, caustic soda for pulping, and wet-strength resin chemistries. Tariff exposure on Chinese bamboo pulp imports threatens cost structures for sustainability-positioned brands. Distribution runs through broadline institutional distributors, direct procurement platforms, and retail grocery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue towel market functions as a stable compounder anchored by permanent post-pandemic hygiene protocol elevation across institutional procurement. Recurring replenishment cycles and subscription auto-replenishment models reinforce predictable revenue visibility.
For Market Incumbents:Acquire TAD manufacturing assets and multi-machine through-air-drying production lines to defend share against premium private label encroachment. Secure captive pulp supply through long-term timber contracts or backward integration into southeastern United States timberlands. Air-dryer substitution in commercial facilities threatens volume; counter with sensor-enabled dispenser infrastructure partnerships that optimize consumption tracking.
For New Entrants and Emerging Players:Enter via bamboo fiber towel specialization targeting European retail channels under EU Ecolabel positioning, where compliance barriers limit incumbent agility. Target German and Nordic sustainability-focused household segments with subscription direct-to-consumer models bypassing grocery shelf competition. Leverage agricultural residue processing partnerships for cost-competitive raw material access.
For Investors and Strategic Acquirers:Private equity firms with consumer staples specialization are the most active acquirer in this space, consolidating regional converters for platform buildouts. Five-to-ten year viability rests on fiber sourcing certification depth and institutional procurement platform relationships. Acquisition target archetype: mid-scale converters with FSC chain-of-custody certification and TAD technology access. Monitor EU Ecolabel criteria tightening as inflection signal for compliance-cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| TAD Technology Investment | Through-air-dried manufacturing secures premium positioning in healthcare and hospitality procurement. |
| Bamboo Fiber Integration | Agricultural residue processing enables EU Ecolabel compliance and sustainability premium capture. |
| Subscription Platform Launch | Direct-to-consumer auto-replenishment bypasses retail competition and builds recurring revenue. |
| FSC Certification Acceleration | Chain-of-custody documentation unlocks European public procurement and corporate ESG sourcing. |
| Dispenser Infrastructure Partnership | Sensor-enabled systems optimize consumption tracking and defend against air-dryer substitution. |
Study Parameters
Bottom-up institutional procurement modeling reconciled against top-down pulp supply tracking forms the analytical core of this study. Primary interviews with foodservice procurement directors, hospitality chain facility managers, tissue converting plant operators, and broadline distributor category buyers combined with secondary validation from EPA Comprehensive Procurement Guidelines filings, EU Ecolabel certification databases, FSC chain-of-custody audit records, and customs trade data. Triangulation across these sources ensures volume and specification alignment.
Historical trendline analysis of creped tissue production capacity, fiber input costs, and channel shipment patterns informed projection frameworks. Segmentation dimensions modeled include product construction, material substrate, distribution channel, and end-use facility type across the projection horizon. CAGRs derive from fitted trend extrapolation adjusted for regulatory phase-in schedules and procurement platform adoption curves. Pulp price volatility indices and dispenser infrastructure replacement cycles serve as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines and intact trade flows for bamboo pulp; deviation in EU Ecolabel criteria stringency or southeastern United States hurricane disruption would shift volume and value trajectories. Forecasts reflect documented assumptions regarding procurement platform consolidation rates and air-dryer substitution penetration ceilings. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Global Healthcare Fabrics Market
Medical and Hygiene Textiles
Europe Adult Diaper Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Global Feminine Hygiene Wash Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
GCC Sanitary Napkin Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market