
 Medical Non-Woven Disposables Market | 2026-2036
Medical Non-Woven Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Non-Woven Disposables Market Analysis
A capital-intensity divergence between integrated fiber producers and finished-goods converters is unwinding legacy margin structures in the medical non-woven disposables supply chain. Kimberly-Clark Corporation leverages captive pulp supply and North American meltblown capacity to sustain cost advantages in surgical drapes. Mölnlycke Health Care AB anchors its position through vertical control over European SMS laminate production. Medline Industries, LP competes via direct distribution contracts with integrated delivery networks, bypassing traditional wholesale channels.
Medical non-woven disposables encompass single-use textile products engineered from synthetic or natural fibers bonded through thermal, chemical, or mechanical means without traditional weaving or knitting, typically achieving bacterial filtration efficiencies exceeding 95% in SMS constructions. These products serve primarily to maintain sterile fields during invasive procedures and prevent cross-contamination in clinical environments. Face masks and surgical drapes represent mature, high-volume categories where pricing pressure from group purchasing organizations compresses margins, while patient gowns in specialized antimicrobial finishes command premium positioning. Hospitals dominate end-user demand but home healthcare represents the fastest-growing consumption point as post-acute care shifts to residential settings.
FDA 510(k) clearance requirements and EPA antimicrobial claims substantiation govern product entry and labeling in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards on barrier-class drapes and gowns sold in Europe. ISO 10993 biocompatibility testing and AAMI PB70 liquid barrier classification create tiered compliance costs that favor manufacturers with established regulatory infrastructure. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance restrictions, as pending limits on fluorinated repellent chemistries threaten to obsolete current premium gown finishes without viable replacements at scale.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing supplier margins while elevating barrier performance standards under FDA 510(k) clearance pathways, forcing converters to absorb compliance costs or exit sterile drape categories entirely.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding ASC procedure volumes in the United States are amplifying demand for compact sterile field kits and single-use gowns optimized for same-day discharge protocols.
- EPA antimicrobial claim substantiation:Validated efficacy labeling against hospital-acquired pathogens is enabling premium positioning for copper-infused and silver-ion treated non-woven substrates in surgical applications.
- Post-acute residential migration:Home healthcare settings in Germany and Japan are adopting disposable wound dressings and isolation gowns as skilled nursing facilities discharge patients earlier.
Market Restraints
- Polypropylene price volatility:Propylene feedstock fluctuations tied to naphtha-cracker economics in the US Gulf Coast are eroding converter margins on high-volume spunbond-meltblown-spunbond laminates.
- Meltblown capacity concentration:European SMS fabric production clusters in Belgium and Germany create geographic single-source risk for barrier-class gown manufacturers during energy price spikes.
- Fluorinated chemistry obsolescence:Pending EPA per- and polyfluoroalkyl substance restrictions threaten to invalidate current blood-repellent finishes without scalable bio-based alternatives certified to AAMI PB70 Level 4.
Strategic Opportunities
- India hospital infrastructure buildout:Government-funded medical cities under the Ayushman Bharat scheme are creating first-time demand for sterile disposables in tier-2 and tier-3 cities previously served by reusable textiles.
- EU Medical Device Regulation clinical evidence pathways:MDR Article 61 requirements for barrier-class products are creating consultancy and testing service demand that vertically integrated manufacturers can capture as revenue streams.
- Biodegradable fiber convergence:PLA-polylactic acid and PHA-polyhydroxyalkanoate non-woven blends are opening composting-certified product lines for outpatient clinics with sustainability procurement mandates.
Industry Challenges
- Regulatory affairs specialization scarcity:FDA 510(k) predicate device strategists and EU MDR technical documentation authors command premium salaries that mid-tier converters struggle to retain.
- ISO 10993 biocompatibility testing backlog:Cytotoxicity and sensitization study queues at certified laboratories are extending product launch timelines for novel antimicrobial finishes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Non-Woven Disposables Market |
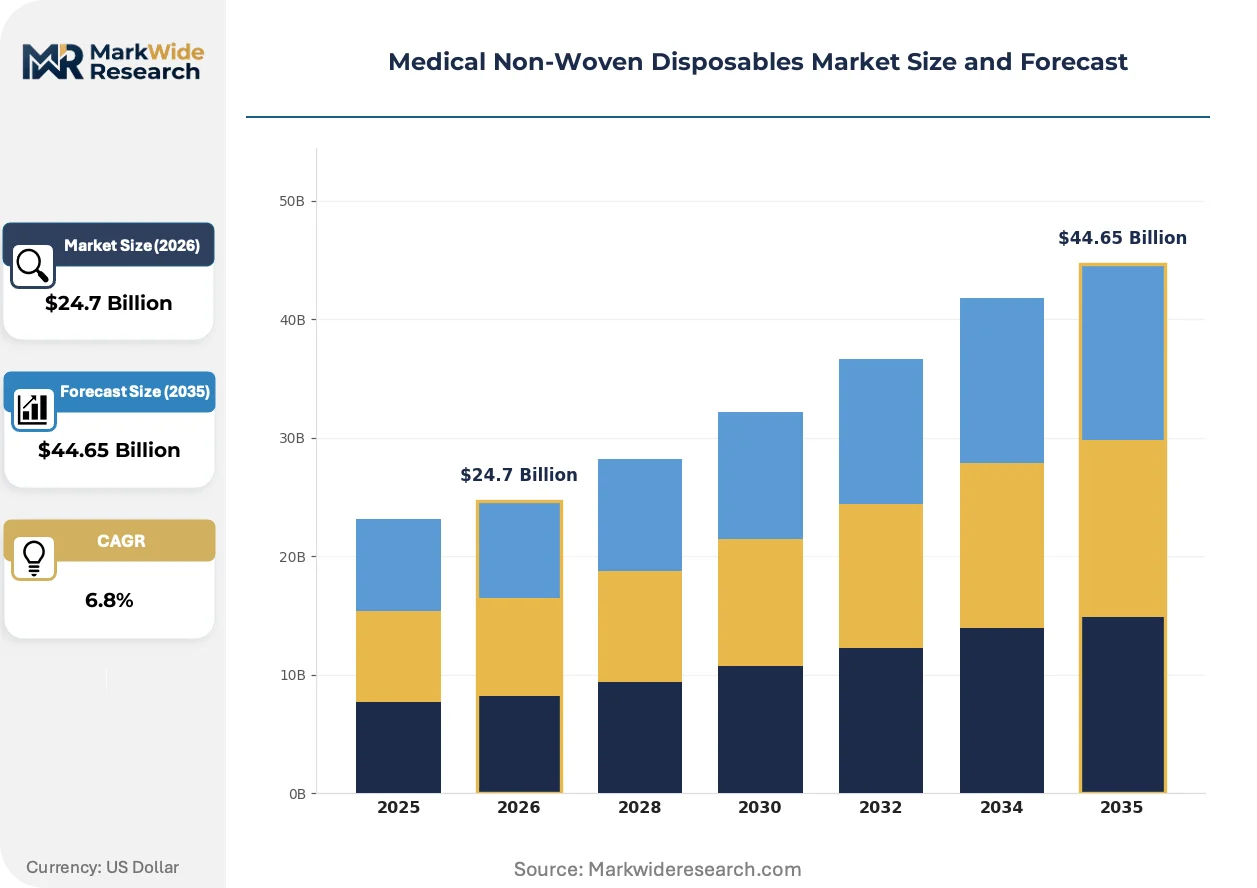
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Drapes, Sterile Wraps, Face Masks, Patient Gowns End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Material: Polypropylene, Polyester, SMS, Spunbond Application: Infection Control, Surgical Procedure, Patient Care, Wound Dressing |
| Companies Covered | Domtar Corporation, Medtronic, Mölnlycke Health Care AB, Kimberly-Clark Corporation, Medline Industries, LP, Freudenberg Performance Materials, Ahlstrom, Asahi Kasei Corporation, Svenska Cellulosa Aktiebolaget SCA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Non-Woven Disposables Market Emerging Trajectories
Material science advances and procurement centralization are reconfiguring competitive advantage around barrier performance certification rather than commodity scale, elevating technical service capabilities above pure manufacturing efficiency.
Electrospun nanofiber membranes are achieving sub-micron filtration efficiency without meltblown density penalties, enabling lighter-weight surgical masks that meet N95-equivalent standards. Cardiac catheterization labs and interventional radiology suites in the United States are piloting these substrates for extended-wear procedural comfort. The technology is decomposing the traditional SMS laminate cost structure by eliminating the meltblown layer entirely in select barrier applications.
EU MDR Annex XVI expansion to include products without intended medical purpose but with medical-like risk profiles is capturing aesthetic procedure drapes and tattoo barriers under clinical evidence requirements. German notified bodies are imposing stricter biological evaluation plans on these borderline products than under the previous Medical Device Directive. French and Italian converters serving cosmetic surgery chains are restructuring quality management systems to accommodate unannounced audits.
Direct contracting between sterile processing departments and manufacturers is displacing distributor intermediaries for high-volume gown and drape categories. IDN supply chain executives in Texas and California are negotiating multi-year sole-source agreements with guaranteed volume floors. This channel compression is most visible in the United States, where group purchasing organization consolidation has left only three national contracts covering the majority of acute care beds.
Medical Non-Woven Disposables Market Segmentation
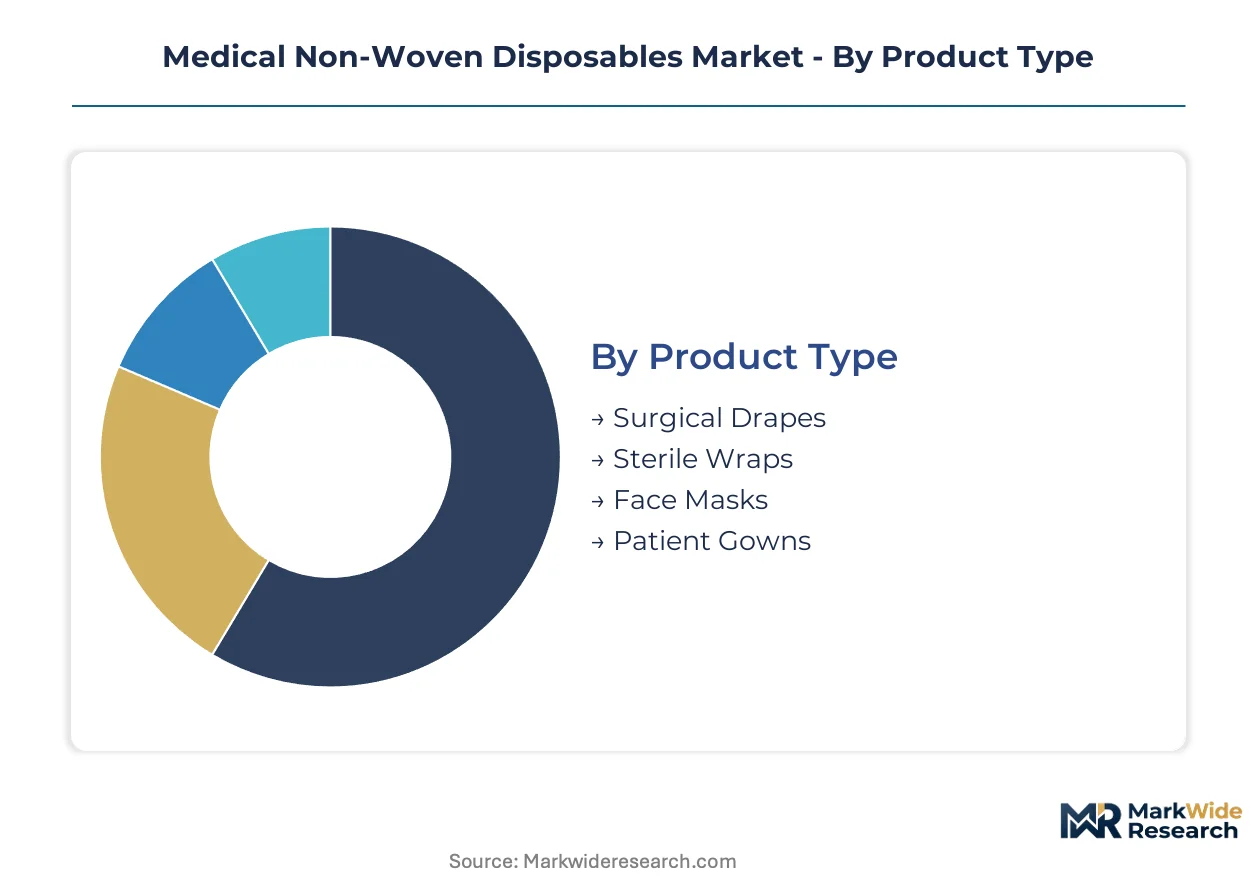
Segmentation in medical non-woven disposables reveals how procurement centralization and regulatory tiering concentrate margin pools in certified barrier products rather than commodity volumes. Understanding these splits exposes where integrated manufacturers defend pricing power against converter competition.
Product Type:
Margin pools concentrate in barrier-class products where FDA 510(k) clearance and AAMI PB70 certification create defensible pricing tiers.
- Surgical Drapes:SMS laminate constructions achieving AAMI Level 3-4 liquid barrier ratings command premium positioning in cardiac and orthopedic suites. Demand concentrates in United States integrated delivery networks consolidating procurement under sole-source contracts with guaranteed volume floors.
- Face Masks:Spunbond-meltblown-spunbond laminates with bacterial filtration efficiency exceeding 95% dominate institutional procurement. European aesthetic clinics and tattoo parlors are absorbing borderline medical devices under expanded EU MDR Annex XVI scope.
- Sterile Wraps:Polypropylene spunbond fabrics for instrument sterilization maintain stable hospital demand.
- Patient Gowns:Antimicrobial-finished non-wovens serve isolation and examination protocols in long-term care.
The dominant share belongs to Surgical Drapes, while Face Masks is closing the gap fastest.
End User:
Customer-type concentration shows acute care commanding procurement scale, though post-acute migration is redistributing volume growth.
- Hospitals:Sterile processing departments in United States IDNs negotiate direct manufacturer contracts, bypassing traditional distribution. Texas and California health systems anchor national purchasing concentration with multi-year agreements covering barrier-class gowns and compact sterile field kits.
- Home Healthcare:Disposable wound dressings and isolation gowns are expanding in Germany and Japan as skilled nursing facilities discharge patients earlier. Residential settings lack sterilization infrastructure, making single-use products operationally essential.
- Clinics:Outpatient facilities in India's tier-2 cities under Ayushman Bharat medical cities drive first-time sterile disposable adoption.
- Long-term Care Facilities:Infection control protocols sustain steady gown and drape consumption in elderly care settings.
Hospitals retain volume leadership, yet Home Healthcare demonstrates the steepest expansion trajectory among end-user categories.
Material:
Supply-side fiber specialization determines cost structure resilience against propylene feedstock volatility.
- SMS:Spunbond-meltblown-spunbond laminates deliver the bacterial filtration and liquid barrier performance required for surgical applications. European production clusters in Belgium and Germany create geographic concentration risk for barrier-class gown manufacturers during energy price spikes.
- Polypropylene:Dominant feedstock for spunbond and meltblown layers faces margin pressure from US Gulf Coast naphtha-cracker economics.
- Spunbond:Single-layer constructions serve lower-barrier applications in examination gowns and sterile wraps.
- Polyester:Alternative fiber for specialized applications requiring different thermal or chemical resistance profiles.
SMS commands the dominant material share, while biodegradable PLA-PHA blends are gaining share fastest in sustainability-mandated outpatient settings.
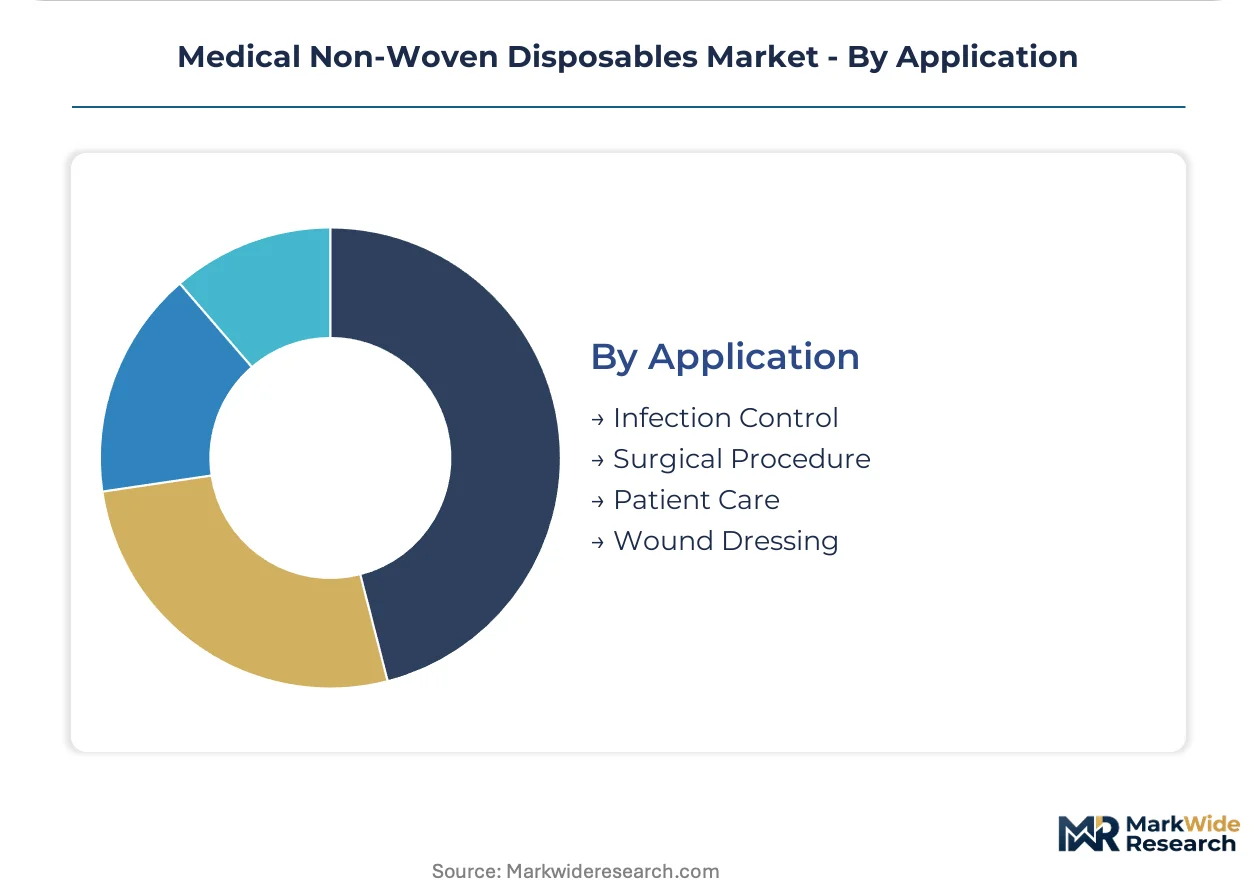
Application:
Use-case segmentation tracks how regulatory scope expansion captures adjacent product categories under clinical evidence requirements.
- Infection Control:Isolation gowns and barrier drapes for hospital-acquired pathogen prevention. EPA antimicrobial claim substantiation enables copper-infused and silver-ion treated substrates to achieve premium positioning in United States surgical suites.
- Surgical Procedure:Sterile field maintenance products governed by FDA 510(k) clearance pathways and EU MDR Article 61 clinical evidence standards. German notified bodies impose stricter biological evaluation plans than under previous Medical Device Directive frameworks.
- Patient Care:General examination and hygiene applications with lower barrier performance requirements.
- Wound Dressing:Post-acute care disposable products expanding in residential settings.
Infection Control holds the dominant application share, while Surgical Procedure is climbing the fastest as MDR scope expansion tightens compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in medical non-woven disposables tilt toward production concentration in fiber-rich economies with established meltblown capacity, while demand gravity shifts toward hospital-consolidated markets with stringent barrier certification requirements. Trade flows reflect this asymmetry: European SMS laminate exports serve United States IDN procurement, while Asian converters supply cost-sensitive clinic segments in emerging economies.
United States
Hospital consolidation into integrated delivery networks concentrates procurement scale under national distribution contracts, elevating FDA 510(k) clearance as a non-negotiable supplier credential. Texas and California health systems anchor multi-year sole-source agreements for barrier-class gowns. Domestic meltblown production clusters along the US Gulf Coast face feedstock volatility from naphtha-cracker economics.
Germany
Notified bodies under EU MDR Article 61 impose stricter biological evaluation plans on barrier-class drapes than previous directive frameworks, extending compliance timelines for converters. SMS production clusters in North Rhine-Westphalia supply laminate substrates across European surgical markets. Freudenberg Performance Materials anchors regional technical textile capacity.
India
Government-funded medical cities under the Ayushman Bharat scheme create first-time sterile disposable demand in tier-2 and tier-3 cities previously served by reusable textiles. CDSCO medical device regulations tighten import substitution incentives for domestic converters. Maharashtra and Gujarat host emerging non-woven fabrication capacity serving hospital infrastructure buildout.
Japan
Post-acute care migration to residential settings drives disposable wound dressing consumption as skilled nursing facilities discharge patients earlier. PMDA biocompatibility requirements align with ISO 10993 standards for novel antimicrobial finishes. Kanto region distribution networks supply home healthcare providers with isolation gowns lacking sterilization infrastructure.
Belgium
European SMS fabric production concentration creates geographic single-source risk for barrier-class gown manufacturers during energy price spikes. REACH chemical restrictions and pending ECHA per- and polyfluoroalkyl substance limits threaten blood-repellent finish obsolescence. Flanders-based laminate producers serve continental surgical drape demand.
Medical Non-Woven Disposables Market Vendor Landscape
Concentration sits with vertically integrated fiber-to-finished-goods producers capable of absorbing regulatory compliance costs that fragment converter competition. Tiered supplier structures separate multinational hygiene conglomerates with captive pulp and meltblown assets from regional converters dependent on spot polymer markets. Strategic archetypes include integrated material-science conglomerates, direct-distribution specialists, and regulatory-affairs-heavy contract manufacturers. Dominant competitive moves encompass backward integration into SMS laminate production and direct contracting with IDN supply chain executives bypassing wholesale channels.
Among North American hygiene conglomerates, Kimberly-Clark Corporation exemplifies the integrated archetype through captive pulp supply and domestic meltblown capacity. Mölnlycke Health Care AB occupies a position within European SMS vertical control, while Medline Industries, LP represents the direct-distribution model negotiating national contracts with United States hospital systems. These three anchors illustrate how barrier certification infrastructure and procurement channel access determine sustainable positioning against commodity converter competition.
| Leading Market Players |
|---|
| Domtar Corporation |
| Medtronic |
| Mölnlycke Health Care AB |
| Kimberly-Clark Corporation |
| Medline Industries, LP |
| Freudenberg Performance Materials |
| Ahlstrom |
| Asahi Kasei Corporation |
| Svenska Cellulosa Aktiebolaget SCA |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways and AAMI PB70 barrier certification tiers simultaneously gate supplier qualification and stratify price positioning across surgical drape and gown categories. United States integrated delivery networks leverage these regulatory thresholds to compress margins on uncertified commodity converters while paying premiums for Level 4 validated laminates.
Pricing Analysis
Configured-to-order pricing for AAMI Level 4 surgical drapes with antimicrobial finishes commands spreads exceeding standard Level 1 examination gown spot pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume commitment scale, with Texas and California IDN sole-source contracts anchoring premium tiers. Cost compression in standard SMS laminates is intensifying because group purchasing organization consolidation limits supplier negotiation leverage. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge protocol cost pressures, while cardiac surgery suites show lowest sensitivity given infection liability exposure.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Rotterdam and Hamburg elevate inbound logistics costs for polypropylene resin shipments. SMS laminate production concentrates in Belgium, Germany, and the United States, with European clusters drawing from Saudi and Qatari propylene feedstock. Raw material dependencies rest on naphtha-cracker economics, meltblown microfiber capacity, and fluorinated blood-repellent chemistries. Single-source vulnerability during energy price spikes threatens barrier-class gown manufacturers dependent on North Rhine-Westphalia substrate supply. Distribution runs through direct manufacturer contracts with hospital sterile processing departments, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates switching costs that lock IDN procurement committees into validated supplier relationships. Certification infrastructure investments function as irreversible commitments that fragment converter competition.
For Market Incumbents: Shield market position by deepening backward integration into captive meltblown capacity along the US Gulf Coast and accelerating EU MDR technical documentation capabilities before notified body backlogs extend. Emerging Indian converters under CDSCO import substitution incentives represent the primary entrant threat. Certification investment in ISO 10993 biocompatibility testing infrastructure serves as the critical defensive lever. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 hospital infrastructure buildout under Ayushman Bharat medical cities, where first-time sterile disposable demand outpaces domestic converter capacity. Biodegradable PLA-PHA non-woven blends for sustainability-mandated European outpatient clinics offer secondary white-space penetration. Direct contracting with Maharashtra and Gujarat state procurement authorities provides the most viable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across SMS laminate production as energy price volatility and fluorinated chemistry obsolescence force redundant capacity investments. Five-to-ten year viability favors vertically integrated fiber-to-finished-goods producers with established regulatory affairs infrastructure. Acquisition targets should display captive pulp or meltblown assets paired with FDA 510(k) predicate device libraries. The signal to watch is EPA per- and polyfluoroalkyl substance restriction timing, which would trigger forced technology transitions and stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Meltblown Capacity | Captive microfiber supply insulates margin structures from propylene feedstock volatility at US Gulf Coast crackers. |
| EU MDR Technical Documentation Investment | Notified body relationships in Germany accelerate barrier-class product clearance timelines under Article 61 pathways. |
| Direct IDN Contracting Bypass | Sole-source agreements with Texas and California health systems displace distributor intermediaries and lock volume floors. |
| Biodegradable Fiber Product Line Development | PLA-PHA composting-certified gowns capture sustainability procurement mandates in European outpatient clinics. |
| Regulatory Affairs Talent Acquisition | FDA 510(k) predicate strategists and EU MDR authors command premium retention packages that fragment mid-tier competition. |
Methodological Framework
A standing panel of sterile processing department managers, GPO contracts directors, biomedical engineers, and SMS laminate production heads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, hospital procurement contract disclosures, and polypropylene trade flow customs data. Bottom-up facility-level capacity assessments triangulated against top-down IDN spending pattern analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning barrier certification tier, end-user facility type, material substrate construction, and regional regulatory cluster. CAGRs derived from procedure volume elasticity analysis and material substitution rate modeling. Forecast inputs incorporated ambulatory surgical center expansion trajectories and EPA fluorinated chemistry restriction scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained hospital consolidation and stable AAMI PB70 certification standards; material deviation would warrant model refresh. Specific risk factors include propylene feedstock price spikes, EU MDR implementation delays, and biodegradable fiber performance certification failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Period Patch Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Sanitary Napkins Machine Market
Medical and Hygiene Textiles
Arm Pouches Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Examination Gowns Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
Antimicrobial Polyamide Textiles Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Absorbent Mats Market