
 Sanitary Napkins Machine Market | 2026-2036
Sanitary Napkins Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Napkins Machine Market Analytics
The premium-commodity split in sanitary napkins machine supply is consolidating around servo-electric precision lines versus mechanical entry-level units. Procter & Gamble leverages its captive engineering standards to specify custom automated lines with integrated quality systems. Kimberly-Clark sustains volume dominance through multi-site standardization of complete-line solutions across its manufacturing footprint. Unicharm differentiates via proprietary pneumatic technology embedded in its regional supply contracts.
Sanitary napkins machines are industrial converting systems that laminate absorbent cores, apply backsheet films, and execute ultrasonic sealing at speeds exceeding 800 pads per minute for high-volume lines. Automated product-type configurations command the dominant margin pool as manufacturers replace semi-automated legacy equipment to meet throughput and hygiene standards. Electric technology segments are gaining fastest among new installations, displacing hydraulic systems where energy efficiency and clean-room compatibility matter. Complete-line solutions anchor capital expenditure patterns, though standalone unit sales persist among mid-tier distributors entering private-label production.
FDA device-quality regulations for US-market feminine hygiene products shape machine validation protocols, while India's BIS standards and PLI scheme for domestic manufacturing redirect procurement toward locally certified equipment suppliers. ISO 13485 medical-device quality frameworks and REACH-compliant material handling specifications further constrain machine design for exporters serving European retail channels. Stakeholders must weigh total cost of ownership against regional certification requirements when selecting between integrated complete-line investments and phased standalone upgrades.
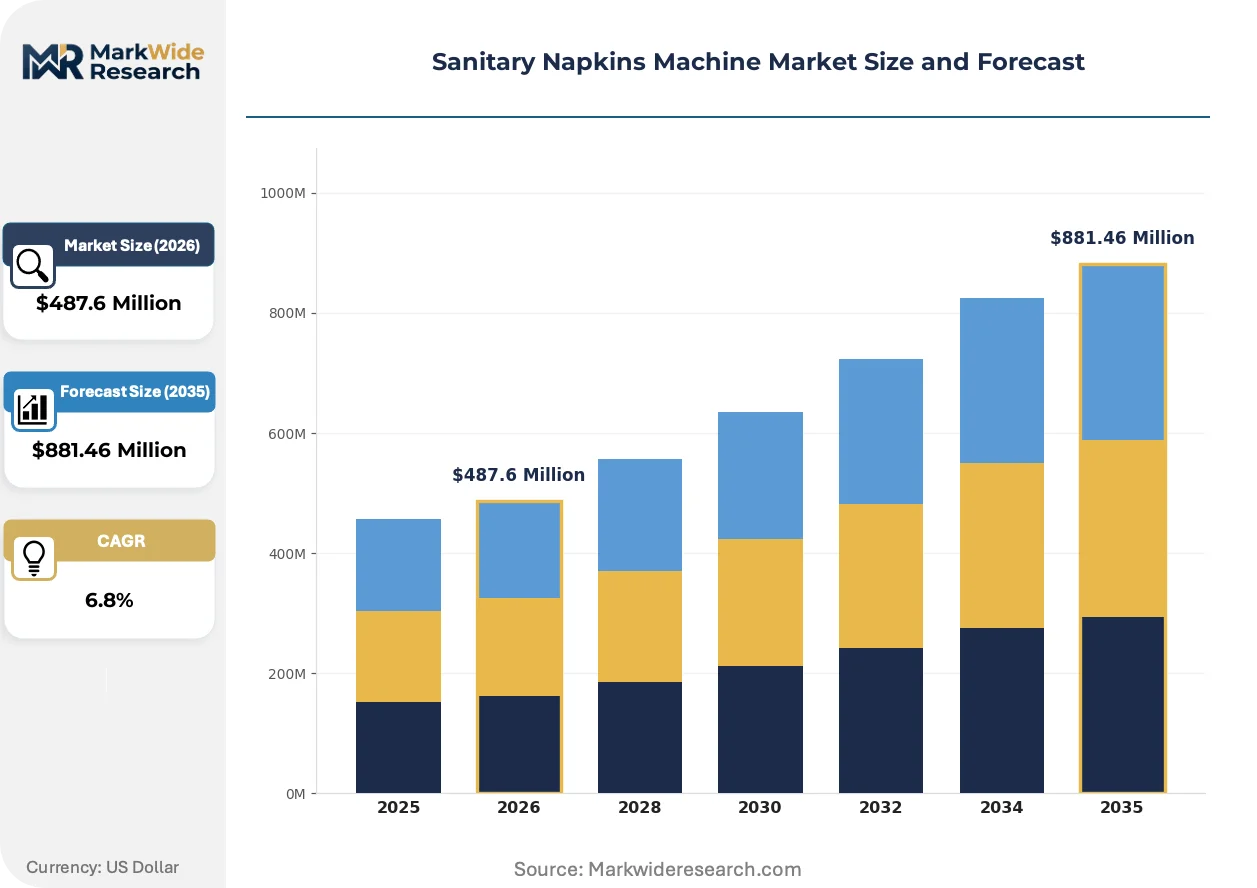
Market Dynamics
Machine procurement decisions across the sanitary napkins converting sector are compressing around India's BIS certification mandates and Vietnam's export-zone clustering, forcing buyers toward automated complete-line investments that satisfy both compliance and throughput requirements simultaneously.
Growth Catalysts
- India's PLI scheme for domestic manufacturing:Production-linked incentives redirect capital toward locally certified equipment suppliers, accelerating automated line adoption among domestic converters seeking subsidy eligibility.
- Servo-electric precision technology:Energy efficiency and clean-room compatibility requirements in high-volume facilities are displacing hydraulic systems across new installations in Southeast Asian industrial zones.
- Contract manufacturing expansion:Private-label brand proliferation in Vietnam's Ho Chi Minh City corridor generates sustained machine procurement from export-oriented suppliers serving regional retail chains.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price fluctuations for precision components compress margin predictability for equipment manufacturers quoting long-delivery complete-line contracts.
- Regional supplier concentration:Core machine engineering capabilities cluster in select European and East Asian manufacturing centers, creating lead-time vulnerability for buyers outside these zones.
- REACH-compliant material handling specifications:European retail channel requirements constrain design flexibility, adding engineering cycle time and certification cost burden for exporters.
Strategic Opportunities
- Indonesia's underpenetrated domestic market:Local absorbent hygiene product manufacturing remains below regional per-capita benchmarks, creating first-mover advantage for equipment suppliers establishing technical service presence.
- ISO 13485 medical-device quality framework convergence:Feminine hygiene products approaching medical-grade standards in select European markets enable premium pricing for validated complete-line solutions.
- Ultrasonic sealing and vision inspection integration:Combined quality assurance technologies reduce downstream rejection rates, opening retrofit service revenue among installed base operators.
Industry Challenges
- Mechatronics technician scarcity:Servo-electric system maintenance and programming expertise concentrates in mature manufacturing economies, complicating operational readiness for buyers in emerging production regions.
- Legacy mechanical line integration complexity:Phased automation upgrades require custom interface engineering between existing semi-automated equipment and new digital control systems, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Napkins Machine Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Semi-Automated, Manual, Custom Technology: Hydraulic, Pneumatic, Electric, Mechanical End User: Manufacturers, Distributors, Retailers, E-Commerce Solution: Complete Line, Standalone Unit, Maintenance Service, Training |
| Companies Covered | Kao Corporation, Johnson & Johnson Services, Procter & Gamble, XY Hygiene, Edgewell Personal Care Company, Kimberly-Clark Corporation, Unicharm Corporation, Nobel Hygiene, Hengan International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Napkins Machine Market Evolving Landscape
Digital control architectures and modular machine configurations are fragmenting traditional complete-line procurement patterns, enabling mid-tier converters to stage capital deployment while maintaining compliance pathway flexibility.
Edge-computing quality monitoring systems with embedded vision inspection are decentralizing quality assurance responsibility from centralized laboratory testing to real-time production-line decision points. Regional contract manufacturers in Vietnam and Thailand are adopting these systems at accelerated pace to satisfy export-market traceability requirements. This technology diffusion is compressing the validation timeline for private-label suppliers seeking retail channel entry.
REACH and RoHS material restrictions in European markets are forcing backsheet film and adhesive suppliers to reformulate product specifications, which cascades into machine sealing-parameter recalibration requirements. Equipment manufacturers serving EU-bound production lines must now engineer broader process windows to accommodate input material variability. Converters with validated lines in Germany and the Netherlands are experiencing extended requalification cycles as material substitutions accelerate.
Buying committees at Southeast Asian contract manufacturers are unbundling after-sales service contracts from initial equipment procurement, treating spare parts inventory and technical training as separately negotiated spend categories. This purchasing behavior fragmentation pressures traditional complete-line vendors to modularize service offerings. The pattern is most pronounced among Vietnam-based suppliers serving Japanese and South Korean retail brand owners with stringent uptime guarantees.
Sanitary Napkins Machine Market Segmentation
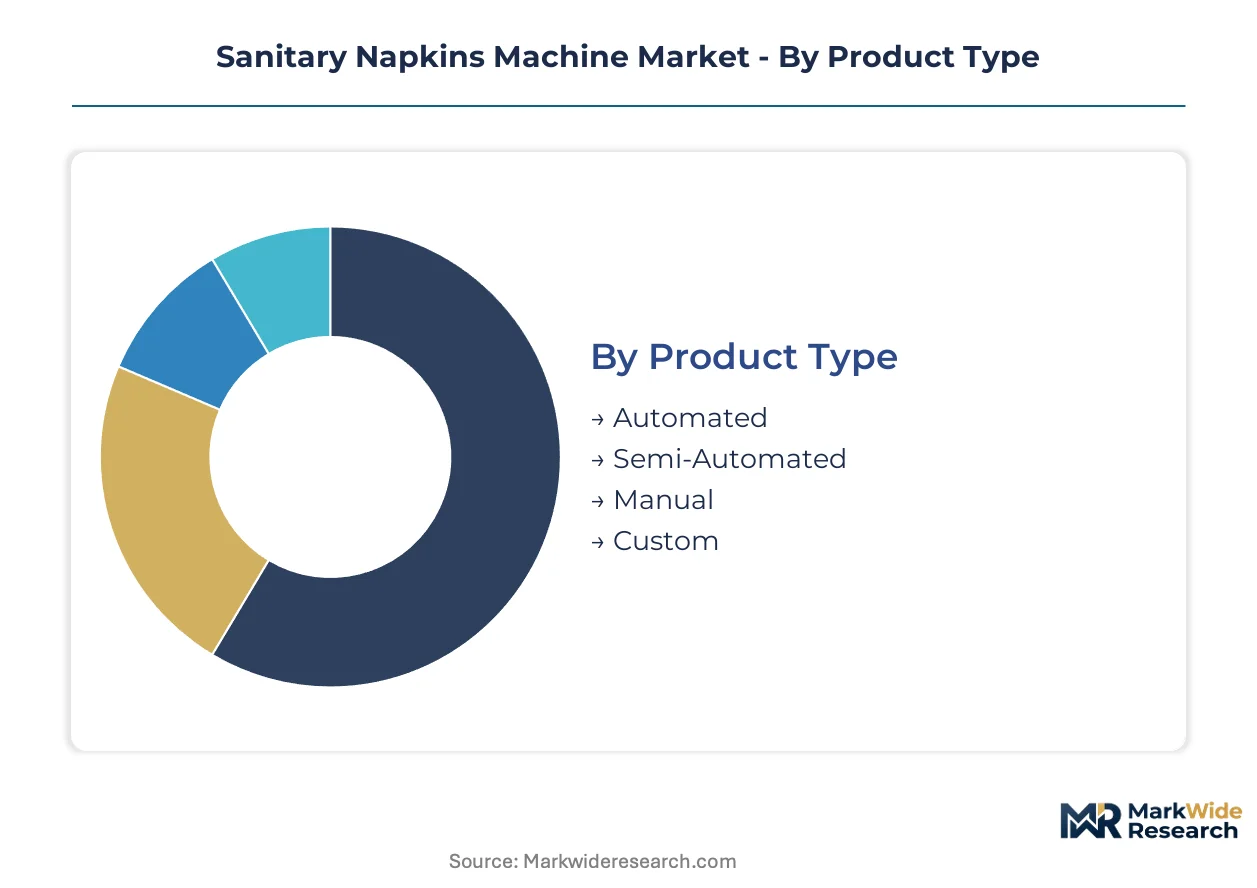
Machine segmentation in sanitary napkins converting reflects divergent capital deployment strategies across emerging and mature production economies. Buyers weigh throughput requirements against certification complexity when selecting between integrated systems and modular upgrades.
Product Type:
Volume lines dominate procurement in Vietnam's export corridors while premium precision equipment anchors India's PLI-subsidized domestic capacity expansion.
- Automated:Servo-electric control architectures execute core lamination, ultrasonic sealing, and vision inspection at speeds exceeding 800 pads per minute. Demand concentrates in Ho Chi Minh City industrial zones where export-oriented contract manufacturers serve Japanese and South Korean retail brand owners with stringent uptime guarantees.
- Semi-Automated:Hybrid configurations retain mechanical core-forming stations while adding digital control layers for backsheet application and final packaging. India's BIS-certified domestic converters favor these systems for phased automation that preserves subsidy eligibility without full capital commitment.
- Manual:Entry-level units with minimal electromechanical integration serve micro-enterprises and pilot production facilities testing regional market receptivity.
- Custom:Engineer-to-order lines incorporate proprietary pneumatic technology and integrated quality systems specified by captive manufacturing operations of multinational hygiene product companies.
Today's leader: Automated. Tomorrow's challenger: Semi-Automated.
Technology:
Energy efficiency mandates and clean-room compatibility requirements are accelerating displacement timelines for legacy hydraulic systems across Southeast Asian installations.
- Electric:Servo motor precision enables sub-millimeter web tension control and real-time parameter adjustment for varying absorbent core densities. New procurement in Thailand's medical-grade hygiene facilities favors electric systems for REACH-compliant material handling and reduced contamination risk.
- Hydraulic:High-force core compression and embossing stations persist in established mechanical lines where capital replacement cycles extend beyond typical depreciation schedules.
- Pneumatic:Proprietary air-pressure systems differentiate regional supply contracts through embedded intellectual property in sealing and cutting modules.
- Mechanical:Gear-driven kinematics with fixed speed ratios anchor entry-level equipment serving price-sensitive private-label entrants in Indonesia's underpenetrated domestic market.
Electric systems are climbing the fastest in new order books. Mechanical retains installed-base dominance.
End User:
Procurement authority fragmentation separates capital equipment decisions from consumables purchasing across Southeast Asian contract manufacturing networks.
- Manufacturers:Integrated hygiene product companies and toll converters drive complete-line investments with integrated quality validation for FDA-regulated export production.
- Distributors:Equipment trading houses in regional supply hubs facilitate standalone unit sales to mid-tier entrants lacking direct supplier relationships with European or East Asian engineering centers.
- Retailers:Private-label program managers at regional retail chains increasingly specify machine validation protocols as a condition of supplier qualification.
- E-Commerce:Direct-to-consumer brand operators with outsourced manufacturing relationships exert indirect pressure through quality audit requirements rather than direct equipment procurement.
Manufacturers command capital expenditure volume. Distributors mediate market access for fragmented demand.
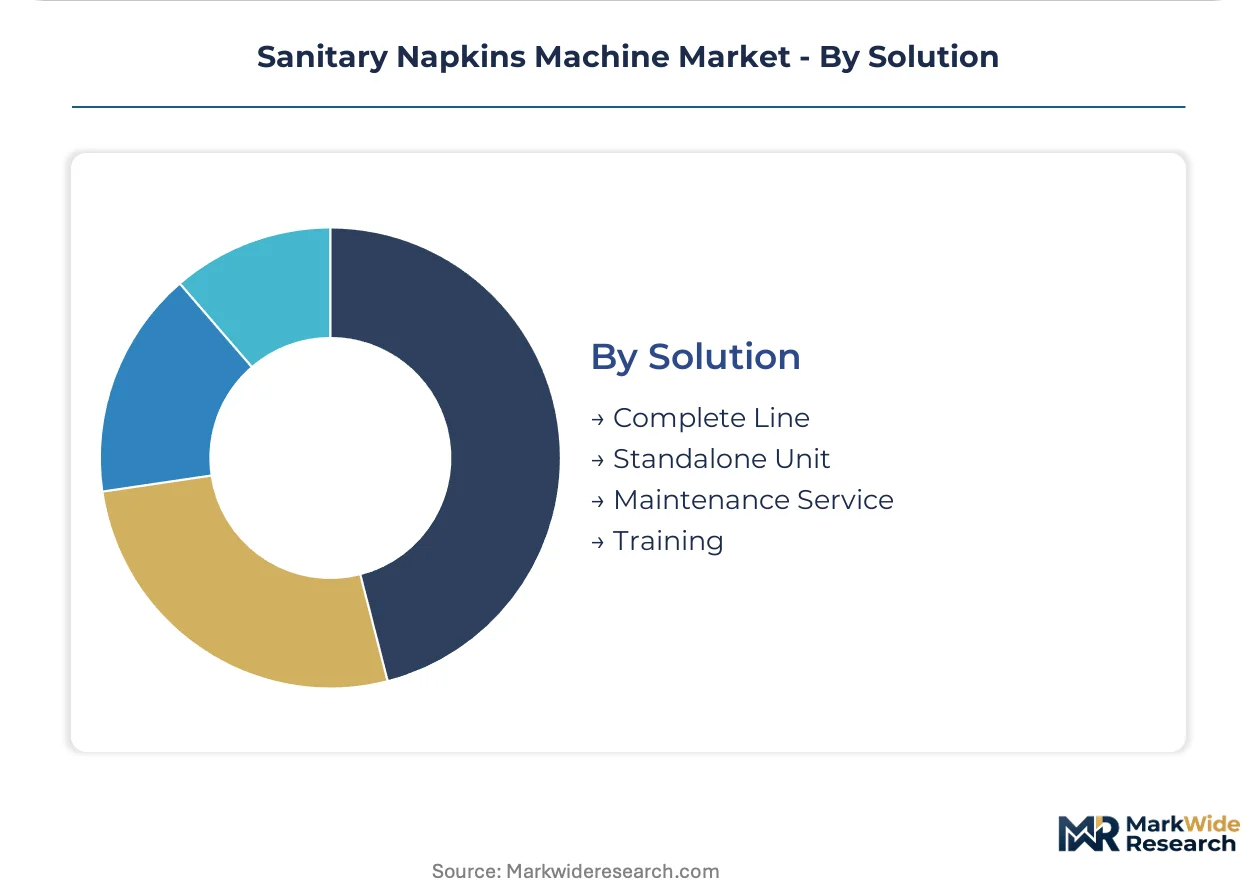
Solution:
Service unbundling among Vietnam-based buying committees is fragmenting traditional complete-line vendor relationships into separately negotiated spend categories.
- Complete Line:Integrated turnkey systems with centralized digital control architectures span raw material unwinding through finished product palletization. These anchor capital deployment for India's PLI scheme beneficiaries seeking automated compliance with BIS certification mandates.
- Standalone Unit:Modular core-forming, backsheet laminating, or packaging stations enable phased upgrades that preserve legacy mechanical asset value while adding targeted automation.
- Maintenance Service:After-sales contracts covering preventive scheduling, spare parts inventory, and emergency response are now separately negotiated from initial equipment procurement.
- Training:Technical education for mechatronics programming and servo system troubleshooting addresses scarcity of qualified technicians in emerging production regions.
Complete Line captures premium margin pools. Maintenance Service represents the steepest expansion trajectory as installed base scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics technician pools in Germany and servo motor engineering clusters in Japan anchor the machinery supply base for sanitary napkins converting equipment. These talent concentrations shape regional competitive positioning across equipment sourcing networks.
India
Domestic converter demand concentrates around BIS certification mandates and PLI scheme subsidy eligibility. The country's national standards body requires automated quality validation systems for feminine hygiene product manufacturing. Gujarat and Maharashtra industrial corridors host the fastest equipment procurement as domestic brands expand capacity.
Vietnam
Export-oriented contract manufacturers drive complete-line investments near Ho Chi Minh City. Japanese and South Korean retail brand owners impose stringent uptime guarantees on suppliers. Binh Duong and Dong Nai provinces cluster precision converting operations serving regional retail chains.
Germany
REACH-compliant material handling specifications and ISO 13485 medical-device frameworks shape machine design for EU-bound production. ECHA chemical restrictions force broader process windows in sealing-parameter engineering. Baden-Württemberg and Bavaria host precision component fabricators supplying ultrasonic sealing modules.
China
Dual carbon goals and MIIT energy efficiency standards accelerate electric system displacement of hydraulic installations. GB standards for industrial machinery quality constrain export equipment configurations. Yangtze River Delta manufacturing bases supply servo motor precision components to Southeast Asian converters.
United States
FDA device-quality regulations for feminine hygiene products mandate validated machine protocols for domestic market entry. EPA energy efficiency guidelines influence clean-room compatible equipment specifications. Midwest industrial zones maintain legacy mechanical line installed bases requiring phased automation retrofit services.
Sanitary Napkins Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sanitary napkins machine supply structure. European and East Asian engineering centers concentrate core machine fabrication capabilities, creating tiered supply relationships with regional distributors. Three archetypes dominate: integrated complete-line turnkey providers, modular standalone unit specialists, and aftermarket service operators. Competitive moves center on geographic expansion through technical service partnerships and portfolio diversification into adjacent hygiene product converting equipment.
Among Asia-Pacific-based fabricators, Hengan International Group and Nobel Hygiene occupy positions within the contract manufacturing tier, while Kao Corporation exemplifies the integrated brand-owner archetype with captive engineering specifications. These companies represent distinct strategic postures toward equipment procurement authority, with some maintaining direct supplier relationships and others routing capital decisions through distributor networks.
| Leading Market Players |
|---|
| Kao Corporation |
| Johnson & Johnson Services |
| Procter & Gamble |
| XY Hygiene |
| Edgewell Personal Care Company |
| Kimberly-Clark Corporation |
| Unicharm Corporation |
| Nobel Hygiene |
| Hengan International Group |
| Others |
Value Network & Pricing Analysis
India's PLI scheme beneficiaries concentrate procurement authority around complete-line vendors offering bundled validation services, compressing price negotiation leverage for equipment suppliers competing on specification compliance rather than standalone unit economics.
Pricing Analysis
Service unbundling among Vietnam-based buying committees fragments traditional complete-line pricing into separately negotiated equipment, spare parts inventory, and technical training contracts. Price differentiation hinges on BIS certification tier and integrated quality system complexity, with entry-level mechanical units facing margin compression from servo-electric displacement. Cost volatility in stainless steel and servo motor inputs intensifies pricing pressure on long-delivery contracts. Small-scale Indonesian entrants exhibit highest price sensitivity, while Japanese retail brand owners prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Precision servo motor engineering draws from manufacturing clusters in Japan and Germany, while ultrasonic sealing module fabrication centers on Baden-Württemberg component specialists. Stainless steel feedstock and pneumatic control systems feed from Yangtze River Delta suppliers serving Southeast Asian assembly operations. Single-source vulnerability concentrates in specialized mechatronics technician training programs anchored in mature manufacturing economies. Distribution runs through regional equipment trading houses in Ho Chi Minh City and Bangkok that mediate access for mid-tier converters lacking direct European or East Asian supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification mandate for feminine hygiene products functions as a regulatory compounder, accelerating capital redeployment toward automated validation systems as domestic converters pursue subsidy eligibility.
For Market Incumbents: Lock in service contract fragmentation by modularizing aftermarket offerings to match Vietnam's unbundled procurement patterns. Deepen technical training partnerships with Indian engineering institutes to address mechatronics technician scarcity threatening operational readiness. Prioritize backward integration into servo motor supply chains to buffer stainless steel cost volatility compressing long-delivery contract margins.
For New Entrants and Emerging Players: Launch via standalone unit distribution partnerships targeting Indonesia's underpenetrated domestic market, where absorbent hygiene product manufacturing remains below regional per-capita benchmarks. Prioritize phased automation configurations that preserve legacy mechanical asset value while adding digital control layers, matching India's BIS-certified converter preference for subsidy-eligible capital staging.
For Investors and Strategic Acquirers: Integrated hygiene product companies with captive engineering specifications represent the most active acquirer category in this space, seeking regional contract manufacturing capacity to secure supply chain control. Target equipment suppliers with validated ISO 13485 frameworks serving European medical-grade hygiene channels. Monitor REACH-compliant material handling specification acceleration as the inflection signal for premium pricing capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Supply | Mitigates input cost volatility from Japanese and German precision component suppliers. |
| ISO 13485 Medical-Device Certification Pathway | Unlocks premium pricing in European markets approaching medical-grade hygiene standards. |
| Technical Training Partnership with Indian Institutes | Addresses mechatronics technician scarcity constraining operational readiness in emerging regions. |
| Phased Automation Configuration Development | Matches India's PLI-subsidized converter preference for staged capital deployment. |
| REACH-Compliant Material Handling Engineering | Satisfies ECHA chemical restrictions forcing broader process windows in EU-bound production lines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at Vietnam's Ho Chi Minh City industrial zones, OEM procurement teams at Indian domestic converters, and aftermarket service heads at European equipment fabricators with secondary validation against BIS certification databases, MIIT energy efficiency disclosures, and customs trade records for servo motor imports. Bottom-up equipment procurement tallies triangulated against top-down capital expenditure estimates across the analysis window.
Segment-weighting approaches distributed value and volume projections across automated, semi-automated, manual, and custom product types; electric, hydraulic, pneumatic, and mechanical technologies; and complete-line, standalone unit, maintenance service, and training solution categories. CAGRs derived from equipment replacement cycle analysis, PLI scheme subsidy uptake trajectories, and export-zone capacity expansion patterns in Vietnam's Binh Duong and Dong Nai provinces.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material cost volatility and regulatory timeline acceleration. Assumptions reflect BIS certification enforcement intensity and REACH reformulation cascade effects. A small set of triggers—servo motor supply disruption, India's PLI scheme modification, and ECHA chemical restriction expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Medical Non-Woven Disposables Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Breast Pads Market
Medical and Hygiene Textiles
Sleeping Masks Market
Medical and Hygiene Textiles
North America Sanitary Napkin Market
Medical and Hygiene Textiles
Foot Mask Market
Medical and Hygiene Textiles
Absorbent Mats Market
Medical and Hygiene Textiles
Pant Type Adult Diaper Market
Medical and Hygiene Textiles
Antibacterial Washcloth Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Global Diabetic Socks Market
Medical and Hygiene Textiles
Intestinal Wash Bags Market
Medical and Hygiene Textiles
Medical Textiles Market
Medical and Hygiene Textiles
Medical Smart Textile Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Period Panties Market