
 GCC Sanitary Napkin Market | 2026-2036
GCC Sanitary Napkin Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Sanitary Napkin Market Intelligence
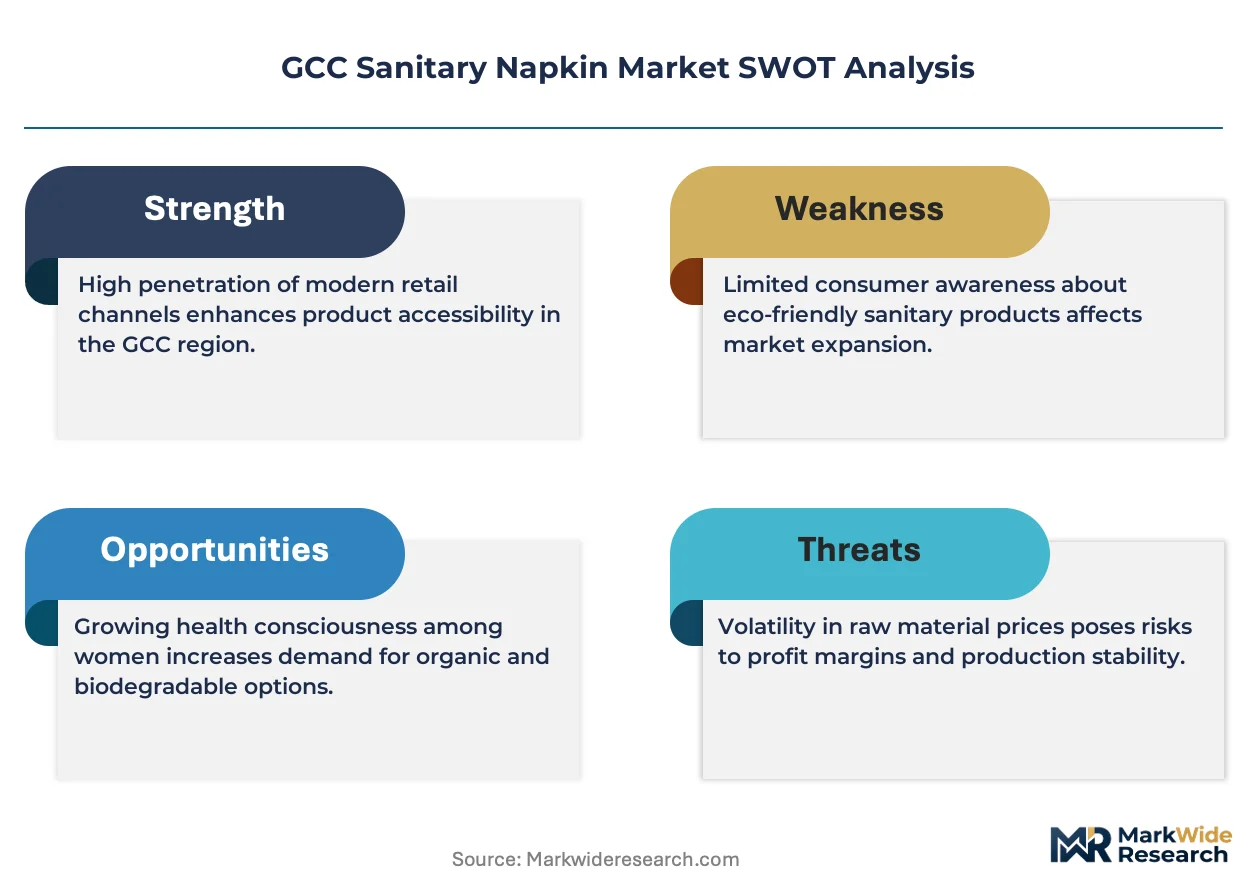
Asset-light distribution franchising is narrowing the capital barrier for regional entrants in the GCC sanitary napkin space. Procter & Gamble Co leverages its multinational logistics infrastructure to sustain shelf dominance across Saudi hypermarkets. Essity AB anchors its regional presence through localized production partnerships that reduce import dependency. Nuqul Group competes by controlling private-label manufacturing capacity serving pharmacy chains across Jordan and the Gulf.
Sanitary napkins are absorbent disposable products constructed with layered nonwoven topsheets, cellulose pulp cores, and polyethylene backsheet films designed to manage menstrual flow with containment and skin dryness. Overnight variants command premium positioning due to extended-wear engineering with reinforced core density and wider rear coverage. Biodegradable material formulations represent the fastest-growing segment as Gulf retailers respond to consumer scrutiny of plastic waste. Cotton-based products maintain stable volume through pharmacy channels where dermatological sensitivity claims support margin retention.
SFDA mandates product registration and ingredient disclosure for all feminine hygiene items sold in Saudi Arabia, creating compliance cost asymmetry between established multinationals and new entrants. Emirates Authority for Standardization and Metrology (ESMA) enforces UAE-specific labeling and absorbency testing protocols that diverge from Saudi requirements. Gulf Cooperation Council customs union harmonization remains incomplete, forcing manufacturers to maintain parallel certification pathways. Stakeholders must monitor which Gulf regulator moves first on biodegradable material standards, as that jurisdiction will likely shape procurement specifications across the trade bloc.
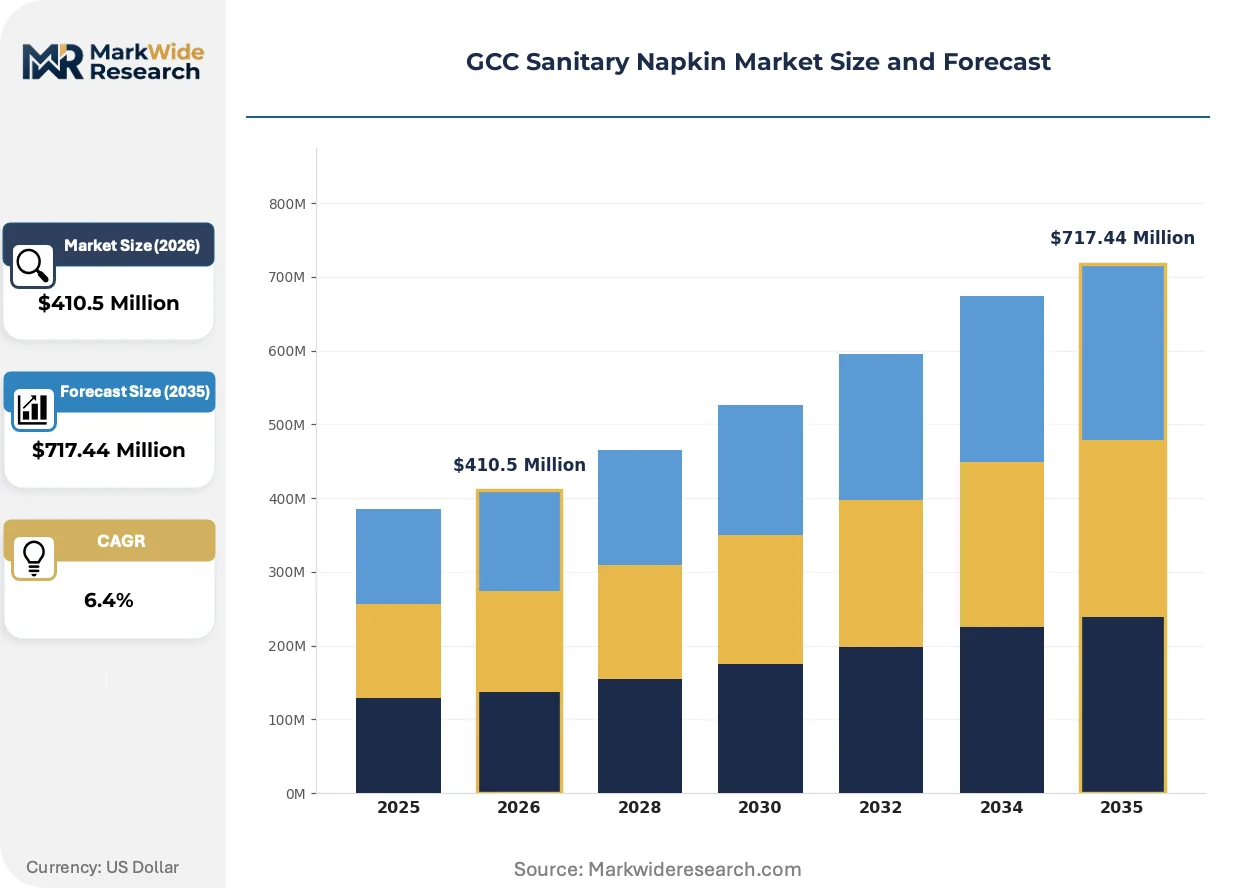
Market Dynamics
Retail modernization across Saudi Arabia and the UAE is compressing traditional wholesale channels while pharmacy network expansion creates parallel distribution density that rewards scale players over regional traders.
Growth Catalysts
- SFDA Registration Mandates:Tightened ingredient disclosure requirements for feminine hygiene products elevate compliance costs that filter out informal importers, consolidating shelf access for certified manufacturers.
- Biodegradable Material Innovation:Cellulose-based core replacements and compostable backsheet films respond to municipal waste diversion targets in Dubai and Riyadh, opening premium positioning for certified sustainable formulations.
- Urban Pharmacy Density:Saudi Arabia's retail pharmacy count expansion concentrates point-of-sale access in high-footfall locations where impulse purchasing and pharmacist recommendation drive brand switching.
Market Restraints
- Import Dependency for Superabsorbent Polymers:GCC manufacturers rely on Asian petrochemical suppliers for SAP feedstock, exposing margin compression when freight rates spike or currency hedges fail.
- Parallel Certification Pathways:ESMA absorbency testing protocols in the UAE diverge from SFDA requirements in Saudi Arabia, forcing dual laboratory submissions that extend product launch timelines by four to six months.
- Reusable Menstrual Product Substitution:Menstrual cups and period underwear gain trial among environmentally conscious consumers in Dubai and Jeddah, particularly in fitness and wellness communities.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:These smaller GCC states maintain lower modern retail saturation, creating first-mover advantage for brands establishing direct pharmacy partnerships before multinational shelf dominance solidifies.
- Subscription Channel Development:Direct-to-home delivery models bypass retail slotting fees while capturing recurring revenue from working women in Riyadh and Doha who prioritize convenience over in-store browsing.
- Organic Cotton Certification Tailwinds:GOTS and OEKO-TEX standards gain retailer procurement preference in UAE hypermarkets, rewarding early certification investments with private-label manufacturing contracts.
Industry Challenges
- Biodegradability Testing Capacity Bottlenecks:Gulf laboratories certified for industrial composting validation remain scarce, delaying product claims for brands pursuing environmental differentiation.
- Cross-Border Inventory Reconciliation:GCC customs union harmonization gaps force manufacturers to maintain separate stock-keeping units for Saudi and UAE markets, complicating demand forecasting and obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Sanitary Napkin Market |
| Market Size in 2026 | $410.5 Million |
| Market Size in 2035 | $717.44 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Panty Liners, Overnight, Super Absorbent Material: Cotton, Plastic, Biodegradable, Synthetic End User: Consumers, Retailers, Distributors, Healthcare Providers Distribution Channel: Supermarkets, E-commerce, Pharmacies, Convenience Stores |
| Companies Covered | Kenvue Inc., Essity AB, Procter & Gamble Co, Johnson & Johnson Inc., Nuqul Group, Indevco Group, Unicharm Corp., SCA Group, Kimberly-Clark Corp., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Sanitary Napkin Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory disclosure mandates are restructuring how sanitary napkins are formulated, certified, and merchandised across Gulf retail environments.
Plant-based absorbent cores derived from agricultural waste streams are collapsing the cost premium between conventional petroleum-derived superabsorbent polymers and bio-alternatives. Saudi manufacturers with captive pulp processing partnerships now source date palm fiber and wheat straw cellulose at scale, enabling price parity with synthetic equivalents. This collapse is eroding the traditional sustainability tax that limited biodegradable products to niche pharmacy positioning.
SFDA's expanded ingredient transparency requirements now mandate full component disclosure on outer packaging, including adhesive and fragrance formulations previously treated as proprietary. Manufacturers must reformulate or license alternative chemistries to avoid competitor scrutiny of legacy compositions. Overnight and ultra-thin segments face the steepest compliance costs due to complex multi-layer construction and fragrance masking requirements.
Young adult women in urban Saudi Arabia and the UAE now research product certifications through mobile channels before in-store purchase, compressing the decision window at physical shelves. Pharmacy staff training programs in Riyadh and Dubai now emphasize digital verification of dermatological claims, replacing traditional sampling as the primary conversion tool. This behavioral pivot privileges brands with searchable certification databases over those relying on packaging aesthetics alone.
GCC Sanitary Napkin Market Segmentation
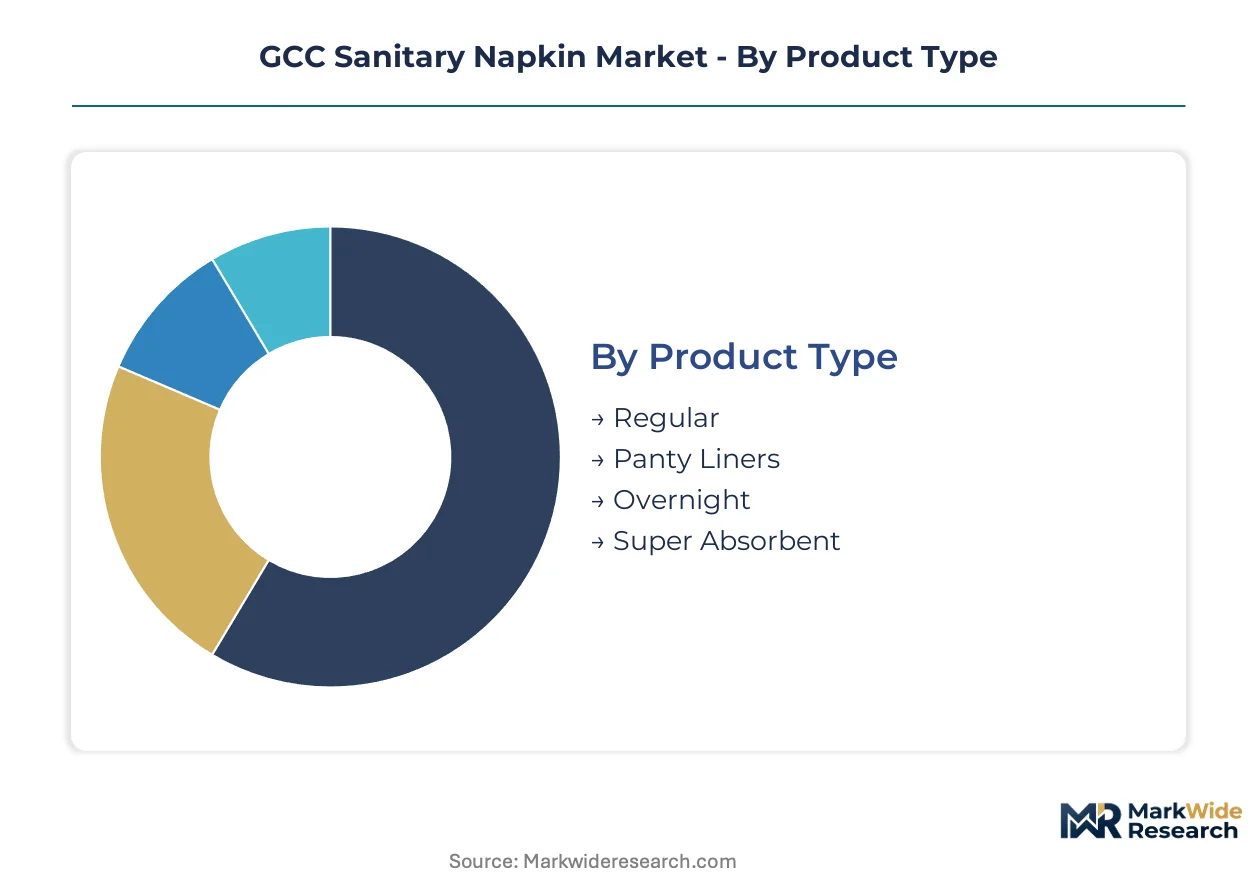
Segmentation in the GCC sanitary napkin market reveals how product specifications, material preferences, and channel access interact with regulatory frameworks across Saudi Arabia and the UAE. Understanding these divisions exposes where compliance costs concentrate and which formulations command shelf priority in modernizing retail environments.
Product Type:
Mature variants dominate pharmacy shelf space while emerging formats capture trial-driven switching behavior among urban young adults.
- Regular:Standard daytime absorbency with cellulose pulp cores and nonwoven topsheets. Pharmacy chains in Riyadh and Jeddah move the highest volumes of this baseline format where price sensitivity among mass-market consumers sustains private-label competition.
- Overnight:Extended-wear engineering incorporates reinforced core density, wider rear coverage, and enhanced polyethylene backsheet containment. Young adult women in urban Saudi Arabia drive premium positioning here as sleep security claims justify price elevation above standard tiers.
- Panty Liners:Ultra-thin daily protection with minimal absorbency for non-menstrual discharge management.
- Super Absorbent:High-capacity variants incorporating elevated superabsorbent polymer loading for heavy flow management.
Regular variants retain volume leadership; Overnight holds the steepest expansion curve.
Material:
Cost tier stratification separates petroleum-derived synthetics from agricultural fiber alternatives as biodegradable certification gains procurement weight in UAE hypermarkets.
- Biodegradable:Compostable backsheet films and cellulose-based core replacements derived from date palm fiber and wheat straw agricultural waste. Dubai and Riyadh municipal waste diversion targets accelerate retailer preference for certified sustainable formulations that reduce landfill burden.
- Cotton:Natural fiber topsheets and absorbent layers marketed for dermatological sensitivity. Pharmacy channels across Saudi Arabia maintain stable cotton volumes where pharmacist recommendations support margin retention against synthetic alternatives.
- Plastic:Conventional polyethylene backsheet and polypropylene nonwoven construction.
- Synthetic:Petroleum-derived superabsorbent polymer cores with standard nonwoven layers.
Synthetic materials retain volume leadership; Biodegradable climbs the fastest as certification costs compress.
End User:
Customer type concentration varies sharply between direct consumption and institutional procurement channels with divergent compliance documentation requirements.
- Consumers:Individual purchasers making brand decisions through mobile research of SFDA registration status and certification databases before in-store conversion.
- Retailers:Hypermarket and pharmacy buyers negotiating slotting fees and private-label manufacturing contracts based on GOTS and OEKO-TEX certification status.
- Distributors:Regional logistics operators managing parallel inventory for Saudi and UAE markets due to incomplete GCC customs union harmonization.
- Healthcare Providers:Hospital and clinic procurement departments sourcing institutional quantities with mandatory ingredient disclosure compliance.
Consumer direct purchasing retains volume leadership; Retailer private-label partnerships hold the steepest expansion curve.
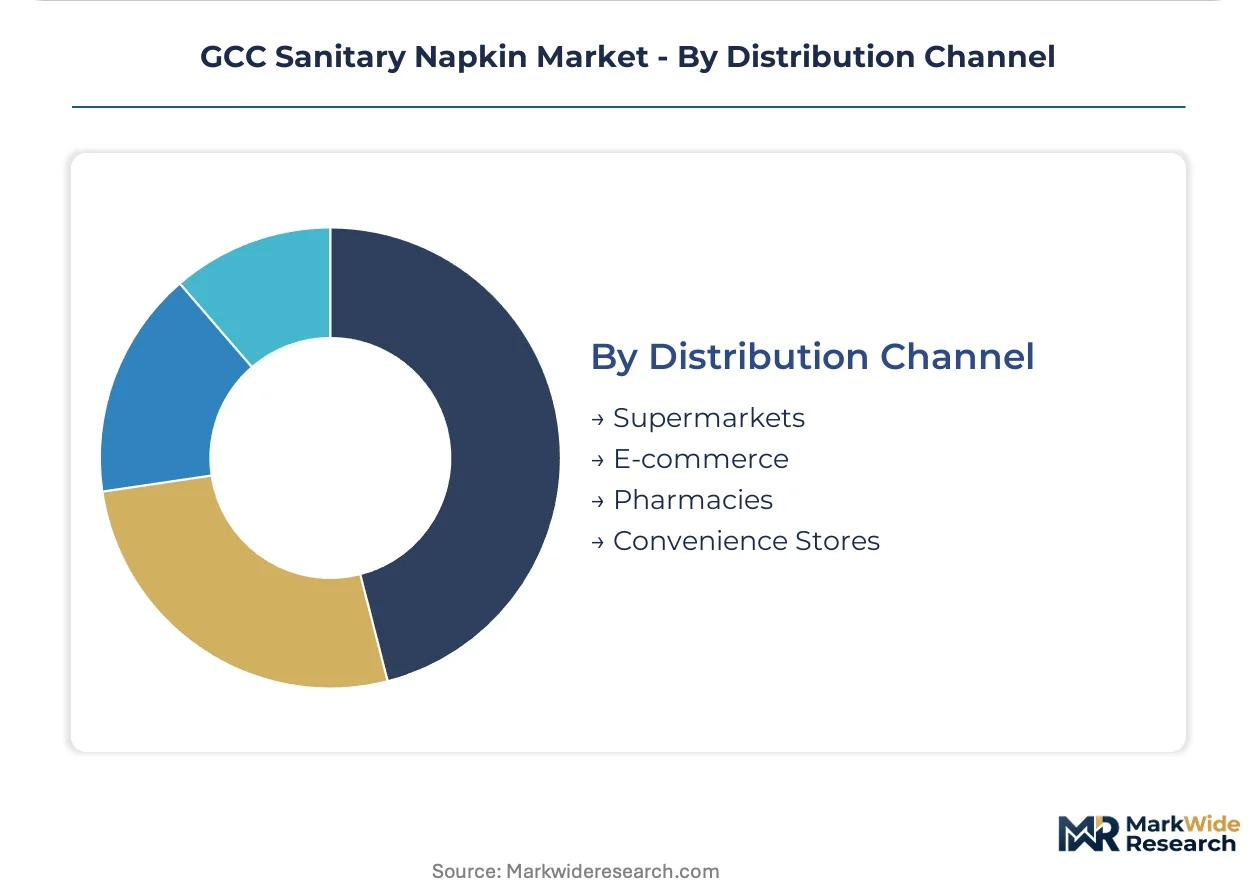
Distribution Channel:
Channel geography determines whether brands face slotting fee pressure in concentrated modern retail or capture recurring revenue through direct subscription models.
- Pharmacies:High-footfall locations in Riyadh and Dubai where pharmacist recommendation drives brand switching and impulse purchasing.
- E-commerce:Direct-to-home subscription models bypassing retail slotting fees while capturing recurring revenue from working women prioritizing convenience.
- Supermarkets:Saudi hypermarket chains where Procter & Gamble maintains shelf dominance through multinational logistics infrastructure.
- Convenience Stores:Emergency purchase locations with limited SKU depth and premium pricing on standard formats.
Pharmacy networks retain volume leadership; E-commerce subscription channels gain share fastest among urban professional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GCC sanitary napkin trade flows reveal a structural import dependency, with finished goods entering from Asian manufacturing hubs while raw material sourcing concentrates in Saudi Arabia's petrochemical corridor. Domestic production capacity expansion in Riyadh and Jeddah is narrowing this gap, though superabsorbent polymer feedstock remains externally sourced.
Saudi Arabia
Pharmacy network densification in Riyadh and Jeddah drives point-of-sale access expansion, with retail pharmacy counts growing fastest in high-footfall urban zones. SFDA registration mandates for feminine hygiene products enforce ingredient disclosure requirements that elevate compliance costs for imported brands. The Eastern Province industrial corridor hosts captive pulp processing partnerships sourcing date palm fiber for biodegradable core production.
United Arab Emirates
Dubai's municipal waste diversion targets accelerate retailer procurement preference for certified compostable formulations across hypermarket chains. ESMA absorbency testing protocols diverge from Saudi requirements, forcing parallel laboratory submissions that extend product launch timelines. Abu Dhabi's healthcare procurement departments source institutional quantities with mandatory full component disclosure compliance.
Kuwait
Modern retail saturation lags Saudi and UAE benchmarks, creating first-mover positioning for brands establishing direct pharmacy partnerships before multinational shelf dominance solidifies. The country's national pharmaceutical regulator maintains alignment with GCC customs union standards while retaining country-specific labeling requirements. Kuwait City retail clusters concentrate distribution infrastructure for cross-border re-export to smaller Gulf states.
Bahrain
Working women in Manama's financial district drive trial of direct-to-home subscription models bypassing traditional retail slotting fees. The national standards body enforces hygiene product labeling harmonized with Saudi SFDA frameworks to facilitate intra-GCC trade. Muharraq's logistics hubs serve as consolidation points for inventory destined to Saudi Arabia's Eastern Province.
Qatar
Doha's wellness communities generate trial demand for reusable menstrual product alternatives among environmentally conscious consumer segments. The Ministry of Public Health mandates product registration with ingredient documentation requirements mirroring UAE ESMA protocols. Lusail's planned retail districts attract pharmacy chain expansion targeting young adult professional women.
GCC Sanitary Napkin Market Key Industry Players
On the supply side, the industry is consolidating around multinational hygiene conglomerates with captive logistics infrastructure, while regional private-label manufacturers capture pharmacy channel share through localized production partnerships. Three strategic archetypes dominate: multinational brand owners with hypermarket shelf dominance, regional manufacturing specialists controlling private-label capacity, and biodegradable material innovators pursuing certification-driven premium positioning. Competitive moves concentrate on strategic partnerships with pulp processors and portfolio diversification into compostable formulations.
Among multinational brand owners, Procter & Gamble Co and Essity AB occupy positions exemplifying scale-driven distribution leverage across Saudi hypermarket networks. Kenvue Inc. and Kimberly-Clark Corp. represent the dermatological sensitivity positioning archetype, with pharmacy channel anchoring through clinician recommendation programs. Nuqul Group and Indevco Group exemplify regional private-label manufacturing specialists, controlling captive production capacity serving pharmacy chains across Jordan and Gulf markets.
| Leading Market Players |
|---|
| Kenvue Inc. |
| Essity AB |
| Procter & Gamble Co |
| Johnson & Johnson Inc. |
| Nuqul Group |
| Indevco Group |
| Unicharm Corp. |
| SCA Group |
| Kimberly-Clark Corp. |
| Others |
Cost & Logistics Intelligence
Asian petrochemical suppliers for superabsorbent polymer feedstock anchor margin compression risk for GCC manufacturers, concentrating pricing power upstream while downstream shelf fees and certification costs erode profitability at brand level.
Pricing Analysis
Pharmacy chain buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Saudi Arabia and the UAE. Price differentiation separates GOTS-certified organic cotton formulations from conventional synthetic tiers, with overnight variants commanding elevation due to extended-wear engineering complexity. Pricing pressure stems from parallel SFDA and ESMA certification costs that extend product launch timelines. Mass-market consumers in Riyadh pharmacy channels exhibit highest price sensitivity, while young adult professionals in Dubai demonstrate lowest sensitivity to premium positioning for biodegradable claims.
Supply Chain Analysis
Contract manufacturing concentration rests with Nuqul Group and Indevco Group facilities across Jordan and Gulf markets, supplemented by multinational captive plants in Saudi Arabia's Eastern Province. Geographic supply concentration centers on China and South Korea for superabsorbent polymer feedstock, with India emerging as alternative cellulose pulp sourcing. Raw material dependencies include petroleum-derived SAP cores, polyethylene backsheet films, and agricultural waste cellulose from date palm fiber processing. Single-source vulnerability for SAP imports exposes margin compression when freight rates spike. Distribution runs through pharmacy network densification in urban Saudi Arabia and subscription direct-to-home models in Doha and Manama.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable material certification tailwinds and pharmacy network expansion signal early-cycle expansion, with municipal waste diversion targets in Dubai and Riyadh accelerating retailer procurement preference for sustainable formulations.
For Market Incumbents: Build certification moats through early GOTS and OEKO-TEX investment that locks in private-label manufacturing contracts with UAE hypermarket buyers. Anchor defensive positioning by deepening captive pulp processing partnerships for date palm fiber sourcing in Saudi Arabia's Eastern Province, neutralizing import dependency for Asian SAP feedstock. Counter reusable menstrual product substitution threat among Dubai wellness communities through dermatological sensitivity claims supported by searchable certification databases. For New Entrants and Emerging Players: Kuwait and Bahrain pharmacy channels represent the most penetrable entry point before multinational shelf dominance solidifies in underpenetrated modern retail environments. Target direct pharmacy partnerships in Kuwait City retail clusters with GOTS-certified organic cotton positioning that commands procurement preference. Bypass slotting fee barriers through subscription channel development capturing recurring revenue from working women in Manama's financial district. For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional private-label manufacturing specialists controlling captive production capacity serving cross-border pharmacy chains. Five-to-ten year viability hinges on biodegradable material innovation capability and SFDA registration compliance infrastructure. Monitor which Gulf regulator moves first on industrial composting validation standards as signal for procurement specification shaping across the trade bloc.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Investment | Early GOTS and OEKO-TEX certification secures private-label contracts with UAE hypermarket procurement teams. |
| Captive Pulp Processing Partnership | Date palm fiber sourcing agreements in Saudi Arabia's Eastern Province reduce SAP import dependency exposure. |
| Pharmacy Network Direct Partnership | First-mover positioning in Kuwait and Bahrain bypasses multinational slotting fee dominance in modern retail. |
| Subscription Channel Development | Direct-to-home models capture recurring revenue from working women in Doha and Manama prioritizing convenience. |
| SFDA Registration Compliance Buildout | Ingredient disclosure infrastructure creates competitive asymmetry filtering informal importers from pharmacy shelves. |
Research Approach
A spread of perspectives from brand managers at multinational hygiene conglomerates, pharmacy chain procurement directors, SFDA regulatory affairs specialists, and biodegradable material R&D leads converged on the working assumptions. Primary interview insights combined with secondary validation from customs and trade data, SFDA registration filings, ESMA absorbency testing protocols, and Nielsen retail audit data across Saudi and UAE pharmacy channels. Bottom-up volume modeling and top-down market sizing triangulated on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product type, material formulation, distribution channel, and end-user archetype. CAGRs derived from trend extrapolation of pharmacy network expansion rates, biodegradable certification adoption curves, and municipal waste diversion policy implementation timelines. Forecast inputs included SFDA registration mandate compliance cost trajectories and superabsorbent polymer import price volatility assumptions.
Macroeconomic conditions sit as an overlay; deviation in Gulf currency peg stability, Asian petrochemical feedstock pricing, or regional freight rate indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization progress and certification cost compression timelines. Quarterly review of SFDA and ESMA regulatory filings, biodegradable testing laboratory capacity expansion, and pharmacy chain slotting fee negotiations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical and Hygiene Textiles
Textile Implants Market
Medical and Hygiene Textiles
Examination Gloves Market
Medical and Hygiene Textiles
Global Surgical Drapes and Gowns Market
Medical and Hygiene Textiles
Global Antimicrobial Medical Textiles Market
Medical and Hygiene Textiles
Antimicrobial Textiles Market
Medical and Hygiene Textiles
Surgical Drapes Market
Medical and Hygiene Textiles
Period Panties Market
Medical and Hygiene Textiles
Textile Based Ph Controllers Market
Medical and Hygiene Textiles
Latin America Sanitary Napkin Market
Medical and Hygiene Textiles
Tissue Towel Market
Medical and Hygiene Textiles
Medical Fabrics Market
Medical and Hygiene Textiles
Washable and Reusable Mask Market
Medical and Hygiene Textiles
United States Sanitary Napkin Market
Medical and Hygiene Textiles
Compressed Towel Market
Medical and Hygiene Textiles
Sanitary Napkin Market
Medical and Hygiene Textiles
Foot Mask Market