
 Medical Rehabilitation Robotics Market | 2026-2036
Medical Rehabilitation Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Rehabilitation Robotics Market Foresight
CE-marked Class IIa medical device certification is rotating toward the baseline qualification for hospital procurement committees across European rehabilitation centers. Ekso Bionics leverages its FDA-cleared EksoNR platform to sustain inpatient neurorehabilitation placements in the United States. Hocoma anchors the European therapeutic robot segment through its Armeo and Lokomat lines, which dominate motorized movement therapy installations in Germany and Switzerland.
Medical rehabilitation robotics encompasses electromechanical systems engineered to restore, augment, or substitute human motor function through programmable force assistance, typically operating with position resolution below one millimeter and force feedback thresholds measured in newtons. These platforms serve stroke survivors, spinal cord injury patients, and orthopedic recovery cases requiring repeatable, quantifiable movement therapy beyond manual physiotherapist capacity. Exoskeletons capture the largest installed base among product types, while AI-based systems represent the fastest-expanding technology tier as machine learning enables real-time gait adaptation. Sensor-embedded units concentrate margin pools through proprietary inertial measurement unit arrays that differentiate hardware-software bundles from commodity mechanical alternatives.
FDA breakthrough device designation and EU MDR Class IIa certification requirements shape product development timelines, with both frameworks demanding clinical evidence packages that filter out undercapitalized entrants. The EU AI Act adds algorithmic transparency obligations for AI-based rehabilitation systems, extending compliance burdens beyond traditional hardware safety standards. Stakeholders must monitor how reimbursement coding evolution in Medicare and national health systems determines whether home care segments achieve parity with institutional settings.
Market Dynamics
CE marking under EU MDR and FDA breakthrough device designation are compressing approval timelines while simultaneously raising clinical evidence thresholds, filtering capital requirements upward and consolidating viable product portfolios among therapeutic robot manufacturers.
Growth Catalysts
- EU MDR Class IIa Certification:Hospital procurement committees across Germany, Switzerland, and Austria now mandate CE-marked therapeutic robots, creating baseline demand for motorized movement therapy platforms in acute rehabilitation settings.
- Stroke Recovery Protocols:Inpatient neurorehabilitation departments in tertiary hospitals are embedding exoskeleton-assisted gait training into standardized post-stroke care pathways, generating repeatable placement cycles.
- Sensor-Embedded Force Feedback Arrays:Proprietary inertial measurement unit clusters with sub-millimeter position resolution are differentiating hardware-software bundles from commodity mechanical alternatives, capturing expanded margin pools.
Market Restraints
- Precious Metal Input Volatility:Neodymium and dysprosium price swings in permanent magnet supply chains create component cost instability for motorized joint actuators in exoskeleton platforms.
- Technical Limitation in Home Settings:Unsupervised patient operation of force-assist systems remains constrained by fall-risk liability and absence of real-time clinician oversight protocols.
- Reimbursement Coding Fragmentation:Medicare and national health systems maintain inconsistent procedure codes for robotic-assisted therapy, creating payment uncertainty that delays institutional purchasing decisions.
Strategic Opportunities
- Home Care Segment Development:Germany's statutory health insurance framework is piloting remote-monitoring reimbursement for outpatient rehabilitation robotics, opening channel expansion beyond hospital walls.
- AI-Act Algorithmic Transparency:EU AI Act compliance requirements for high-risk medical devices are creating first-mover advantage for rehabilitation platforms with documented machine-learning decision pathways.
- Orthopedic Recovery Applications:Post-surgical joint replacement rehabilitation represents underpenetrated demand relative to neurological indications, with sports medicine clinics in Switzerland testing early adoption.
Industry Challenges
- Clinical Evidence Generation Burden:FDA breakthrough and EU MDR pathways demand multi-center randomized controlled trials that extend development timelines and consume capital reserves.
- Mechatronics Talent Scarcity:Integration of force control algorithms with physical hardware requires specialized engineers whose concentration in Swiss and German research clusters limits geographic hiring flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Rehabilitation Robotics Market |
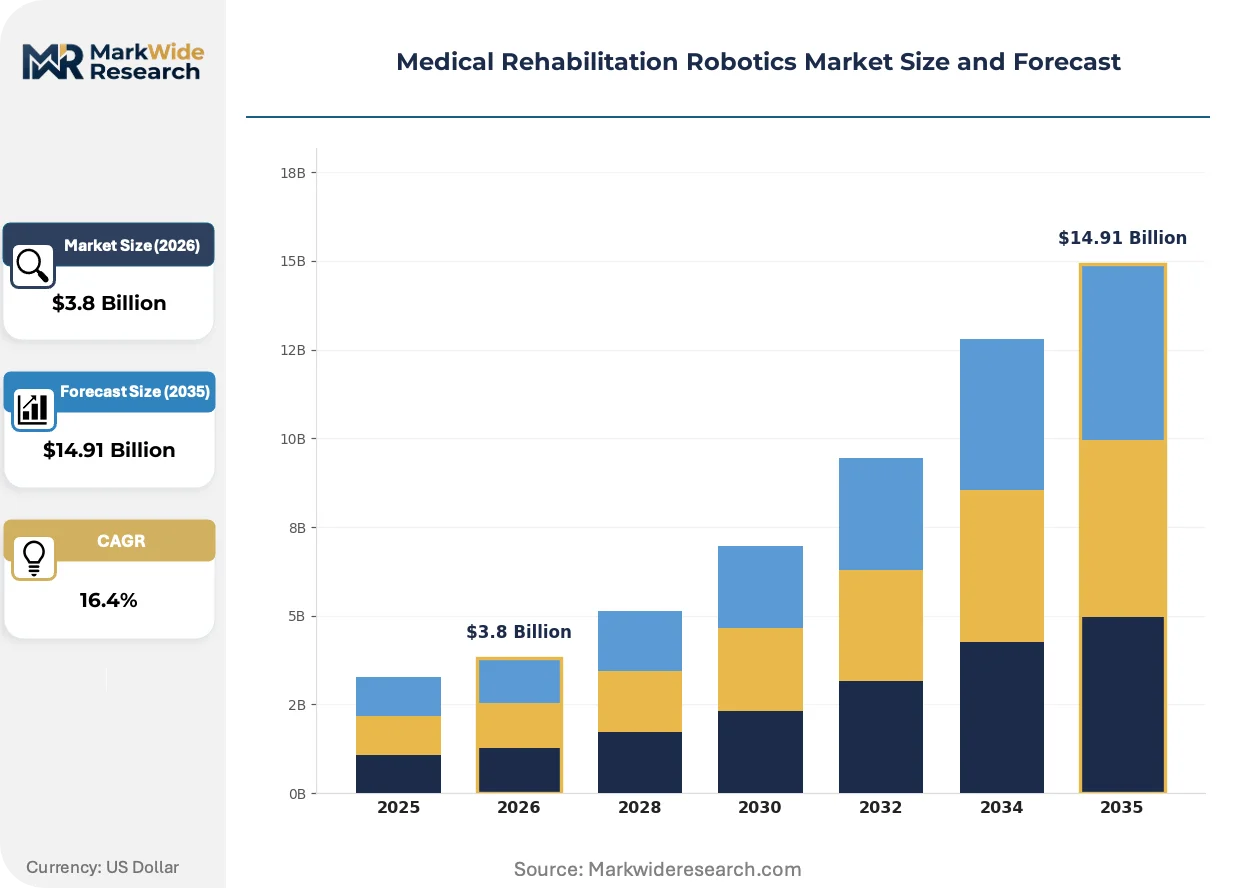
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Robotic Prosthetics, Assistive Devices, Therapeutic Robots End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Technology: AI-Based Systems, Mechanical Systems, Sensor-Embedded Units, Haptic Feedback Application: Stroke Recovery, Physical Therapy, Orthopedic Rehabilitation, Mobility Assistance |
| Companies Covered | Cyberdyne, Ekso Bionics, DIH, BIONIK, LIFEWARD, myomo, ReWalk Robotics, Hocoma, Rex Bionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Rehabilitation Robotics Market Shifts & Advancements
Wearable drive systems and embedded AI inference engines are restructuring how rehabilitation robotics deliver force assistance, shifting competitive advantage toward software-defined adaptation rather than mechanical precision alone.
Soft actuation technology using pneumatic artificial muscles and cable-driven series elastic actuators is miniaturizing power-to-weight ratios in lower-limb exoskeletons. Tertiary hospital rehabilitation departments in Germany and Switzerland are piloting these platforms for ambulatory stroke recovery. The technology is miniaturizing previously stationary gait trainers into transportable systems that compress inpatient length-of-stay while maintaining therapy intensity.
FDA breakthrough device designation paired with EU MDR Class IIa requirements is elevating clinical evidence standards for therapeutic robot premarket submissions. Manufacturers now face mandatory biocompatibility testing and software lifecycle documentation that extends development cycles. AI-based rehabilitation systems bear additional algorithmic transparency obligations under the EU AI Act, with stroke-focused platforms in the Netherlands and Belgium investing in explainable machine-learning architectures to satisfy notified body scrutiny.
Hospital procurement committees are unbundling after-sales service contracts from hardware purchases, demanding discrete pricing for maintenance, software updates, and clinician training. German rehabilitation center networks are leading this shift, negotiating multi-year service level agreements separately from capital equipment acquisition. The pattern concentrates margin pressure on manufacturers while creating recurring revenue opportunities for technical support providers with localized field engineering presence.
Medical Rehabilitation Robotics Market Segmentation
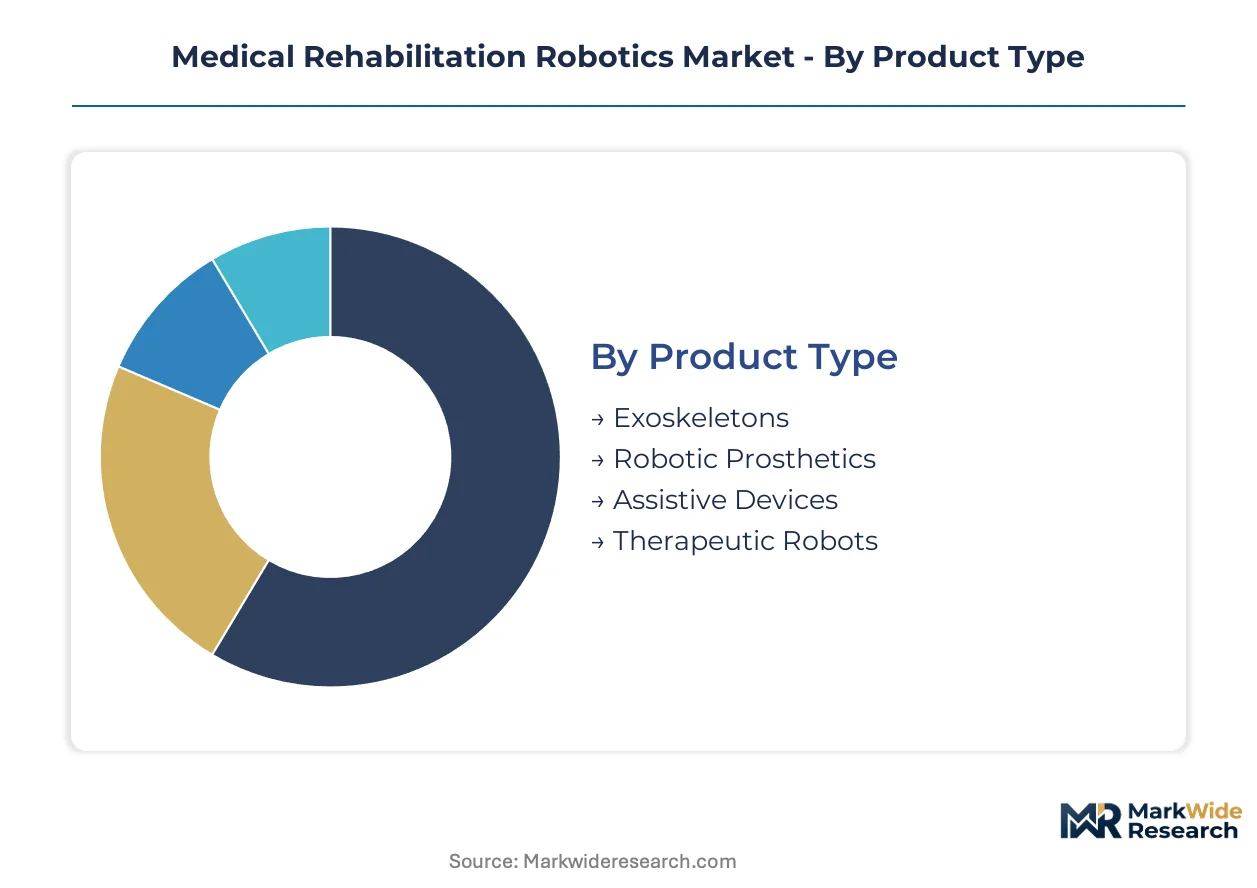
Segmentation in medical rehabilitation robotics reveals how regulatory pathways, reimbursement structures, and clinical evidence requirements reshape competitive positioning across hardware categories and care settings. Understanding these divisions exposes where capital requirements concentrate and where technology differentiation commands premium placement.
Product Type:
FDA breakthrough designation and EU MDR Class IIa certification requirements fragment product viability, with higher regulatory burdens filtering out undercapitalized entrants in motorized movement platforms.
- Exoskeletons:Motorized frameworks with position resolution below one millimeter deliver programmable force assistance for gait restoration. German rehabilitation centers and Swiss university hospitals concentrate procurement of these systems, driven by stroke recovery protocol standardization and inpatient neurorehabilitation reimbursement codes. Established volume favors exoskeletons; emerging adoption favors therapeutic robots.
- Therapeutic Robots:Stationary electromechanical platforms enable repeatable limb movement therapy with quantifiable outcome metrics. Tertiary hospital departments in Germany embed these into post-stroke care pathways, generating placement cycles tied to length-of-stay compression targets.
- Robotic Prosthetics:Microprocessor-controlled limb replacements with myoelectric signal processing restore motor function for amputee patients.
- Assistive Devices:Powered wheelchairs and mobility aids with basic sensor feedback support independent patient movement outside clinical supervision.
Cost tier stratification separates capital-intensive exoskeleton platforms from lower-acuity assistive alternatives, with reimbursement coding determining viable price points in institutional versus home settings.
End User:
Procurement authority and reimbursement pathways diverge sharply across care environments, with hospital committees demanding clinical evidence packages that home care distributors cannot satisfy.
- Hospitals:Tertiary acute care institutions with dedicated neurorehabilitation departments command the largest capital equipment budgets. FDA-cleared and CE-marked platforms achieve placement through standardized post-stroke protocols, with Medicare and statutory insurance frameworks in Germany enabling predictable payment cycles.
- Rehabilitation Centers:Specialized outpatient facilities in Germany and Switzerland concentrate repeat-session therapy demand. These centers negotiate multi-year service level agreements separately from hardware acquisition, unbundling maintenance and software update contracts.
- Home Care:Unsupervised patient operation remains constrained by fall-risk liability and absent real-time clinician oversight protocols.
- Clinics:Sports medicine and orthopedic practices in Switzerland pilot post-surgical joint replacement applications with lower session volumes than hospital settings.
Institutional purchasing concentration favors hospitals; reimbursement pilot programs favor home care expansion.
Technology:
Software-defined adaptation capabilities now differentiate margin capture, with algorithmic transparency obligations under EU AI Act compliance creating first-mover advantages for documented machine-learning architectures.
- AI-Based Systems:Real-time gait adaptation through embedded inference engines enables personalized force assistance without manual clinician recalibration. Platforms in the Netherlands and Belgium invest in explainable machine-learning architectures to satisfy notified body scrutiny under algorithmic transparency mandates.
- Sensor-Embedded Units:Proprietary inertial measurement unit arrays with sub-millimeter position resolution differentiate hardware-software bundles from commodity mechanical alternatives. These systems capture expanded margin pools through data-driven outcome documentation that supports reimbursement claims.
- Mechanical Systems:Passive or spring-assisted frameworks without programmable control occupy lower price tiers with limited clinical evidence requirements.
- Haptic Feedback:Force-reflective interfaces enable remote therapist-patient interaction for telerehabilitation applications.
Margin concentration favors sensor-embedded units; regulatory compliance complexity favors AI-based platforms with documented decision pathways.
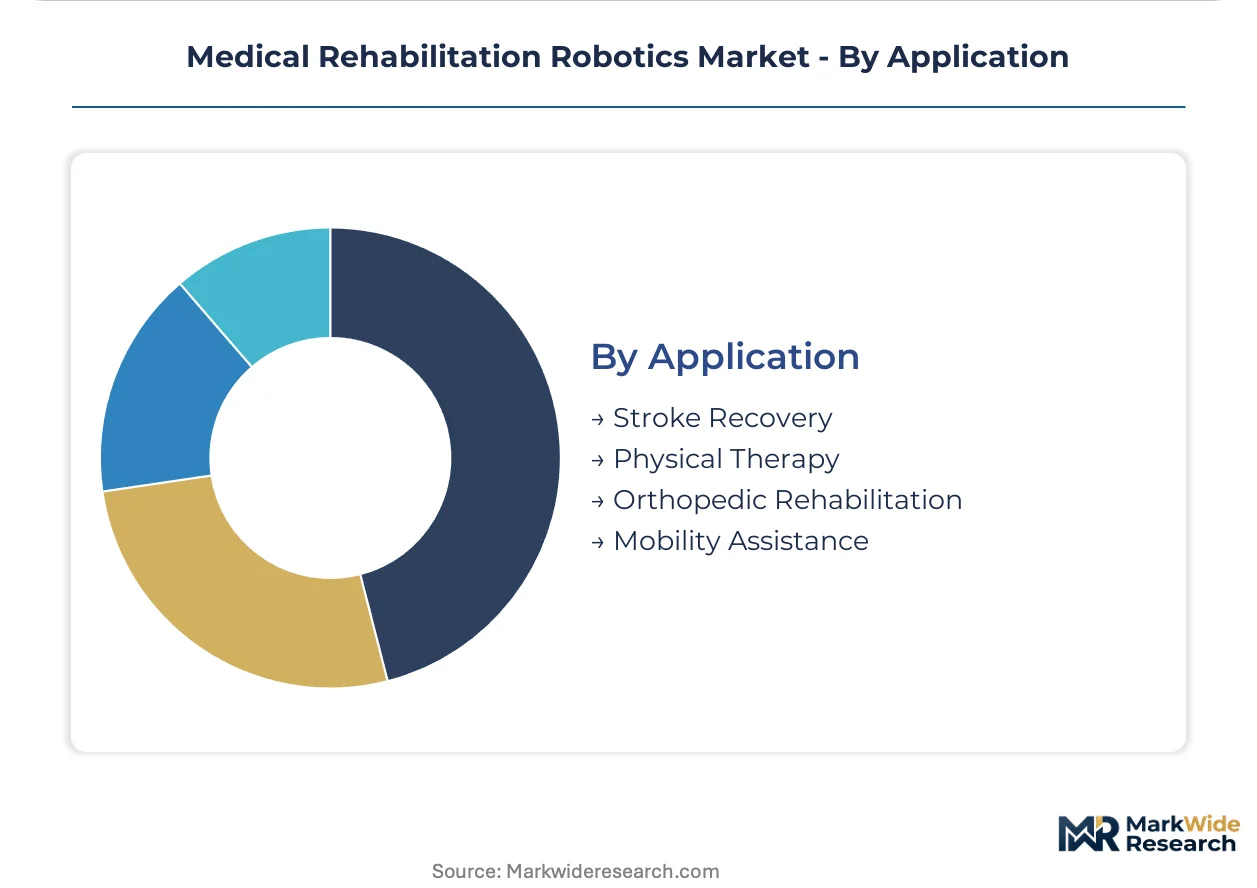
Application:
Clinical evidence density and reimbursement maturity vary across therapeutic indications, with neurological applications commanding stronger payment codes than orthopedic alternatives.
- Stroke Recovery:Standardized inpatient neurorehabilitation protocols in German and Swiss tertiary hospitals embed exoskeleton-assisted gait training as core therapy modality. Medicare and national health system coding for post-stroke robotic assistance enables repeatable placement cycles with predictable reimbursement.
- Orthopedic Rehabilitation:Post-surgical joint replacement therapy represents underpenetrated demand relative to neurological indications. Sports medicine clinics in Switzerland test early adoption, with procedure code fragmentation delaying institutional purchasing decisions.
- Physical Therapy:General rehabilitative movement therapy spans multiple indication types with less specialized equipment requirements.
- Mobility Assistance:Chronic condition management and degenerative disease support demand lower-acuity devices with home care distribution channels.
Reimbursement code maturity favors stroke recovery; volume expansion potential favors orthopedic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in German and Swiss rehabilitation engineering clusters, where statutory insurance frameworks and university hospital networks sustain dense therapeutic robot deployment. FDA-cleared platforms anchor North American placement cycles, while Asian markets pilot reimbursement pilots for home care expansion.
United States
Medicare reimbursement codes for inpatient neurorehabilitation drive tertiary hospital procurement of FDA-cleared exoskeleton platforms. The FDA breakthrough device designation pathway compresses approval timelines for therapeutic robot submissions. Boston and Pittsburgh rehabilitation research clusters concentrate clinical trial activity and mechatronics talent pipelines.
Germany
Statutory health insurance reimbursement for motorized movement therapy sustains the largest installed base of CE-marked rehabilitation robots in acute care settings. EU MDR Class IIa certification mandates filter hospital procurement toward notified body-approved platforms. Baden-Württemberg and Bavaria anchor manufacturing and clinical validation networks for therapeutic robot systems.
Switzerland
University hospital rehabilitation departments in Zurich and Geneva standardize exoskeleton-assisted gait training for post-stroke protocols. Swissmedic medical device regulations align with EU MDR requirements, enabling parallel CE marking submissions. The Lake Geneva region concentrates orthopedic rehabilitation pilot programs for post-surgical joint replacement applications.
Japan
Aging demographics and long-term care insurance expansion generate demand for assistive robotics in institutional eldercare settings. PMDA regulatory pathways for therapeutic medical devices require local clinical evidence generation. The Kanto region around Tokyo hosts rehabilitation engineering research clusters and hospital network pilot deployments.
Netherlands
Rehabilitation center networks in the Randstad region pilot AI-based gait adaptation systems under EU AI Act algorithmic transparency requirements. National health system reimbursement for outpatient robotic therapy creates channel expansion beyond hospital walls. Eindhoven's mechatronics engineering base supplies sensor-embedded force feedback componentry.
Medical Rehabilitation Robotics Market Competitive Landscape
Concentration sits with integrated therapeutic robot manufacturers possessing CE-marked and FDA-cleared platform portfolios. The vendor base stratifies across three tiers: established European specialists with statutory insurance network relationships, North American innovators leveraging breakthrough designation pathways, and emerging Asian players testing home care reimbursement pilots. Dominant competitive moves include multi-year service level agreement unbundling from hardware sales and algorithmic transparency documentation for EU AI Act compliance.
Within the European specialist tier, Hocoma and Cyberdyne represent archetypes of statutory insurance-anchored market presence, while Ekso Bionics occupies a position exemplifying FDA breakthrough pathway leverage for inpatient neurorehabilitation placement. These three companies anchor the competitive structure through divergent regulatory positioning and geographic reimbursement network density.
| Leading Market Players |
|---|
| Cyberdyne |
| Ekso Bionics |
| DIH |
| BIONIK |
| LIFEWARD |
| myomo |
| ReWalk Robotics |
| Hocoma |
| Rex Bionics |
| Others |
Supply & Pricing Matrix
Capacity utilization at Baden-Württemberg mechatronics clusters shapes both component availability floors and exoskeleton platform pricing power, with statutory insurance procurement timelines compressing margin recovery windows for manufacturers serving German rehabilitation networks.
Pricing Analysis
EU MDR Class IIa certification dictates the pricing tier structure across European rehabilitation robotics, separating notified body-approved platforms from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, embedded sensor array sophistication, and after-sales service bundling. Cost compression in standard-tier motorized joint actuators is intensifying because neodymium permanent magnet supply volatility feeds through to component sourcing. Hospital procurement committees in Germany exhibit lowest price sensitivity due to statutory reimbursement predictability, while Swiss sports medicine clinics demonstrate highest sensitivity given procedure code fragmentation for orthopedic applications.
Supply Chain Analysis
Inventory cycles for force feedback sensor arrays extend lead times beyond twelve months, constraining production scheduling for AI-based rehabilitation platforms. Component manufacturing concentrates in Germany, Switzerland, and the Netherlands, with Eindhoven mechatronics engineering bases supplying inertial measurement unit clusters. Permanent magnet sourcing rests on Chinese rare earth processing and Japanese magnet fabrication. Single-source vulnerability in neodymium-dysprosium supply chains threatens actuator cost stability. Distribution runs through hospital procurement committees and rehabilitation center networks, with service level agreements unbundled from hardware transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is underway as AI-based gait adaptation systems shift competitive advantage from mechanical precision toward software-defined interoperability, with EU AI Act algorithmic transparency requirements favoring documented machine-learning architectures.
For Market Incumbents: Shield installed base positions through multi-year service level agreement unbundling that captures recurring revenue streams while new entrants struggle to match localized field engineering presence. Deepen backward integration into proprietary sensor array production to offset permanent magnet cost volatility. Prioritize CE marking renewal investments ahead of EU MDR enforcement deadlines to maintain German statutory insurance network access. For New Entrants and Emerging Players: Anchor in orthopedic rehabilitation applications where procedure code maturity lags stroke recovery, creating white-space opportunity in Swiss sports medicine clinics and post-surgical joint replacement settings. Target home care segments through remote-monitoring reimbursement pilots in Germany's statutory health insurance framework. Pursue hospital system partnership go-to-market models that leverage existing clinical validation infrastructure rather than building de novo evidence packages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-embedded platform specialists with documented EU AI Act compliance pathways and established reimbursement coding relationships. Long-term viability hinges on algorithmic transparency capabilities that extend beyond hardware safety standards to satisfy notified body scrutiny. Watch for Medicare reimbursement code consolidation signals as inflection indicators for home care segment expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa certification unlocks German statutory insurance procurement channels. |
| Hospital System Partnership | Multi-year service agreements with Baden-Württemberg rehabilitation networks secure placement cycles. |
| Software Companion Development | Explainable machine-learning architectures satisfy EU AI Act algorithmic transparency mandates. |
| Reimbursement Strategy | Medicare coding alignment determines inpatient neurorehabilitation payment predictability. |
| FDA Submission | Breakthrough device designation compresses approval timelines for therapeutic robot platforms. |
Research Methodology
Cross-validation between primary interviews with rehabilitation clinicians and hospital purchasing committees anchors the qualitative findings, with secondary validation drawing from FDA 510(k) filings, EU MDR notified body documentation, and German statutory health insurance reimbursement databases. Bottom-up triangulation across exoskeleton installation records and top-down reconciliation against Medicare procedure code utilization data shapes volume estimates. Stakeholder input incorporated biomedical engineers, GPO contracts managers, and mechatronics R&D directors across German and Swiss manufacturing clusters.
Sensitivity analysis around neodymium price volatility and reimbursement code adoption timelines tests forecast robustness across the projection horizon. Segmentation modeling spans product type, end user, technology tier, and application indication dimensions. CAGR derivation incorporates statutory insurance framework expansion rates, clinical evidence generation timelines, and AI-based platform penetration curves. Forecast inputs include permanent magnet supply chain stability indices and EU AI Act implementation pacing.
Material uncertainties — regulatory enforcement delays, rare earth export restrictions, and reimbursement coding fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about clinical evidence standards and algorithmic transparency compliance without guaranteeing notified body approval timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Global Molecular Robotics Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Asia Pacific Automated Guided Vehicle (AGV) Market
Robotics and Automation
Microsurgery Robot Market
Robotics and Automation
Global Exoskeleton Market