
 Healthcare Mobile Robots Market | 2026-2036
Healthcare Mobile Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Mobile Robots Market Analytics
Buyer concentration among hospital networks is recalibrating vendor qualification criteria toward integrated platform providers. Omron Corporation leverages its automation heritage to anchor logistics deployments across acute care campuses. ABB Ltd competes through modular navigation architectures that sustain interoperability with existing building management systems. Xenex Disinfection Services Inc. differentiates via UV-C payload specialization that controls infection prevention protocols in high-turnover wards.
Healthcare mobile robots comprise wheeled or tracked autonomous systems equipped with sensors, manipulators, or payload bays designed for clinical environments, typically operating at speeds below two meters per second with lithium-ion powertrains and LiDAR-based spatial mapping. These systems execute material transport, environmental disinfection, surgical assistance, or remote patient interaction to offset personnel shortages and reduce pathogen transmission vectors. Delivery robots dominate installed base volumes while disinfection robots capture premium pricing tiers due to validated sporicidal efficacy requirements. Surgical robots occupy concentrated margin pools where teleoperated technology intersects with augmented reality visualization for minimally invasive procedures.
FDA 510(k) clearance pathways and EU MDR Class IIa certification obligations shape product development cycles and geographic launch sequencing for manufacturers. Japan's PMDA and METI coordinate reimbursement coding that determines hospital budget allocation for autonomous care assistance. Stakeholders must monitor evolving cybersecurity standards for networked medical devices as connectivity requirements expand beyond single-facility deployments.
Market Dynamics
Hospital procurement consolidation is compressing vendor qualification timelines and privileging multi-function platform providers capable of unified fleet management across acute care campuses.
Growth Catalysts
- EU MDR Class IIa Certification Pathway:Streamlined conformity assessment procedures for autonomous mobile medical devices are accelerating product launch sequencing across European hospital networks.
- Lithium-Ion Powertrain Density:Energy storage improvements extending operational range above sixteen hours per charge cycle are expanding deployment feasibility in multi-building medical campuses.
- Japan's PMDA Reimbursement Coding:METI-coordinated autonomous care assistance budget allocations are creating predictable procurement pipelines for telepresence and delivery robot categories.
Market Restraints
- LiDAR Sensor Supply Concentration:Dependence on Asian-manufactured solid-state optical components creates input cost volatility and lead time uncertainty for navigation subsystem assembly.
- FDA 510(k) Predicate Device Requirements:Substantial equivalence demonstrations for novel disinfection payloads extend regulatory review cycles and compress first-mover advantage windows.
- UV-C Mercury Vapor Lamp Substitution:LED-based sporicidal arrays achieving validated efficacy thresholds threaten incumbent high-voltage system architectures and associated service revenue streams.
Strategic Opportunities
- German Acute Care Campus Consolidation:Krankenhauszukunftsgesetz hospital restructuring funds are creating capital availability for integrated logistics automation in merged facility networks.
- Augmented Reality Surgical Visualization Convergence:Integration of haptic feedback systems with teleoperated manipulators is opening premium procedure categories beyond traditional laparoscopy.
- ISO 13485:2016 Quality Management Certification:Medical device-specific quality system adoption is creating differentiation pathways for vendors seeking differentiated positioning in procurement evaluations.
Industry Challenges
- Clinical Engineering Talent Scarcity:Shortages of biomedical technicians trained in autonomous system maintenance are extending mean time to repair and elevating total cost of ownership.
- Legacy Building Management System Interoperability:Integration with proprietary elevator control and HVAC networks requires custom protocol bridges that fragment deployment scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Mobile Robots Market |
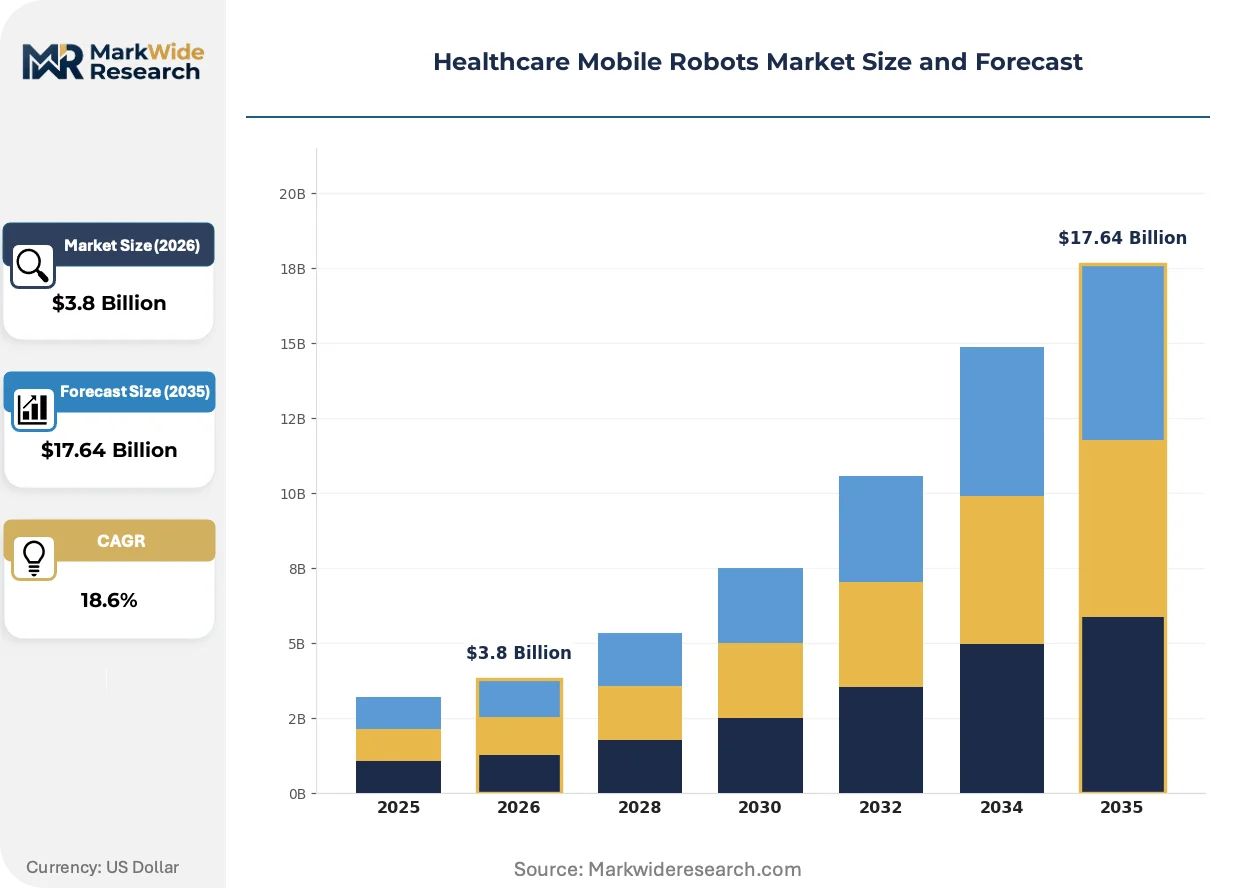
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Delivery Robots, Disinfection Robots, Surgical Robots, Telepresence Robots End User: Hospitals, Clinics, Nursing Homes, Rehabilitation Centers Technology: AI-Powered, Teleoperated, Autonomous Navigation, Augmented Reality Application: Patient Care, Logistics Management, Sanitation, Remote Consultation |
| Companies Covered | Omron Corporation, Ateago Technology, Toyota Motor Corporation, Awabot, VGo Communications, Inc., ABB Ltd, Teradyne, Xenex Disinfection Services Inc., Aethon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Mobile Robots Market Evolving Landscape
Edge computing architectures are redistributing processing loads from centralized servers to onboard sensor fusion units, altering fleet management economics and cybersecurity perimeter definitions.
Swarm coordination algorithms are decentralizing fleet control from single-master architectures to distributed agent negotiation protocols. Large hospital networks in the United States are piloting hundred-unit deployments where individual robots negotiate corridor priority without central dispatch intervention. This topology is decentralizing capital requirements by eliminating redundant server infrastructure and reducing single-point-of-failure vulnerabilities in critical care logistics.
Japan's PMDA has issued guidance documents clarifying software-as-a-medical-device classification for autonomous navigation updates, creating regulatory precedent for over-the-air capability expansion. Manufacturers must now maintain version-controlled cybersecurity documentation across deployed fleets. Surgical assistance platforms with teleoperated functionality face the most stringent documentation burdens under this framework.
Acute care procurement committees are unbundling hardware acquisition from multi-year service agreements, compressing vendor switching cycles and elevating interoperability certification weighting in bid evaluations. German hospital networks pioneered this separation, with purchasing cooperatives now standardizing on open API requirements. This pattern is most visible in disinfection robot categories where sporicidal efficacy validation protocols have commoditized core hardware differentiation.
Healthcare Mobile Robots Market Segmentation
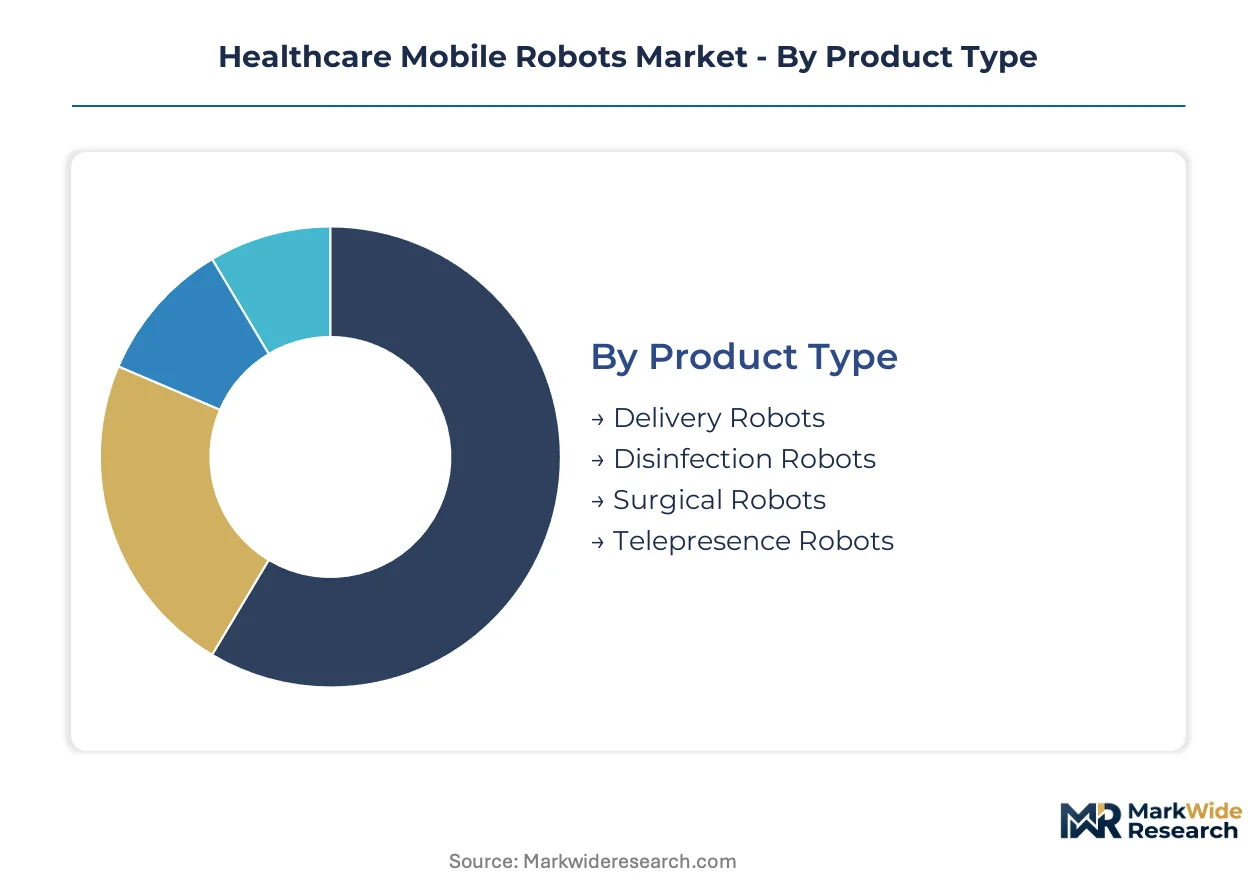
Segmentation in healthcare mobile robotics reveals distinct procurement patterns across clinical settings. Buyers prioritize different capability bundles based on facility scale, regulatory environment, and staffing constraints.
Product Type:
Hospital procurement departments differentiate platforms by payload specialization and margin profile.
- Delivery Robots:Wheeled autonomous systems with modular payload bays transport pharmaceuticals, linens, and laboratory specimens across acute care campuses. Demand concentrates in United States hospital networks where centralized pharmacy distribution and multi-building campuses strain human courier capacity.
- Disinfection Robots:UV-C or hydrogen peroxide vapor emission systems achieve validated sporicidal efficacy in high-turnover patient rooms and surgical suites. German Krankenhauszukunftsgesetz restructuring funds are accelerating capital deployment for infection prevention automation in merged facility networks.
- Surgical Robots:Teleoperated manipulators with haptic feedback and augmented reality visualization support minimally invasive procedures. Japan's PMDA maintains stringent software-as-a-medical-device documentation requirements for navigation updates.
- Telepresence Robots:Mobile video conferencing platforms enable remote specialist consultation and family visitation in isolation wards. Clinics in rural United States markets deploy these for teleradiology and stroke assessment protocols.
Delivery robots lead volumes today; disinfection robots are gaining share fastest.
End User:
Facility type determines fleet scale, integration complexity, and regulatory scrutiny intensity.
- Hospitals:Acute care campuses operate the largest autonomous fleets, with hundred-unit deployments piloting swarm coordination without central dispatch. FDA 510(k) clearance pathways shape vendor qualification timelines for multi-function platform procurement.
- Clinics:Outpatient facilities prioritize compact telepresence and delivery units for pharmaceutical logistics and remote specialist access. METI-coordinated reimbursement coding in Japan creates predictable budget pipelines for autonomous care assistance categories.
- Nursing Homes:Long-term care operators deploy medication delivery and social engagement robots to offset certified nursing assistant shortages. EU MDR Class IIa certification requirements extend product development cycles for European market entry.
- Rehabilitation Centers:Physical therapy facilities utilize augmented reality surgical assistance platforms for precision movement therapy and remote physician oversight.
Hospitals dominate installed base; nursing homes are expanding most quickly.
Technology:
Processing architecture and control modality determine cybersecurity perimeter definitions and regulatory documentation burdens.
- AI-Powered:Machine learning-based navigation systems adapt to dynamic corridor congestion and elevator scheduling in real-time. Edge computing redistribution to onboard sensor fusion units is altering fleet management economics.
- Teleoperated:Human-in-the-loop control architectures dominate surgical assistance categories where haptic feedback precision determines procedure outcomes.
- Autonomous Navigation:LiDAR-based spatial mapping with lithium-ion powertrains enables sixteen-hour operational range for logistics deployment. Solid-state optical component supply concentration creates input cost volatility.
- Augmented Reality:Visualization overlays integrate with teleoperated manipulators for premium procedure categories beyond traditional laparoscopy.
Autonomous navigation leads deployment volumes; augmented reality is climbing the fastest.
Application:
Use case specificity drives payload customization and interoperability certification requirements.
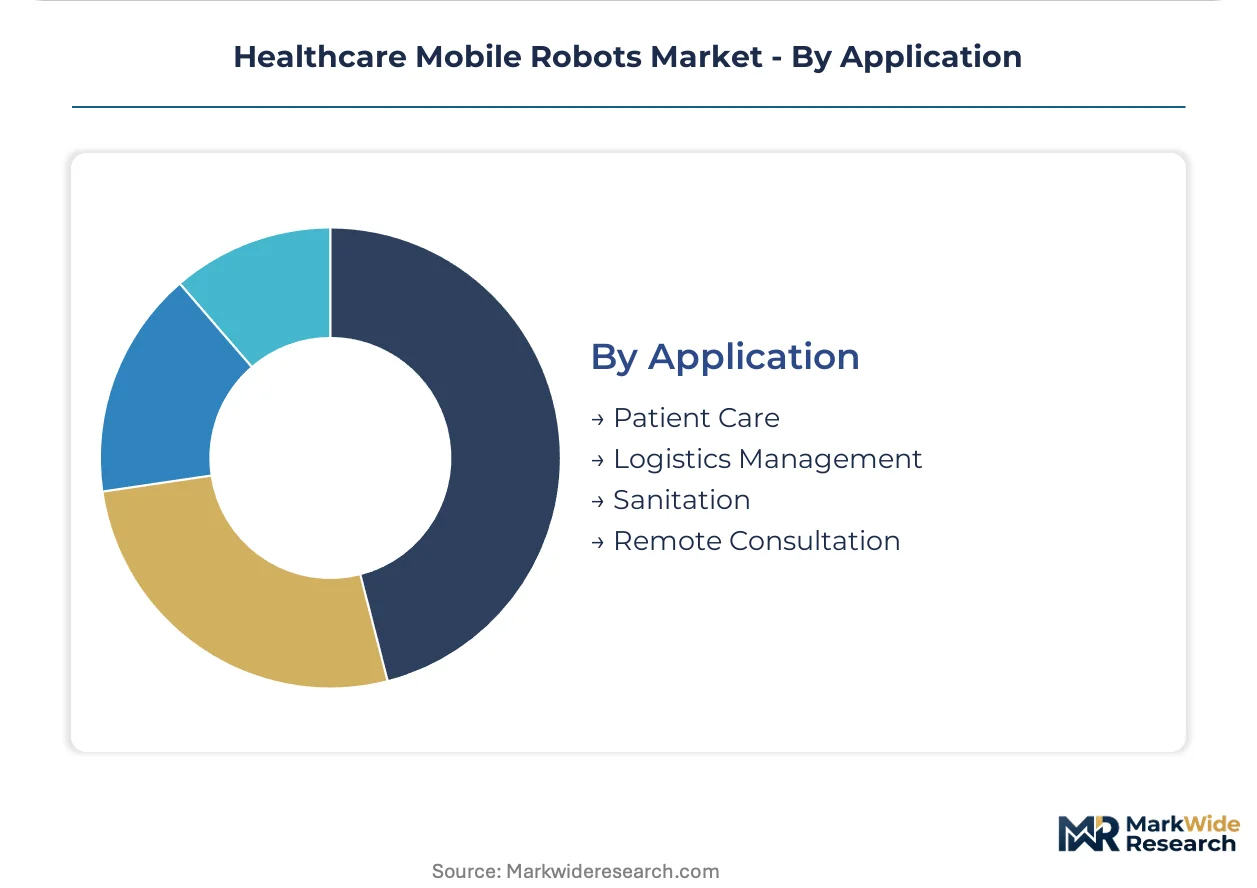
- Patient Care:Direct clinical interaction robots support mobility assistance, vital sign monitoring, and medication adherence prompting. Japanese PMDA guidance on autonomous care assistance reimbursement coding shapes procurement patterns.
- Logistics Management:Material transport automation offsets personnel shortages in pharmacy, central supply, and environmental services. German purchasing cooperatives standardize on open API requirements, compressing vendor switching cycles.
- Sanitation:Environmental disinfection systems with validated sporicidal efficacy command premium pricing tiers. LED-based sporicidal arrays threaten incumbent mercury vapor lamp architectures.
- Remote Consultation:Telepresence platforms extend specialist reach to underserved geographies and isolation protocols. FCC connectivity standards influence deployment feasibility in United States rural markets.
Logistics management leads volumes today; sanitation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks deploy larger autonomous fleets than German counterparts, though Tokyo's acute care campuses pioneer swarm coordination protocols. Japan's reimbursement coding creates procurement predictability that contrasts with the fragmented budget cycles in European markets.
United States
Hospital consolidation into mega-systems like HCA Healthcare and CommonSpirit Health drives demand for hundred-unit fleet deployments. FDA 510(k) clearance pathways compress vendor qualification timelines for multi-function platforms. The Dallas-Fort Worth metroplex anchors logistics automation pilots where robots negotiate corridor priority without central dispatch.
Germany
Krankenhauszukunftsgesetz restructuring funds channel capital toward infection prevention automation in merged facility networks. EU MDR Class IIa certification requirements reshape product development cycles for autonomous navigation systems. The Rhine-Ruhr metropolitan region concentrates purchasing cooperative standardization efforts on open API requirements.
Japan
METI-coordinated autonomous care assistance budget allocations create predictable procurement pipelines for telepresence and delivery categories. PMDA guidance on software-as-a-medical-device classification establishes regulatory precedent for over-the-air capability expansion. The Kanto region surrounding Tokyo hosts the densest concentration of acute care campus pilots testing edge computing redistribution.
China
Centralized pharmacy distribution networks in tier-one cities strain human courier capacity and accelerate logistics robot adoption. NMPA medical device registration pathways determine geographic launch sequencing for manufacturers targeting hospital procurement. The Yangtze River Delta cluster around Shanghai anchors domestic production of LiDAR navigation subsystems.
South Korea
Aging demographics in the Seoul Capital Area drive demand for patient care robots supporting mobility assistance and medication adherence. MFDS medical device quality system requirements align with ISO 13485:2016 standards for procurement differentiation. The Busan-Ulsan corridor concentrates rehabilitation center deployments of augmented reality surgical assistance platforms.
Healthcare Mobile Robots Market Competitive Landscape
Japanese producers anchor one tier; European specialists hold differentiated positions in disinfection payload architectures. The vendor base organizes around three strategic archetypes: diversified automation conglomerates leveraging cross-industry navigation IP, pure-play healthcare robotics ventures concentrating on FDA-cleared clinical applications, and industrial equipment manufacturers extending existing service networks into hospital procurement channels. Dominant competitive moves include strategic partnerships with hospital purchasing cooperatives and technology licensing agreements for swarm coordination algorithms.
Among diversified automation conglomerates, Omron Corporation and ABB Ltd exemplify platform providers capable of unified fleet management across acute care campuses. Xenex Disinfection Services Inc. occupies a specialized position within the UV-C payload tier, representing vendors who differentiate through validated sporicidal efficacy protocols rather than navigation hardware. Toyota Motor Corporation anchors the industrial extension archetype, leveraging automotive automation heritage to compete in logistics deployment categories.
| Leading Market Players |
|---|
| Omron Corporation |
| Ateago Technology |
| Toyota Motor Corporation |
| Awabot |
| VGo Communications, Inc. |
| ABB Ltd |
| Teradyne |
| Xenex Disinfection Services Inc. |
| Aethon |
| Others |
Value Network & Pricing Analysis
LED-based sporicidal array commercialization is simultaneously collapsing UV-C disinfection hardware margins and fragmenting supplier power across Asian optical component markets. This technology transition rewards buyers with unbundled procurement options while compressing service revenue streams that historically subsidized capital equipment pricing.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for LiDAR navigation subsystems used in hospital logistics fleets. Pricing stratifies across FDA-cleared premium tiers, EU MDR Class IIa mid-market certification levels, and economy segments lacking validated sporicidal efficacy. Cost compression in disinfection hardware is intensifying because LED arrays achieve parity with mercury vapor lamp performance at lower bill-of-materials cost. Hospital GPOs exhibit highest price sensitivity in telepresence categories where software differentiation remains limited.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital procurement committees now require qualified suppliers for both solid-state LiDAR emitters and lithium-ion powertrain cells. Manufacturing concentrates in China, South Korea, and Japan for navigation subsystems, with German producers anchoring precision manipulator assemblies for surgical platforms. Raw material dependencies include rare-earth phosphors for UV-C LED efficiency, high-purity silicon for optical sensors, and nickel-cobalt cathode formulations. Single-source vulnerability concentrates in Asian-manufactured solid-state optical components. Distribution runs through regional medical device distributors with ISO 13485:2016 certification and direct hospital GPO contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Class IIa certification deadlines function as a regulatory compounder, accelerating procurement consolidation around vendors with established conformity assessment pathways. Hospital networks now disqualify non-compliant suppliers from multi-year fleet contracts.
For Market Incumbents: Anchor platform interoperability through open API standardization to defend against modular navigation entrants. Deepen backward integration into LiDAR sensor production to offset Asian supply concentration risks. Prioritize ISO 13485:2016 quality system maintenance as procurement committees elevate certification weighting in bid evaluations. For New Entrants and Emerging Players: Begin with nursing home medication delivery applications where FDA 510(k) predicate requirements remain less stringent than surgical categories. Target rural United States clinic telepresence deployments underserved by incumbent logistics platforms. Pursue reimbursement strategy development aligned with Japan's PMDA autonomous care assistance coding. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play disinfection ventures facing LED substitution pressure on legacy mercury vapor architectures. Five-to-ten year viability favors diversified automation conglomerates with cross-industry navigation IP and hospital purchasing cooperative relationships. Monitor FDA cybersecurity guidance publication as inflection indicator for teleoperated surgical platform capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways compress vendor qualification timelines for multi-function platform procurement. |
| CE Marking Pathway | EU MDR Class IIa certification accelerates product launch sequencing across German hospital networks. |
| Hospital System Partnership | Purchasing cooperative relationships secure hundred-unit fleet deployment contracts in United States mega-systems. |
| Software Companion Development | PMDA software-as-a-medical-device documentation enables over-the-air capability expansion for surgical platforms. |
| Reimbursement Strategy | METI-coordinated autonomous care assistance coding creates predictable procurement pipelines in Japanese acute care. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at device manufacturers grounded qualitative assessments. Secondary validation drew from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up installed base estimates triangulated against top-down addressable facility counts across acute care, clinic, and nursing home segments.
Bottom-up modeling aggregated unit economics across product type, end user facility scale, technology architecture, and application specificity. Segmentation dimensions included payload specialization, fleet deployment size, navigation system complexity, and regional regulatory cluster. CAGRs derived from logistic curve penetration modeling calibrated to historical adoption rates in comparable medical device categories. Forecast inputs incorporated lithium-ion energy density improvement curves and FDA review cycle duration trends.
Several conditions sit outside the modeled scope, including unforeseen cybersecurity incident liability frameworks and abrupt reimbursement coding revisions by national health authorities. Forecasts reflect documented assumptions regarding regulatory pathway stability and component supply continuity. Deviation in LiDAR sensor trade policy or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Retail Robotics Market