
 Asia Pacific Automated Guided Vehicle (AGV) Market | 2026-2036
Asia Pacific Automated Guided Vehicle (AGV) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automated Guided Vehicle (AGV) Market Outlook
Buyer concentration in Asia Pacific automotive assembly is pivoting toward tier-one electronics contract manufacturers expanding their own captive logistics networks. Daifuku Co., Ltd. leverages its decades-long installed base in semiconductor fabs to sustain recurring automation contracts across South Korea and Taiwan. Toyota Industries Corporation anchors the heavy-duty forklift AGV segment through proprietary drive-train technology and captive battery supply. Suzhou Casun Intelligent Robot Co., Ltd. competes aggressively on vision-based navigation systems priced for mid-market warehouse operators in Vietnam and Indonesia.
Automated Guided Vehicles in the Asia Pacific context comprise self-propelled mobile robots that transport materials along programmed paths using guidance technologies such as magnetic tape, laser reflectors, or lidar-based simultaneous localization and mapping, typically operating at speeds up to two meters per second in controlled industrial environments. Their primary purpose centers on eliminating fork-traffic congestion and reducing labor dependency in high-throughput distribution and manufacturing facilities. Towing AGVs dominate in heavy automotive assembly lines where continuous takt-time feeding of chassis components generates the largest installed revenue base, while vision-based technology captures the fastest expansion as camera-and-AI stacks displace laser reflector infrastructure in brownfield warehouse retrofits across the region. Unit Load AGVs occupy a mature niche in cleanroom electronics manufacturing where payload precision outweighs speed requirements, concentrating margin pools among Japanese and South Korean vendors with long-standing cleanroom certifications.
Japan's METI enforces functional safety standards for collaborative mobile robots that effectively gate market access for uncertified European and Chinese entrants, while China's SAMR mandates GB-standard electromagnetic compatibility testing for all automated industrial vehicles sold domestically. South Korea's MFDS-aligned workplace safety inspections extend to AGV fleet operations in pharmaceutical distribution centers, creating compliance-driven replacement cycles. Stakeholders must monitor divergence between Japanese SIL-rated safety architectures and China's emerging autonomous vehicle standards for indoor industrial mobility, as regulatory misalignment threatens to fragment product platform strategies across the region.
Market Dynamics
Vision-guided navigation systems are compressing deployment timelines in Southeast Asian warehouses, while Japan's METI safety certification requirements erect compliance barriers that reshape competitive entry patterns across the region.
Growth Catalysts
- GB-standard electromagnetic compatibility mandates:China's SAMR testing requirements for automated industrial vehicles create replacement demand as domestic facilities upgrade legacy magnetic-tape systems to certified autonomous platforms.
- Semiconductor cleanroom logistics:South Korean and Taiwanese fabs expand captive AGV fleets to reduce particle contamination risks from human material handling in sub-10nm wafer production environments.
- Yangtze River Delta manufacturing density:Automotive and electronics plants in Jiangsu and Zhejiang provinces deploy fleet-scale installations to synchronize just-in-sequence component delivery with compressed takt times.
Market Restraints
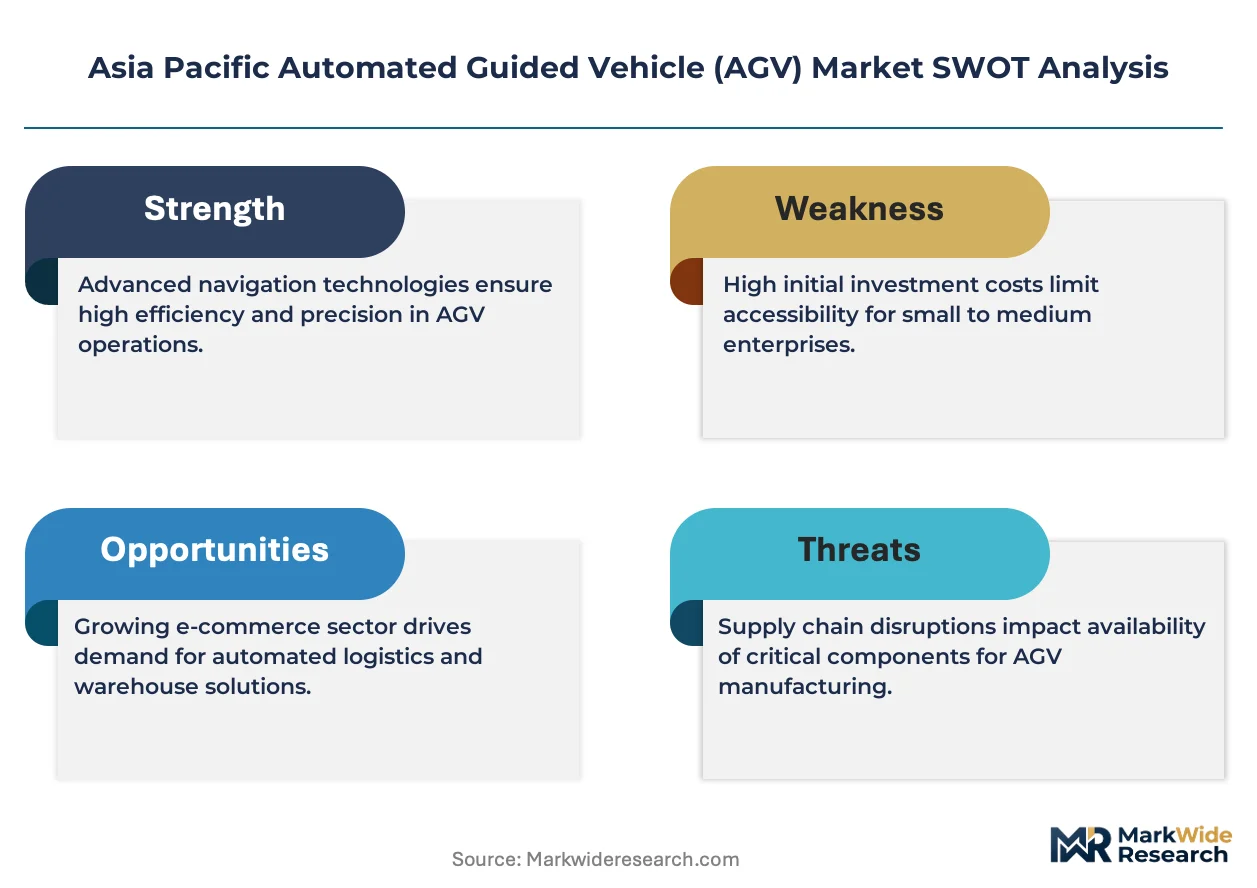
- Lithium iron phosphate cell supply concentration:Battery pack costs fluctuate with Chinese cathode material output, squeezing margins for mid-market warehouse operators in Vietnam and Indonesia.
- SIL-rated safety architecture fragmentation:Divergence between Japan's METI functional safety standards and China's emerging indoor autonomous vehicle rules forces dual-certification investments that delay product launches.
- Manual forklift substitution economics:Labor cost arbitrage in Indonesian and Philippine distribution centers sustains incumbent material handling equipment against automation payback calculations.
Strategic Opportunities
- Pharmaceutical cold chain distribution:South Korea's MFDS-aligned workplace safety inspections for AGV fleets in temperature-controlled drug logistics create compliance-driven upgrade cycles among regional 3PL providers.
- Lidar-camera sensor fusion:Convergence of solid-state lidar with edge-computing vision stacks enables navigation without facility infrastructure retrofits, opening brownfield warehouse conversions in Thailand and Malaysia.
- Captive fleet leasing models:Equipment-as-a-service structures reduce upfront capital barriers for mid-market e-commerce fulfillment operators across Southeast Asia.
Industry Challenges
- Simultaneous localization and mapping expertise scarcity:Deployment of vision-guided systems requires specialized robotics engineers that concentrate in Shenzhen, Tokyo, and Seoul, constraining rollout velocity in secondary markets.
- Legacy warehouse management system integration:Brownfield facilities in Indonesia and Vietnam operate on decade-old software architectures that resist API connectivity with modern fleet management platforms.
- Cleanroom certification timelines:Japanese and South Korean vendors face extended validation cycles for ISO Class 3-5 electronics manufacturing deployments, compressing revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automated Guided Vehicle (AGV) Market |
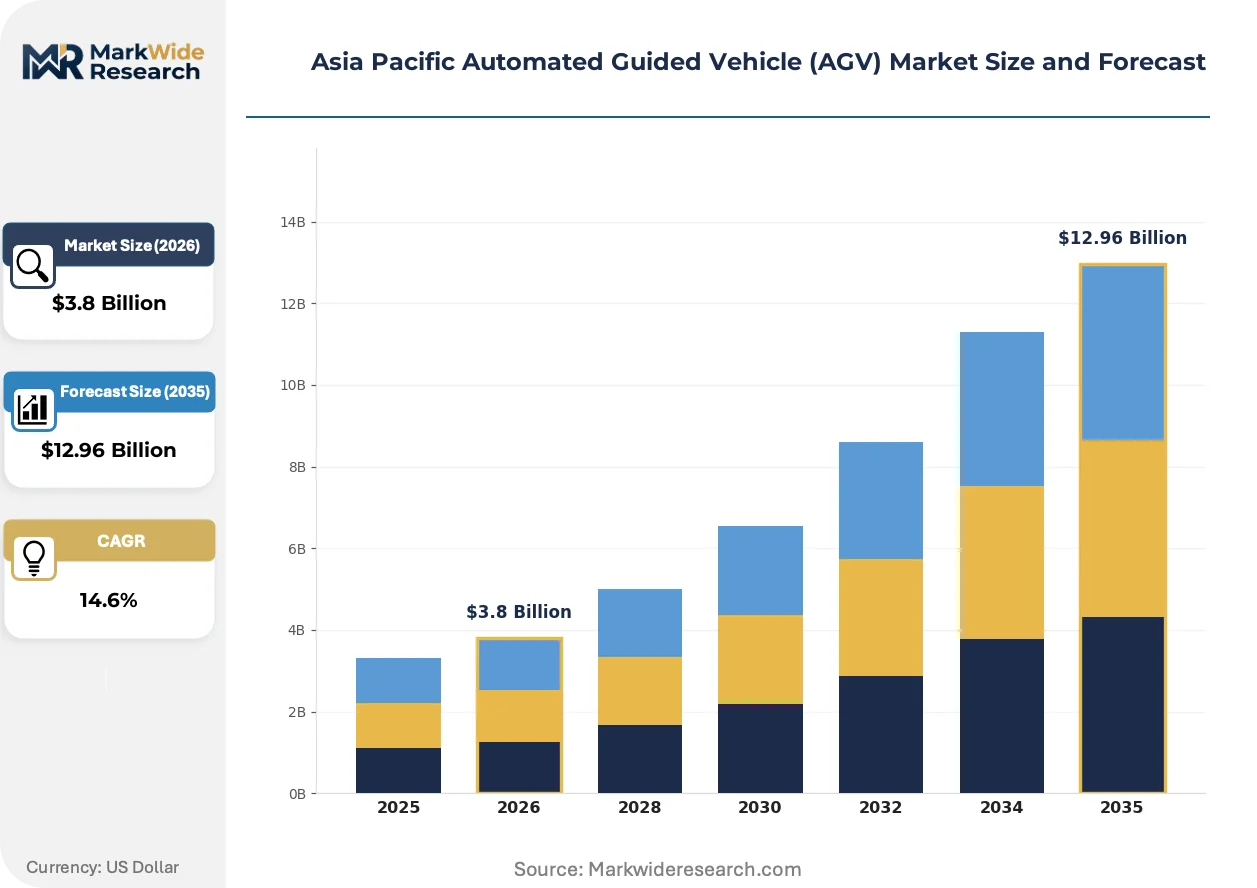
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Towing AGVs, Unit Load AGVs, Forklift AGVs, Pallet Trucks End User: Healthcare, Manufacturing, Retail, Logistics Technology: Lidar, Magnetic, Vision-based, Laser-guided Application: Material Handling, Warehouse Management, Assembly Lines, Order Fulfillment |
| Companies Covered | Meidensha Corporation, Nanchang Industrial Control Robot Co., Ltd., Daifuku Co., Ltd., Midea Group Co. Ltd., Murata Machinery Ltd., Toyota Industries Corporation, Suzhou Casun Intelligent Robot Co., Ltd., Scott Technology Ltd., Mitsubishi Logisnext Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automated Guided Vehicle (AGV) Market Strategic Shifts
Navigation hardware and fleet software architectures are fusing into unified platforms that reduce deployment friction, while regulatory divergence between Northeast Asian safety frameworks forces modular product strategies.
Camera-based simultaneous localization and mapping is converging with edge AI inference chips to eliminate laser reflector infrastructure in existing warehouse environments. Third-party logistics operators in Vietnam and Indonesia adopt these retrofit-friendly systems to avoid facility downtime during automation upgrades. The technology is converging with predictive maintenance algorithms that compress total cost of ownership calculations for mid-market buyers.
METI's functional safety standards for collaborative mobile robots mandate SIL-rated emergency stop systems and speed-separation protocols in shared human-robot workspaces. Japanese automotive assembly plants now require certified platforms for takt-time feeding applications, filtering uncertified Chinese and European entrants from procurement shortlists. Electronics contract manufacturers in Taiwan and South Korea pursue parallel certification tracks to maintain access across diverging regulatory regimes.
Buyer preference is hardening toward fleet-scale procurement with unified fleet management software rather than single-unit pilot programs. Regional e-commerce fulfillment operators in Thailand and Malaysia now specify multi-vendor interoperability requirements in tender documents, displacing proprietary single-source architectures. This consolidation pattern concentrates specification influence among systems integrators with established deployment track records in high-throughput distribution environments.
Asia Pacific Automated Guided Vehicle (AGV) Market Segmentation
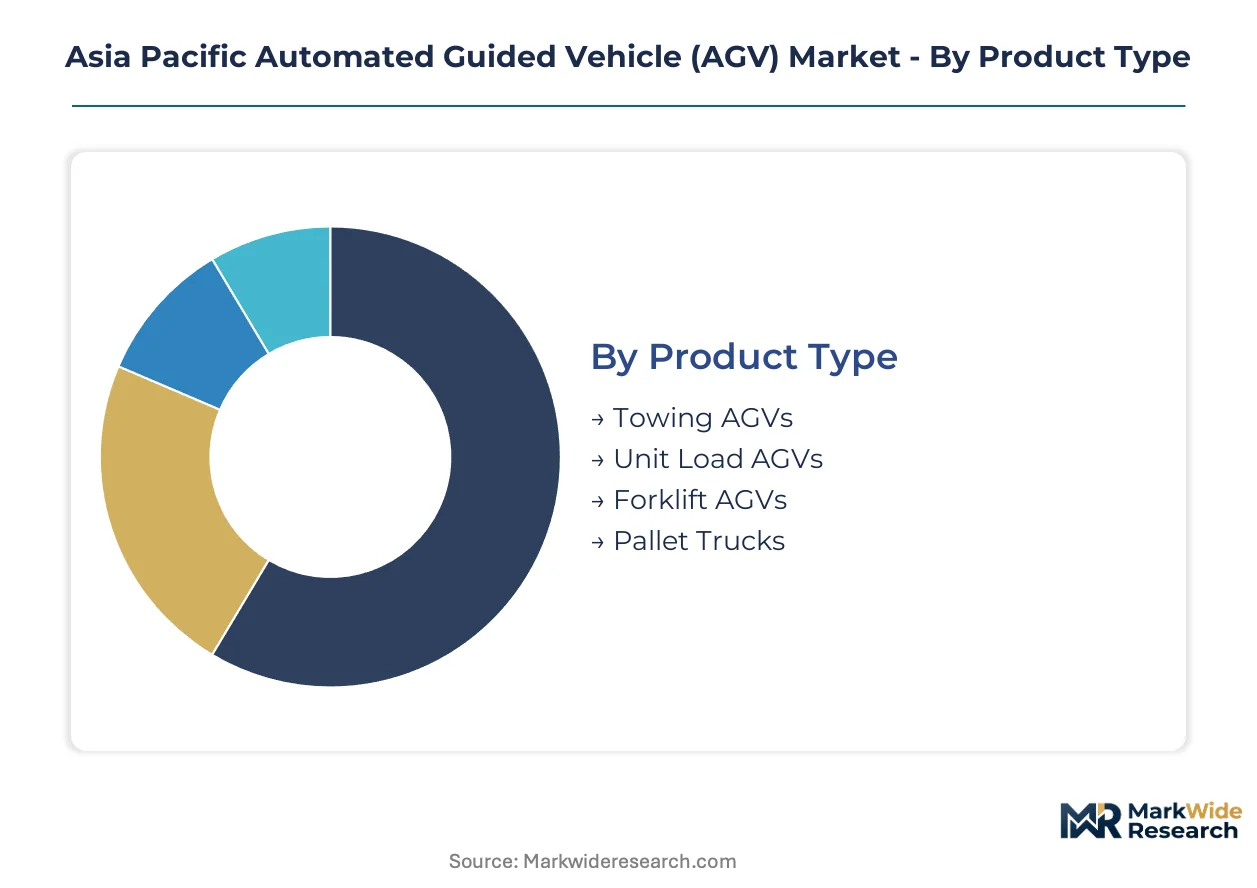
AGV procurement patterns across the Asia Pacific diverge sharply by facility type and operational intensity. Semiconductor fabs demand contamination-proof platforms while e-commerce warehouses prioritize rapid retrofit deployment without infrastructure overhaul.
Product Type:
Supply concentration in heavy-load towing systems and cleanroom-certified unit load carriers shapes vendor margin structures across Northeast Asia.
- Towing AGVs:These heavy-duty platforms pull sequential trailer trains along fixed magnetic or inductive paths at controlled speeds. Automotive assembly plants in Japan and South Korea deploy fleet-scale installations to maintain takt-time synchronization for chassis component feeding. METI safety certification requirements filter procurement to established domestic vendors with SIL-rated emergency stop architectures.
- Unit Load AGVs:Precision platforms transport discrete pallets or racks with positional accuracy within millimeters. Electronics cleanrooms in Taiwan and South Korea specify ISO Class 3-5 certified units to eliminate particle contamination risks during sub-10nm wafer production. Extended validation cycles compress revenue recognition for Japanese and South Korean suppliers.
- Forklift AGVs:Counterbalance and reach variants automate pallet stacking and retrieval in high-bay warehouses.
- Pallet Trucks:Low-profile walkie-style units handle floor-level transport in distribution centers with limited vertical storage.
Towing AGVs absorb the bulk of installed capacity; Vision-guided forklift variants are expanding most quickly in Southeast Asian brownfield retrofits.
End User:
Cost tier stratification separates high-specification cleanroom deployments from price-sensitive warehouse automation in emerging ASEAN markets.
- Healthcare:Hospital logistics and pharmaceutical distribution centers in South Korea deploy temperature-controlled AGV fleets under MFDS-aligned workplace safety inspections.
- Manufacturing:Electronics and automotive plants across China's Yangtze River Delta drive fleet-scale procurement for just-in-sequence component delivery.
- Retail:Back-of-store automation in Japanese convenience chains focuses on compact towing units for overnight replenishment.
- Logistics:Third-party operators in Vietnam and Indonesia adopt vision-based systems to avoid facility downtime during automation upgrades.
Manufacturing absorbs the bulk of installed capacity; Logistics is climbing the fastest as e-commerce fulfillment scales across Southeast Asia.
Technology:
Application requirements dictate navigation modality selection, with infrastructure-free systems gaining share in leased warehouse environments.
- Lidar:Solid-state sensors generate real-time point clouds for obstacle detection and dynamic path planning without facility retrofits. Third-party logistics operators in Thailand and Malaysia specify lidar-camera fusion to accelerate brownfield deployment timelines.
- Vision-based:Camera arrays with edge AI inference enable simultaneous localization and mapping using existing facility features. Mid-market warehouse operators in Vietnam and Indonesia favor these systems to eliminate laser reflector installation costs.
- Magnetic:Inductive wire or tape guidance remains prevalent in heavy automotive assembly where path predictability outweighs flexibility.
- Laser-guided:Reflector-based triangulation dominates legacy installations in Japanese semiconductor fabs with established infrastructure.
Magnetic systems retain the bulk of legacy installed capacity; Vision-based platforms are gaining share fastest in greenfield Southeast Asian warehouses.
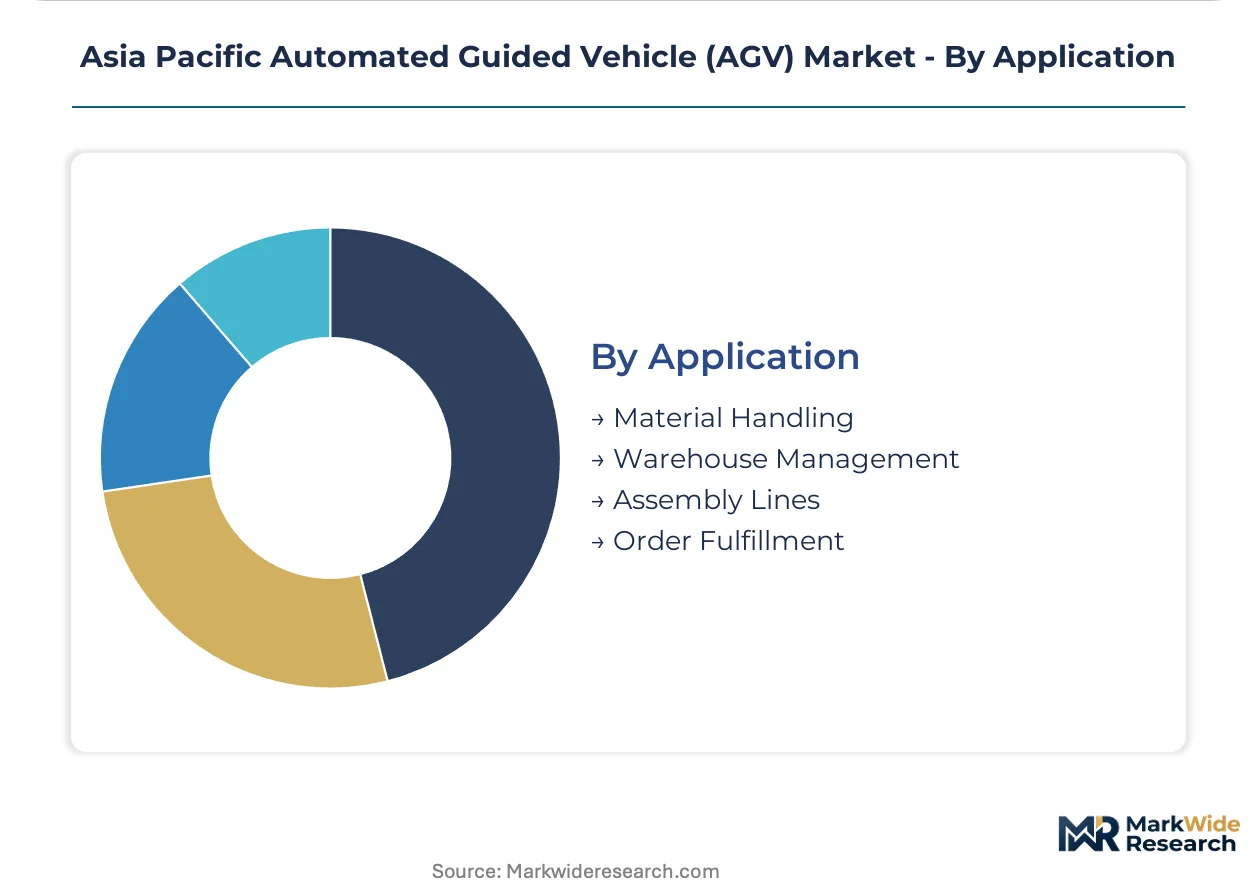
Application:
Customer type segmentation separates high-throughput distribution operators from precision-focused electronics manufacturers with divergent performance specifications.
- Material Handling:Cross-dock and staging operations in Chinese automotive plants deploy heavy towing fleets for synchronous component delivery.
- Warehouse Management:Inventory putaway and retrieval automation concentrates in South Korean pharmaceutical cold chain facilities facing MFDS compliance-driven replacement cycles.
- Assembly Lines:Takt-time feeding applications in Japanese automotive plants require METI-certified collaborative platforms with speed-separation protocols.
- Order Fulfillment:Piece-picking support and transport in Southeast Asian e-commerce centers favors compact pallet trucks with rapid deployment capability.
Material Handling retains the bulk of installed capacity; Order Fulfillment shows the steepest expansion trajectory as regional e-commerce penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's Yangtze River Delta manufacturing corridor, where automotive and electronics plants deploy fleet-scale AGV installations. E-commerce fulfillment centers across Southeast Asia are accelerating procurement of vision-guided systems. Japan's METI safety standards for autonomous mobile robots are reshaping product certification requirements across Northeast Asia.
China
Automotive and electronics plants in Jiangsu and Zhejiang provinces drive fleet-scale procurement for just-in-sequence component delivery. SAMR mandates GB-standard electromagnetic compatibility testing for all automated industrial vehicles sold domestically. The Yangtze River Delta manufacturing corridor hosts the densest concentration of towing AGV deployments for synchronous chassis feeding.
Japan
Automotive assembly plants require METI-certified collaborative platforms with SIL-rated emergency stop systems for takt-time feeding applications. METI enforces functional safety standards that effectively gate market access for uncertified European and Chinese entrants. The Kanto and Kansai industrial belts concentrate cleanroom-certified unit load AGV demand from semiconductor fabs.
South Korea
Electronics cleanrooms specify ISO Class 3-5 certified platforms to eliminate particle contamination risks during sub-10nm wafer production. MFDS-aligned workplace safety inspections extend to AGV fleet operations in pharmaceutical distribution centers, creating compliance-driven replacement cycles. The Seoul Capital Area anchors captive fleet expansions among memory and logic chip manufacturers.
Vietnam
Third-party logistics operators adopt vision-based systems to avoid facility downtime during brownfield warehouse automation upgrades. Labor cost arbitrage sustains incumbent manual forklift operations against automation payback calculations in distribution centers. The northern industrial provinces around Hanoi concentrate mid-market warehouse operator demand for camera-and-AI navigation stacks.
Indonesia
E-commerce fulfillment operators favor compact pallet trucks with rapid deployment capability for piece-picking support and transport. Legacy warehouse management system architectures resist API connectivity with modern fleet management platforms, constraining rollout velocity. The Greater Jakarta metropolitan area hosts the region's fastest-expanding logistics automation procurement for regional distribution hubs.
Asia Pacific Automated Guided Vehicle (AGV) Market Competitive Environment
Japanese producers anchor the premium-tier certification-heavy segment; Chinese specialists hold the mid-market vision-guided retrofit niche. The vendor base stratifies across three tiers: established cleanroom-certified incumbents with decades-long fab relationships, diversified industrial conglomerates leveraging captive battery and drive-train supply, and agile vision-navigation challengers pricing for Southeast Asian warehouse operators. Competitive moves concentrate on dual-certification investments for regulatory divergence bridging and fleet-scale procurement bundling with unified software platforms.
Within the established cleanroom-certified tier, Daifuku Co., Ltd. and Murata Machinery Ltd. exemplify vendors sustaining recurring automation contracts through long-standing semiconductor fab relationships. Toyota Industries Corporation anchors the heavy-duty industrial vehicle segment through proprietary drive-train technology and captive supply chain control. Suzhou Casun Intelligent Robot Co., Ltd. occupies the vision-based navigation challenger position, competing on systems priced for mid-market warehouse operators in Vietnam and Indonesia.
| Leading Market Players |
|---|
| Meidensha Corporation |
| Nanchang Industrial Control Robot Co., Ltd. |
| Daifuku Co., Ltd. |
| Midea Group Co. Ltd. |
| Murata Machinery Ltd. |
| Toyota Industries Corporation |
| Suzhou Casun Intelligent Robot Co., Ltd. |
| Scott Technology Ltd. |
| Mitsubishi Logisnext Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Camera-and-AI navigation stacks displacing laser reflector infrastructure simultaneously compress deployment costs for mid-market warehouse operators and concentrate component sourcing among Shenzhen-based edge-computing chip vendors. This technology transition reshapes margin pools across the Asia Pacific AGV landscape by decoupling system pricing from facility retrofit expenses.
Pricing Analysis
Volume absorption concentrates in fleet-scale procurement contracts while margin capture clusters among cleanroom-certified Japanese vendors serving semiconductor fabs. Three-tier pricing structure across premium SIL-rated platforms, standard magnetic-guided systems, and economy vision-based units separates buyers by certification requirements and payload precision needs. Price differentiation hinges on METI functional safety compliance and ISO Class 3-5 cleanroom validation, with cost compression in the mid-market tier intensifying as Chinese vision-navigation specialists compete on hardware margins. Third-party logistics operators in Vietnam and Indonesia exhibit highest price sensitivity, while South Korean memory chip manufacturers prioritize contamination-proof specifications over unit economics.
Supply Chain Analysis
Cleanroom certification and METI SIL-rating requirements gate supplier qualification, filtering component sourcing to established Japanese and South Korean vendors with validated fab relationships. Lithium iron phosphate cell production concentrates in China, solid-state lidar module assembly centers on Japanese optoelectronics specialists, and edge AI inference chip fabrication draws from Taiwan semiconductor foundries. Single-source vulnerability in Chinese cathode material output threatens battery pack cost stability for mid-market warehouse operators. Distribution runs through systems integrators with deployment track records in high-throughput Yangtze River Delta manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between Japanese METI safety frameworks and Chinese SAMR electromagnetic compatibility mandates is forcing dual-certification investments that weaker capitalized players cannot sustain, accelerating consolidation toward vendors with compliance infrastructure across both jurisdictions.
For Market Incumbents: Acquire specialized SLAM engineering teams in Shenzhen and Tokyo to secure scarce navigation algorithm talent before Chinese vision-guided specialists scale. Daifuku and Murata Machinery should reinforce cleanroom certification moats through captive validation facility investments in South Korea, while Toyota Industries must defend heavy-duty forklift AGV margins by locking lithium iron phosphate supply contracts with Chinese cathode producers ahead of mid-market competitors.
For New Entrants and Emerging Players: SAMR GB-standard electromagnetic compatibility mandates in China open a window for domestic vision-navigation specialists to displace uncertified European legacy vendors in Yangtze River Delta brownfield retrofits. Target Indonesian e-commerce fulfillment operators with equipment-as-a-service leasing structures that bypass upfront capital barriers, and penetrate Vietnamese third-party logistics through lidar-camera fusion systems requiring zero facility infrastructure modifications.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking captive automation capabilities, with financial sponsor interest clustering on vision-software layers with recurring SaaS revenue potential. Long-term viability favors vendors with demonstrated fleet-scale deployment credentials across both METI-certified Japanese automotive plants and SAMR-compliant Chinese electronics facilities. Watch for inflection in South Korean pharmaceutical cold chain automation procurement under MFDS-aligned workplace safety inspection expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | METI SIL-rating and SAMR GB-standard compliance bridges fragmented regulatory regimes across Northeast Asia. |
| Vision-Navigation Software Layer | Camera-and-AI SLAM stacks displace laser reflector infrastructure in Southeast Asian brownfield warehouses. |
| Captive Battery Supply Agreement | Lithium iron phosphate cell sourcing from Chinese cathode producers insulates margins against material cost volatility. |
| Fleet-Scale Procurement Bundling | Unified fleet management software contracts displace single-unit pilot programs among regional 3PL operators. |
| Cleanroom Validation Facility Expansion | ISO Class 3-5 certification capacity in South Korea and Taiwan accelerates revenue recognition for electronics fab deployments. |
Study Parameters
Trade association filings, customs export records, and semiconductor equipment procurement databases formed the secondary backbone for volume and value estimation. Primary interviews with AGV fleet managers at automotive assembly plants, warehouse automation directors at third-party logistics operators, cleanroom facility engineers at memory chip fabs, and procurement leads at electronics contract manufacturers validated deployment timelines and pricing structures. Bottom-up unit shipment tallies across towing, unit load, and vision-guided forklift categories were triangulated against top-down manufacturing value-add estimates from national industrial statistics.
Historical trendline analysis of magnetic-guided system displacement by vision-navigation platforms informed adoption curve modeling across the projection horizon. Segmentation dimensions included navigation technology modality, end-use facility type, payload capacity tier, and regional regulatory compliance cluster. CAGRs were derived from installed base expansion rates correlated with manufacturing automation intensity indices and e-commerce fulfillment center buildout pipelines. Forecast inputs incorporated lithium iron phosphate cell supply forecasts and METI safety standard revision timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state lidar cost reduction would alter the outlook for camera-only navigation penetration in mid-market warehouses. Forecasts reflect assumptions regarding regulatory harmonization timelines and semiconductor capital expenditure cycles. A model refresh is warranted upon material change in Chinese cathode material export policy or METI collaborative robot safety standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Sweeper Robot Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Robotic Coffee Bars Market
Robotics and Automation
Assistive Robotics Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Global Automotive Gesture Recognition System Market